
Blogs
PW Consulting: Pet Insect Protein Market Hits $750M in 2025, Projected 14.5% CAGR to 2032
By pmarketresearch, 2026-09-16
Future-Proofing Pet Nutrition: The Strategic Imperative of Insect Protein in 2026
The global pet food industry stands at a critical inflection point. Driven by escalating consumer demand for sustainable, hypoallergenic, and nutrient-dense nutrition, insect protein has transitioned from a niche innovation to a core strategic category. For executive leadership, R&D directors, and supply chain strategists, the window to secure competitive advantage in this space is narrowing rapidly. As we move through 2026, understanding the structural shifts, regulatory accelerations, and competitive maneuvers shaping this market is no longer optional—it is a prerequisite for resilient portfolio growth.
PW Consulting’s newly released Pet Food Insect Protein Market research report provides a comprehensive, data-rich roadmap for navigating this transformation. This article serves as a strategic preview, outlining the macro trajectory, competitive architecture, and operational levers that will define industry winners in the 2026–2032 forecast period. To preserve the analytical rigor and proprietary granularity of our full dataset, we highlight the strategic contours here while reserving the precise regional allocations, application-tier breakdowns, and detailed financial modeling for the complete intelligence package.
The Macro Trajectory: Sustained Expansion and Capital Confidence
The market has demonstrated consistent, compounding growth over the past half-decade, reflecting both structural demand shifts and maturing production ecosystems. Historical valuation records show the sector expanding from approximately USD 380 million in 2020 to USD 750 million by 2025, a trajectory that underscores accelerating commercial adoption across premium and specialty segments. Looking ahead, the forecast period projects rapid convergence toward a multi-billion-dollar valuation, with the market expected to approach USD 906 million in 2026 and continue its ascent through the early 2030s.
Underlying this expansion is a forecast compound annual growth rate of 14.5 percent, a figure that positions insect protein among the fastest-scaling alternative protein categories in modern pet nutrition. Such growth velocity signals more than transient trend adoption; it reflects entrenched formulation pipelines, supply chain localization initiatives, and regulatory frameworks that are progressively de-risking ingredient procurement. For strategic planners, this CAGR implies that market share captured today will compound significantly over the next seven years, making early positioning and vertical integration critical determinants of long-term profitability.
Revenue concentration data further illuminates the market’s maturation stage. Current metrics indicate a moderately fragmented landscape, with cumulative enterprise share remaining below pivotal consolidation thresholds. This structural openness presents a distinct strategic window: organizations that move decisively on capacity scaling, regulatory compliance, and premium-brand partnerships can establish defensible positioning before market tightening narrows the field.
Insect Feed Market
Operational Architecture: What the Full Report Delivers
Our research framework is engineered to translate macro trends into executable decision matrices. The complete report delivers a multi-dimensional analysis designed for cross-functional alignment across strategy, procurement, R&D, and commercial leadership. Key deliverables include:
- Historical and Forecast Modeling: Granular volume and value trajectories spanning 2020 through 2032, enabling scenario planning for capacity investment, pricing strategy, and margin optimization.
- Ingredient-Type Stratification: Comparative analysis of primary insect protein streams, evaluating nutritional profiles, processing requirements, and formulation compatibility across dry, wet, and treat formats.
- Application-Segment Mapping: Breakdown of demand drivers across dog food, cat food, and treats/snacks, with insights into formulation intensity, premiumization trends, and pet-owner purchasing behavior.
- Regional Dynamics and Market Access: Evaluation of regulatory timelines, localized production footprints, distribution channel maturity, and cross-border ingredient compliance pathways.
- Competitive Benchmarking and Strategic Positioning: Company-level assessments covering production scale, technological differentiation, partnership ecosystems, and recent capital or facility developments.
- Regulatory and Sustainability Intelligence: Synthesis of AAFCO authorizations, European legislative allowances, lifecycle assessment metrics, and emerging certification frameworks that influence procurement eligibility and brand positioning.
Each analytical module is cross-referenced to support integrated decision-making. Whether evaluating a potential supplier partnership, planning a new product introduction, or assessing geographic expansion feasibility, the report’s architecture ensures that strategic choices are grounded in verifiable, forward-looking intelligence rather than fragmented market narratives.
Competitive Dynamics: Key Players and Strategic Maneuvers
The competitive landscape reflects a hybrid structure of specialized insect ingredient producers and agile pet food brands that have embedded insect protein into core formulations. This dual-ecosystem dynamic creates both collaboration opportunities and competitive friction, as ingredient suppliers increasingly engage in co-development agreements while brands seek exclusive supply arrangements to differentiate premium offerings.
European-origin producers have established early technical leadership, particularly in black soldier fly larvae and mealworm-derived ingredients. Companies such as Innovafeed and Protix have scaled large-format production facilities and positioned their outputs for premium pet food integration, leveraging proprietary rearing and processing methodologies that emphasize nutrient retention and batch consistency. Innovafeed’s recent operational expansions in North America signal a deliberate strategy to localize supply chains and reduce transatlantic logistics friction, while Protix has consistently reinforced its market presence through new protein line launches targeting high-end formulations.
Mealworm specialization has also reached a regulatory and commercial milestone. Ÿnsect, operating from France, supplies mealworm-based protein streams under its Sprÿng brand and achieved a defining authorization to commercialize mealworm proteins for dog food in the United States. This regulatory breakthrough not only validates mealworm nutritional profiles for canine maintenance diets but also establishes a precedent that could accelerate broader alternative-protein acceptance across North American channels. Meanwhile, US-based entities such as EnviroFlight, operating under Darling Ingredients, and Canada-focused producers like Enterra, are advancing black soldier fly ingredient portfolios specifically approved for cat and dog applications, aligning production with regional regulatory frameworks and consumer preference patterns.
Pet Food Insect Protein Market
On the brand side, companies including Yora Pet Foods, Jiminy’s, Tomojo, petgood, and Entomo Farms illustrate how insect protein has moved beyond ingredient supply into complete-diet and treat portfolios. These brands are experimenting with cricket-derived streams, black soldier fly blends, and hybrid formulations to address palatability, allergen management, and sustainability storytelling. Such diversification indicates that the application layer is evolving from early proof-of-concept toward mainstream SKU architecture, with formulation engineers increasingly treating insect protein as a functional, scalable input rather than a promotional novelty.
Regulatory Catalysts and Formulation Realities
Regulatory clarity has emerged as one of the most powerful growth accelerators in this category. In the United States, AAFCO approvals have permitted the use of black soldier fly larvae in whole dried, meal, and oil forms for adult dog maintenance pet food and treats. This authorization framework reduces procurement uncertainty for formulators and provides a compliant pathway for ingredient integration across mainstream and premium product lines. Europe, meanwhile, has established legislative allowances for black soldier fly fat and proteins in pet food formulations, creating a harmonized baseline that supports cross-border supply planning and ingredient standardization.
Beyond regulatory alignment, pricing dynamics reflect the premium positioning of insect-derived inputs. Sector analysis indicates that premium black soldier fly protein for pet food applications commands a range of approximately USD 4 to 8 per kilogram of protein, a pricing band that underscores both processing complexity and value capture potential. For procurement and margin strategy teams, this range highlights the importance of scale efficiency, yield optimization, and long-term offtake agreements in maintaining robust unit economics as demand intensifies.
Sustainability metrics are increasingly influencing procurement decisions and brand positioning. Recent certification updates, including improved sustainability scoring for European production operations, demonstrate that lifecycle performance is becoming a measurable competitive differentiator. As pet owners and retail buyers place greater weight on environmental footprints, ingredient suppliers and brand owners alike are likely to face heightened expectations around traceability, resource efficiency, and verifiable sustainability claims.
Demand-Side Shifts and Strategic Allocation
Consumer and industry behavior continues to reshape how insect protein is deployed across the value chain. Analysis suggests that over half of global insect production is now directed toward pet food applications, a structural allocation that reflects pet nutrition’s role as the primary commercialization pathway for insect-derived ingredients. This demand concentration indicates that pet food manufacturers are not merely experimenting with alternative proteins—they are actively anchoring supply relationships and formulation pipelines around them.
Premiumization remains a defining commercial theme. As brands seek to differentiate through functional nutrition, allergen-aware formulations, and sustainability credentials, insect protein provides a compelling narrative and a technically versatile ingredient base. Treats and snacks, in particular, represent an attractive vehicle for incremental adoption, offering lower formulation risk and faster speed-to-market compared with complete-diet overhauls. At the same time, ongoing advancements in palatability optimization and processing consistency are reducing historical adoption barriers, enabling broader integration across daily feeding regimens.
Why This Research Matters for 2026 Decision-Making
The 2026 landscape demands more than high-level trend awareness. It requires a precise understanding of where capacity is expanding, which regulatory pathways are opening, how ingredient pricing is likely to evolve, and which competitive moves will reshape supply security and brand differentiation. PW Consulting’s full report translates these variables into an actionable intelligence framework, enabling leadership teams to stress-test investment theses, align procurement strategies with forecast dynamics, and identify partnership or acquisition targets that complement long-term growth objectives.
Because the market is scaling at a double-digit CAGR and regulatory clarity is steadily broadening, organizations that act on detailed, verified data will be better positioned to secure favorable supply terms, capture premium-segment demand, and anticipate consolidation pressures. The complete report contains the granular regional and application-level valuations, supplier-level operational metrics, and forward scenario analyses necessary to convert strategic intent into executable plans.
Conclusion: Securing Position Before the Curve Steepens
Insect protein in pet food has crossed the threshold from emerging alternative to strategic category. The combination of sustained compound growth, accelerating regulatory authorization, expanding production footprints, and entrenched demand allocation toward pet nutrition creates a market environment where timing, data quality, and execution discipline will separate leaders from followers. PW Consulting’s Pet Food Insect Protein Market report is designed to provide the analytical depth required to navigate that environment with confidence.
For executives seeking to validate expansion plans, optimize ingredient sourcing, or benchmark competitive positioning, the full dataset offers the granularity necessary to make informed, forward-looking decisions. We invite strategy, procurement, and commercial leaders to access the complete research for detailed segmentation valuation, competitive profiling, and scenario-based forecasting that will directly inform 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Pet Food Insect Protein Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global ASRS Market to Hit $20.08B by 2032, Driven by 8.21% CAGR
By pmarketresearch, 2026-09-16
Strategic Imperative: Navigating the Automated Storage Retrieval System Market in 2026
The global intralogistics landscape is undergoing a structural transformation, driven by the convergence of labor scarcity, e-commerce velocity, and technological maturity. For executives planning capital allocation in 2026, understanding the Automated Storage Retrieval System (AS/RS) market is no longer a niche engineering consideration—it is a board-level strategic priority. This article serves as a precursor to PW Consulting's latest comprehensive market research, designed to equip decision-makers with the contextual framework needed to interpret the full intelligence report.
As organizations move from pilot projects to scaled deployment, the ability to discern genuine growth trajectories from market noise is critical. The following analysis synthesizes macroeconomic data, competitive dynamics, and operational drivers to outline why this market warrants immediate attention.
Market Trajectory and Economic Significance
The historical performance of the AS/RS sector indicates a robust and accelerating adoption curve. Over the past five years, the global market has demonstrated resilience against supply chain disruptions, evolving from a consolidated revenue base to a significantly expanded operational footprint. Current market valuation estimates place the 2026 revenue at approximately 12.1 billion USD, reflecting a cumulative growth trend that has been consistent since 2020.
Looking toward the end of the forecast period, projections suggest the market will surpass the 20 billion USD milestone by 2032. This expansion is underpinned by a compound annual growth rate (CAGR) of roughly 8.21 percent across the 2026 to 2032 forecast horizon. Such growth rates signal a market moving beyond early adoption into a mainstream infrastructure phase, where automation is becoming a default requirement rather than a competitive differentiator.
Several macroeconomic factors are fueling this trajectory. According to recent data from the U.S. Bureau of Labor Statistics, warehouse automation is being accelerated by labor shortages, with 600,000 unfilled positions projected for 2026. Simultaneously, a PwC intralogistics study indicates that modern e-commerce growth requires AS/RS throughput exceeding 1,000 picks per hour, a benchmark that manual operations struggle to meet consistently. These pressures are forcing capital investment into automated solutions that maximize density and speed without proportional increases in human labor.
Operational Dynamics and Supply Chain Context
While demand signals are strong, the procurement environment in 2026 presents a complex mix of cost pressures and technological enablers. Decision-makers must balance the urgency of automation against the volatility of input costs. For instance, the World Steel Association reported in March 2025 that steel coil prices for structural frames in AS/RS rose 12 percent to 850 USD per ton due to supply chain disruptions. This input cost volatility can impact the total cost of ownership for large-scale installations, necessitating careful vendor negotiation and timing strategies.
Conversely, technological cost reductions are improving the economic case for specific system types. BloombergNEF noted in January 2025 that Li-ion battery prices for AS/RS shuttles declined 15 percent to 120 USD per kWh in 2025. This reduction lowers the operational expenditure for battery-dependent shuttle and bot-based systems, potentially shifting the preference toward flexible, mobile automation solutions over fixed infrastructure in certain applications.
Regulatory compliance also remains a critical consideration, particularly for operations expanding into or within Europe. The European Commission updated the EU Machinery Directive 2006/42/EC in 2024, mandating enhanced safety sensors for AS/RS stacker cranes. Compliance with these updated standards is not merely a legal checkbox but a factor that influences system design, integration costs, and vendor selection. Companies must ensure their chosen partners are aligned with these newer safety protocols to avoid retrofitting costs later.
Key Drivers Influencing Investment
- Labor Economics: Rising wage pressures and unfilled positions in key logistics hubs are making the ROI calculation for automation more favorable.
- Throughput Requirements: The shift toward same-day and next-day delivery expectations is pushing throughput requirements beyond manual capabilities.
- Space Optimization: Urban land costs are driving the need for vertical storage solutions and high-density cubing technologies.
- Regulatory Safety: New safety mandates are standardizing sensor integration, influencing the baseline specification for new installations.
Competitive Landscape and Strategic Positioning
The AS/RS market is characterized by a mix of established industrial giants and specialized technology innovators. Market concentration data suggests a moderately fragmented landscape, with the top three competitors holding approximately 31.4 percent of the market share and the top five controlling around 46.8 percent. This structure implies that while scale players dominate significant portions of the market, there is ample room for specialized providers to capture value in niche applications or specific geographies.
Leaders in the space are diversifying their portfolios to address varying density and throughput needs. Dematic, headquartered in Atlanta, GA, remains a global leader in automated storage and retrieval systems including shuttle-based, crane-based, and mini-load solutions. At ProMat 2025 in March 2025, Dematic showcased next-generation AutoStore Fusion AS/RS with enhanced robot density, signaling a push toward higher capacity within smaller footprints.
Swisslog, based in Buchs, Switzerland, continues to innovate in high-density storage with solutions like AutoStore, CarryPick, and Matrix. In January 2025, they launched the CarryPick Edge AS/RS specifically for cold storage with -30°C capability, addressing the stringent requirements of temperature-controlled logistics. Meanwhile, Daifuku from Osaka, Japan, leverages strong ties in the automotive sector, recently delivering ETV OS pallet shuttle AS/RS to Toyota's North American parts center in November 2024.
Worldwide Automated Storage Retrieval System Market
European manufacturers are also aggressively expanding their technological edges. KION Group, through its Linde Material Handling brand in Wiesbaden, Germany, delivers AutoStore-integrated and stacker crane AS/RS through STILL and Linde brands. Jungheinrich of Hamburg presented new shuttle-based AS/RS at LogiMAT 2024 with AI-optimized throughput, highlighting the industry's shift toward software-defined hardware performance. SSI Schaefer, based in Neunkirchen, Germany, continues to optimize retail and pharma storage with Weasel shuttle and Miniload solutions, recently appointing a new distributor for Weasel AS/RS in the Southeast Asia region to expand their geographic reach.
Specialized players are carving out distinct value propositions. AutoStore in Stavanger, Norway, pioneers cubic grid-based AS/RS with R5 robots for ultra-dense storage, particularly in e-commerce and wholesale. TGW Logistics in Wels, Austria, focuses on e-fulfillment with their PickCenter and FlashPick solutions for modular shuttle and tote-based automation. WITRON in Parkstein, Germany, designs OPM AS/RS for grocery retail with high-speed tote and tray handling, while Interlake Mecalux in Barcelona supports food and beverage sectors with Easy WMS-integrated stacker cranes. Murata Machinery from Kyoto adds depth in the semiconductor and automotive industries with their VANTIQ mini-load and pallet systems.
Vendor Selection Considerations
- Technology Fit: Evaluate whether shuttle, crane, or cube-based systems align with your SKU profile and throughput needs.
- Geographic Support: Consider vendor presence in key operational regions, as seen with SSI Schaefer's recent Southeast Asia expansion.
- Industry Specifics: Certain vendors offer specialized adaptations, such as Swisslog's cold storage capabilities or Daifuku's automotive pedigree.
- Integration Ecosystem: Assess the compatibility of AS/RS hardware with existing Warehouse Management Systems (WMS) and software layers.
Segmentation Insights and Application Diversity
The AS/RS market is not monolithic; it is defined by diverse technology types and end-user applications, each with distinct growth drivers. Understanding the broad allocation of market activity helps in benchmarking organizational strategy against industry trends. However, precise quantitative splits require deeper analysis available in the full report.
In terms of technology types, the market encompasses a wide spectrum ranging from traditional Unit Load systems to advanced Mini Load solutions. Vertical Lift Modules (VLMs) and Shuttle and Bot-based Systems represent significant segments, catering to different density and speed requirements. Carousels also maintain a presence in specific operational contexts. The choice between these types often depends on the physical characteristics of the goods being stored and the required access frequency.
End-user diversification is equally critical. While E-commerce and Retail drive a substantial portion of demand due to the need for rapid order fulfillment, other sectors are adopting AS/RS at varying paces. Food and Beverages, Automotive, Healthcare and Pharmaceuticals, and Manufacturing sectors all contribute to the overall market volume. Each industry presents unique challenges, such as hygiene standards in pharma, traceability in automotive, or temperature control in food logistics.
Regional dynamics also play a pivotal role in shaping market opportunities. Activity is distributed across major economic zones including Asia Pacific, Europe, North America, and the Rest of World. Each region exhibits different adoption rates influenced by local labor costs, infrastructure maturity, and regulatory environments. For a detailed understanding of regional performance metrics and specific application share, stakeholders are encouraged to consult the complete dataset in the full research publication.
Conclusion and Call to Action
The Automated Storage Retrieval System market in 2026 presents a landscape of significant opportunity tempered by complex operational and economic variables. The projected growth to over 20 billion USD by 2032 underscores the long-term viability of automation investments. However, success depends on navigating the nuances of technology selection, vendor capabilities, and external cost drivers.
Strategic decisions made in this market will define operational efficiency for the next decade. To support these critical decisions, PW Consulting has compiled a detailed Worldwide Automated Storage Retrieval System Market report. This document provides the granular data, segmentation breakdowns, and competitive analysis necessary to move from high-level strategy to executable planning.
We invite industry leaders, investors, and supply chain executives to access the full report for comprehensive intelligence. The detailed insights contained within will enable you to validate assumptions, benchmark against peers, and secure a competitive advantage in the evolving world of intralogistics automation.
Worldwide Warehouse Automated Sorting System Market
For detailed analysis of this topic, please visit the official page: Worldwide Automated Storage Retrieval System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Sunlight Simulators Market to Reach $890.52M by 2032 at 7.0% CAGR
By pmarketresearch, 2026-09-16
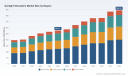
Global Sunlight Simulators Market: Strategic Intelligence for Enterprise Decision-Making in 2026
Introduction: Navigating Solar Simulation Amidst Technological Transition
The global demand for precise, reproducible, and spectrally accurate sunlight simulation has entered a phase of accelerated maturation. As photovoltaic manufacturing scales, next-generation tandem and perovskite architectures mature, and cross-industry applications in aerospace, biotechnology, and materials testing expand, organizations face increasingly complex procurement and R&D strategy choices. Our newly released Worldwide Sunlight Simulators Market study delivers a comprehensive, data-driven foundation for enterprise decision-makers operating in 2026 and beyond.
This executive overview distills the core strategic themes, competitive architectures, and operational imperatives that will shape capital allocation, technology roadmapping, and partnership strategies. By mapping historical trajectories against forward-looking forecast horizons, the report equips leadership teams with actionable intelligence while preserving the granular analytical depth required for precise market navigation.
Macro Market Trajectory and Structural Growth Dynamics
The sunlight simulators market has demonstrated consistent expansion over the historical evaluation window, building from approximately 395.4 million USD in 2020 to an estimated 554.57 million USD in 2025. This baseline reflects sustained investment in standardized testing infrastructure, regulatory compliance frameworks, and research-grade optical instrumentation. Looking ahead, the forecast period extending through 2032 projects a steady compound annual growth rate of 7.0 percent, culminating in a market valuation approaching 890.52 million USD.
Such growth is not homogenous. Demand acceleration is being shaped by the interplay of three structural forces: the proliferation of high-throughput module qualification lines, the transition from legacy continuous-spectrum illumination technologies toward spectrally tunable solid-state architectures, and the broadening of application mandates beyond traditional photovoltaic qualification. Organizations that rely on static market assumptions risk misaligning procurement cycles, R&D budgets, and capacity planning with the actual pace of segment-level demand migration.
Strategic planning in 2026 must therefore account for the divergence between headline growth and segment-specific velocity. Forecasting models embedded in this study isolate these dynamics, enabling readers to distinguish between incremental market expansion and structural technology substitution events that will redefine procurement requirements, vendor evaluation criteria, and facility investment timelines.
Research and Testing Applications: The Demand Anchor
Photovoltaic module testing continues to function as the primary demand engine for sunlight simulation infrastructure. Qualification workflows, manufacturing line verification, and performance certification depend on repeatable illumination conditions that meet stringent international standards. As cell architectures grow more complex—incorporating tandem stacks, heterojunction designs, and advanced anti-reflective or passivation coatings—testing protocols increasingly require adjustable spectral output, uniform irradiance across large areas, and precise thermal management during measurement cycles.
Beyond solar energy, secondary application verticals are contributing incremental but strategically significant growth. Aerospace and defense organizations utilize solar simulation for optical sensor calibration, environmental exposure verification, and materials durability assessment under controlled solar spectra. Materials and cosmetics testing laboratories leverage standardized illumination for photostability evaluation, weathering simulation, and formulation screening. Concurrently, biotechnology and agriculture applications are expanding the use case envelope for controlled-spectrum exposure in plant physiology research, photobiological assays, and controlled-environment agricultural prototyping.
Understanding how spending patterns distribute across these application domains is essential for equipment manufacturers, laboratory operators, and supply chain planners. The study delineates how application-specific requirements influence light source selection, classification thresholds, and automation integration, ensuring that procurement strategies are aligned with actual usage intensity rather than generalized market narratives.
Technology Architecture and Light Source Evolution
The technological composition of the sunlight simulators market reflects an ongoing architectural debate between established xenon lamp platforms and emerging LED-based simulation systems. LED-based simulators have gained prominence through their spectral tunability, extended operational lifetimes, reduced thermal footprints, and compatibility with automated testing environments. These attributes align with high-throughput manufacturing lines and research workflows that demand rapid reconfiguration between spectral profiles such as AM0, AM1.5G, and customized band-limited outputs.
Xenon lamp-based simulators retain relevance in scenarios requiring high-intensity flash or continuous-spectrum outputs that historically align with specific qualification standards and legacy test infrastructure. In parallel, metal halide and complementary light source configurations serve niche requirements where particular spectral characteristics, illumination geometries, or cost considerations dictate equipment selection. The market is not experiencing a simple substitution effect; rather, it is evolving into a multi-technology landscape in which end users select platforms based on application class, testing cadence, spectral fidelity requirements, and total cost of ownership over the equipment lifecycle.
A critical strategic consideration is how classification standards influence purchasing behavior. Equipment rated across Class A, A+, and A+++ parameters must satisfy defined criteria for spectral match, temporal stability, and spatial uniformity. Organizations evaluating capital expenditures need clarity on which classification tier matches their regulatory obligations, internal quality thresholds, and future technology roadmap. The report examines these technical differentiators through a commercial lens, connecting laboratory performance specifications with procurement economics and vendor evaluation frameworks.
Geographic Distribution and Regional Demand Drivers
Regional demand patterns reflect differences in manufacturing density, research infrastructure investment, regulatory environments, and energy policy momentum. Asia Pacific represents a substantial share of current market activity, supported by concentrated photovoltaic manufacturing ecosystems, expanding research institutions, and large-scale module qualification operations. North America and Europe maintain robust demand driven by advanced research programs, aerospace and defense testing requirements, pharmaceutical and cosmetics photostability workflows, and sustained investment in next-generation photovoltaic technologies.
The Rest of World segment, while smaller in absolute terms, reflects emerging testing infrastructure development and regional qualification center expansion. Enterprises operating across multiple jurisdictions must account for variations in standards adoption, service network availability, calibration support, and equipment localization requirements. Regional procurement strategies that ignore local service ecosystems or compliance nuances often encounter longer deployment cycles, higher validation costs, and greater operational risk.
Our geographic analysis avoids simplistic ranking narratives. Instead, it examines how regional manufacturing footprints, export qualification requirements, and localized testing mandates shape equipment specification decisions, vendor selection criteria, and after-sales service expectations. This framing enables multinational operators to design region-specific deployment strategies rather than applying uniform procurement templates across diverse markets.
Competitive Landscape: Differentiation, M&A, and Capability Consolidation
The competitive environment is defined by a concentrated but diversifying vendor base. The top five participants collectively account for approximately 48.7 percent of market revenue, while the top three hold roughly 31.4 percent, indicating a landscape where established leaders retain meaningful share but face rising pressure from specialized innovators and capability expansions through acquisition.
Several participants illustrate the strategic directions shaping the market. G2V Optics Inc. has built its positioning around advanced tunable LED solar simulators, including the Pico and Sunbrick series, with Class AAA and A+A+A+ configurations designed to replicate AM0 through AM1.5G spectra. Its emphasis on long LED lifetime and automation support appeals to research, photovoltaic, aerospace, and photochemistry applications requiring repeatable spectral control.
Eternal Sun has positioned itself as a leading provider of solar module testing equipment, offering steady-state LED solar simulators with A+A+A+ class performance alongside SPIRE Xenon-based flash solar simulators for IV testing of PV modules. Its support for tandem and perovskite technologies, combined with temperature control capabilities, reflects alignment with evolving cell architectures and qualification demands.
Avalon ST has focused on long-pulse, high-accuracy large-area LED solar simulators under its Nexun series, with A+ to A+++ classifications targeting photovoltaic and spatial industry applications, including perovskite, HJT, and AM0 testing. Its 2025 acquisition of PASAN SA represents a notable consolidation move, integrating LED-based solar simulation expertise with xenon-based simulators and precision measurement systems to broaden PV metrology offerings. This type of capability combination illustrates how vendors are seeking to serve customers across multiple light source architectures rather than competing within a single technology niche.
Newport Corporation provides the Sol series of arc lamp and LED solar simulators with compliance to ASTM, IEC, and JIS standards, including UV Sol-UV models for varied illumination areas and material testing applications. Solar Light Company, LLC delivers precision research-grade solar simulators aligned with ISO, FDA, JCIA, COLIPA, ASTM, and IEC standards, with strong recognition in SPF testing laboratories and light sciences applications. Abet Technologies, Inc. offers compliant simulators spanning 150W to 3kW, including the SunLite line for solar cell testing across DSSC, perovskite, silicon, and thin film technologies. Sciencetech Inc. complements this landscape with customized and standard simulators, including high-flux models for research applications in photovoltaics and related fields.
These profiles underscore a market in which competitive advantage is increasingly determined by application coverage, standards compliance breadth, spectral customization capability, and the ability to support automation and temperature-controlled testing workflows. Recent activity, such as the 2025 consolidation involving Avalon ST and the 2024 high-flux installation milestone achieved by Sciencetech Inc., signals an industry that is actively reshaping its capability base to match the requirements of advanced cell technologies and high-throughput testing environments.
Strategic Value of the Report for Enterprise Decision-Making
This study is designed to convert market complexity into operational clarity. It provides decision-makers with a structured framework for evaluating technology roadmaps, procurement timing, vendor qualification, and investment prioritization. The analysis is built to support multiple organizational functions, including R&D strategy, manufacturing operations, quality and compliance teams, procurement, and corporate development.
Key deliverables and practical contents include:
Worldwide Sunlight Simulators Market
- A full historical reconstruction from 2020 through 2025, paired with a forecast trajectory extending to 2032, enabling sensitivity analysis around adoption velocity, technology mix shifts, and demand elasticity.
- Segment-level evaluation across light source architectures, application categories, and regional demand structures, with interpretive guidance on how each dimension influences purchasing requirements and vendor selection.
- Competitive profiling of leading manufacturers, including headquarters location, product architecture, standards compliance, application focus, and recent strategic developments, supporting benchmarking and partnership assessment.
- Analysis of market concentration metrics and implications for supplier negotiation, switching costs, and technology roadmap dependency.
- Contextual interpretation of industry dynamics affecting procurement cycles, validation requirements, and service infrastructure expectations.
- Decision-oriented frameworks for aligning equipment classification, spectral customization needs, illumination area requirements, and automation readiness with actual operational use cases.
This multidimensional structure allows readers to move beyond top-line market sizing and into the operational logic that determines where value is created or lost. Procurement leaders can use the analysis to time capital expenditures against anticipated technology mix transitions. R&D managers can map spectral and classification requirements to upcoming cell or material programs. Corporate development teams can evaluate acquisition targets and partnership opportunities based on capability complementarity rather than revenue scale alone.
Forward Outlook for 2026 and Beyond
The next phase of market development will likely be shaped by the continued integration of LED-based tunability with high-accuracy large-area illumination, the expansion of flash and steady-state solutions for advanced tandem and perovskite module testing, and the growing importance of precision measurement ecosystems that accompany solar simulation hardware. As qualification standards evolve and product architectures become more spectrally and thermally demanding, equipment selection will increasingly hinge on lifecycle performance, automation compatibility, and vendor-supported calibration and service networks.
Enterprises that establish clear internal definitions of required spectral match, temporal stability, spatial uniformity, and application coverage will be better positioned to navigate vendor offerings without over-specifying or under-equipping their testing infrastructure. At the same time, organizations operating across multiple verticals should expect to manage a more diversified equipment portfolio, balancing high-throughput manufacturing requirements against research-grade flexibility and specialized compliance demands.
This report provides the analytical scaffolding needed to make those decisions with confidence. It combines historical market reconstruction, forward-looking demand modeling, technology architecture assessment, and competitive capability mapping into a single strategic reference point for 2026 planning cycles.
Conclusion
The worldwide sunlight simulators market is entering a period in which growth, technology differentiation, and application expansion will jointly determine competitive outcomes. Enterprise leaders who rely on aggregate market narratives alone risk misjudging where demand is actually intensifying, which technological pathways will dominate specific use cases, and how vendor capabilities are consolidating to serve advanced testing requirements.
Our full market study delivers the granular segmentation, competitive benchmarking, regional interpretation, and forward forecast detail necessary to translate strategic intent into executable plans. To access the complete dataset, segmentation analysis, competitive profiles, and scenario-based forecast frameworks that support precise procurement, R&D, and investment decisions, refer to the full report through our official research portal.
Aviation Simulators Market
For detailed analysis of this topic, please visit the official page: Worldwide Sunlight Simulators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Potassium Carbonate Hydrate Market Hits $479.77M in 2025, Set to Reach $648.54M by 2032 at 4.4% CAGR
By pmarketresearch, 2026-09-16
Navigating the Evolving Landscape of Potassium Carbonate Hydrate: Strategic Insights for 2026 and Beyond
The global potassium carbonate hydrate market is entering a pivotal phase defined by steady structural growth, shifting regulatory frameworks, and intensifying competition across key industrial verticals. As we advance into 2026, corporate decision-makers across manufacturing, supply chain, and procurement functions require more than high-level forecasts. They need a granular, actionable intelligence framework that maps historical trajectories, anticipates macroeconomic and policy inflection points, and decodes the competitive maneuvering of leading producers. Our newly published Worldwide Potassium Carbonate Hydrate Market research study delivers precisely that. Designed as a strategic compass rather than a static dataset, this report equips executives with the analytical depth required to optimize sourcing strategies, evaluate market entry opportunities, and align capital allocation with emerging demand cycles.
Over the past half-decade, the sector has demonstrated remarkable resilience amid fluctuating feedstock costs, regional energy constraints, and evolving compliance mandates. From 2020 through 2025, global revenue expanded from approximately 382.45 million USD to 479.77 million USD, reflecting a compound trajectory that underscores the material's indispensable role across glass and ceramics, agrochemicals, food processing, and specialty chemical synthesis. Looking ahead to the 2026 to 2032 forecast window, the market is projected to reach 502.78 million USD in the current year, with sustained momentum carrying valuation toward 648.54 million USD by the close of the forecast period. This expansion is underpinned by a consistent compound annual growth rate of 4.4%, signaling a moderately paced but structurally robust upward curve. For strategic planners, these figures are not merely retrospective milestones; they represent baseline parameters against which capacity investments, pricing strategies, and regional allocation decisions must be calibrated.
Strategic Forecast Architecture: Mapping 2026 to 2032
The credibility of any market intelligence asset lies in its ability to translate macroeconomic indicators into operational foresight. This report constructs a multi-layered forecasting architecture that accounts for historical consumption patterns, production economics, and forward-looking demand triggers. The base year of 2025 anchors a robust back-casting methodology, ensuring that incremental year-over-year movements reflect authentic market dynamics rather than statistical smoothing. As the analysis progresses through 2026, 2027, and beyond, the model incorporates sensitivity variables tied to feedstock availability, energy pricing volatility, and regulatory compliance costs. Executives will find particular value in how the forecast isolates inflection points where supply chain bottlenecks or policy shifts could materially alter regional supply-demand equilibriums. By treating the 4.4% CAGR not as a static promise but as a dynamic range modulated by real-world variables, the study empowers leadership teams to stress-test their strategic assumptions against plausible disruption scenarios.
Supply Chain Architecture and Production Economics
Understanding the potassium carbonate hydrate value chain requires a clear grasp of how raw material inputs translate into finished grades ready for industrial, food, or pharmaceutical deployment. The production pathway typically begins with potassium hydroxide derived from potash, which reacts with carbon dioxide in controlled carbonation environments. Notably, this process frequently involves carbon capture mechanisms that initially yield the hydrated form, K2CO3·1.5H2O, before targeted dehydration steps produce anhydrous variants for specialized applications. This technical nuance carries direct implications for energy intensity, capital expenditure, and regional cost competitiveness. Facilities integrated with upstream chlor-alkali operations benefit from feedstock synergies, while standalone producers must navigate broader commodity market exposures. Pricing dynamics in late 2025 further illustrate the geography-driven cost landscape. In Northeast Asia, hydrated potassium carbonate traded around 1.17 USD per kilogram, supported by firm upstream potassium hydroxide costs and consistent pull from specialty glass and ceramics manufacturers. Across Europe, prices climbed to approximately 1.70 USD per kilogram, reflecting higher energy and natural gas expenditures that directly pressure energy-intensive carbonation processes, alongside robust demand from pharmaceutical and detergent sectors. These regional differentials are not transient anomalies; they represent structural pricing layers that procurement and manufacturing strategists must factor into long-term contract negotiations and plant location evaluations.
Regulatory and Compliance Inflection Points
Regulatory shifts are rapidly transitioning from peripheral considerations to central strategic variables. Beginning January 1, 2026, potassium carbonate has been added to the Internal Revenue Service taxable chemical substances list under Superfund tax rules, a development triggered by the fact that taxable chemicals constitute more than twenty percent by weight in its predominant production methodology. This classification introduces new compliance cost considerations that will ripple through production economics, particularly for facilities operating at scale or those navigating multi-jurisdictional supply networks. Simultaneously, the material remains under review within the USDA National Organic Program sunset process, with ongoing evaluation slated for 2027 regarding its continued allowance in organic crop production as a synthetic substance. For agrochemical and food processing stakeholders, the trajectory of this review carries tangible implications for formulation strategies, certification pathways, and downstream market access. The report dissects these regulatory currents with precision, mapping how compliance timelines intersect with production planning, supply chain diversification, and product portfolio positioning. Executives who anticipate regulatory friction rather than react to it will secure decisive cost and market access advantages.
Competitive Landscape and Strategic Positioning
Global Market Concentration and Strategic Holdings
The potassium carbonate hydrate sector exhibits moderate concentration, with the top three players collectively capturing approximately 42.8 percent of market revenue and the top five expanding that share to 58.5 percent. This structure indicates a landscape where scale advantages, integrated production capabilities, and diversified application portfolios create meaningful competitive moats, while still leaving substantial room for specialized producers and regional champions to carve out defensible niches. Strategic positioning in this environment demands more than volume expansion; it requires alignment between grade specialization, geographic reach, and application-specific technical support.
Potassium Formate Market
Key Players and Strategic Profiles
Armand Products Company, headquartered in Muscle Shoals, Alabama, stands as a world leader in potassium carbonate production, operating large-scale manufacturing capacity that ships both anhydrous and hydrated grades globally across industrial, food, and specialty applications. Its ISO 9001:2015 certified facility underscores a commitment to standardized quality control that resonates strongly with regulated end markets. Vynova Group, anchored by Belgium-based operations, supplies multiple grades in crystalline granulated, powder, and hydrated forms to European and worldwide markets, with dedicated applications spanning food, pharmaceutical, agrochemical, and cocoa processing sectors. Its multi-format capability positions the company as a flexible supplier capable of addressing highly specific formulation requirements. INEOS KOH operates across the USA and Europe, producing liquid potassium carbonate at a forty-seven percent solution concentration using upstream potassium hydroxide from its chlor-alkali plant. This integration supports demanding use cases in video glass manufacturing, animal feed additives, and polymer catalysts, where consistent chemical delivery and volume reliability are paramount. Hawkins, Inc., based in the USA, manufactures high-purity liquid potassium carbonate at the same forty-seven percent concentration, targeting agriculture, printed circuit board production, food preservation, and oil industry applications. Its focus on purity and liquid-form convenience addresses specialized processing environments where handling efficiency and chemical precision directly influence downstream performance. UNID Company Ltd., headquartered in Seoul, South Korea, operates as a major Asian producer within its inorganic chemicals division, leveraging significant production capacity to serve both domestic and export markets. Evonik Industries AG, the Germany-based global specialty chemicals company, produces potassium carbonate for a broad spectrum of industrial applications, drawing on its advanced chemical engineering infrastructure to support performance-driven formulations. AGC Inc., also known as AGC Chemicals, is headquartered in Japan and supplies high-purity potassium carbonate specifically tailored for ceramics, glass, and other specialty applications where material consistency and trace impurity control are non-negotiable. Altair Chimica SpA, an Italian producer, operates alongside caustic potash and other inorganic chemicals, offering European buyers integrated sourcing options that reduce supply chain fragmentation. In China, Zhejiang Dayang Biotech Group Co. Ltd. has established itself as a significant manufacturer and exporter with broad domestic and international supply reach, while Wentong Potassium Salt Group, operating under Qinghai Yanhu, focuses on high-purity potassium carbonate grades and has pursued capacity expansions specifically targeted at electronics and industrial uses. Together, these players illustrate a competitive ecosystem where scale, purity, regional proximity, and application specialization intersect in complex ways. The report provides detailed comparative analytics that reveal how each enterprise is positioning itself to capture value across grade segments, geographic corridors, and end-use verticals.
Report Architecture: Operational Intelligence for Decision Makers
The Worldwide Potassium Carbonate Hydrate Market study is engineered for immediate operational relevance. Beyond macroeconomic forecasting, the report delivers a structured breakdown of market segmentation that maps revenue distribution across grades, applications, and regions, enabling procurement teams to identify concentration risks and supply diversification pathways. The grade analysis distinguishes between industrial, food, and pharmaceutical categories, highlighting how purity thresholds, certification requirements, and pricing premiums shape margin structures and competitive dynamics. Application-level evaluation traces how demand from glass and ceramics, agrochemicals and fertilizers, food processing, chemical intermediates, and other verticals interacts with production capacity, seasonal consumption cycles, and substitution risks. Geographic coverage extends across Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa, providing context on regional supply-demand balances, logistics considerations, and localized pricing behaviors without reducing the narrative to static percentage breakdowns. Competitive profiling synthesizes facility capabilities, certification footprints, product format portfolios, and strategic expansions into actionable benchmarking frameworks. The report also integrates scenario analysis modules that allow executive teams to model the financial and operational impact of regulatory adjustments, feedstock volatility, and demand acceleration or deceleration across the forecast window. By aligning quantitative baselines with qualitative strategic context, the study functions as a decision-support platform that can be deployed across planning, sourcing, and market-entry workstreams.
Strategic Imperatives for Corporate Leadership
As the market navigates the 2026 to 2032 horizon, leadership teams must translate intelligence into action across several interconnected fronts. First, procurement strategies should account for the widening regional price differentials and the structural energy cost pressures that influence European and Northeast Asian supply economics, particularly when negotiating multi-year supply agreements. Second, regulatory preparedness must become a core competency, with compliance teams tracking the Superfund taxable chemical classification and the ongoing USDA organic program review to anticipate cost adjustments and formulation constraints before they disrupt procurement cycles. Third, competitive positioning demands clarity on grade specialization and application focus, as margin profiles diverge sharply between bulk industrial supply and high-purity pharmaceutical or specialty glass requirements. Fourth, capacity planning and geographic diversification should be evaluated against regional concentration patterns and logistics resilience, ensuring that supply networks can absorb localized disruptions without compromising delivery reliability. Finally, strategic partnerships and supplier evaluations should be grounded in a detailed understanding of each major producer's technical capabilities, certification status, and expansion trajectories, enabling more precise vendor selection and long-term collaboration frameworks.
Worldwide Potassium Carbonate Hydrate Market
The Worldwide Potassium Carbonate Hydrate Market research study is designed to serve as the foundational intelligence asset for these strategic priorities. By combining rigorous historical analysis, transparent forecasting methodology, segmentation insights, and competitive profiling, the report provides a comprehensive view of where the market stands, how it is likely to evolve, and what decisions will separate resilient operators from reactive followers. Executives who engage with the full spectrum of findings will be better positioned to allocate capital efficiently, negotiate from a position of informed strength, and anticipate the regulatory and competitive shifts that will define the next phase of market development. To access the complete segmentation breakdowns, detailed company benchmarking, regional pricing trajectories, and scenario modeling tools that underpin these insights, we invite you to explore the full report through our official portal and integrate this intelligence directly into your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Potassium Carbonate Hydrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Sonobuoy Launcher Market to Hit $530.14M by 2032, Growing at 5.46% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence in the Deep Blue: Navigating the Global Sonobuoy Launcher Market in 2026
The undersea warfare landscape is undergoing a profound transformation. As naval powers prioritize anti-submarine warfare (ASW) capabilities to counter evolving underwater threats, the mechanisms by which airborne assets deploy surveillance equipment have become critical nodes in the defense supply chain. The Worldwide Sonobuoy Launcher Market represents more than just a component segment; it is the enabling interface between maritime patrol platforms and the acoustic sensors essential for detecting modern submarines. For defense executives, procurement officers, and strategic investors, understanding the trajectory of this market is no longer optional—it is imperative for capitalizing on emerging opportunities and mitigating supply chain risks in Fiscal Year 2026 and beyond.
In this complex environment, generic market observations are insufficient. Decision-makers require granular intelligence that connects macroeconomic trends, technological shifts, and competitive maneuvering. PW Consulting is proud to introduce our latest comprehensive study, designed to equip stakeholders with the actionable intelligence needed to navigate this specialized sector. This introduction outlines the strategic value of the research, highlighting the market's current momentum, the competitive dynamics shaping the industry, and the specific operational content included in our full report.
Worldwide Sonobuoy Launcher Market
Market Trajectory and Economic Context
The sonobuoy launcher sector has demonstrated resilient growth over the past five years, driven by sustained defense spending and the modernization of ASW fleets. According to our analysis, the global market revenue has shown a consistent upward trajectory, with historical performance reflecting the steady demand for airborne ASW capabilities. The market valuation stood at approximately $346.93 million in 2024, progressing to an estimated $365.4 million in 2025. This growth is not merely linear; it reflects the increasing complexity of naval missions and the necessity for reliable deployment systems for A-size, F-size, and G-size sonobuoys.
The forecast period from 2026 to 2032 indicates a robust expansion path. Our models project the market will reach approximately $408.79 million in 2026, signaling a significant step up in procurement and modernization cycles. Looking further ahead, the compound annual growth rate (CAGR) is calculated at 5.46 percent. This rate underscores a mature yet steadily growing industry, fueled by the replacement of legacy systems and the integration of new platforms.
- Revenue Momentum: The transition from 2025 to 2026 reflects a critical inflection point where multiple naval programs converge.
- Long-Term Outlook: Projections extend through 2032, offering visibility into long-term R&D and production planning.
- Currency and Scale: All financial data is presented in USD Million, ensuring consistency for international benchmarking.
This macroeconomic backdrop provides the necessary context for understanding vendor performance and contract opportunities. However, the aggregate numbers only tell part of the story. The distribution of revenue across different launcher technologies, platforms, and geographic regions reveals where the true value lies and which segments are primed for disruption. Our full report dissects these segments without exposing the detailed figures here, inviting readers to access the complete dataset for precise benchmarking.
Technology Segmentation and Platform Integration
The market is characterized by a diverse array of launcher technologies, each suited to specific operational requirements and platform constraints. Pneumatic systems remain a dominant force, valued for their reliability and reloadability during flight operations. Gravity and rotary mechanisms offer alternative deployment profiles, while pyrotechnic solutions cater to specialized rapid-release scenarios. The choice of launcher type is inextricably linked to the host platform, whether it be a high-altitude maritime patrol aircraft, a low-and-slow ASW helicopter, or emerging unmanned aerial systems.
Platform integration is a key driver of demand. Maritime patrol aircraft continue to represent the largest share of deployment activity, given their endurance and sensor capacity. ASW helicopters provide essential low-altitude coverage, while unmanned aerial vehicles are increasingly being explored for expendable sensor delivery. Surface vessels also contribute to the ecosystem, albeit to a lesser extent in the airborne launcher context. The interplay between platform availability and launcher compatibility creates a complex matrix of requirements. Our report analyzes these dynamics in depth, evaluating how shifts in platform procurement—such as the continued acquisition of P-8A Poseidon aircraft or MH-60 helicopters—ripple through the launcher supply chain.
Competitive Landscape: Key Players and Strategic Positionings
The competitive environment is moderately concentrated, with a few major players commanding significant market share. This structure offers stability but also presents barriers to entry for smaller firms. The leading companies are not merely manufacturers; they are system integrators deeply embedded in naval aviation programs. Understanding their specific capabilities, recent contract wins, and technological roadmaps is essential for assessing supplier risk and partnership potential.
L3Harris Technologies stands out as a key contributor, designing and manufacturing pneumatic-powered sonobuoy launching systems. Their portfolio includes the Sonobuoy Rotary Launch System (SRL), capable of holding ten A-size sonobuoys with a launch capability every three seconds, and the Sonobuoy Single Launch System (SSL) for single A-, F-, or G-size units. These systems are reloadable in flight and suited for maritime patrol aircraft such as the P-8A. L3Harris maintains full-rate production and has a proven flight heritage. Recent developments, including a prominent contract award in December 2025 related to advanced systems and a sole-source contract in January 2024 for the P-8A Poseidon Sonobuoy Rotary Launcher Lower Tray Retrofit, highlight their entrenched position in critical U.S. Navy programs.
Ultra Maritime, based in the UK, provides sonobuoy systems and associated launcher technologies. They are actively developing next-generation multistatic sonobuoys compatible with existing naval launcher infrastructure, including P-8A platforms. In April 2026, Ultra Maritime was awarded a sole source firm-fixed-price contract for Low Rate Initial Production of AN/SSQ-125B sonobuoys, supporting integration with existing naval launcher systems. This contract underscores the ongoing relevance of launcher compatibility even as sonobuoy technology evolves.
Lockheed Martin remains involved in sonobuoy programs and upgrades to related launcher systems, such as the MK36 Super Hercules, to enhance performance and range in ASW applications. Thales Group develops multi-platform sonobuoy launchers adaptable to frigates, corvettes, and helicopters, alongside advanced sonobuoys like SonoFlash with extended detection range and multistatic capabilities. Sparton Corporation, now part of Elbit Systems, manufactures sonobuoys with extensive deployment history and supports associated launching systems for air-to-sea deployment.
Missile Decoy Launcher System Market
The market also includes specialized and niche players who offer tailored solutions. Alkan S.A. in France specializes in sonobuoy launcher solutions for naval and aircraft platforms. JSK Naval Support Inc. in Canada provides niche launcher solutions tailored to specific mission requirements and platform integration. Geospectrum Technologies Inc. focuses on launcher systems with an emphasis on acoustic technology and underwater surveillance. Marshall Aerospace and Defence Group delivers launch carousel assemblies and related components, while MES S.p.A. produces light stores dispensing units and composite launch tubes for sonobuoy and similar expendable stores.
Our report provides a detailed competitive benchmarking analysis, evaluating each firm's market share relative to the competitive landscape. The market concentration is significant, with the top three players holding a substantial portion of the revenue and the top five commanding a dominant share. This structure influences pricing power, supply chain resilience, and the pace of innovation. Stakeholders must understand these dynamics to negotiate effectively or identify potential gaps in the market for new entrants.
Industry Dynamics and Emerging Trends
Several macro trends and regulatory developments are reshaping the sonobuoy launcher market. The U.S. Navy's FY2026 budget continues to support sonobuoy programs across P-8, P-3, and H-60 platforms. There is a strong emphasis on maintaining a healthy industrial base through multiple qualified vendors for sonobuoy and associated launcher components. This policy environment favors established players while creating opportunities for secondary suppliers to qualify for niches.
Technological evolution is also a major driver. The integration of sonobuoy launchers with unmanned platforms is gaining traction. The U.S. Navy's SBIR Topic N251-016, released in December 2024, highlights the development of expendable sonobuoy-launched UAVs for ASW cued search from P-8A launcher infrastructure. This convergence of unmanned systems and traditional launcher architecture represents a frontier for innovation and potential market expansion. Additionally, raw material considerations remain relevant. Sonobuoy launch containers and related structures historically utilize aluminum cylinders and composite materials for launch tubes to achieve lightweight, durable performance under air-deployed conditions. Fluctuations in material costs or supply constraints can impact production timelines and pricing.
Geopolitical factors further influence demand. A rising focus on anti-submarine warfare capabilities drives demand for sonobuoy launchers in naval modernization programs, particularly in North America and allied nations operating P-8A and MH-60 platforms. Regional security concerns and the need to counter advanced submarine threats in key maritime corridors are prompting governments to invest in robust ASW architectures. These geopolitical currents ensure that demand for reliable launcher systems remains a priority for defense budgets globally.
Inside the Report: Operational Content and Analytical Tools
The Worldwide Sonobuoy Launcher Market report is structured to provide maximum utility for strategic planning. It goes beyond descriptive statistics to offer analytical frameworks that support decision-making. The report includes a comprehensive overview of the market ecosystem, covering definitions, scope, and key product classifications. It details the segmentation by region, type, and platform, allowing readers to isolate specific areas of interest.
A major component of the study is the competitive landscape analysis. Each key company is profiled with information on headquarters, product offerings, recent contract awards, and strategic initiatives. These profiles are supported by data on market share and concentration, providing context for competitive intensity. The report also examines the value chain, from raw material suppliers of aluminum and composites to the integrators and end-users within naval organizations.
Furthermore, the analysis incorporates a review of industry dynamics, including regulatory frameworks, technological trends, and macroeconomic factors. The historical data from 2020 to 2025 is presented to establish baselines, and the forecast data through 2032 offers a forward-looking perspective. Methodologies are clearly outlined to ensure transparency and reliability. Stakeholders can use this information to validate internal forecasts, identify supplier risks, and explore potential partnership opportunities.
Our research emphasizes actionable insights. For procurement professionals, the report highlights vendor capabilities and contract trends that can inform sourcing strategies. For investors, the growth projections and segment analysis help assess the viability of market entry or expansion. For defense planners, the technological and platform integration details support requirements definition and capability planning. The report is designed to be a reference tool that can be consulted repeatedly as the market evolves.
Strategic Recommendations for 2026 Decision-Makers
Based on the prevailing market signals, organizations should consider several strategic priorities. First, maintaining visibility into the status of key platform programs is essential. The P-8A Poseidon and H-60 helicopter fleets are central to launcher demand, and any changes in procurement rates or retrofit requirements will directly impact the market. Second, monitoring the progress of unmanned integration is critical. The potential for sonobuoy-launched UAVs could alter the requirements for launcher infrastructure and create new niches for specialized components. Third, supply chain resilience should be a focus. Given the concentration of the market and the emphasis on qualified vendors, ensuring access to reliable suppliers and understanding the material dependencies of launcher systems is vital for operational continuity.
Finally, stakeholders should engage with the full intelligence available in our research. While this introduction highlights the key themes, the detailed segmentation data, market size breakdowns, and competitive share analysis are available in the complete report. Access to this granular level of detail is necessary for precise valuation, risk assessment, and strategic positioning.
Conclusion: Accessing Comprehensive Market Intelligence
The Worldwide Sonobuoy Launcher Market is at a juncture where sustained growth meets technological evolution and shifting strategic priorities. The revenue trajectory, competitive concentration, and emerging trends all point to a market that is vital for modern naval capabilities. However, navigating this market requires more than a high-level overview. It demands deep, data-driven insights that reveal the nuances of segmentation, the specifics of vendor performance, and the probabilities of future growth.
PW Consulting's new market research report provides the depth and rigor required for informed decision-making in 2026. By combining historical analysis with forward-looking forecasts and detailed competitive profiling, the study offers a complete view of the landscape. We invite defense executives, strategic planners, and industry leaders to explore the full findings to unlock the intelligence needed to drive success. The complete dataset, including regional and segment-specific figures, is available for download. Access the source webpage today to obtain the full report and ensure your organization is equipped with the insights necessary to thrive in this dynamic market.
For detailed analysis of this topic, please visit the official page: Worldwide Sonobuoy Launcher Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Dry Electrostatic Precipitator Market Hits $3.8B in 2025, Growing 4.12% CAGR Through 2032
By pmarketresearch, 2026-09-16
Global Dry Electrostatic Precipitator Market Outlook 2026: Strategic Imperatives for Industrial Emission Control
The global industrial landscape is undergoing a seismic shift in how particulate matter is managed, driven by tightening environmental regulations and the urgent need for operational efficiency. As we move into 2026, the Dry Electrostatic Precipitator (ESP) market stands at a critical inflection point. For executives in power generation, steel, cement, and chemical sectors, understanding the trajectory of this market is no longer optional—it is a strategic necessity. This analysis draws upon the latest comprehensive market research to outline the forces shaping the industry and the opportunities available for stakeholders who act decisively.
Market Trajectory and Growth Dynamics
The historical performance of the dry ESP sector reveals a steady, resilient expansion pattern. From 2020 to 2025, the market demonstrated consistent revenue growth, reflecting the ongoing industrialization of emerging economies and the retrofitting needs of established infrastructure in developed nations. As of the base year 2025, the overall market valuation has solidified, setting a robust foundation for the forecast period extending through 2032.
Looking ahead, the forecast period from 2026 to 2032 indicates a continued upward trend in revenue. The projected Compound Annual Growth Rate (CAGR) during this timeframe underscores a moderate but stable growth environment. This growth is not merely a function of volume but is deeply tied to technological upgrades and compliance-driven investments. Organizations that align their capital expenditure plans with this growth trajectory will be better positioned to capture market share and optimize their environmental compliance portfolios.
Key macro drivers are fueling this demand. The global push for carbon neutrality has intensified the focus on capturing submicron particles, necessitating upgrades to existing filtration systems. Furthermore, regulatory bodies across major economies are enforcing stricter emission standards. For instance, mandates requiring high particulate removal efficiency for coal-fired plants are accelerating the replacement cycle of older equipment. Similarly, directives in Europe regarding industrial emissions are compelling manufacturers to adopt advanced dry ESP technologies to meet stringent limits. These regulatory pressures convert compliance from a cost center into a strategic investment area, driving the overall market valuation toward higher peaks in the late 2020s.
Segmentation Insights: Configuration and End-User Dynamics
Understanding the structural composition of the market is vital for targeted strategy development. The market is primarily bifurcated by configuration, with distinct advantages offered by different technological setups. The single-stage dry ESP configuration currently holds a significant share of the revenue landscape. This dominance is attributed to its widespread application in large-scale industrial processes where established infrastructure supports this technology. However, the two-stage dry ESP segment represents a crucial area of growth, particularly for applications requiring higher efficiency and lower pressure drops.
On the demand side, the power generation sector remains the cornerstone of market consumption. As the largest end-user category, it drives substantial revenue through both new installations and retrofits aimed at meeting modern emission standards. Following closely, the steel and metallurgy industry constitutes a major demand pillar. The harsh operating environments in steel mills require robust ESP solutions capable of withstanding high temperatures and corrosive conditions, making durability a key selection criterion.
Additional significant end-user segments include cement manufacturing and chemicals and petrochemicals. In the cement sector, the demand is influenced by the need for high-temperature models resistant to alkali corrosion, aligning with the processing requirements of kilns. Meanwhile, the chemicals and petrochemicals industry utilizes compact dry ESP systems for specific processes, often integrating advanced control systems for precision operation. Mining and other allied industries also contribute to the demand mix, though to a lesser extent compared to the heavy industrial giants. Each segment presents unique operational challenges, requiring tailored ESP solutions rather than a one-size-fits-all approach.
Regional Performance Patterns
Geographically, the market exhibits a diversified landscape of demand. The Asia Pacific region emerges as the leading revenue contributor, reflecting the intense industrial activity and rapid infrastructure development within this zone. The concentration of manufacturing hubs and power plants in this region necessitates substantial investment in emission control technologies.
Europe follows as a significant market, driven by mature industrial bases and stringent environmental directives that mandate continuous upgrades to pollution control systems. North America also represents a substantial market share, with demand fueled by regulatory compliance in power generation and industrial processing sectors.
Beyond these major hubs, the Middle East and Africa, as well as Latin America, present developing market opportunities. While their current revenue contributions are smaller compared to the leading regions, they offer growth potential as industrialization accelerates and environmental frameworks mature. For global players, navigating these regional nuances requires a localized strategy that accounts for specific regulatory environments, availability of raw materials, and local competitive dynamics.
Competitive Landscape and Industry Moves
The market is characterized by a moderately concentrated competitive environment. A handful of key players command a significant portion of the market revenue, yet there remains ample room for specialized entrants and innovation-driven competition. Leading companies such as Babcock & Wilcox, GE Power, Hitachi Zosen, Mitsubishi Heavy Industries, Sumitomo Heavy Industries, FLSmidth, and Dürr AG are pivotal in shaping the industry standards.
These corporations are not merely competing on price; they are differentiating through technological capabilities. Babcock & Wilcox, for example, has focused on delivering modular designs for high-efficiency particulate removal, recently completing a delivery for a U.S. cement plant aimed at PM2.5 compliance. Similarly, FLSmidth has showcased next-generation technologies featuring AI-optimized electrode cleaning, highlighting the industry's shift toward smart manufacturing and operational intelligence. Hitachi Zosen has secured notable contracts for steel mill expansions, emphasizing durability through rigid discharge electrodes designed for harsh environments.
Mitsubishi Heavy Industries continues to supply advanced technologies with high-voltage transformers optimized for fine particle capture, while Sumitomo Heavy Industries focuses on energy-efficient rapping systems for non-ferrous metal smelters. Dürr AG provides compact solutions for automotive and chemical industries, integrating control systems for seamless operation. GE Power emphasizes low-pressure drop systems for coal-fired and waste-to-energy plants. This diversification in product offerings means that procurement decisions are increasingly complex, requiring buyers to evaluate specific technical fit rather than relying on brand reputation alone.
Recent industry activity underscores the dynamism of this sector. Throughout 2025 and into 2026, key players have engaged in strategic deliveries, trade show showcases, and contract awards that signal their commitment to specific verticals. These moves suggest that competition will intensify in areas where regulatory deadlines are closest, particularly in power generation and cement manufacturing. Companies that can demonstrate proven compliance records and reliability in harsh conditions will likely gain preference in bidding processes.
Worldwide Dry Electrostatic Precipitator Market
Electrostatic Precipitators (ESP) Market
Operational Challenges and Cost Factors
While the growth outlook is positive, stakeholders must navigate several headwinds affecting cost structures and supply chain stability. One significant factor is the volatility in raw material prices. High-voltage steel transformer cores, essential components for dry ESPs, have experienced price increases due to alloy shortages. This cost pressure flows downstream, affecting the overall capital expenditure required for new installations or major upgrades.
Component costs also remain a critical consideration. Specialized stainless steel used for rigid discharge electrode plates has seen average industrial quotes reach significant levels per meter. These costs impact the total cost of ownership and must be factored into long-term budgeting. Organizations need to weigh the upfront investment against the long-term benefits of efficiency and compliance.
Furthermore, the regulatory landscape continues to evolve. Standards mandating extremely high particulate removal efficiency for coal plants are driving retrofits, which can strain existing operational budgets. The requirement to capture submicron particles under various international directives means that older units may become obsolete faster than anticipated, forcing unplanned capital expenditures. Supply chain resilience is therefore crucial; relying on single-source suppliers for critical components like transformer cores or specialized electrodes could expose operations to delays and cost spikes.
Strategic Recommendations for Stakeholders
For industry leaders planning their 2026 strategy, several actions are recommended based on the current market intelligence.
- Prioritize Compliance Upgrades: With regulatory deadlines approaching, allocating capital for ESP retrofits should be a top priority. Delaying these investments risks non-compliance penalties and operational shutdowns.
- Evaluate Total Cost of Ownership: Beyond the initial purchase price, consider energy efficiency, maintenance requirements, and component longevity. Technologies that offer lower pressure drops and energy-efficient rapping systems can reduce operational expenditures over the equipment's lifecycle.
- Monitor Supply Chain Vulnerabilities: Given the volatility in steel and alloy prices, diversifying suppliers or securing long-term contracts for critical components can mitigate cost risks.
- Invest in Intelligent Systems: The emergence of AI-optimized cleaning and integrated control systems suggests a future where predictive maintenance and automated adjustments drive efficiency. Early adoption of these technologies may provide a competitive edge in operational reliability.
- Segment-Specific Solutions: Avoid generic procurement. Engage with vendors who understand the specific demands of your industry, whether it is alkali corrosion resistance for cement or durability for steel mills.
Conclusion
The Dry Electrostatic Precipitator market is poised for steady evolution through the end of the decade. Driven by regulatory mandates, industrial expansion, and technological innovation, the sector offers substantial opportunities for those who navigate it with informed precision. The convergence of macro drivers like carbon neutrality goals and micro-level factors such as component costs creates a complex decision-making environment. Success in this landscape requires more than just monitoring market size; it demands a deep understanding of segmentation dynamics, competitive moves, and operational constraints.
Access to granular data regarding regional splits, specific end-user valuations, and detailed configuration breakdowns is essential for crafting a winning strategy. While the high-level trends provide direction, the specific metrics needed to justify capital allocation and vendor selection lie within the detailed analysis. Stakeholders are encouraged to engage with the full market research report to unlock the comprehensive intelligence required to make decisive, data-backed decisions in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Dry Electrostatic Precipitator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Blood Thinning Drugs Market to Reach $90.63 Billion by 2032 with 8.5% CAGR
By pmarketresearch, 2026-09-16
Strategic Horizons in the Global Blood Thinning Drugs Market Through 2032
The worldwide market for blood thinning drugs is entering a defining inflection point. As healthcare systems grapple with aging populations, rising prevalence of atrial fibrillation, and evolving regulatory landscapes, the therapeutic category continues to attract sustained investment and strategic attention. This analysis draws directly from our newly released Worldwide Blood Thinning Drugs Market research, offering executive decision-makers a structured view of where value will be created, where volatility will emerge, and how to position portfolios against the forecast horizon spanning 2026 to 2032.
The baseline has sharpened considerably. Historical tracking from 2020 through 2025 demonstrates consistent expansion, with the overall market reaching an estimated value in the 2025 base year before advancing toward a projected trajectory that places the category at a materially larger revenue footprint by the close of the decade. The compound annual growth rate across the full forecast window is tracked at 8.5 percent, a pace that underscores durable demand drivers rather than a temporary post-pandemic rebound. What matters now for leadership teams is not simply the headline trajectory but the structural forces shaping it, the competitive transitions underway, and the hidden inflection points that will separate opportunistic positioning from durable advantage.
Macro Trajectory and Revenue Architecture
The revenue architecture of the blood thinning segment reflects a broad but increasingly differentiated landscape. Baseline valuations for 2023 and 2024 already signaled robust momentum, and the upward continuation into 2025 established a strong platform for the forecast years. Rather than relying on a single therapeutic pillar, the category derives strength from a multi-drug-class composition that balances mature anticoagulants with newer direct oral agents, alongside injectable heparin-based formulations and vitamin K antagonists that retain relevance in specific clinical pathways.
The forecast curve shows sustained year-over-year growth as the market advances through 2026, 2027, and beyond, culminating in a substantially larger revenue base by 2032. This expansion is not uniform. It is shaped by therapeutic adoption patterns, regional purchasing dynamics, payer access environments, and the ongoing shift in clinical practice toward agents with improved safety profiles and simplified monitoring requirements. For strategy teams, the implication is clear: aggregate growth narratives can obscure divergence within segments, and effective planning requires a view that separates headline momentum from the underlying demand engines.
The report provides a detailed walk-through of that divergence. It maps how distinct drug classes, clinical indications, and regional markets interact with pricing pressure, formulary positioning, and supply continuity, offering a foundation for scenario planning rather than a static snapshot. Leaders who connect these structural layers to their internal pipeline, manufacturing footprint, and commercial access strategy will be best positioned to translate macro growth into realized share.
Segmentation and Demand Drivers
Understanding where demand is concentrated requires looking past the total revenue figure into the shape of the market itself. The therapeutic landscape is anchored by direct oral anticoagulants, which command the largest revenue share and continue to benefit from clinical preferences grounded in favorable safety profiles and the elimination of routine monitoring. Heparin and low molecular weight heparin categories remain foundational, particularly in hospital and inpatient settings, and their production depends on chain reliability for porcine mucosal raw materials. Vitamin K antagonists and other anticoagulant options continue to serve important, if narrower, roles in specific patient populations and treatment protocols.
On the indication side, atrial fibrillation represents the dominant clinical driver, supported by widespread screening, aging demographics, and expanded therapeutic eligibility. Deep vein thrombosis and pulmonary embolism form the next tier of demand, with treatment and prevention pathways intersecting both outpatient and inpatient care settings. Additional indications round out the demand base, contributing incremental but strategically relevant volume.
Regionally, the market reflects a concentration pattern that rewards both established commercial infrastructure and disciplined entry strategies. North America and Europe remain central revenue anchors, while the Asia Pacific region represents a substantial and expanding share of global demand. Latin America and the Middle East and Africa collectively contribute meaningful volume, and each geography carries its own reimbursement conditions, procurement rhythms, and regulatory cadence. The report provides a complete regional and application breakdown, but the strategic takeaway for now is that regional intensity differs not only in scale but in time-to-value, access constraints, and competitive density.
Supply chain considerations add another layer of complexity. Heparin-based production in particular depends on stable sourcing of raw materials, and any disruption in that chain can create ripple effects across pricing, availability, and hospital procurement. Simultaneously, the broader transition toward direct oral agents continues to reshape prescription patterns, driven by their operational advantages in routine care. The interplay of these drivers is examined in depth within the research, with the objective of helping organizations anticipate rather than react to demand shifts.
Heparin Market
Competitive Landscape and Strategic Positioning
The competitive field in blood thinning drugs is defined by both concentration and specialization. At the top of the market, a small group of leading firms accounts for an outsized share of revenue, reflecting the scale advantages of patented oral anticoagulants, entrenched formulary positions, and established global commercialization capabilities. This concentration creates a dual reality: it signals durable franchise value for incumbents, but it also raises the stakes for differentiation, access negotiations, and lifecycle management as patent timelines advance.
Bristol-Myers Squibb Company and Pfizer Inc. continue to co-market Eliquis, a leading direct oral anticoagulant positioned for stroke prevention in non-valvular atrial fibrillation and for the treatment and prevention of venous thromboembolism. Their shared commercial footprint has made Eliquis a central reference point in the oral anticoagulant category. Bayer AG markets Xarelto, a direct Factor Xa inhibitor indicated across stroke prevention, DVT and PE treatment, and broader cardiovascular event reduction, while Johnson & Johnson, through Janssen Pharmaceuticals, co-markets Xarelto and extends the category with additional anticoagulation options in its broader portfolio. Boehringer Ingelheim International GmbH markets Pradaxa, a direct thrombin inhibitor used in atrial fibrillation stroke prevention and DVT/PE management, and Daiichi Sankyo Company, Limited markets Savaysa/Lixiana, another direct Factor Xa inhibitor serving stroke prevention and VTE treatment needs.
Beyond the branded oral anticoagulant leaders, a second tier of competitors competes with depth in injectable and heparin-based formulations. Sanofi S.A. produces Lovenox, a low molecular weight heparin widely used across both hospital and outpatient anticoagulation settings. Aspen Pharmacare Holdings Limited specializes in generic and branded heparin-based anticoagulants and low molecular weight heparins for global distribution. GlaxoSmithKline plc offers Arixtra, a synthetic Factor Xa inhibitor for prevention and treatment of thromboembolic conditions. F. Hoffmann-La Roche Ltd supports anticoagulation-related therapeutic areas through diagnostics and biologics, while Dr. Reddy's Laboratories Ltd. manufactures generic versions of key anticoagulants, including rivaroxaban and enoxaparin, for global supply. Amphastar Pharmaceuticals Inc. produces generic heparin and enoxaparin injectable anticoagulants for hospital use, Baxter International Inc. supplies heparin-based anticoagulants and injectable formulations for critical care, and Fresenius Kabi AG manufactures generic enoxaparin and other injectable anticoagulants for worldwide distribution.
This competitive configuration matters because it determines where pricing power persists, where generic erosion accelerates, and where operational execution in supply, access, and formulation becomes the decisive advantage. The report unpacks these dynamics systematically, allowing executive teams to evaluate each player's exposure to patent transitions, generic entry, hospital procurement patterns, and regional formulary pressure without relying on incomplete secondhand narratives.
Regulatory and Commercial Dynamics Shaping 2026 and Beyond
The market is being re-shaped not only by demand drivers but by discrete regulatory and commercial events that can alter revenue trajectories quickly. One notable development is the voluntary withdrawal of Andexxa, the reversal agent for Factor Xa inhibitors rivaroxaban and apixaban, from the US market following FDA analysis showing that risks of thromboembolic events outweighed benefits. This regulatory outcome has implications for safety perceptions, clinical protocol design, and the broader risk-management framework around Factor Xa inhibitor use.
At the same time, competitive and access dynamics are shifting on the generic side. In March 2025, the FDA approved the first generics of Xarelto 2.5 mg tablets for the reduction of major cardiovascular events in adult patients with coronary artery disease or peripheral artery disease. This expansion of generic availability changes the cost and access calculus in a specific but commercially meaningful indication set.
A further catalyst is approaching in the European market. The European market exclusivity for Eliquis is set to expire in May 2026, opening the door for generic entry across the region. Analyst projections indicate a corresponding decline in global sales for the reference product in 2026, underscoring the sensitivity of branded oral anticoagulant revenue to patent timelines and generic competition. This transition will test incumbent positioning, regional pricing strategy, and the ability of competitors to capture share without disrupting care continuity.
Worldwide Blood Thinning Drugs Market
Other forces are less dramatic but no less important. Ongoing adoption of direct oral anticoagulants continues to be driven by their improved safety profile relative to warfarin and the absence of routine monitoring requirements, supporting broader use in atrial fibrillation and VTE management. Meanwhile, heparin and low molecular weight heparin production depends on consistent supply chains for porcine mucosal extracts, with major manufacturers maintaining active global production to support hospital and outpatient demand. Each of these forces is integrated into the research narrative, with the intent of giving strategy teams a current and actionable view of the operating environment.
What the Research Delivers: Content and Analytical Coverage
The Worldwide Blood Thinning Drugs Market study is designed as a decision-support instrument rather than a descriptive overview. It begins with a full historical reconstruction from 2020 through the 2025 base year, establishing the trajectory and growth pattern needed to evaluate whether recent momentum is structurally sustainable. From that baseline, the forecast spans 2026 through 2032, providing year-by-year revenue projections that support budgeting, capacity planning, and investment prioritization.
The report contains detailed segmentation analysis across drug class, indication, and region, enabling teams to pinpoint where growth is being generated and where share shifts are most likely. It profiles the competitive landscape across the leading branded and generic participants, mapping each company's product footprint, therapeutic focus, and strategic posture. Recent developments are integrated directly into the market dynamics discussion, so that patent expirations, generic approvals, and regulatory actions are not treated as isolated news items but as inputs to forward-looking strategy.
In addition to quantitative estimates, the research covers market concentration, supply chain dependencies, access and reimbursement considerations, and the clinical logic that underpins prescribing shifts. This combination allows the document to serve multiple internal audiences: commercial leaders can use it for access and share strategy, R&D and pipeline teams can benchmark therapeutic positioning, and supply and operations teams can assess continuity risk in vulnerable categories. The aim is to provide a single, coherent framework for evaluating how the category will evolve and where specific organizational decisions will have the greatest impact.
Strategic Implications for 2026 Decision-Makers
For organizations operating in or adjacent to the blood thinning drugs category, the forecast window rewards disciplined prioritization. The most immediate strategic question is how to respond to the European exclusivity transition for Eliquis in 2026. Companies with exposure to oral anticoagulants should assess the likely pace and pattern of generic entry, the resilience of branded pricing, and the potential for regional share redistribution. Those with generic portfolios should evaluate whether supply readiness, regulatory positioning, and tender access are sufficient to capture opportunity without compromising margin quality.
A second priority is the management of concentration risk in heparin and low molecular weight heparin supply. Because production depends on stable raw material sourcing, any interruption can affect availability and pricing across hospital and outpatient channels. Mapping exposure across manufacturing relationships, inventory buffers, and regional procurement requirements should be part of any operational risk review.
A third priority is the continued integration of clinical and access strategy. Direct oral anticoagulants are likely to retain adoption momentum given their safety and monitoring advantages, but access conditions, formulary placement, and regional reimbursement realities will determine how that momentum translates into revenue. Teams should use the segmentation detail to match commercial assets to the indication and geography combinations where adoption potential is strongest.
Finally, the category's concentration profile suggests that competitive intelligence should be continuous rather than episodic. With a small group of firms accounting for a large share of revenue, even localized formulary changes or regulatory actions can alter competitive balance. The report provides the structural baseline needed to interpret those moves accurately and to adjust strategy without overreacting to isolated events.
Conclusion: Positioning for the Forecast Period
The blood thinning drugs market is moving through a period in which growth, concentration, and transition intersect. The projected 8.5 percent compound annual growth rate through 2032, anchored by a large revenue base already established in the 2025 base year, signals that the category remains strategically important. Yet the real value of the research lies in its ability to show where that growth will be distributed, how competitive exposure is changing, and what events in 2025 and 2026 mean for the years that follow.
For executive teams, the central task is to convert macro certainty into operational precision. That requires a view that goes beyond headline size and connects drug-class dynamics, indication demand, regional variation, supply continuity, and regulatory catalysts into one decision-ready framework. The Worldwide Blood Thinning Drugs Market research is built to provide exactly that view, with full segmentation data, complete competitive profiling, and detailed scenario support available in the full report. Readers seeking the granular figures, regional splits, indication shares, and company-level positioning should access the complete study to ensure strategic decisions are grounded in the full evidence base.
For detailed analysis of this topic, please visit the official page: Worldwide Blood Thinning Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Intelligence for the Next Decade: Inside the Worldwide Contraceptive Pills Market
The global contraceptive pills market stands at a pivotal inflection point. Between 2020 and 2032, the sector is projected to expand from a baseline exceeding 16 billion USD to a forecasted valuation approaching 34.5 billion USD, reflecting a compound annual growth rate of 6.51 percent. This trajectory is not merely a function of demographic expansion; it is the compound result of regulatory innovation, shifting reimbursement architectures, formulation breakthroughs, and deeply entrenched competitive dynamics that reward foresight. For executives navigating portfolio allocation, market entry, pricing strategy, or supply chain optimization, understanding the structural forces shaping this landscape has transitioned from a nice-to-have to an operational imperative.
Our latest comprehensive research, Worldwide Contraceptive Pills Market, delivers a granular, forward-looking intelligence framework designed specifically for enterprise decision-making in 2026 and beyond. Rather than offering static historical snapshots, this study maps the causal mechanisms driving demand, dissects the competitive maneuvers defining share allocation, and quantifies the momentum vectors that will separate strategic winners from reactive followers. Below, we outline the analytical architecture of the report and demonstrate how its insights translate into actionable corporate strategy.
A Market Defined by Regulatory Disruption and Formulation Evolution
The industry is undergoing a structural recalibration. The United States regulatory environment has already catalyzed measurable behavioral shifts. Following the historic approval of the first nonprescription daily oral contraceptive, availability expanded across retail and digital channels in early 2024, accompanied by a suggested retail price of approximately 19.99 USD for a one-month supply. Subsequent observational studies documented increased utilization rates in the months that followed, underscoring how convenience and reduced access friction can rapidly reshape consumption patterns.
Worldwide Contraceptive Pills Market
Parallel regulatory milestones have broadened the formulation frontier. The introduction of the first orally disintegrating tablet for pregnancy prevention addressed long-standing adherence barriers for populations with swallowing difficulties, while signaling a broader industry pivot toward patient-centric delivery mechanisms. Looking ahead, additional over-the-counter combined oral contraceptive candidates are progressing toward formal submission windows, with applications anticipated around the middle of the decade. These developments are not isolated product launches; they represent architectural changes in how contraception is accessed, reimbursed, and prescribed across different payer ecosystems.
Reimbursement dynamics remain equally critical. In the United States, the majority of women with private insurance or Medicaid continue to receive no-cost coverage for prescription oral contraceptives, yet coverage for over-the-counter alternatives remains fragmented and heavily dependent on state-level policy in the absence of sweeping federal guidance. This creates a bifurcated market environment where channel strategy, pricing architecture, and formulary positioning must be calibrated with precision rather than assumed through broad generalizations.
Simultaneously, procurement economics in low- and middle-income countries reveal that pill acquisition costs still command the largest single share of total supply expenditures, with private-sector operators handling a disproportionate share of both end users and associated costs. These cost structures directly influence sourcing decisions, margin modeling, and the viability of tiered-market strategies for multinational manufacturers seeking sustainable scale.
Decoding the Segmentation Architecture
The report disaggregates the market across three foundational dimensions, each carrying distinct strategic implications for product development, channel management, and regional prioritization.
By formulation type, the analysis separates combined oral contraceptives, progestogen-only variants, and emergency contraception. Each category operates under different clinical positioning, demand elasticity, prescribing habits, and reimbursement pathways. The relative weight of these segments shifts meaningfully across regions and over time, influenced by guideline updates, cultural attitudes, and the speed of generic conversion.
By distribution channel, the market is mapped across retail pharmacies, hospital pharmacies, and online pharmacies. The interplay among these channels is becoming increasingly nonlinear as digital procurement, mail-order fulfillment, and self-access models reshape traditional dispensing hierarchies. Channel economics, inventory velocity, and patient acquisition costs differ substantially across these pathways, and procurement or commercial leaders require precise visibility into which channels are capturing incremental volume under current regulatory and reimbursement conditions.
By geography, the study illuminates regional demand intensity, maturity curves, and growth acceleration patterns. Mature markets exhibit stable baseline volumes with innovation-driven differentiation, while emerging markets reflect demographic momentum, public health program integration, and evolving private-sector penetration. The report tracks how these regional ecosystems diverge in terms of competitive intensity, pricing norms, and regulatory cadence, enabling firms to align resource deployment with the markets where strategic leverage is highest.
Crucially, the full segmentation breakdown, including precise regional and type-level valuations, is reserved within the complete report. This deliberate approach ensures that clients receive contextualized strategic guidance rather than fragmented figures, while preserving the research as a curated intelligence asset that rewards direct engagement.
Competitive Landscape: Concentration, Maneuvering, and Innovation Velocity
Market structure analysis reveals a moderately concentrated competitive environment. The top three participants collectively account for a substantial share of total revenue, while the leading five firms extend their footprint further. Such concentration underscores the importance of portfolio optimization, lifecycle management, and channel leverage, but it does not diminish the strategic relevance of agile generic manufacturers and specialty innovators who are actively reshaping sub-segments.
Industry leadership is anchored by global pharmaceutical organizations with deep women's health portfolios and established commercial infrastructure. Bayer AG continues to maintain a prominent position through established combined and progestin-only oral contraceptives. Pfizer Inc. sustains a broad hormonal contraceptive presence and leverages its global commercialization engine to defend and expand share. Organon & Co. has sharpened its focus on women's health, embedding oral contraceptive offerings within a deliberately structured reproductive health portfolio. Merck & Co., Inc. and Johnson & Johnson, through its Janssen segment, contribute additional branded and portfolio-based depth to the branded end of the market. AbbVie Inc., incorporating legacy Allergan assets, reinforces its footprint in the hormonal contraceptive category through established product lines.
Generic manufacturing and accessible pricing strategies define another critical competitive axis. Teva Pharmaceutical Industries Ltd. operates as a leading generic producer with an extensive portfolio of branded equivalents, while Perrigo Company PLC has captured strategic attention through its pioneering role in over-the-counter access, bringing the first FDA-approved nonprescription daily oral contraceptive to mainstream retail and digital distribution. Amneal Pharmaceuticals LLC further extends the generic footprint with oral contraceptive products integrated into its broader portfolio.
Indian pharmaceutical manufacturers constitute a highly active and globally oriented production base. HLL Lifecare Limited operates as a government-linked enterprise with wide-ranging oral contraceptive production, including supply alignments with public health programs. Aurobindo Pharma Limited, Lupin Pharmaceuticals Inc., Cipla Inc., Zydus Lifesciences Ltd., and Sun Pharmaceutical Industries Ltd. each maintain active generic portfolios targeting domestic and international markets, with Lupin pursuing tentative approvals for specific active ingredient combinations and the broader group collectively supporting affordability, supply continuity, and cross-border distribution flexibility.
Recent industry developments illustrate how quickly competitive conditions can evolve. The widespread retail and online availability of the first over-the-counter daily oral contraceptive following its 2023 approval demonstrated how regulatory milestones can translate rapidly into market behavior. The introduction of the first orally disintegrating combined formulation broadened the clinical utility spectrum. Observational data from mid-2025 confirmed rising utilization patterns after over-the-counter availability expanded, reinforcing the strategic importance of anticipating adoption curves and adjusting supply, pricing, and awareness investments accordingly.
Detailed competitor profiles, capability assessments, pipeline positioning, and strategic grouping are fully developed within the report, enabling leadership teams to benchmark their posture against actual market architecture rather than surface-level brand presence.
Fertility Drugs Market
The 2026 Decision Lens: Why This Research Matters Now
As corporate planning cycles move deeper into 2026, several interrelated questions demand evidence-based answers: How will over-the-counter availability alter channel economics and payer negotiations? Which formulation categories will capture the fastest incremental demand under evolving clinical guidelines? Where should manufacturing and distribution capacity be prioritized to align with regional growth acceleration? How can firms balance branded differentiation with generic affordability while navigating reimbursement fragmentation? What competitive moves are likely from both incumbents and emerging generic or specialty entrants?
This report is designed to answer those questions with structured rigor. It integrates historical trajectory, forward-looking forecast modeling, segmentation mapping, competitive profiling, and regulatory and reimbursement context into a unified decision-support framework. Analysts, strategists, and commercial leaders will find practical utility in its treatment of demand drivers, supply economics, channel behavior, and competitive response patterns. Rather than presenting isolated numbers, the study connects market signals to operational consequences, helping organizations stress-test assumptions, prioritize investments, and anticipate second-order effects.
What the Report Delivers
The full study offers an end-to-end market assessment calibrated for executive and operational use. Its scope includes:
- Historical performance tracking across the base year and preceding years, establishing baseline trends and volatility patterns
- Forward-looking forecasts through the end of the decade, anchored in explicit growth assumptions and segmentation logic
- Granular segmentation analysis across type, distribution channel, and region, with narrative interpretation of structural drivers
- Competitive profiling of leading global, generic, and emerging market manufacturers, including portfolio orientation and strategic positioning
- Regulatory, reimbursement, and procurement context that shapes access, pricing, and demand elasticity across different market environments
- Synthesis of recent developments, including over-the-counter access expansion, novel formulation approvals, and utilization trend data
- Strategic implications for market entry, portfolio allocation, channel strategy, pricing architecture, and competitive response
To preserve analytical integrity and maximize strategic value, detailed tables, precise segmentation valuations, and full quantitative forecasts are provided within the complete downloadable research. This approach allows us to demonstrate methodological depth while ensuring that market participants receive the complete dataset required for planning, modeling, and executive review.
Moving From Intelligence to Execution
The worldwide contraceptive pills market is being reshaped by regulatory innovation, formulation diversity, channel expansion, reimbursement complexity, and competitive maneuvering across both branded and generic domains. These forces create opportunity for organizations that act on detailed evidence rather than broad assumptions. Our Worldwide Contraceptive Pills Market research is built to provide that evidence with clarity, structure, and strategic relevance.
For decision-makers seeking to align product strategy, commercial planning, and market positioning with the most current and comprehensive industry intelligence, the full report offers the depth and precision necessary to convert insight into execution. Explore the complete analysis, access the detailed segmentation and forecast data, and equip your team with the intelligence required to navigate the next phase of market evolution with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Contraceptive Pills Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Women's Non-athletic Footwear Market Hits $188.4M in 2025, Projects 4.5% CAGR to 2032
By pmarketresearch, 2026-09-16
Navigating Growth and Complexity in the Global Women's Non-Athletic Footwear Market (2026-2032)
The global women's non-athletic footwear market stands at a pivotal juncture in 2026. As consumer preferences shift towards a blend of comfort, style, and sustainability, industry leaders must navigate a landscape defined by volatile raw material costs, evolving regulatory standards, and intense competition among luxury conglomerates and contemporary brands. PW Consulting's latest comprehensive study, Worldwide Women's Non-athletic Footwear Market, offers a critical roadmap for stakeholders aiming to capitalize on projected growth through 2032.
This report is not merely a statistical overview; it is a strategic instrument designed to inform product development, supply chain resilience, and market entry strategies. By analyzing historical performance from 2020 to 2025 and forecasting trends through 2032, this research provides the granularity needed to make informed decisions in a fragmented yet lucrative sector.
Worldwide Women's Non-athletic Footwear Market
Market Trajectory and Valuation Overview
The market has demonstrated resilient growth over the past five years, recovering from pandemic-era disruptions to establish a robust upward trajectory. In 2020, the global revenue for women's non-athletic footwear stood at approximately USD 148,500 million. By 2025, this figure had climbed to USD 188,400 million, reflecting a compound annual growth rate that underscores the category's inherent demand drivers. Looking ahead, the forecast period from 2026 to 2032 suggests continued expansion, with valuations projected to reach USD 256,390 million by the end of the forecast window.
This growth is not linear. The forecast model anticipates fluctuations that reflect broader economic conditions, such as the slight contraction observed in the 2029 projection compared to 2028, before resuming growth. Understanding these nuances is vital for capacity planning and inventory management. The report details the specific drivers behind these peaks and troughs, linking them to consumer confidence indices, disposable income trends, and seasonal fashion cycles. For executives planning capital allocation in 2026, grasping the velocity of this growth is essential to avoid overstocking or missed opportunities during high-demand periods.
Deep Dive into Product Categories and Material Dynamics
The market is segmented into distinct product categories, each with its own growth 잠재력을 및 consumer appeal. While the total market value is significant, the distribution of revenue across categories reveals where consumer spend is concentrating. Boots, casual shoes and loafers, sandals, heels and pumps, and flats and wedges represent the core pillars of this industry. The report provides a detailed breakdown of how each category performed historically and how it is expected to evolve.
For instance, the demand for comfortable yet stylish options has pushed casual shoes and loafers into prominence, while seasonal shifts continue to drive sandal and boot sales. Meanwhile, the enduring popularity of heels and pumps in professional and formal settings maintains a steady revenue stream for luxury and contemporary brands alike. Our analysis goes beyond basic volume counts to explore the price elasticity within each category, helping brands identify where premiumization strategies might succeed versus where value-oriented positioning is required.
Material composition remains a critical cost and branding lever. Leather continues to hold a substantial share of the material market, valued for its durability and prestige. However, supply chain volatility poses risks. Raw material data indicates that wet-blue leather prices rose significantly in early 2025, driven by drought conditions impacting cattle herds in Brazil. Additionally, regulatory constraints in India led to a decline in leather exports during 2024-2025. These disruptions highlight the vulnerability of leather-dependent supply chains.
Consequently, synthetic and textiles are gaining adoption for cost stability and design flexibility. The report analyzes the trade-offs between material choices, examining how brands are balancing premium perception with cost control. Furthermore, the rise of sustainability mandates is reshaping material procurement. With increased focus on ISO 14021 environmental labeling standards to address greenwashing concerns, brands must verify their material claims. Our study evaluates how different material segments are adapting to these regulatory pressures and what it means for sourcing strategies in the coming years.
Regional Consumption Patterns and Market Concentration
Geographically, the market is diverse, with consumption patterns varying significantly by region. The report segments the market into Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa. Each region presents unique opportunities and challenges, from distribution infrastructure maturity to local fashion preferences. While global brands often prioritize developed markets, emerging economies offer substantial volume growth potential.
Understanding the regional weight of each market is crucial for supply chain optimization and marketing spend allocation. The research provides a comparative analysis of regional revenue contributions without exposing sensitive granular data publicly, ensuring that clients who engage with the full report gain a competitive edge in market selection. The concentration of market power is another key focus. With a CR3 of 12.45% and a CR5 of 18.6%, the market remains relatively fragmented compared to other luxury sectors, allowing for niche players and regional specialists to thrive alongside conglomerates. However, consolidation trends are observable, particularly among mid-sized brands seeking scale to compete on logistics and sustainability compliance.
Competitive Landscape and Strategic Moves
The competitive environment is characterized by a mix of heritage luxury houses, accessible luxury groups, and specialized footwear manufacturers. Key players such as Prada SpA, LVMH, Chanel, Kering, Capri Holdings, and Tapestry Inc. dominate the high-end segment, leveraging brand equity and design innovation. These entities frequently use runway showcases to set trends that trickle down to contemporary markets. For example, recent runway presentations have highlighted reimagined classic silhouettes, such as platform Mary Janes and dipped-toe shoes, signaling shifts in aesthetic preferences that manufacturers must anticipate.
On the accessible and contemporary side, companies like Steve Madden Ltd., Skechers USA, Inc., Caleres, Inc., Bata Corporation, The ALDO Group, and VF Corporation compete on style, comfort, and price accessibility. Steve Madden continues to drive trend-focused designs at contemporary price points, while Skechers emphasizes comfort technologies like memory foam enhancements. Caleres manages a diverse portfolio through owned brands and wholesale channels, ensuring broad market reach. Bata maintains a strong presence in emerging and developed markets with affordable formal and casual styles.
Innovation in comfort and sustainability is also evident among European manufacturers. ECCO Sko A/S utilizes direct-injection technology and leather expertise to produce premium comfortable footwear. Geox S.p.A. differentiates itself with patented breathable membrane technology, appealing to consumers seeking functionality without sacrificing style. The ALDO Group focuses on fashion-forward seasonal collections that emphasize both style and accessibility. These strategic differentiators are critical in a market where product differentiation is increasingly difficult.
Recent developments underscore the dynamic nature of this landscape. In late 2025, Chanel showcased dipped-toe shoes for Spring/Summer 2026, reinforcing the luxury segment's focus on subtle detailing. Similarly, ALDO launched its Spring and Summer 2025 collection with an emphasis on enhanced comfort and sustainable materials. Within the Prada Group, Miu Miu launched the 'Tyre' sneaker collection, blending lace-up and ballerina silhouettes with flexible natural rubber soles, illustrating the blurring lines between athletic and non-athletic aesthetics. These moves are not isolated; they signal broader industry shifts towards versatility and sustainability that are dissected in depth within the full report.
Consumer Behavior and Industry Challenges
Consumer habits are reshaping the market foundation. Women's footwear accounted for a significant share of the overall footwear market in 2025, driven by demand for comfort and style in non-athletic categories. The post-pandemic preference for comfort-first designs has not diminished the desire for aesthetics; rather, it has created a hybrid demand where consumers expect both. This shift challenges brands to innovate in sole technology, ergonomics, and material breathability while maintaining fashionable silhouettes.
Supply chain resilience remains a top challenge. Beyond leather price volatility, brands must navigate labor costs, shipping logistics, and regulatory compliance across multiple jurisdictions. The industry is also grappling with sustainability expectations. Consumers and regulators alike are demanding transparency regarding material sourcing and environmental impact. The implementation of stricter environmental labeling standards requires brands to audit their supply chains rigorously. Failure to comply can result in reputational damage and market access restrictions.
Additionally, the rise of direct-to-consumer channels and digital marketing alters how brands interact with their 고객. Inventory management must become more agile to respond to real-time demand signals rather than relying solely on seasonal forecasts. The report examines how leading companies are adapting their operational models to meet these demands, offering case studies and strategic recommendations.
Footwear Market
Strategic Value for 2026 Decision-Makers
For executives navigating 2026, this report serves as a decision-support system. It answers critical questions regarding where to invest, what to produce, and how to compete. By synthesizing market size data, segmentation splits, and competitive intelligence, the study enables:
- Product Portfolio Optimization: Identify high-growth categories and materials to align design pipelines with market demand.
- Supply Chain Risk Mitigation: Understand raw material volatility and regional supply constraints to build more resilient sourcing strategies.
- Competitive Positioning: Benchmark against key players to identify gaps in the market and opportunities for differentiation.
- Regional Market Entry: Evaluate regional revenue potentials and consumer behaviors to prioritize expansion or contraction strategies.
- Sustainability Compliance: Stay ahead of regulatory changes regarding environmental labeling and material sourcing.
The insights contained within this study are derived from extensive primary and secondary research, ensuring accuracy and relevance. However, the full depth of the analysis—including precise segmentation values, regional breakdowns, and detailed company profiles—is reserved for subscribers. This approach ensures that the intelligence remains a valuable asset for strategic planning rather than public knowledge.
Conclusion
The women's non-athletic footwear market offers substantial opportunities for growth, but realizing them requires more than intuition. It demands data-driven clarity on market dynamics, competitive moves, and consumer shifts. As the industry moves through the forecast period to 2032, the ability to adapt to material cost fluctuations, sustainability mandates, and evolving style preferences will define market leaders.
PW Consulting's Worldwide Women's Non-athletic Footwear Market report provides the comprehensive intelligence needed to navigate this complexity. For organizations committed to securing their position in this evolving landscape, accessing the full dataset and strategic analysis is a critical next step. We invite stakeholders to explore the complete findings to unlock the specific insights required to drive success in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Women's Non-athletic Footwear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Hip Orthosis Market to Hit $776M by 2032, Growing at 5.25% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Hip Orthosis Market: A 2026 Outlook
The global orthopedic device landscape is undergoing a subtle transformation, and the hip orthosis segment stands at the convergence of demographic inevitability and technological refinement. As we release our latest Worldwide Hip Orthosis Market research, this analysis serves as a critical strategic compass for executives navigating 2026 planning cycles. The market has demonstrated resilient, compound growth from 2020 through 2025, with base-year revenue reaching 542.4 million USD. Forward projections indicate sustained momentum, positioning the sector to approach 576.66 million USD in 2026 and continuing toward 776.03 million USD by 2032. This trajectory reflects a 5.25 percent compound annual growth rate, a figure that carries far more significance than a headline metric. It signals durable demand drivers, evolving reimbursement pathways, and a competitive environment where product differentiation and supply-chain precision will increasingly determine share capture.
For corporate strategists, clinicians, and investors, the question in 2026 is no longer whether the hip orthosis market will grow, but where the highest-margin opportunities lie, how regulatory and reimbursement frameworks will shape procurement behavior, and which product architectures will align with shifting patient and provider expectations. This report is designed to convert macro momentum into executable insight, equipping decision-makers with the granularity required to prioritize investments, reposition portfolios, and anticipate competitive moves before they reshape the category.
Worldwide Hip Orthosis Market
The Trajectory: Translating Market Momentum Into Decision Confidence
Understanding the arc of this market requires more than observing top-line figures. The historical window from 2020 to 2025 reveals a pattern of consistent expansion, underpinned by rising surgical volumes, an aging population managing degenerative joint conditions, and growing clinical confidence in orthotic support for both post-operative protocols and chronic care management. As the forecast period unfolds from 2026 through 2032, the growth path remains stable yet nuanced. Revenue is expected to scale through 2027, place at 614.72 million USD, before reflecting anticipated demand adjustments; by 2028, the market reaches 617.55 million USD, and then resumes a steadier ascent through the remainder of the decade.
This trajectory matters because it exposes the strategic inflection points where companies must act. A moderate but reliable CAGR suggests that pure volume plays will not be sufficient to outperform. Instead, market leaders will differentiate through product efficacy, material innovation, clinician-friendly deployment, and reimbursement alignment. The report contextualizes each forecasted phase, helping leadership teams map resource allocation, capacity planning, and market-entry timing to the periods where demand signals are strongest, rather than relying on backward-looking averages.
Equally important is market concentration. With the top three participants accounting for a combined 38.5 percent share and the top five reaching 52.4 percent, the category reflects a moderately concentrated structure that still leaves meaningful room for specialized entrants and regional differentiation. This balance between established incumbency and accessible niches informs partnership strategy, distribution design, and messaging focus. Companies entering or expanding within the space must decide whether to compete through broad clinical positioning or to concentrate on application-specific solutions where clinical evidence and payer acceptance converge.
What This Report Delivers: Actionable Intelligence Beyond the Headlines
A market research study becomes strategically valuable only when it converts data into decisions. Our Worldwide Hip Orthosis Market research is structured to provide precisely that operational utility. Rather than presenting a static aggregation of figures, the study delivers an integrated analytical framework that connects market sizing, segmentation logic, competitive behavior, reimbursement architecture, and industrial dynamics into a coherent planning toolkit.
Portfolio and Segment Positioning
The report examines how product architectures and clinical applications shape revenue distribution, enabling leaders to evaluate where their offerings align with market priorities and where gaps may be exploited. By analyzing the interplay between rigid constructs and flexible or semi-rigid alternatives, as well as the relative weight of post-operative recovery, osteoarthritis and chronic condition management, hip dysplasia and congenital disorders, and trauma and fracture management, the study helps teams identify which use cases are expanding most effectively and which present the clearest value proposition for specific customer segments. This approach supports more disciplined SKU strategy, engineering prioritization, and clinical communication.
Competitive Landscape and Strategic Benchmarking
Market share data alone does not explain why certain firms hold influence. The report profiles leading participants across geographic headquarters, clinical focus, and product philosophy, translating these attributes into actionable competitive intelligence. Companies such as Össur, Ottobock, Orthomerica, Breg, Becker Orthopedic, Thuasne, Restorative Care of America, Fillauer, and Aspen Medical Products are assessed not merely as names on a ranking, but as strategic participants whose clinical positioning, material choices, and post-op or chronic-care emphasis define how value is created in the category.
- Össur emphasizes load dispersion and proprioceptive control for osteoarthritis, alongside post-hip arthroscopy support with controlled, gentle forces.
- Ottobock focuses on abduction orthotics designed for pain relief, malposition correction, and hip dysplasia treatment, with practical deployment features including breathable, zip-on construction.
- Orthomerica prioritizes total-contact comfort and dislocation prevention for postoperative and chronic use, with design families that emphasize patient stability and wearability.
- Breg centers its hip offerings on postoperative care, emphasizing patient-centric comfort, simplicity, and structured support.
- Becker Orthopedic contributes prefabricated abduction-oriented solutions that broaden accessible bracing options.
- Thuasne integrates prescription orthotic brace portfolios for post-operative and chronic pain contexts, extending its broader bracing ecosystem.
- Restorative Care of America, Inc. offers hip and torso orthoses aimed at support and immobilization needs.
- Fillauer advances orthotic innovation across lower-limb and hip applications, reinforcing technical breadth in the category.
- Aspen Medical Products leverages its spinal and stabilization expertise to support hip and torso stabilization within a connected bracing portfolio.
These profiles are synthesized into a competitive framework that clarifies where differentiation is being built, where commoditization risk exists, and where clinically anchored messaging can create defensible positioning.
Reimbursement and Regulatory Architecture
Hip orthosis adoption does not occur in a clinical vacuum; it is shaped heavily by coding, coverage, and policy. The report incorporates current reimbursement dynamics, including the role of HCPCS Level II codes spanning L1600 to L1690, which cover a range of abduction control designs from flexible Frejka-type configurations to static adjustable Ilfeld-type systems. For 2025, HCPCS code L1686 describes a prefabricated postoperative hip orthosis with abduction control, and PDAC approval has reinforced its relevance for post-op hip abduction applications.
The study also addresses the regulatory environment in which these codes operate. Hip orthoses are classified under existing HCPCS Level II structures with annual fee schedule updates, and recent determinations signal continuity rather than fragmentation. Discussions during 2024 and 2025 have included the potential development of off-the-shelf hip orthosis coding pathways alongside custom-fitted options such as bilateral thigh cuffs with adjustable abductor spreader bars. These developments matter because reimbursement predictability directly influences procurement confidence, patient access, and the economics of product design. The report translates these policy signals into strategic implications for pricing, documentation, clinician support, and market-access planning.
Market Dynamics and Operational Read-Throughs
Beyond sizing and competition, the research examines the operational forces shaping supply, demand, and go-to-market effectiveness. This includes how reimbursement clarity supports broader adoption of standardized post-operative bracing, how material and ergonomic improvements influence wear compliance, and how clinical preference is shifting toward solutions that balance support with patient comfort. The report connects these dynamics to practical recommendations for product development, sales force training, clinical education, and regional expansion planning. It also frames the market in terms of concentration and fragmentation, helping organizations decide whether to pursue scale advantages, specialized applications, or strategic alliances that bridge capability gaps.
Why 2026 Is a Strategic Inflection Point
The 2026 planning environment rewards those who can align product strategy with reimbursement reality and competitive timing. With base-year momentum already established and forecast growth extending through 2032, the next several quarters will determine which organizations capture share efficiently and which respond reactively. The market’s moderate concentration suggests that category leadership remains contestable, particularly in segments where clinical evidence, comfort, and ease of application reinforce adoption. At the same time, reimbursement alignment and code-based procurement pathways create both a gate and an opportunity: companies that design for coverage clarity and clinician usability will have a structural advantage in purchasing decisions.
Strategically, this means 2026 is not simply a year for incremental portfolio updates. It is a moment to evaluate whether current product lines map to the applications and patient profiles most likely to expand, whether go-to-market motion reflects actual reimbursement and procurement behavior, and whether competitive positioning is anchored in outcomes that providers and payers respect. The report supports these judgments by tying market size, segmentation, concentration, and regulatory context into a single decision framework.
Who Should Use This Research
This study is built for executives and specialists who need to convert uncertainty into structured action. That includes orthopedic device leadership, product and engineering teams evaluating segment fit, commercial leaders designing market-entry and expansion plans, reimbursement and market-access professionals tracking coding and coverage implications, and investors seeking a disciplined view of category dynamics. Each section is oriented toward practical use: assessing where to invest, where to defend, and where to differentiate without overcommitting to assumptions that the data does not support.
Access the Complete Market Intelligence
Macro indicators establish direction, but strategic execution requires segment clarity, competitive mapping, and policy-aware planning. This summary previews the analytical depth of our Worldwide Hip Orthosis Market research, while the full report provides the detailed segmentation logic, competitive benchmarking, reimbursement analysis, and forecasted scenarios needed to make confident 2026 decisions. For organizations ready to move from observation to action, the complete intelligence framework is available through our official research portal, where the full dataset, methodology, and strategic recommendations can be reviewed in complete form.
Worldwide Spinal Orthosis Market
For detailed analysis of this topic, please visit the official page: Worldwide Hip Orthosis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com