

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Sunlight Simulators Market to Reach $890.52M by 2032 at 7.0% CAGR

Global Sunlight Simulators Market: Strategic Intelligence for Enterprise Decision-Making in 2026
Introduction: Navigating Solar Simulation Amidst Technological Transition
The global demand for precise, reproducible, and spectrally accurate sunlight simulation has entered a phase of accelerated maturation. As photovoltaic manufacturing scales, next-generation tandem and perovskite architectures mature, and cross-industry applications in aerospace, biotechnology, and materials testing expand, organizations face increasingly complex procurement and R&D strategy choices. Our newly released Worldwide Sunlight Simulators Market study delivers a comprehensive, data-driven foundation for enterprise decision-makers operating in 2026 and beyond.
This executive overview distills the core strategic themes, competitive architectures, and operational imperatives that will shape capital allocation, technology roadmapping, and partnership strategies. By mapping historical trajectories against forward-looking forecast horizons, the report equips leadership teams with actionable intelligence while preserving the granular analytical depth required for precise market navigation.
Macro Market Trajectory and Structural Growth Dynamics
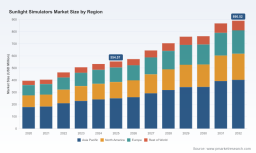
The sunlight simulators market has demonstrated consistent expansion over the historical evaluation window, building from approximately 395.4 million USD in 2020 to an estimated 554.57 million USD in 2025. This baseline reflects sustained investment in standardized testing infrastructure, regulatory compliance frameworks, and research-grade optical instrumentation. Looking ahead, the forecast period extending through 2032 projects a steady compound annual growth rate of 7.0 percent, culminating in a market valuation approaching 890.52 million USD.
Such growth is not homogenous. Demand acceleration is being shaped by the interplay of three structural forces: the proliferation of high-throughput module qualification lines, the transition from legacy continuous-spectrum illumination technologies toward spectrally tunable solid-state architectures, and the broadening of application mandates beyond traditional photovoltaic qualification. Organizations that rely on static market assumptions risk misaligning procurement cycles, R&D budgets, and capacity planning with the actual pace of segment-level demand migration.
Strategic planning in 2026 must therefore account for the divergence between headline growth and segment-specific velocity. Forecasting models embedded in this study isolate these dynamics, enabling readers to distinguish between incremental market expansion and structural technology substitution events that will redefine procurement requirements, vendor evaluation criteria, and facility investment timelines.
Research and Testing Applications: The Demand Anchor
Photovoltaic module testing continues to function as the primary demand engine for sunlight simulation infrastructure. Qualification workflows, manufacturing line verification, and performance certification depend on repeatable illumination conditions that meet stringent international standards. As cell architectures grow more complex—incorporating tandem stacks, heterojunction designs, and advanced anti-reflective or passivation coatings—testing protocols increasingly require adjustable spectral output, uniform irradiance across large areas, and precise thermal management during measurement cycles.
Beyond solar energy, secondary application verticals are contributing incremental but strategically significant growth. Aerospace and defense organizations utilize solar simulation for optical sensor calibration, environmental exposure verification, and materials durability assessment under controlled solar spectra. Materials and cosmetics testing laboratories leverage standardized illumination for photostability evaluation, weathering simulation, and formulation screening. Concurrently, biotechnology and agriculture applications are expanding the use case envelope for controlled-spectrum exposure in plant physiology research, photobiological assays, and controlled-environment agricultural prototyping.
Understanding how spending patterns distribute across these application domains is essential for equipment manufacturers, laboratory operators, and supply chain planners. The study delineates how application-specific requirements influence light source selection, classification thresholds, and automation integration, ensuring that procurement strategies are aligned with actual usage intensity rather than generalized market narratives.
Technology Architecture and Light Source Evolution
The technological composition of the sunlight simulators market reflects an ongoing architectural debate between established xenon lamp platforms and emerging LED-based simulation systems. LED-based simulators have gained prominence through their spectral tunability, extended operational lifetimes, reduced thermal footprints, and compatibility with automated testing environments. These attributes align with high-throughput manufacturing lines and research workflows that demand rapid reconfiguration between spectral profiles such as AM0, AM1.5G, and customized band-limited outputs.
Xenon lamp-based simulators retain relevance in scenarios requiring high-intensity flash or continuous-spectrum outputs that historically align with specific qualification standards and legacy test infrastructure. In parallel, metal halide and complementary light source configurations serve niche requirements where particular spectral characteristics, illumination geometries, or cost considerations dictate equipment selection. The market is not experiencing a simple substitution effect; rather, it is evolving into a multi-technology landscape in which end users select platforms based on application class, testing cadence, spectral fidelity requirements, and total cost of ownership over the equipment lifecycle.
A critical strategic consideration is how classification standards influence purchasing behavior. Equipment rated across Class A, A+, and A+++ parameters must satisfy defined criteria for spectral match, temporal stability, and spatial uniformity. Organizations evaluating capital expenditures need clarity on which classification tier matches their regulatory obligations, internal quality thresholds, and future technology roadmap. The report examines these technical differentiators through a commercial lens, connecting laboratory performance specifications with procurement economics and vendor evaluation frameworks.
Geographic Distribution and Regional Demand Drivers
Regional demand patterns reflect differences in manufacturing density, research infrastructure investment, regulatory environments, and energy policy momentum. Asia Pacific represents a substantial share of current market activity, supported by concentrated photovoltaic manufacturing ecosystems, expanding research institutions, and large-scale module qualification operations. North America and Europe maintain robust demand driven by advanced research programs, aerospace and defense testing requirements, pharmaceutical and cosmetics photostability workflows, and sustained investment in next-generation photovoltaic technologies.
The Rest of World segment, while smaller in absolute terms, reflects emerging testing infrastructure development and regional qualification center expansion. Enterprises operating across multiple jurisdictions must account for variations in standards adoption, service network availability, calibration support, and equipment localization requirements. Regional procurement strategies that ignore local service ecosystems or compliance nuances often encounter longer deployment cycles, higher validation costs, and greater operational risk.
Our geographic analysis avoids simplistic ranking narratives. Instead, it examines how regional manufacturing footprints, export qualification requirements, and localized testing mandates shape equipment specification decisions, vendor selection criteria, and after-sales service expectations. This framing enables multinational operators to design region-specific deployment strategies rather than applying uniform procurement templates across diverse markets.
Competitive Landscape: Differentiation, M&A, and Capability Consolidation
The competitive environment is defined by a concentrated but diversifying vendor base. The top five participants collectively account for approximately 48.7 percent of market revenue, while the top three hold roughly 31.4 percent, indicating a landscape where established leaders retain meaningful share but face rising pressure from specialized innovators and capability expansions through acquisition.
Several participants illustrate the strategic directions shaping the market. G2V Optics Inc. has built its positioning around advanced tunable LED solar simulators, including the Pico and Sunbrick series, with Class AAA and A+A+A+ configurations designed to replicate AM0 through AM1.5G spectra. Its emphasis on long LED lifetime and automation support appeals to research, photovoltaic, aerospace, and photochemistry applications requiring repeatable spectral control.
Eternal Sun has positioned itself as a leading provider of solar module testing equipment, offering steady-state LED solar simulators with A+A+A+ class performance alongside SPIRE Xenon-based flash solar simulators for IV testing of PV modules. Its support for tandem and perovskite technologies, combined with temperature control capabilities, reflects alignment with evolving cell architectures and qualification demands.
Avalon ST has focused on long-pulse, high-accuracy large-area LED solar simulators under its Nexun series, with A+ to A+++ classifications targeting photovoltaic and spatial industry applications, including perovskite, HJT, and AM0 testing. Its 2025 acquisition of PASAN SA represents a notable consolidation move, integrating LED-based solar simulation expertise with xenon-based simulators and precision measurement systems to broaden PV metrology offerings. This type of capability combination illustrates how vendors are seeking to serve customers across multiple light source architectures rather than competing within a single technology niche.
Newport Corporation provides the Sol series of arc lamp and LED solar simulators with compliance to ASTM, IEC, and JIS standards, including UV Sol-UV models for varied illumination areas and material testing applications. Solar Light Company, LLC delivers precision research-grade solar simulators aligned with ISO, FDA, JCIA, COLIPA, ASTM, and IEC standards, with strong recognition in SPF testing laboratories and light sciences applications. Abet Technologies, Inc. offers compliant simulators spanning 150W to 3kW, including the SunLite line for solar cell testing across DSSC, perovskite, silicon, and thin film technologies. Sciencetech Inc. complements this landscape with customized and standard simulators, including high-flux models for research applications in photovoltaics and related fields.
These profiles underscore a market in which competitive advantage is increasingly determined by application coverage, standards compliance breadth, spectral customization capability, and the ability to support automation and temperature-controlled testing workflows. Recent activity, such as the 2025 consolidation involving Avalon ST and the 2024 high-flux installation milestone achieved by Sciencetech Inc., signals an industry that is actively reshaping its capability base to match the requirements of advanced cell technologies and high-throughput testing environments.
Strategic Value of the Report for Enterprise Decision-Making
This study is designed to convert market complexity into operational clarity. It provides decision-makers with a structured framework for evaluating technology roadmaps, procurement timing, vendor qualification, and investment prioritization. The analysis is built to support multiple organizational functions, including R&D strategy, manufacturing operations, quality and compliance teams, procurement, and corporate development.
Key deliverables and practical contents include:
Worldwide Sunlight Simulators Market
- A full historical reconstruction from 2020 through 2025, paired with a forecast trajectory extending to 2032, enabling sensitivity analysis around adoption velocity, technology mix shifts, and demand elasticity.
- Segment-level evaluation across light source architectures, application categories, and regional demand structures, with interpretive guidance on how each dimension influences purchasing requirements and vendor selection.
- Competitive profiling of leading manufacturers, including headquarters location, product architecture, standards compliance, application focus, and recent strategic developments, supporting benchmarking and partnership assessment.
- Analysis of market concentration metrics and implications for supplier negotiation, switching costs, and technology roadmap dependency.
- Contextual interpretation of industry dynamics affecting procurement cycles, validation requirements, and service infrastructure expectations.
- Decision-oriented frameworks for aligning equipment classification, spectral customization needs, illumination area requirements, and automation readiness with actual operational use cases.
This multidimensional structure allows readers to move beyond top-line market sizing and into the operational logic that determines where value is created or lost. Procurement leaders can use the analysis to time capital expenditures against anticipated technology mix transitions. R&D managers can map spectral and classification requirements to upcoming cell or material programs. Corporate development teams can evaluate acquisition targets and partnership opportunities based on capability complementarity rather than revenue scale alone.
Forward Outlook for 2026 and Beyond
The next phase of market development will likely be shaped by the continued integration of LED-based tunability with high-accuracy large-area illumination, the expansion of flash and steady-state solutions for advanced tandem and perovskite module testing, and the growing importance of precision measurement ecosystems that accompany solar simulation hardware. As qualification standards evolve and product architectures become more spectrally and thermally demanding, equipment selection will increasingly hinge on lifecycle performance, automation compatibility, and vendor-supported calibration and service networks.
Enterprises that establish clear internal definitions of required spectral match, temporal stability, spatial uniformity, and application coverage will be better positioned to navigate vendor offerings without over-specifying or under-equipping their testing infrastructure. At the same time, organizations operating across multiple verticals should expect to manage a more diversified equipment portfolio, balancing high-throughput manufacturing requirements against research-grade flexibility and specialized compliance demands.
This report provides the analytical scaffolding needed to make those decisions with confidence. It combines historical market reconstruction, forward-looking demand modeling, technology architecture assessment, and competitive capability mapping into a single strategic reference point for 2026 planning cycles.
Conclusion
The worldwide sunlight simulators market is entering a period in which growth, technology differentiation, and application expansion will jointly determine competitive outcomes. Enterprise leaders who rely on aggregate market narratives alone risk misjudging where demand is actually intensifying, which technological pathways will dominate specific use cases, and how vendor capabilities are consolidating to serve advanced testing requirements.
Our full market study delivers the granular segmentation, competitive benchmarking, regional interpretation, and forward forecast detail necessary to translate strategic intent into executable plans. To access the complete dataset, segmentation analysis, competitive profiles, and scenario-based forecast frameworks that support precise procurement, R&D, and investment decisions, refer to the full report through our official research portal.
Aviation Simulators Market
For detailed analysis of this topic, please visit the official page: Worldwide Sunlight Simulators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com