

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Hip Orthosis Market to Hit $776M by 2032, Growing at 5.25% CAGR

Strategic Intelligence for the Hip Orthosis Market: A 2026 Outlook
The global orthopedic device landscape is undergoing a subtle transformation, and the hip orthosis segment stands at the convergence of demographic inevitability and technological refinement. As we release our latest Worldwide Hip Orthosis Market research, this analysis serves as a critical strategic compass for executives navigating 2026 planning cycles. The market has demonstrated resilient, compound growth from 2020 through 2025, with base-year revenue reaching 542.4 million USD. Forward projections indicate sustained momentum, positioning the sector to approach 576.66 million USD in 2026 and continuing toward 776.03 million USD by 2032. This trajectory reflects a 5.25 percent compound annual growth rate, a figure that carries far more significance than a headline metric. It signals durable demand drivers, evolving reimbursement pathways, and a competitive environment where product differentiation and supply-chain precision will increasingly determine share capture.
For corporate strategists, clinicians, and investors, the question in 2026 is no longer whether the hip orthosis market will grow, but where the highest-margin opportunities lie, how regulatory and reimbursement frameworks will shape procurement behavior, and which product architectures will align with shifting patient and provider expectations. This report is designed to convert macro momentum into executable insight, equipping decision-makers with the granularity required to prioritize investments, reposition portfolios, and anticipate competitive moves before they reshape the category.
Worldwide Hip Orthosis Market
The Trajectory: Translating Market Momentum Into Decision Confidence
Understanding the arc of this market requires more than observing top-line figures. The historical window from 2020 to 2025 reveals a pattern of consistent expansion, underpinned by rising surgical volumes, an aging population managing degenerative joint conditions, and growing clinical confidence in orthotic support for both post-operative protocols and chronic care management. As the forecast period unfolds from 2026 through 2032, the growth path remains stable yet nuanced. Revenue is expected to scale through 2027, place at 614.72 million USD, before reflecting anticipated demand adjustments; by 2028, the market reaches 617.55 million USD, and then resumes a steadier ascent through the remainder of the decade.
This trajectory matters because it exposes the strategic inflection points where companies must act. A moderate but reliable CAGR suggests that pure volume plays will not be sufficient to outperform. Instead, market leaders will differentiate through product efficacy, material innovation, clinician-friendly deployment, and reimbursement alignment. The report contextualizes each forecasted phase, helping leadership teams map resource allocation, capacity planning, and market-entry timing to the periods where demand signals are strongest, rather than relying on backward-looking averages.
Equally important is market concentration. With the top three participants accounting for a combined 38.5 percent share and the top five reaching 52.4 percent, the category reflects a moderately concentrated structure that still leaves meaningful room for specialized entrants and regional differentiation. This balance between established incumbency and accessible niches informs partnership strategy, distribution design, and messaging focus. Companies entering or expanding within the space must decide whether to compete through broad clinical positioning or to concentrate on application-specific solutions where clinical evidence and payer acceptance converge.
What This Report Delivers: Actionable Intelligence Beyond the Headlines
A market research study becomes strategically valuable only when it converts data into decisions. Our Worldwide Hip Orthosis Market research is structured to provide precisely that operational utility. Rather than presenting a static aggregation of figures, the study delivers an integrated analytical framework that connects market sizing, segmentation logic, competitive behavior, reimbursement architecture, and industrial dynamics into a coherent planning toolkit.
Portfolio and Segment Positioning
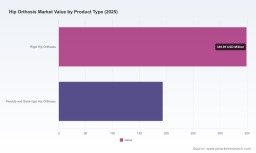
The report examines how product architectures and clinical applications shape revenue distribution, enabling leaders to evaluate where their offerings align with market priorities and where gaps may be exploited. By analyzing the interplay between rigid constructs and flexible or semi-rigid alternatives, as well as the relative weight of post-operative recovery, osteoarthritis and chronic condition management, hip dysplasia and congenital disorders, and trauma and fracture management, the study helps teams identify which use cases are expanding most effectively and which present the clearest value proposition for specific customer segments. This approach supports more disciplined SKU strategy, engineering prioritization, and clinical communication.
Competitive Landscape and Strategic Benchmarking
Market share data alone does not explain why certain firms hold influence. The report profiles leading participants across geographic headquarters, clinical focus, and product philosophy, translating these attributes into actionable competitive intelligence. Companies such as Össur, Ottobock, Orthomerica, Breg, Becker Orthopedic, Thuasne, Restorative Care of America, Fillauer, and Aspen Medical Products are assessed not merely as names on a ranking, but as strategic participants whose clinical positioning, material choices, and post-op or chronic-care emphasis define how value is created in the category.
- Össur emphasizes load dispersion and proprioceptive control for osteoarthritis, alongside post-hip arthroscopy support with controlled, gentle forces.
- Ottobock focuses on abduction orthotics designed for pain relief, malposition correction, and hip dysplasia treatment, with practical deployment features including breathable, zip-on construction.
- Orthomerica prioritizes total-contact comfort and dislocation prevention for postoperative and chronic use, with design families that emphasize patient stability and wearability.
- Breg centers its hip offerings on postoperative care, emphasizing patient-centric comfort, simplicity, and structured support.
- Becker Orthopedic contributes prefabricated abduction-oriented solutions that broaden accessible bracing options.
- Thuasne integrates prescription orthotic brace portfolios for post-operative and chronic pain contexts, extending its broader bracing ecosystem.
- Restorative Care of America, Inc. offers hip and torso orthoses aimed at support and immobilization needs.
- Fillauer advances orthotic innovation across lower-limb and hip applications, reinforcing technical breadth in the category.
- Aspen Medical Products leverages its spinal and stabilization expertise to support hip and torso stabilization within a connected bracing portfolio.
These profiles are synthesized into a competitive framework that clarifies where differentiation is being built, where commoditization risk exists, and where clinically anchored messaging can create defensible positioning.
Reimbursement and Regulatory Architecture
Hip orthosis adoption does not occur in a clinical vacuum; it is shaped heavily by coding, coverage, and policy. The report incorporates current reimbursement dynamics, including the role of HCPCS Level II codes spanning L1600 to L1690, which cover a range of abduction control designs from flexible Frejka-type configurations to static adjustable Ilfeld-type systems. For 2025, HCPCS code L1686 describes a prefabricated postoperative hip orthosis with abduction control, and PDAC approval has reinforced its relevance for post-op hip abduction applications.
The study also addresses the regulatory environment in which these codes operate. Hip orthoses are classified under existing HCPCS Level II structures with annual fee schedule updates, and recent determinations signal continuity rather than fragmentation. Discussions during 2024 and 2025 have included the potential development of off-the-shelf hip orthosis coding pathways alongside custom-fitted options such as bilateral thigh cuffs with adjustable abductor spreader bars. These developments matter because reimbursement predictability directly influences procurement confidence, patient access, and the economics of product design. The report translates these policy signals into strategic implications for pricing, documentation, clinician support, and market-access planning.
Market Dynamics and Operational Read-Throughs
Beyond sizing and competition, the research examines the operational forces shaping supply, demand, and go-to-market effectiveness. This includes how reimbursement clarity supports broader adoption of standardized post-operative bracing, how material and ergonomic improvements influence wear compliance, and how clinical preference is shifting toward solutions that balance support with patient comfort. The report connects these dynamics to practical recommendations for product development, sales force training, clinical education, and regional expansion planning. It also frames the market in terms of concentration and fragmentation, helping organizations decide whether to pursue scale advantages, specialized applications, or strategic alliances that bridge capability gaps.
Why 2026 Is a Strategic Inflection Point
The 2026 planning environment rewards those who can align product strategy with reimbursement reality and competitive timing. With base-year momentum already established and forecast growth extending through 2032, the next several quarters will determine which organizations capture share efficiently and which respond reactively. The market’s moderate concentration suggests that category leadership remains contestable, particularly in segments where clinical evidence, comfort, and ease of application reinforce adoption. At the same time, reimbursement alignment and code-based procurement pathways create both a gate and an opportunity: companies that design for coverage clarity and clinician usability will have a structural advantage in purchasing decisions.
Strategically, this means 2026 is not simply a year for incremental portfolio updates. It is a moment to evaluate whether current product lines map to the applications and patient profiles most likely to expand, whether go-to-market motion reflects actual reimbursement and procurement behavior, and whether competitive positioning is anchored in outcomes that providers and payers respect. The report supports these judgments by tying market size, segmentation, concentration, and regulatory context into a single decision framework.
Who Should Use This Research
This study is built for executives and specialists who need to convert uncertainty into structured action. That includes orthopedic device leadership, product and engineering teams evaluating segment fit, commercial leaders designing market-entry and expansion plans, reimbursement and market-access professionals tracking coding and coverage implications, and investors seeking a disciplined view of category dynamics. Each section is oriented toward practical use: assessing where to invest, where to defend, and where to differentiate without overcommitting to assumptions that the data does not support.
Access the Complete Market Intelligence
Macro indicators establish direction, but strategic execution requires segment clarity, competitive mapping, and policy-aware planning. This summary previews the analytical depth of our Worldwide Hip Orthosis Market research, while the full report provides the detailed segmentation logic, competitive benchmarking, reimbursement analysis, and forecasted scenarios needed to make confident 2026 decisions. For organizations ready to move from observation to action, the complete intelligence framework is available through our official research portal, where the full dataset, methodology, and strategic recommendations can be reviewed in complete form.
Worldwide Spinal Orthosis Market
For detailed analysis of this topic, please visit the official page: Worldwide Hip Orthosis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com