

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Sonobuoy Launcher Market to Hit $530.14M by 2032, Growing at 5.46% CAGR

Strategic Intelligence in the Deep Blue: Navigating the Global Sonobuoy Launcher Market in 2026
The undersea warfare landscape is undergoing a profound transformation. As naval powers prioritize anti-submarine warfare (ASW) capabilities to counter evolving underwater threats, the mechanisms by which airborne assets deploy surveillance equipment have become critical nodes in the defense supply chain. The Worldwide Sonobuoy Launcher Market represents more than just a component segment; it is the enabling interface between maritime patrol platforms and the acoustic sensors essential for detecting modern submarines. For defense executives, procurement officers, and strategic investors, understanding the trajectory of this market is no longer optional—it is imperative for capitalizing on emerging opportunities and mitigating supply chain risks in Fiscal Year 2026 and beyond.
In this complex environment, generic market observations are insufficient. Decision-makers require granular intelligence that connects macroeconomic trends, technological shifts, and competitive maneuvering. PW Consulting is proud to introduce our latest comprehensive study, designed to equip stakeholders with the actionable intelligence needed to navigate this specialized sector. This introduction outlines the strategic value of the research, highlighting the market's current momentum, the competitive dynamics shaping the industry, and the specific operational content included in our full report.
Worldwide Sonobuoy Launcher Market
Market Trajectory and Economic Context
The sonobuoy launcher sector has demonstrated resilient growth over the past five years, driven by sustained defense spending and the modernization of ASW fleets. According to our analysis, the global market revenue has shown a consistent upward trajectory, with historical performance reflecting the steady demand for airborne ASW capabilities. The market valuation stood at approximately $346.93 million in 2024, progressing to an estimated $365.4 million in 2025. This growth is not merely linear; it reflects the increasing complexity of naval missions and the necessity for reliable deployment systems for A-size, F-size, and G-size sonobuoys.
The forecast period from 2026 to 2032 indicates a robust expansion path. Our models project the market will reach approximately $408.79 million in 2026, signaling a significant step up in procurement and modernization cycles. Looking further ahead, the compound annual growth rate (CAGR) is calculated at 5.46 percent. This rate underscores a mature yet steadily growing industry, fueled by the replacement of legacy systems and the integration of new platforms.
- Revenue Momentum: The transition from 2025 to 2026 reflects a critical inflection point where multiple naval programs converge.
- Long-Term Outlook: Projections extend through 2032, offering visibility into long-term R&D and production planning.
- Currency and Scale: All financial data is presented in USD Million, ensuring consistency for international benchmarking.
This macroeconomic backdrop provides the necessary context for understanding vendor performance and contract opportunities. However, the aggregate numbers only tell part of the story. The distribution of revenue across different launcher technologies, platforms, and geographic regions reveals where the true value lies and which segments are primed for disruption. Our full report dissects these segments without exposing the detailed figures here, inviting readers to access the complete dataset for precise benchmarking.
Technology Segmentation and Platform Integration
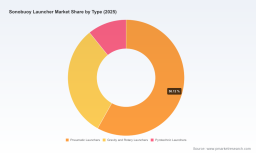
The market is characterized by a diverse array of launcher technologies, each suited to specific operational requirements and platform constraints. Pneumatic systems remain a dominant force, valued for their reliability and reloadability during flight operations. Gravity and rotary mechanisms offer alternative deployment profiles, while pyrotechnic solutions cater to specialized rapid-release scenarios. The choice of launcher type is inextricably linked to the host platform, whether it be a high-altitude maritime patrol aircraft, a low-and-slow ASW helicopter, or emerging unmanned aerial systems.
Platform integration is a key driver of demand. Maritime patrol aircraft continue to represent the largest share of deployment activity, given their endurance and sensor capacity. ASW helicopters provide essential low-altitude coverage, while unmanned aerial vehicles are increasingly being explored for expendable sensor delivery. Surface vessels also contribute to the ecosystem, albeit to a lesser extent in the airborne launcher context. The interplay between platform availability and launcher compatibility creates a complex matrix of requirements. Our report analyzes these dynamics in depth, evaluating how shifts in platform procurement—such as the continued acquisition of P-8A Poseidon aircraft or MH-60 helicopters—ripple through the launcher supply chain.
Competitive Landscape: Key Players and Strategic Positionings
The competitive environment is moderately concentrated, with a few major players commanding significant market share. This structure offers stability but also presents barriers to entry for smaller firms. The leading companies are not merely manufacturers; they are system integrators deeply embedded in naval aviation programs. Understanding their specific capabilities, recent contract wins, and technological roadmaps is essential for assessing supplier risk and partnership potential.
L3Harris Technologies stands out as a key contributor, designing and manufacturing pneumatic-powered sonobuoy launching systems. Their portfolio includes the Sonobuoy Rotary Launch System (SRL), capable of holding ten A-size sonobuoys with a launch capability every three seconds, and the Sonobuoy Single Launch System (SSL) for single A-, F-, or G-size units. These systems are reloadable in flight and suited for maritime patrol aircraft such as the P-8A. L3Harris maintains full-rate production and has a proven flight heritage. Recent developments, including a prominent contract award in December 2025 related to advanced systems and a sole-source contract in January 2024 for the P-8A Poseidon Sonobuoy Rotary Launcher Lower Tray Retrofit, highlight their entrenched position in critical U.S. Navy programs.
Ultra Maritime, based in the UK, provides sonobuoy systems and associated launcher technologies. They are actively developing next-generation multistatic sonobuoys compatible with existing naval launcher infrastructure, including P-8A platforms. In April 2026, Ultra Maritime was awarded a sole source firm-fixed-price contract for Low Rate Initial Production of AN/SSQ-125B sonobuoys, supporting integration with existing naval launcher systems. This contract underscores the ongoing relevance of launcher compatibility even as sonobuoy technology evolves.
Lockheed Martin remains involved in sonobuoy programs and upgrades to related launcher systems, such as the MK36 Super Hercules, to enhance performance and range in ASW applications. Thales Group develops multi-platform sonobuoy launchers adaptable to frigates, corvettes, and helicopters, alongside advanced sonobuoys like SonoFlash with extended detection range and multistatic capabilities. Sparton Corporation, now part of Elbit Systems, manufactures sonobuoys with extensive deployment history and supports associated launching systems for air-to-sea deployment.
Missile Decoy Launcher System Market
The market also includes specialized and niche players who offer tailored solutions. Alkan S.A. in France specializes in sonobuoy launcher solutions for naval and aircraft platforms. JSK Naval Support Inc. in Canada provides niche launcher solutions tailored to specific mission requirements and platform integration. Geospectrum Technologies Inc. focuses on launcher systems with an emphasis on acoustic technology and underwater surveillance. Marshall Aerospace and Defence Group delivers launch carousel assemblies and related components, while MES S.p.A. produces light stores dispensing units and composite launch tubes for sonobuoy and similar expendable stores.
Our report provides a detailed competitive benchmarking analysis, evaluating each firm's market share relative to the competitive landscape. The market concentration is significant, with the top three players holding a substantial portion of the revenue and the top five commanding a dominant share. This structure influences pricing power, supply chain resilience, and the pace of innovation. Stakeholders must understand these dynamics to negotiate effectively or identify potential gaps in the market for new entrants.
Industry Dynamics and Emerging Trends
Several macro trends and regulatory developments are reshaping the sonobuoy launcher market. The U.S. Navy's FY2026 budget continues to support sonobuoy programs across P-8, P-3, and H-60 platforms. There is a strong emphasis on maintaining a healthy industrial base through multiple qualified vendors for sonobuoy and associated launcher components. This policy environment favors established players while creating opportunities for secondary suppliers to qualify for niches.
Technological evolution is also a major driver. The integration of sonobuoy launchers with unmanned platforms is gaining traction. The U.S. Navy's SBIR Topic N251-016, released in December 2024, highlights the development of expendable sonobuoy-launched UAVs for ASW cued search from P-8A launcher infrastructure. This convergence of unmanned systems and traditional launcher architecture represents a frontier for innovation and potential market expansion. Additionally, raw material considerations remain relevant. Sonobuoy launch containers and related structures historically utilize aluminum cylinders and composite materials for launch tubes to achieve lightweight, durable performance under air-deployed conditions. Fluctuations in material costs or supply constraints can impact production timelines and pricing.
Geopolitical factors further influence demand. A rising focus on anti-submarine warfare capabilities drives demand for sonobuoy launchers in naval modernization programs, particularly in North America and allied nations operating P-8A and MH-60 platforms. Regional security concerns and the need to counter advanced submarine threats in key maritime corridors are prompting governments to invest in robust ASW architectures. These geopolitical currents ensure that demand for reliable launcher systems remains a priority for defense budgets globally.
Inside the Report: Operational Content and Analytical Tools
The Worldwide Sonobuoy Launcher Market report is structured to provide maximum utility for strategic planning. It goes beyond descriptive statistics to offer analytical frameworks that support decision-making. The report includes a comprehensive overview of the market ecosystem, covering definitions, scope, and key product classifications. It details the segmentation by region, type, and platform, allowing readers to isolate specific areas of interest.
A major component of the study is the competitive landscape analysis. Each key company is profiled with information on headquarters, product offerings, recent contract awards, and strategic initiatives. These profiles are supported by data on market share and concentration, providing context for competitive intensity. The report also examines the value chain, from raw material suppliers of aluminum and composites to the integrators and end-users within naval organizations.
Furthermore, the analysis incorporates a review of industry dynamics, including regulatory frameworks, technological trends, and macroeconomic factors. The historical data from 2020 to 2025 is presented to establish baselines, and the forecast data through 2032 offers a forward-looking perspective. Methodologies are clearly outlined to ensure transparency and reliability. Stakeholders can use this information to validate internal forecasts, identify supplier risks, and explore potential partnership opportunities.
Our research emphasizes actionable insights. For procurement professionals, the report highlights vendor capabilities and contract trends that can inform sourcing strategies. For investors, the growth projections and segment analysis help assess the viability of market entry or expansion. For defense planners, the technological and platform integration details support requirements definition and capability planning. The report is designed to be a reference tool that can be consulted repeatedly as the market evolves.
Strategic Recommendations for 2026 Decision-Makers
Based on the prevailing market signals, organizations should consider several strategic priorities. First, maintaining visibility into the status of key platform programs is essential. The P-8A Poseidon and H-60 helicopter fleets are central to launcher demand, and any changes in procurement rates or retrofit requirements will directly impact the market. Second, monitoring the progress of unmanned integration is critical. The potential for sonobuoy-launched UAVs could alter the requirements for launcher infrastructure and create new niches for specialized components. Third, supply chain resilience should be a focus. Given the concentration of the market and the emphasis on qualified vendors, ensuring access to reliable suppliers and understanding the material dependencies of launcher systems is vital for operational continuity.
Finally, stakeholders should engage with the full intelligence available in our research. While this introduction highlights the key themes, the detailed segmentation data, market size breakdowns, and competitive share analysis are available in the complete report. Access to this granular level of detail is necessary for precise valuation, risk assessment, and strategic positioning.
Conclusion: Accessing Comprehensive Market Intelligence
The Worldwide Sonobuoy Launcher Market is at a juncture where sustained growth meets technological evolution and shifting strategic priorities. The revenue trajectory, competitive concentration, and emerging trends all point to a market that is vital for modern naval capabilities. However, navigating this market requires more than a high-level overview. It demands deep, data-driven insights that reveal the nuances of segmentation, the specifics of vendor performance, and the probabilities of future growth.
PW Consulting's new market research report provides the depth and rigor required for informed decision-making in 2026. By combining historical analysis with forward-looking forecasts and detailed competitive profiling, the study offers a complete view of the landscape. We invite defense executives, strategic planners, and industry leaders to explore the full findings to unlock the intelligence needed to drive success. The complete dataset, including regional and segment-specific figures, is available for download. Access the source webpage today to obtain the full report and ensure your organization is equipped with the insights necessary to thrive in this dynamic market.
For detailed analysis of this topic, please visit the official page: Worldwide Sonobuoy Launcher Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com