

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Dry Electrostatic Precipitator Market Hits $3.8B in 2025, Growing 4.12% CAGR Through 2032

Global Dry Electrostatic Precipitator Market Outlook 2026: Strategic Imperatives for Industrial Emission Control
The global industrial landscape is undergoing a seismic shift in how particulate matter is managed, driven by tightening environmental regulations and the urgent need for operational efficiency. As we move into 2026, the Dry Electrostatic Precipitator (ESP) market stands at a critical inflection point. For executives in power generation, steel, cement, and chemical sectors, understanding the trajectory of this market is no longer optional—it is a strategic necessity. This analysis draws upon the latest comprehensive market research to outline the forces shaping the industry and the opportunities available for stakeholders who act decisively.
Market Trajectory and Growth Dynamics
The historical performance of the dry ESP sector reveals a steady, resilient expansion pattern. From 2020 to 2025, the market demonstrated consistent revenue growth, reflecting the ongoing industrialization of emerging economies and the retrofitting needs of established infrastructure in developed nations. As of the base year 2025, the overall market valuation has solidified, setting a robust foundation for the forecast period extending through 2032.
Looking ahead, the forecast period from 2026 to 2032 indicates a continued upward trend in revenue. The projected Compound Annual Growth Rate (CAGR) during this timeframe underscores a moderate but stable growth environment. This growth is not merely a function of volume but is deeply tied to technological upgrades and compliance-driven investments. Organizations that align their capital expenditure plans with this growth trajectory will be better positioned to capture market share and optimize their environmental compliance portfolios.
Key macro drivers are fueling this demand. The global push for carbon neutrality has intensified the focus on capturing submicron particles, necessitating upgrades to existing filtration systems. Furthermore, regulatory bodies across major economies are enforcing stricter emission standards. For instance, mandates requiring high particulate removal efficiency for coal-fired plants are accelerating the replacement cycle of older equipment. Similarly, directives in Europe regarding industrial emissions are compelling manufacturers to adopt advanced dry ESP technologies to meet stringent limits. These regulatory pressures convert compliance from a cost center into a strategic investment area, driving the overall market valuation toward higher peaks in the late 2020s.
Segmentation Insights: Configuration and End-User Dynamics
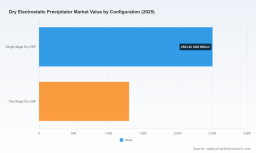
Understanding the structural composition of the market is vital for targeted strategy development. The market is primarily bifurcated by configuration, with distinct advantages offered by different technological setups. The single-stage dry ESP configuration currently holds a significant share of the revenue landscape. This dominance is attributed to its widespread application in large-scale industrial processes where established infrastructure supports this technology. However, the two-stage dry ESP segment represents a crucial area of growth, particularly for applications requiring higher efficiency and lower pressure drops.
On the demand side, the power generation sector remains the cornerstone of market consumption. As the largest end-user category, it drives substantial revenue through both new installations and retrofits aimed at meeting modern emission standards. Following closely, the steel and metallurgy industry constitutes a major demand pillar. The harsh operating environments in steel mills require robust ESP solutions capable of withstanding high temperatures and corrosive conditions, making durability a key selection criterion.
Additional significant end-user segments include cement manufacturing and chemicals and petrochemicals. In the cement sector, the demand is influenced by the need for high-temperature models resistant to alkali corrosion, aligning with the processing requirements of kilns. Meanwhile, the chemicals and petrochemicals industry utilizes compact dry ESP systems for specific processes, often integrating advanced control systems for precision operation. Mining and other allied industries also contribute to the demand mix, though to a lesser extent compared to the heavy industrial giants. Each segment presents unique operational challenges, requiring tailored ESP solutions rather than a one-size-fits-all approach.
Regional Performance Patterns
Geographically, the market exhibits a diversified landscape of demand. The Asia Pacific region emerges as the leading revenue contributor, reflecting the intense industrial activity and rapid infrastructure development within this zone. The concentration of manufacturing hubs and power plants in this region necessitates substantial investment in emission control technologies.
Europe follows as a significant market, driven by mature industrial bases and stringent environmental directives that mandate continuous upgrades to pollution control systems. North America also represents a substantial market share, with demand fueled by regulatory compliance in power generation and industrial processing sectors.
Beyond these major hubs, the Middle East and Africa, as well as Latin America, present developing market opportunities. While their current revenue contributions are smaller compared to the leading regions, they offer growth potential as industrialization accelerates and environmental frameworks mature. For global players, navigating these regional nuances requires a localized strategy that accounts for specific regulatory environments, availability of raw materials, and local competitive dynamics.
Competitive Landscape and Industry Moves
The market is characterized by a moderately concentrated competitive environment. A handful of key players command a significant portion of the market revenue, yet there remains ample room for specialized entrants and innovation-driven competition. Leading companies such as Babcock & Wilcox, GE Power, Hitachi Zosen, Mitsubishi Heavy Industries, Sumitomo Heavy Industries, FLSmidth, and Dürr AG are pivotal in shaping the industry standards.
These corporations are not merely competing on price; they are differentiating through technological capabilities. Babcock & Wilcox, for example, has focused on delivering modular designs for high-efficiency particulate removal, recently completing a delivery for a U.S. cement plant aimed at PM2.5 compliance. Similarly, FLSmidth has showcased next-generation technologies featuring AI-optimized electrode cleaning, highlighting the industry's shift toward smart manufacturing and operational intelligence. Hitachi Zosen has secured notable contracts for steel mill expansions, emphasizing durability through rigid discharge electrodes designed for harsh environments.
Mitsubishi Heavy Industries continues to supply advanced technologies with high-voltage transformers optimized for fine particle capture, while Sumitomo Heavy Industries focuses on energy-efficient rapping systems for non-ferrous metal smelters. Dürr AG provides compact solutions for automotive and chemical industries, integrating control systems for seamless operation. GE Power emphasizes low-pressure drop systems for coal-fired and waste-to-energy plants. This diversification in product offerings means that procurement decisions are increasingly complex, requiring buyers to evaluate specific technical fit rather than relying on brand reputation alone.
Recent industry activity underscores the dynamism of this sector. Throughout 2025 and into 2026, key players have engaged in strategic deliveries, trade show showcases, and contract awards that signal their commitment to specific verticals. These moves suggest that competition will intensify in areas where regulatory deadlines are closest, particularly in power generation and cement manufacturing. Companies that can demonstrate proven compliance records and reliability in harsh conditions will likely gain preference in bidding processes.
Worldwide Dry Electrostatic Precipitator Market
Electrostatic Precipitators (ESP) Market
Operational Challenges and Cost Factors
While the growth outlook is positive, stakeholders must navigate several headwinds affecting cost structures and supply chain stability. One significant factor is the volatility in raw material prices. High-voltage steel transformer cores, essential components for dry ESPs, have experienced price increases due to alloy shortages. This cost pressure flows downstream, affecting the overall capital expenditure required for new installations or major upgrades.
Component costs also remain a critical consideration. Specialized stainless steel used for rigid discharge electrode plates has seen average industrial quotes reach significant levels per meter. These costs impact the total cost of ownership and must be factored into long-term budgeting. Organizations need to weigh the upfront investment against the long-term benefits of efficiency and compliance.
Furthermore, the regulatory landscape continues to evolve. Standards mandating extremely high particulate removal efficiency for coal plants are driving retrofits, which can strain existing operational budgets. The requirement to capture submicron particles under various international directives means that older units may become obsolete faster than anticipated, forcing unplanned capital expenditures. Supply chain resilience is therefore crucial; relying on single-source suppliers for critical components like transformer cores or specialized electrodes could expose operations to delays and cost spikes.
Strategic Recommendations for Stakeholders
For industry leaders planning their 2026 strategy, several actions are recommended based on the current market intelligence.
- Prioritize Compliance Upgrades: With regulatory deadlines approaching, allocating capital for ESP retrofits should be a top priority. Delaying these investments risks non-compliance penalties and operational shutdowns.
- Evaluate Total Cost of Ownership: Beyond the initial purchase price, consider energy efficiency, maintenance requirements, and component longevity. Technologies that offer lower pressure drops and energy-efficient rapping systems can reduce operational expenditures over the equipment's lifecycle.
- Monitor Supply Chain Vulnerabilities: Given the volatility in steel and alloy prices, diversifying suppliers or securing long-term contracts for critical components can mitigate cost risks.
- Invest in Intelligent Systems: The emergence of AI-optimized cleaning and integrated control systems suggests a future where predictive maintenance and automated adjustments drive efficiency. Early adoption of these technologies may provide a competitive edge in operational reliability.
- Segment-Specific Solutions: Avoid generic procurement. Engage with vendors who understand the specific demands of your industry, whether it is alkali corrosion resistance for cement or durability for steel mills.
Conclusion
The Dry Electrostatic Precipitator market is poised for steady evolution through the end of the decade. Driven by regulatory mandates, industrial expansion, and technological innovation, the sector offers substantial opportunities for those who navigate it with informed precision. The convergence of macro drivers like carbon neutrality goals and micro-level factors such as component costs creates a complex decision-making environment. Success in this landscape requires more than just monitoring market size; it demands a deep understanding of segmentation dynamics, competitive moves, and operational constraints.
Access to granular data regarding regional splits, specific end-user valuations, and detailed configuration breakdowns is essential for crafting a winning strategy. While the high-level trends provide direction, the specific metrics needed to justify capital allocation and vendor selection lie within the detailed analysis. Stakeholders are encouraged to engage with the full market research report to unlock the comprehensive intelligence required to make decisive, data-backed decisions in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Dry Electrostatic Precipitator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com