

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Blood Thinning Drugs Market to Reach $90.63 Billion by 2032 with 8.5% CAGR

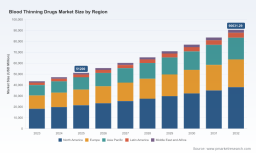
Strategic Horizons in the Global Blood Thinning Drugs Market Through 2032
The worldwide market for blood thinning drugs is entering a defining inflection point. As healthcare systems grapple with aging populations, rising prevalence of atrial fibrillation, and evolving regulatory landscapes, the therapeutic category continues to attract sustained investment and strategic attention. This analysis draws directly from our newly released Worldwide Blood Thinning Drugs Market research, offering executive decision-makers a structured view of where value will be created, where volatility will emerge, and how to position portfolios against the forecast horizon spanning 2026 to 2032.
The baseline has sharpened considerably. Historical tracking from 2020 through 2025 demonstrates consistent expansion, with the overall market reaching an estimated value in the 2025 base year before advancing toward a projected trajectory that places the category at a materially larger revenue footprint by the close of the decade. The compound annual growth rate across the full forecast window is tracked at 8.5 percent, a pace that underscores durable demand drivers rather than a temporary post-pandemic rebound. What matters now for leadership teams is not simply the headline trajectory but the structural forces shaping it, the competitive transitions underway, and the hidden inflection points that will separate opportunistic positioning from durable advantage.
Macro Trajectory and Revenue Architecture
The revenue architecture of the blood thinning segment reflects a broad but increasingly differentiated landscape. Baseline valuations for 2023 and 2024 already signaled robust momentum, and the upward continuation into 2025 established a strong platform for the forecast years. Rather than relying on a single therapeutic pillar, the category derives strength from a multi-drug-class composition that balances mature anticoagulants with newer direct oral agents, alongside injectable heparin-based formulations and vitamin K antagonists that retain relevance in specific clinical pathways.
The forecast curve shows sustained year-over-year growth as the market advances through 2026, 2027, and beyond, culminating in a substantially larger revenue base by 2032. This expansion is not uniform. It is shaped by therapeutic adoption patterns, regional purchasing dynamics, payer access environments, and the ongoing shift in clinical practice toward agents with improved safety profiles and simplified monitoring requirements. For strategy teams, the implication is clear: aggregate growth narratives can obscure divergence within segments, and effective planning requires a view that separates headline momentum from the underlying demand engines.
The report provides a detailed walk-through of that divergence. It maps how distinct drug classes, clinical indications, and regional markets interact with pricing pressure, formulary positioning, and supply continuity, offering a foundation for scenario planning rather than a static snapshot. Leaders who connect these structural layers to their internal pipeline, manufacturing footprint, and commercial access strategy will be best positioned to translate macro growth into realized share.
Segmentation and Demand Drivers
Understanding where demand is concentrated requires looking past the total revenue figure into the shape of the market itself. The therapeutic landscape is anchored by direct oral anticoagulants, which command the largest revenue share and continue to benefit from clinical preferences grounded in favorable safety profiles and the elimination of routine monitoring. Heparin and low molecular weight heparin categories remain foundational, particularly in hospital and inpatient settings, and their production depends on chain reliability for porcine mucosal raw materials. Vitamin K antagonists and other anticoagulant options continue to serve important, if narrower, roles in specific patient populations and treatment protocols.
On the indication side, atrial fibrillation represents the dominant clinical driver, supported by widespread screening, aging demographics, and expanded therapeutic eligibility. Deep vein thrombosis and pulmonary embolism form the next tier of demand, with treatment and prevention pathways intersecting both outpatient and inpatient care settings. Additional indications round out the demand base, contributing incremental but strategically relevant volume.
Regionally, the market reflects a concentration pattern that rewards both established commercial infrastructure and disciplined entry strategies. North America and Europe remain central revenue anchors, while the Asia Pacific region represents a substantial and expanding share of global demand. Latin America and the Middle East and Africa collectively contribute meaningful volume, and each geography carries its own reimbursement conditions, procurement rhythms, and regulatory cadence. The report provides a complete regional and application breakdown, but the strategic takeaway for now is that regional intensity differs not only in scale but in time-to-value, access constraints, and competitive density.
Supply chain considerations add another layer of complexity. Heparin-based production in particular depends on stable sourcing of raw materials, and any disruption in that chain can create ripple effects across pricing, availability, and hospital procurement. Simultaneously, the broader transition toward direct oral agents continues to reshape prescription patterns, driven by their operational advantages in routine care. The interplay of these drivers is examined in depth within the research, with the objective of helping organizations anticipate rather than react to demand shifts.
Heparin Market
Competitive Landscape and Strategic Positioning
The competitive field in blood thinning drugs is defined by both concentration and specialization. At the top of the market, a small group of leading firms accounts for an outsized share of revenue, reflecting the scale advantages of patented oral anticoagulants, entrenched formulary positions, and established global commercialization capabilities. This concentration creates a dual reality: it signals durable franchise value for incumbents, but it also raises the stakes for differentiation, access negotiations, and lifecycle management as patent timelines advance.
Bristol-Myers Squibb Company and Pfizer Inc. continue to co-market Eliquis, a leading direct oral anticoagulant positioned for stroke prevention in non-valvular atrial fibrillation and for the treatment and prevention of venous thromboembolism. Their shared commercial footprint has made Eliquis a central reference point in the oral anticoagulant category. Bayer AG markets Xarelto, a direct Factor Xa inhibitor indicated across stroke prevention, DVT and PE treatment, and broader cardiovascular event reduction, while Johnson & Johnson, through Janssen Pharmaceuticals, co-markets Xarelto and extends the category with additional anticoagulation options in its broader portfolio. Boehringer Ingelheim International GmbH markets Pradaxa, a direct thrombin inhibitor used in atrial fibrillation stroke prevention and DVT/PE management, and Daiichi Sankyo Company, Limited markets Savaysa/Lixiana, another direct Factor Xa inhibitor serving stroke prevention and VTE treatment needs.
Beyond the branded oral anticoagulant leaders, a second tier of competitors competes with depth in injectable and heparin-based formulations. Sanofi S.A. produces Lovenox, a low molecular weight heparin widely used across both hospital and outpatient anticoagulation settings. Aspen Pharmacare Holdings Limited specializes in generic and branded heparin-based anticoagulants and low molecular weight heparins for global distribution. GlaxoSmithKline plc offers Arixtra, a synthetic Factor Xa inhibitor for prevention and treatment of thromboembolic conditions. F. Hoffmann-La Roche Ltd supports anticoagulation-related therapeutic areas through diagnostics and biologics, while Dr. Reddy's Laboratories Ltd. manufactures generic versions of key anticoagulants, including rivaroxaban and enoxaparin, for global supply. Amphastar Pharmaceuticals Inc. produces generic heparin and enoxaparin injectable anticoagulants for hospital use, Baxter International Inc. supplies heparin-based anticoagulants and injectable formulations for critical care, and Fresenius Kabi AG manufactures generic enoxaparin and other injectable anticoagulants for worldwide distribution.
This competitive configuration matters because it determines where pricing power persists, where generic erosion accelerates, and where operational execution in supply, access, and formulation becomes the decisive advantage. The report unpacks these dynamics systematically, allowing executive teams to evaluate each player's exposure to patent transitions, generic entry, hospital procurement patterns, and regional formulary pressure without relying on incomplete secondhand narratives.
Regulatory and Commercial Dynamics Shaping 2026 and Beyond
The market is being re-shaped not only by demand drivers but by discrete regulatory and commercial events that can alter revenue trajectories quickly. One notable development is the voluntary withdrawal of Andexxa, the reversal agent for Factor Xa inhibitors rivaroxaban and apixaban, from the US market following FDA analysis showing that risks of thromboembolic events outweighed benefits. This regulatory outcome has implications for safety perceptions, clinical protocol design, and the broader risk-management framework around Factor Xa inhibitor use.
At the same time, competitive and access dynamics are shifting on the generic side. In March 2025, the FDA approved the first generics of Xarelto 2.5 mg tablets for the reduction of major cardiovascular events in adult patients with coronary artery disease or peripheral artery disease. This expansion of generic availability changes the cost and access calculus in a specific but commercially meaningful indication set.
A further catalyst is approaching in the European market. The European market exclusivity for Eliquis is set to expire in May 2026, opening the door for generic entry across the region. Analyst projections indicate a corresponding decline in global sales for the reference product in 2026, underscoring the sensitivity of branded oral anticoagulant revenue to patent timelines and generic competition. This transition will test incumbent positioning, regional pricing strategy, and the ability of competitors to capture share without disrupting care continuity.
Worldwide Blood Thinning Drugs Market
Other forces are less dramatic but no less important. Ongoing adoption of direct oral anticoagulants continues to be driven by their improved safety profile relative to warfarin and the absence of routine monitoring requirements, supporting broader use in atrial fibrillation and VTE management. Meanwhile, heparin and low molecular weight heparin production depends on consistent supply chains for porcine mucosal extracts, with major manufacturers maintaining active global production to support hospital and outpatient demand. Each of these forces is integrated into the research narrative, with the intent of giving strategy teams a current and actionable view of the operating environment.
What the Research Delivers: Content and Analytical Coverage
The Worldwide Blood Thinning Drugs Market study is designed as a decision-support instrument rather than a descriptive overview. It begins with a full historical reconstruction from 2020 through the 2025 base year, establishing the trajectory and growth pattern needed to evaluate whether recent momentum is structurally sustainable. From that baseline, the forecast spans 2026 through 2032, providing year-by-year revenue projections that support budgeting, capacity planning, and investment prioritization.
The report contains detailed segmentation analysis across drug class, indication, and region, enabling teams to pinpoint where growth is being generated and where share shifts are most likely. It profiles the competitive landscape across the leading branded and generic participants, mapping each company's product footprint, therapeutic focus, and strategic posture. Recent developments are integrated directly into the market dynamics discussion, so that patent expirations, generic approvals, and regulatory actions are not treated as isolated news items but as inputs to forward-looking strategy.
In addition to quantitative estimates, the research covers market concentration, supply chain dependencies, access and reimbursement considerations, and the clinical logic that underpins prescribing shifts. This combination allows the document to serve multiple internal audiences: commercial leaders can use it for access and share strategy, R&D and pipeline teams can benchmark therapeutic positioning, and supply and operations teams can assess continuity risk in vulnerable categories. The aim is to provide a single, coherent framework for evaluating how the category will evolve and where specific organizational decisions will have the greatest impact.
Strategic Implications for 2026 Decision-Makers
For organizations operating in or adjacent to the blood thinning drugs category, the forecast window rewards disciplined prioritization. The most immediate strategic question is how to respond to the European exclusivity transition for Eliquis in 2026. Companies with exposure to oral anticoagulants should assess the likely pace and pattern of generic entry, the resilience of branded pricing, and the potential for regional share redistribution. Those with generic portfolios should evaluate whether supply readiness, regulatory positioning, and tender access are sufficient to capture opportunity without compromising margin quality.
A second priority is the management of concentration risk in heparin and low molecular weight heparin supply. Because production depends on stable raw material sourcing, any interruption can affect availability and pricing across hospital and outpatient channels. Mapping exposure across manufacturing relationships, inventory buffers, and regional procurement requirements should be part of any operational risk review.
A third priority is the continued integration of clinical and access strategy. Direct oral anticoagulants are likely to retain adoption momentum given their safety and monitoring advantages, but access conditions, formulary placement, and regional reimbursement realities will determine how that momentum translates into revenue. Teams should use the segmentation detail to match commercial assets to the indication and geography combinations where adoption potential is strongest.
Finally, the category's concentration profile suggests that competitive intelligence should be continuous rather than episodic. With a small group of firms accounting for a large share of revenue, even localized formulary changes or regulatory actions can alter competitive balance. The report provides the structural baseline needed to interpret those moves accurately and to adjust strategy without overreacting to isolated events.
Conclusion: Positioning for the Forecast Period
The blood thinning drugs market is moving through a period in which growth, concentration, and transition intersect. The projected 8.5 percent compound annual growth rate through 2032, anchored by a large revenue base already established in the 2025 base year, signals that the category remains strategically important. Yet the real value of the research lies in its ability to show where that growth will be distributed, how competitive exposure is changing, and what events in 2025 and 2026 mean for the years that follow.
For executive teams, the central task is to convert macro certainty into operational precision. That requires a view that goes beyond headline size and connects drug-class dynamics, indication demand, regional variation, supply continuity, and regulatory catalysts into one decision-ready framework. The Worldwide Blood Thinning Drugs Market research is built to provide exactly that view, with full segmentation data, complete competitive profiling, and detailed scenario support available in the full report. Readers seeking the granular figures, regional splits, indication shares, and company-level positioning should access the complete study to ensure strategic decisions are grounded in the full evidence base.
For detailed analysis of this topic, please visit the official page: Worldwide Blood Thinning Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com