

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
全球避孕药市场将在2026-2032年以6.51%的CAGR增长至34548.71百万美元

Strategic Intelligence for the Next Decade: Inside the Worldwide Contraceptive Pills Market
The global contraceptive pills market stands at a pivotal inflection point. Between 2020 and 2032, the sector is projected to expand from a baseline exceeding 16 billion USD to a forecasted valuation approaching 34.5 billion USD, reflecting a compound annual growth rate of 6.51 percent. This trajectory is not merely a function of demographic expansion; it is the compound result of regulatory innovation, shifting reimbursement architectures, formulation breakthroughs, and deeply entrenched competitive dynamics that reward foresight. For executives navigating portfolio allocation, market entry, pricing strategy, or supply chain optimization, understanding the structural forces shaping this landscape has transitioned from a nice-to-have to an operational imperative.
Our latest comprehensive research, Worldwide Contraceptive Pills Market, delivers a granular, forward-looking intelligence framework designed specifically for enterprise decision-making in 2026 and beyond. Rather than offering static historical snapshots, this study maps the causal mechanisms driving demand, dissects the competitive maneuvers defining share allocation, and quantifies the momentum vectors that will separate strategic winners from reactive followers. Below, we outline the analytical architecture of the report and demonstrate how its insights translate into actionable corporate strategy.
A Market Defined by Regulatory Disruption and Formulation Evolution
The industry is undergoing a structural recalibration. The United States regulatory environment has already catalyzed measurable behavioral shifts. Following the historic approval of the first nonprescription daily oral contraceptive, availability expanded across retail and digital channels in early 2024, accompanied by a suggested retail price of approximately 19.99 USD for a one-month supply. Subsequent observational studies documented increased utilization rates in the months that followed, underscoring how convenience and reduced access friction can rapidly reshape consumption patterns.
Worldwide Contraceptive Pills Market
Parallel regulatory milestones have broadened the formulation frontier. The introduction of the first orally disintegrating tablet for pregnancy prevention addressed long-standing adherence barriers for populations with swallowing difficulties, while signaling a broader industry pivot toward patient-centric delivery mechanisms. Looking ahead, additional over-the-counter combined oral contraceptive candidates are progressing toward formal submission windows, with applications anticipated around the middle of the decade. These developments are not isolated product launches; they represent architectural changes in how contraception is accessed, reimbursed, and prescribed across different payer ecosystems.
Reimbursement dynamics remain equally critical. In the United States, the majority of women with private insurance or Medicaid continue to receive no-cost coverage for prescription oral contraceptives, yet coverage for over-the-counter alternatives remains fragmented and heavily dependent on state-level policy in the absence of sweeping federal guidance. This creates a bifurcated market environment where channel strategy, pricing architecture, and formulary positioning must be calibrated with precision rather than assumed through broad generalizations.
Simultaneously, procurement economics in low- and middle-income countries reveal that pill acquisition costs still command the largest single share of total supply expenditures, with private-sector operators handling a disproportionate share of both end users and associated costs. These cost structures directly influence sourcing decisions, margin modeling, and the viability of tiered-market strategies for multinational manufacturers seeking sustainable scale.
Decoding the Segmentation Architecture
The report disaggregates the market across three foundational dimensions, each carrying distinct strategic implications for product development, channel management, and regional prioritization.
By formulation type, the analysis separates combined oral contraceptives, progestogen-only variants, and emergency contraception. Each category operates under different clinical positioning, demand elasticity, prescribing habits, and reimbursement pathways. The relative weight of these segments shifts meaningfully across regions and over time, influenced by guideline updates, cultural attitudes, and the speed of generic conversion.
By distribution channel, the market is mapped across retail pharmacies, hospital pharmacies, and online pharmacies. The interplay among these channels is becoming increasingly nonlinear as digital procurement, mail-order fulfillment, and self-access models reshape traditional dispensing hierarchies. Channel economics, inventory velocity, and patient acquisition costs differ substantially across these pathways, and procurement or commercial leaders require precise visibility into which channels are capturing incremental volume under current regulatory and reimbursement conditions.
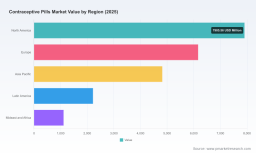
By geography, the study illuminates regional demand intensity, maturity curves, and growth acceleration patterns. Mature markets exhibit stable baseline volumes with innovation-driven differentiation, while emerging markets reflect demographic momentum, public health program integration, and evolving private-sector penetration. The report tracks how these regional ecosystems diverge in terms of competitive intensity, pricing norms, and regulatory cadence, enabling firms to align resource deployment with the markets where strategic leverage is highest.
Crucially, the full segmentation breakdown, including precise regional and type-level valuations, is reserved within the complete report. This deliberate approach ensures that clients receive contextualized strategic guidance rather than fragmented figures, while preserving the research as a curated intelligence asset that rewards direct engagement.
Competitive Landscape: Concentration, Maneuvering, and Innovation Velocity
Market structure analysis reveals a moderately concentrated competitive environment. The top three participants collectively account for a substantial share of total revenue, while the leading five firms extend their footprint further. Such concentration underscores the importance of portfolio optimization, lifecycle management, and channel leverage, but it does not diminish the strategic relevance of agile generic manufacturers and specialty innovators who are actively reshaping sub-segments.
Industry leadership is anchored by global pharmaceutical organizations with deep women's health portfolios and established commercial infrastructure. Bayer AG continues to maintain a prominent position through established combined and progestin-only oral contraceptives. Pfizer Inc. sustains a broad hormonal contraceptive presence and leverages its global commercialization engine to defend and expand share. Organon & Co. has sharpened its focus on women's health, embedding oral contraceptive offerings within a deliberately structured reproductive health portfolio. Merck & Co., Inc. and Johnson & Johnson, through its Janssen segment, contribute additional branded and portfolio-based depth to the branded end of the market. AbbVie Inc., incorporating legacy Allergan assets, reinforces its footprint in the hormonal contraceptive category through established product lines.
Generic manufacturing and accessible pricing strategies define another critical competitive axis. Teva Pharmaceutical Industries Ltd. operates as a leading generic producer with an extensive portfolio of branded equivalents, while Perrigo Company PLC has captured strategic attention through its pioneering role in over-the-counter access, bringing the first FDA-approved nonprescription daily oral contraceptive to mainstream retail and digital distribution. Amneal Pharmaceuticals LLC further extends the generic footprint with oral contraceptive products integrated into its broader portfolio.
Indian pharmaceutical manufacturers constitute a highly active and globally oriented production base. HLL Lifecare Limited operates as a government-linked enterprise with wide-ranging oral contraceptive production, including supply alignments with public health programs. Aurobindo Pharma Limited, Lupin Pharmaceuticals Inc., Cipla Inc., Zydus Lifesciences Ltd., and Sun Pharmaceutical Industries Ltd. each maintain active generic portfolios targeting domestic and international markets, with Lupin pursuing tentative approvals for specific active ingredient combinations and the broader group collectively supporting affordability, supply continuity, and cross-border distribution flexibility.
Recent industry developments illustrate how quickly competitive conditions can evolve. The widespread retail and online availability of the first over-the-counter daily oral contraceptive following its 2023 approval demonstrated how regulatory milestones can translate rapidly into market behavior. The introduction of the first orally disintegrating combined formulation broadened the clinical utility spectrum. Observational data from mid-2025 confirmed rising utilization patterns after over-the-counter availability expanded, reinforcing the strategic importance of anticipating adoption curves and adjusting supply, pricing, and awareness investments accordingly.
Detailed competitor profiles, capability assessments, pipeline positioning, and strategic grouping are fully developed within the report, enabling leadership teams to benchmark their posture against actual market architecture rather than surface-level brand presence.
Fertility Drugs Market
The 2026 Decision Lens: Why This Research Matters Now
As corporate planning cycles move deeper into 2026, several interrelated questions demand evidence-based answers: How will over-the-counter availability alter channel economics and payer negotiations? Which formulation categories will capture the fastest incremental demand under evolving clinical guidelines? Where should manufacturing and distribution capacity be prioritized to align with regional growth acceleration? How can firms balance branded differentiation with generic affordability while navigating reimbursement fragmentation? What competitive moves are likely from both incumbents and emerging generic or specialty entrants?
This report is designed to answer those questions with structured rigor. It integrates historical trajectory, forward-looking forecast modeling, segmentation mapping, competitive profiling, and regulatory and reimbursement context into a unified decision-support framework. Analysts, strategists, and commercial leaders will find practical utility in its treatment of demand drivers, supply economics, channel behavior, and competitive response patterns. Rather than presenting isolated numbers, the study connects market signals to operational consequences, helping organizations stress-test assumptions, prioritize investments, and anticipate second-order effects.
What the Report Delivers
The full study offers an end-to-end market assessment calibrated for executive and operational use. Its scope includes:
- Historical performance tracking across the base year and preceding years, establishing baseline trends and volatility patterns
- Forward-looking forecasts through the end of the decade, anchored in explicit growth assumptions and segmentation logic
- Granular segmentation analysis across type, distribution channel, and region, with narrative interpretation of structural drivers
- Competitive profiling of leading global, generic, and emerging market manufacturers, including portfolio orientation and strategic positioning
- Regulatory, reimbursement, and procurement context that shapes access, pricing, and demand elasticity across different market environments
- Synthesis of recent developments, including over-the-counter access expansion, novel formulation approvals, and utilization trend data
- Strategic implications for market entry, portfolio allocation, channel strategy, pricing architecture, and competitive response
To preserve analytical integrity and maximize strategic value, detailed tables, precise segmentation valuations, and full quantitative forecasts are provided within the complete downloadable research. This approach allows us to demonstrate methodological depth while ensuring that market participants receive the complete dataset required for planning, modeling, and executive review.
Moving From Intelligence to Execution
The worldwide contraceptive pills market is being reshaped by regulatory innovation, formulation diversity, channel expansion, reimbursement complexity, and competitive maneuvering across both branded and generic domains. These forces create opportunity for organizations that act on detailed evidence rather than broad assumptions. Our Worldwide Contraceptive Pills Market research is built to provide that evidence with clarity, structure, and strategic relevance.
For decision-makers seeking to align product strategy, commercial planning, and market positioning with the most current and comprehensive industry intelligence, the full report offers the depth and precision necessary to convert insight into execution. Explore the complete analysis, access the detailed segmentation and forecast data, and equip your team with the intelligence required to navigate the next phase of market evolution with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Contraceptive Pills Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com