

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Potassium Carbonate Hydrate Market Hits $479.77M in 2025, Set to Reach $648.54M by 2032 at 4.4% CAGR

Navigating the Evolving Landscape of Potassium Carbonate Hydrate: Strategic Insights for 2026 and Beyond
The global potassium carbonate hydrate market is entering a pivotal phase defined by steady structural growth, shifting regulatory frameworks, and intensifying competition across key industrial verticals. As we advance into 2026, corporate decision-makers across manufacturing, supply chain, and procurement functions require more than high-level forecasts. They need a granular, actionable intelligence framework that maps historical trajectories, anticipates macroeconomic and policy inflection points, and decodes the competitive maneuvering of leading producers. Our newly published Worldwide Potassium Carbonate Hydrate Market research study delivers precisely that. Designed as a strategic compass rather than a static dataset, this report equips executives with the analytical depth required to optimize sourcing strategies, evaluate market entry opportunities, and align capital allocation with emerging demand cycles.
Over the past half-decade, the sector has demonstrated remarkable resilience amid fluctuating feedstock costs, regional energy constraints, and evolving compliance mandates. From 2020 through 2025, global revenue expanded from approximately 382.45 million USD to 479.77 million USD, reflecting a compound trajectory that underscores the material's indispensable role across glass and ceramics, agrochemicals, food processing, and specialty chemical synthesis. Looking ahead to the 2026 to 2032 forecast window, the market is projected to reach 502.78 million USD in the current year, with sustained momentum carrying valuation toward 648.54 million USD by the close of the forecast period. This expansion is underpinned by a consistent compound annual growth rate of 4.4%, signaling a moderately paced but structurally robust upward curve. For strategic planners, these figures are not merely retrospective milestones; they represent baseline parameters against which capacity investments, pricing strategies, and regional allocation decisions must be calibrated.
Strategic Forecast Architecture: Mapping 2026 to 2032
The credibility of any market intelligence asset lies in its ability to translate macroeconomic indicators into operational foresight. This report constructs a multi-layered forecasting architecture that accounts for historical consumption patterns, production economics, and forward-looking demand triggers. The base year of 2025 anchors a robust back-casting methodology, ensuring that incremental year-over-year movements reflect authentic market dynamics rather than statistical smoothing. As the analysis progresses through 2026, 2027, and beyond, the model incorporates sensitivity variables tied to feedstock availability, energy pricing volatility, and regulatory compliance costs. Executives will find particular value in how the forecast isolates inflection points where supply chain bottlenecks or policy shifts could materially alter regional supply-demand equilibriums. By treating the 4.4% CAGR not as a static promise but as a dynamic range modulated by real-world variables, the study empowers leadership teams to stress-test their strategic assumptions against plausible disruption scenarios.
Supply Chain Architecture and Production Economics
Understanding the potassium carbonate hydrate value chain requires a clear grasp of how raw material inputs translate into finished grades ready for industrial, food, or pharmaceutical deployment. The production pathway typically begins with potassium hydroxide derived from potash, which reacts with carbon dioxide in controlled carbonation environments. Notably, this process frequently involves carbon capture mechanisms that initially yield the hydrated form, K2CO3·1.5H2O, before targeted dehydration steps produce anhydrous variants for specialized applications. This technical nuance carries direct implications for energy intensity, capital expenditure, and regional cost competitiveness. Facilities integrated with upstream chlor-alkali operations benefit from feedstock synergies, while standalone producers must navigate broader commodity market exposures. Pricing dynamics in late 2025 further illustrate the geography-driven cost landscape. In Northeast Asia, hydrated potassium carbonate traded around 1.17 USD per kilogram, supported by firm upstream potassium hydroxide costs and consistent pull from specialty glass and ceramics manufacturers. Across Europe, prices climbed to approximately 1.70 USD per kilogram, reflecting higher energy and natural gas expenditures that directly pressure energy-intensive carbonation processes, alongside robust demand from pharmaceutical and detergent sectors. These regional differentials are not transient anomalies; they represent structural pricing layers that procurement and manufacturing strategists must factor into long-term contract negotiations and plant location evaluations.
Regulatory and Compliance Inflection Points
Regulatory shifts are rapidly transitioning from peripheral considerations to central strategic variables. Beginning January 1, 2026, potassium carbonate has been added to the Internal Revenue Service taxable chemical substances list under Superfund tax rules, a development triggered by the fact that taxable chemicals constitute more than twenty percent by weight in its predominant production methodology. This classification introduces new compliance cost considerations that will ripple through production economics, particularly for facilities operating at scale or those navigating multi-jurisdictional supply networks. Simultaneously, the material remains under review within the USDA National Organic Program sunset process, with ongoing evaluation slated for 2027 regarding its continued allowance in organic crop production as a synthetic substance. For agrochemical and food processing stakeholders, the trajectory of this review carries tangible implications for formulation strategies, certification pathways, and downstream market access. The report dissects these regulatory currents with precision, mapping how compliance timelines intersect with production planning, supply chain diversification, and product portfolio positioning. Executives who anticipate regulatory friction rather than react to it will secure decisive cost and market access advantages.
Competitive Landscape and Strategic Positioning
Global Market Concentration and Strategic Holdings
The potassium carbonate hydrate sector exhibits moderate concentration, with the top three players collectively capturing approximately 42.8 percent of market revenue and the top five expanding that share to 58.5 percent. This structure indicates a landscape where scale advantages, integrated production capabilities, and diversified application portfolios create meaningful competitive moats, while still leaving substantial room for specialized producers and regional champions to carve out defensible niches. Strategic positioning in this environment demands more than volume expansion; it requires alignment between grade specialization, geographic reach, and application-specific technical support.
Potassium Formate Market
Key Players and Strategic Profiles
Armand Products Company, headquartered in Muscle Shoals, Alabama, stands as a world leader in potassium carbonate production, operating large-scale manufacturing capacity that ships both anhydrous and hydrated grades globally across industrial, food, and specialty applications. Its ISO 9001:2015 certified facility underscores a commitment to standardized quality control that resonates strongly with regulated end markets. Vynova Group, anchored by Belgium-based operations, supplies multiple grades in crystalline granulated, powder, and hydrated forms to European and worldwide markets, with dedicated applications spanning food, pharmaceutical, agrochemical, and cocoa processing sectors. Its multi-format capability positions the company as a flexible supplier capable of addressing highly specific formulation requirements. INEOS KOH operates across the USA and Europe, producing liquid potassium carbonate at a forty-seven percent solution concentration using upstream potassium hydroxide from its chlor-alkali plant. This integration supports demanding use cases in video glass manufacturing, animal feed additives, and polymer catalysts, where consistent chemical delivery and volume reliability are paramount. Hawkins, Inc., based in the USA, manufactures high-purity liquid potassium carbonate at the same forty-seven percent concentration, targeting agriculture, printed circuit board production, food preservation, and oil industry applications. Its focus on purity and liquid-form convenience addresses specialized processing environments where handling efficiency and chemical precision directly influence downstream performance. UNID Company Ltd., headquartered in Seoul, South Korea, operates as a major Asian producer within its inorganic chemicals division, leveraging significant production capacity to serve both domestic and export markets. Evonik Industries AG, the Germany-based global specialty chemicals company, produces potassium carbonate for a broad spectrum of industrial applications, drawing on its advanced chemical engineering infrastructure to support performance-driven formulations. AGC Inc., also known as AGC Chemicals, is headquartered in Japan and supplies high-purity potassium carbonate specifically tailored for ceramics, glass, and other specialty applications where material consistency and trace impurity control are non-negotiable. Altair Chimica SpA, an Italian producer, operates alongside caustic potash and other inorganic chemicals, offering European buyers integrated sourcing options that reduce supply chain fragmentation. In China, Zhejiang Dayang Biotech Group Co. Ltd. has established itself as a significant manufacturer and exporter with broad domestic and international supply reach, while Wentong Potassium Salt Group, operating under Qinghai Yanhu, focuses on high-purity potassium carbonate grades and has pursued capacity expansions specifically targeted at electronics and industrial uses. Together, these players illustrate a competitive ecosystem where scale, purity, regional proximity, and application specialization intersect in complex ways. The report provides detailed comparative analytics that reveal how each enterprise is positioning itself to capture value across grade segments, geographic corridors, and end-use verticals.
Report Architecture: Operational Intelligence for Decision Makers
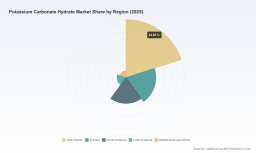
The Worldwide Potassium Carbonate Hydrate Market study is engineered for immediate operational relevance. Beyond macroeconomic forecasting, the report delivers a structured breakdown of market segmentation that maps revenue distribution across grades, applications, and regions, enabling procurement teams to identify concentration risks and supply diversification pathways. The grade analysis distinguishes between industrial, food, and pharmaceutical categories, highlighting how purity thresholds, certification requirements, and pricing premiums shape margin structures and competitive dynamics. Application-level evaluation traces how demand from glass and ceramics, agrochemicals and fertilizers, food processing, chemical intermediates, and other verticals interacts with production capacity, seasonal consumption cycles, and substitution risks. Geographic coverage extends across Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa, providing context on regional supply-demand balances, logistics considerations, and localized pricing behaviors without reducing the narrative to static percentage breakdowns. Competitive profiling synthesizes facility capabilities, certification footprints, product format portfolios, and strategic expansions into actionable benchmarking frameworks. The report also integrates scenario analysis modules that allow executive teams to model the financial and operational impact of regulatory adjustments, feedstock volatility, and demand acceleration or deceleration across the forecast window. By aligning quantitative baselines with qualitative strategic context, the study functions as a decision-support platform that can be deployed across planning, sourcing, and market-entry workstreams.
Strategic Imperatives for Corporate Leadership
As the market navigates the 2026 to 2032 horizon, leadership teams must translate intelligence into action across several interconnected fronts. First, procurement strategies should account for the widening regional price differentials and the structural energy cost pressures that influence European and Northeast Asian supply economics, particularly when negotiating multi-year supply agreements. Second, regulatory preparedness must become a core competency, with compliance teams tracking the Superfund taxable chemical classification and the ongoing USDA organic program review to anticipate cost adjustments and formulation constraints before they disrupt procurement cycles. Third, competitive positioning demands clarity on grade specialization and application focus, as margin profiles diverge sharply between bulk industrial supply and high-purity pharmaceutical or specialty glass requirements. Fourth, capacity planning and geographic diversification should be evaluated against regional concentration patterns and logistics resilience, ensuring that supply networks can absorb localized disruptions without compromising delivery reliability. Finally, strategic partnerships and supplier evaluations should be grounded in a detailed understanding of each major producer's technical capabilities, certification status, and expansion trajectories, enabling more precise vendor selection and long-term collaboration frameworks.
Worldwide Potassium Carbonate Hydrate Market
The Worldwide Potassium Carbonate Hydrate Market research study is designed to serve as the foundational intelligence asset for these strategic priorities. By combining rigorous historical analysis, transparent forecasting methodology, segmentation insights, and competitive profiling, the report provides a comprehensive view of where the market stands, how it is likely to evolve, and what decisions will separate resilient operators from reactive followers. Executives who engage with the full spectrum of findings will be better positioned to allocate capital efficiently, negotiate from a position of informed strength, and anticipate the regulatory and competitive shifts that will define the next phase of market development. To access the complete segmentation breakdowns, detailed company benchmarking, regional pricing trajectories, and scenario modeling tools that underpin these insights, we invite you to explore the full report through our official portal and integrate this intelligence directly into your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Potassium Carbonate Hydrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com