

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Women's Non-athletic Footwear Market Hits $188.4M in 2025, Projects 4.5% CAGR to 2032

Navigating Growth and Complexity in the Global Women's Non-Athletic Footwear Market (2026-2032)
The global women's non-athletic footwear market stands at a pivotal juncture in 2026. As consumer preferences shift towards a blend of comfort, style, and sustainability, industry leaders must navigate a landscape defined by volatile raw material costs, evolving regulatory standards, and intense competition among luxury conglomerates and contemporary brands. PW Consulting's latest comprehensive study, Worldwide Women's Non-athletic Footwear Market, offers a critical roadmap for stakeholders aiming to capitalize on projected growth through 2032.
This report is not merely a statistical overview; it is a strategic instrument designed to inform product development, supply chain resilience, and market entry strategies. By analyzing historical performance from 2020 to 2025 and forecasting trends through 2032, this research provides the granularity needed to make informed decisions in a fragmented yet lucrative sector.
Worldwide Women's Non-athletic Footwear Market
Market Trajectory and Valuation Overview
The market has demonstrated resilient growth over the past five years, recovering from pandemic-era disruptions to establish a robust upward trajectory. In 2020, the global revenue for women's non-athletic footwear stood at approximately USD 148,500 million. By 2025, this figure had climbed to USD 188,400 million, reflecting a compound annual growth rate that underscores the category's inherent demand drivers. Looking ahead, the forecast period from 2026 to 2032 suggests continued expansion, with valuations projected to reach USD 256,390 million by the end of the forecast window.
This growth is not linear. The forecast model anticipates fluctuations that reflect broader economic conditions, such as the slight contraction observed in the 2029 projection compared to 2028, before resuming growth. Understanding these nuances is vital for capacity planning and inventory management. The report details the specific drivers behind these peaks and troughs, linking them to consumer confidence indices, disposable income trends, and seasonal fashion cycles. For executives planning capital allocation in 2026, grasping the velocity of this growth is essential to avoid overstocking or missed opportunities during high-demand periods.
Deep Dive into Product Categories and Material Dynamics
The market is segmented into distinct product categories, each with its own growth 잠재력을 및 consumer appeal. While the total market value is significant, the distribution of revenue across categories reveals where consumer spend is concentrating. Boots, casual shoes and loafers, sandals, heels and pumps, and flats and wedges represent the core pillars of this industry. The report provides a detailed breakdown of how each category performed historically and how it is expected to evolve.
For instance, the demand for comfortable yet stylish options has pushed casual shoes and loafers into prominence, while seasonal shifts continue to drive sandal and boot sales. Meanwhile, the enduring popularity of heels and pumps in professional and formal settings maintains a steady revenue stream for luxury and contemporary brands alike. Our analysis goes beyond basic volume counts to explore the price elasticity within each category, helping brands identify where premiumization strategies might succeed versus where value-oriented positioning is required.
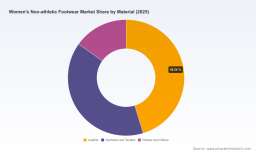
Material composition remains a critical cost and branding lever. Leather continues to hold a substantial share of the material market, valued for its durability and prestige. However, supply chain volatility poses risks. Raw material data indicates that wet-blue leather prices rose significantly in early 2025, driven by drought conditions impacting cattle herds in Brazil. Additionally, regulatory constraints in India led to a decline in leather exports during 2024-2025. These disruptions highlight the vulnerability of leather-dependent supply chains.
Consequently, synthetic and textiles are gaining adoption for cost stability and design flexibility. The report analyzes the trade-offs between material choices, examining how brands are balancing premium perception with cost control. Furthermore, the rise of sustainability mandates is reshaping material procurement. With increased focus on ISO 14021 environmental labeling standards to address greenwashing concerns, brands must verify their material claims. Our study evaluates how different material segments are adapting to these regulatory pressures and what it means for sourcing strategies in the coming years.
Regional Consumption Patterns and Market Concentration
Geographically, the market is diverse, with consumption patterns varying significantly by region. The report segments the market into Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa. Each region presents unique opportunities and challenges, from distribution infrastructure maturity to local fashion preferences. While global brands often prioritize developed markets, emerging economies offer substantial volume growth potential.
Understanding the regional weight of each market is crucial for supply chain optimization and marketing spend allocation. The research provides a comparative analysis of regional revenue contributions without exposing sensitive granular data publicly, ensuring that clients who engage with the full report gain a competitive edge in market selection. The concentration of market power is another key focus. With a CR3 of 12.45% and a CR5 of 18.6%, the market remains relatively fragmented compared to other luxury sectors, allowing for niche players and regional specialists to thrive alongside conglomerates. However, consolidation trends are observable, particularly among mid-sized brands seeking scale to compete on logistics and sustainability compliance.
Competitive Landscape and Strategic Moves
The competitive environment is characterized by a mix of heritage luxury houses, accessible luxury groups, and specialized footwear manufacturers. Key players such as Prada SpA, LVMH, Chanel, Kering, Capri Holdings, and Tapestry Inc. dominate the high-end segment, leveraging brand equity and design innovation. These entities frequently use runway showcases to set trends that trickle down to contemporary markets. For example, recent runway presentations have highlighted reimagined classic silhouettes, such as platform Mary Janes and dipped-toe shoes, signaling shifts in aesthetic preferences that manufacturers must anticipate.
On the accessible and contemporary side, companies like Steve Madden Ltd., Skechers USA, Inc., Caleres, Inc., Bata Corporation, The ALDO Group, and VF Corporation compete on style, comfort, and price accessibility. Steve Madden continues to drive trend-focused designs at contemporary price points, while Skechers emphasizes comfort technologies like memory foam enhancements. Caleres manages a diverse portfolio through owned brands and wholesale channels, ensuring broad market reach. Bata maintains a strong presence in emerging and developed markets with affordable formal and casual styles.
Innovation in comfort and sustainability is also evident among European manufacturers. ECCO Sko A/S utilizes direct-injection technology and leather expertise to produce premium comfortable footwear. Geox S.p.A. differentiates itself with patented breathable membrane technology, appealing to consumers seeking functionality without sacrificing style. The ALDO Group focuses on fashion-forward seasonal collections that emphasize both style and accessibility. These strategic differentiators are critical in a market where product differentiation is increasingly difficult.
Recent developments underscore the dynamic nature of this landscape. In late 2025, Chanel showcased dipped-toe shoes for Spring/Summer 2026, reinforcing the luxury segment's focus on subtle detailing. Similarly, ALDO launched its Spring and Summer 2025 collection with an emphasis on enhanced comfort and sustainable materials. Within the Prada Group, Miu Miu launched the 'Tyre' sneaker collection, blending lace-up and ballerina silhouettes with flexible natural rubber soles, illustrating the blurring lines between athletic and non-athletic aesthetics. These moves are not isolated; they signal broader industry shifts towards versatility and sustainability that are dissected in depth within the full report.
Consumer Behavior and Industry Challenges
Consumer habits are reshaping the market foundation. Women's footwear accounted for a significant share of the overall footwear market in 2025, driven by demand for comfort and style in non-athletic categories. The post-pandemic preference for comfort-first designs has not diminished the desire for aesthetics; rather, it has created a hybrid demand where consumers expect both. This shift challenges brands to innovate in sole technology, ergonomics, and material breathability while maintaining fashionable silhouettes.
Supply chain resilience remains a top challenge. Beyond leather price volatility, brands must navigate labor costs, shipping logistics, and regulatory compliance across multiple jurisdictions. The industry is also grappling with sustainability expectations. Consumers and regulators alike are demanding transparency regarding material sourcing and environmental impact. The implementation of stricter environmental labeling standards requires brands to audit their supply chains rigorously. Failure to comply can result in reputational damage and market access restrictions.
Additionally, the rise of direct-to-consumer channels and digital marketing alters how brands interact with their 고객. Inventory management must become more agile to respond to real-time demand signals rather than relying solely on seasonal forecasts. The report examines how leading companies are adapting their operational models to meet these demands, offering case studies and strategic recommendations.
Footwear Market
Strategic Value for 2026 Decision-Makers
For executives navigating 2026, this report serves as a decision-support system. It answers critical questions regarding where to invest, what to produce, and how to compete. By synthesizing market size data, segmentation splits, and competitive intelligence, the study enables:
- Product Portfolio Optimization: Identify high-growth categories and materials to align design pipelines with market demand.
- Supply Chain Risk Mitigation: Understand raw material volatility and regional supply constraints to build more resilient sourcing strategies.
- Competitive Positioning: Benchmark against key players to identify gaps in the market and opportunities for differentiation.
- Regional Market Entry: Evaluate regional revenue potentials and consumer behaviors to prioritize expansion or contraction strategies.
- Sustainability Compliance: Stay ahead of regulatory changes regarding environmental labeling and material sourcing.
The insights contained within this study are derived from extensive primary and secondary research, ensuring accuracy and relevance. However, the full depth of the analysis—including precise segmentation values, regional breakdowns, and detailed company profiles—is reserved for subscribers. This approach ensures that the intelligence remains a valuable asset for strategic planning rather than public knowledge.
Conclusion
The women's non-athletic footwear market offers substantial opportunities for growth, but realizing them requires more than intuition. It demands data-driven clarity on market dynamics, competitive moves, and consumer shifts. As the industry moves through the forecast period to 2032, the ability to adapt to material cost fluctuations, sustainability mandates, and evolving style preferences will define market leaders.
PW Consulting's Worldwide Women's Non-athletic Footwear Market report provides the comprehensive intelligence needed to navigate this complexity. For organizations committed to securing their position in this evolving landscape, accessing the full dataset and strategic analysis is a critical next step. We invite stakeholders to explore the complete findings to unlock the specific insights required to drive success in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Women's Non-athletic Footwear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com