
Blogs
PW Consulting Forecasts Global Phenolic Molding Compound Market to Hit $3,128.18M by 2032, CAGR 4.85%
By pmarketresearch, 2026-09-16
Navigating the Future of the Global Phenolic Molding Compound Market: Strategic Insights for 2026 and Beyond
The phenolic molding compound (PMC) industry stands at a critical inflection point. As global manufacturing ecosystems oscillate between post-pandemic normalization, supply chain restructuring, and accelerating electrification, decision-makers across automotive, electrical, and industrial sectors require more than surface-level trend summaries. They need granular, forward-looking intelligence calibrated for execution. Our newly released Worldwide Phenolic Molding Compound Market study delivers exactly that: a rigorous, data-driven blueprint for navigating the 2026-2032 horizon.
This article outlines the strategic architecture of the report, interprets the macro trajectory shaping the industry, and demonstrates how procurement leaders, product developers, and competitive intelligence teams can leverage the findings to secure operational advantage in the coming years.
Market Trajectory: Decoding the 2026-2032 Growth Arc
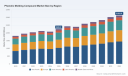
The global PMC market has demonstrated remarkable resilience through a volatile five-year cycle. Tracking historical performance from 2020 through the 2025 base year reveals a compound revenue stream that weathered raw material shocks, geopolitical trade friction, and shifting end-use demand. The overall market expanded from approximately 1,810.45 million USD in 2020 to a 2025 valuation of 2,245.5 million USD. While 2024 registered a temporary contraction to 2,082.15 million USD—a reflection of inventory corrections and regional demand recalibration—the subsequent rebound underscores the sector's structural durability and the latent pull from high-growth downstream applications.
Looking ahead, our forecast model projects the market to reach 2,430.68 million USD in 2026, accelerating through the end of the decade to touch 3,128.18 million USD by 2032. This trajectory translates to a forecasted CAGR of 4.85 percent across the 2026-2032 period. For strategic planners, this growth rate is not merely a headline figure; it signals a maturing but still expanding addressable space where incremental gains will be captured by firms that align product portfolios with regional price dynamics, regulatory shifts, and application-specific performance requirements.
Phenolic Resins Market
Crucially, the forecast accounts for divergent regional fundamentals. Raw material pricing volatility, exemplified by phenol markets in Q1 2026, illustrates why a uniform global strategy is insufficient. In Northeast Asia, phenol prices climbed to 1.01 USD/KG in March 2026, reflecting an 8.6 percent upward move from December driven by firm demand from phenolic resin manufacturing and rising cumene feedstock costs. Europe presents a contrasting picture: prices settled at 1.00 USD/KG, dipping 3.8 percent amid softening resin-sector demand and competitive Asian imports. North America registered 1.18 USD/KG, with a modest 0.8 percent decline against a backdrop of adequate local production and slightly weak resin demand. These price divergences directly influence margin structures, sourcing strategies, and regional capacity allocation—variables our report dissects in depth.
Report Architecture: What Decision-Makers Will Find Inside
The Worldwide Phenolic Molding Compound Market study is engineered for execution. Rather than offering static snapshots, the report maps the value chain from raw material inputs through compounding, molding processes, and end-use deployment. Every section is designed to answer the questions that keep strategy and operations leaders awake at night: where will volume concentrate, which product architectures will command pricing power, and how should organizations position against intensifying regional competition.
Granular Segmentation Analysis
The report deconstructs the market across multiple dimensions, enabling readers to isolate the sub-segments that align with their strategic mandates. A thorough type-level evaluation contrasts Novolac and Resol phenolic resin architectures, examining how their distinct curing behaviors, thermal profiles, and cost structures position them across compression, transfer, and injection molding workflows. Application-level analysis traces demand drivers across automotive, electrical and electronics, industrial components, aerospace and defense, and other emerging verticals. Each application segment is examined through the lens of performance thresholds, certification requirements, and substitution risk, providing a clear view of where growth will materialize and why.
Worldwide Phenolic Molding Compound Market
Regional Supply-Demand Equilibrium
Regional dynamics receive dedicated treatment, recognizing that PMC consumption is fundamentally shaped by local manufacturing footprints, logistics constraints, and raw material accessibility. The analysis maps production capacity distribution, evaluates regional pricing pressure points, and identifies how trade flows and localized resin demand are reshaping competitive positioning. Readers will gain a clear understanding of which regions function as volume engines, which are transitioning toward higher-value formulations, and where supply gaps may create tactical opportunities.
Competitive Landscape: Who Holds the Field and How the Board Is Shifting
Market concentration in the global PMC sector remains moderate, with the top three players collectively commanding approximately 24.15 percent of revenue and the top five holding 38.6 percent. This fragmented-but-consolidating structure creates both defensive moats and offensive openings. The report profiles the firms defining the competitive terrain, analyzing their geographic reach, technical differentiators, and strategic maneuvers.
- Sumitomo Bakelite Co., Ltd. (Tokyo, Japan) maintains a globally integrated footprint spanning production sites in Shizuoka, Nantong, North America, Belgium, and Singapore. Its portfolio emphasizes glass-fiber-reinforced and filler-modified phenolic compounds engineered for weight reduction, cost efficiency, and design flexibility. In March 2026, the company launched a new series of high-adhesion phenolic resins designed for diverse material interfaces, broadening its formulation capabilities for advanced molding applications. This followed a 2024 capacity expansion in Nantong, China, which added significant volume to its regional supply base.
- PLENCO (Plastics Engineering Company), headquartered in Sheboygan, Wisconsin, USA, delivers both novolac and resol phenolic resins alongside tailored molding compounds. Its value proposition centers on dimensional stability, electrical insulation, and heat resistance, serving industrial customers across compression, transfer, and injection molding processes.
- Bakelite Synthetics (Bakelite), with multiple US sites and global reach, emphasizes high-quality thermoset solutions for consumer goods, electrical, and industrial sectors. Its strategy hinges on consistent quality assurance and broad application coverage across mature and growing verticals.
- Chang Chun Plastics Co., Ltd. (Taiwan) manufactures the LONGLITE brand of heat-hardening phenolic molding compounds, formulated to meet customer-specific requirements in electrical, automotive, and industrial applications. Its regional strength in Asia positions it to capture demand tied to localized supply chain development.
- Resinoid Engineering Corporation (USA) specializes in phenolic compound raw goods and custom compounding, with a particular emphasis on high-temperature materials rated for continuous use above 400°F. Its aftermarket automotive focus makes it a notable player in performance-critical niche applications.
- Shengquan Group (China) ranks among the largest phenolic resin manufacturers globally, supplying resins for molding compounds to both domestic and international enterprises. Its scale and integrated supply chain provide a cost-advantaged base for regional and export markets.
- Kaihua Ruida Plastic-Tech Co., Ltd. (Zhejiang, China) produces UL-approved phenolic molding compounds and Bakelite powders, including the PF2D1-9600J series, engineered for heat resistance and dimensional stability across appliance, construction, and automotive sectors.
The report does not stop at profiles. It evaluates how recent capacity investments, product launches, and regional pricing pressures are reshaping share dynamics. Readers will understand which players are expanding into high-performance formulations, which are leveraging cost leadership in core segments, and where consolidation or partnerships may alter the competitive hierarchy over the forecast period.
Industry Dynamics: Raw Material Pressure, Regulatory Anchors, and Demand Realignment
No strategic assessment of the PMC market is complete without addressing the forces that constrain or enable growth. Raw material economics remain the most immediate variable. As noted, phenol pricing divergence across Northeast Asia, Europe, and North America in early 2026 illustrates how regional feedstock costs and import competition directly influence compounding margins. The report integrates these pricing signals into forward-looking cost scenarios, helping procurement teams anticipate squeeze points and evaluate hedging, dual-sourcing, or formulation-adaptation strategies.
Regulatory and certification frameworks further shape market access, particularly in electrical and electronics applications. UL certification remains active for a wide array of phenolic molding compounds supplied as pellets, covering critical performance metrics such as flame class, hot wire ignition (HWI), high current arc ignition (HAI), and relative thermal index (RTI). Compliance with these standards is not optional; it is a gating requirement for market entry in safety-sensitive segments. Our analysis maps how certification requirements influence product development timelines, testing costs, and competitive positioning, enabling firms to align R&D investment with the compliance pathways that matter most to their target customers.
Beyond inputs and regulation, demand-side realignment is accelerating. Automotive electrification, lightweighting mandates, and the continued migration toward higher-efficiency electrical components are shifting the composition of PMC consumption. At the same time, industrial and aerospace applications continue to prize the thermal stability, arc resistance, and mechanical integrity that phenolic architectures deliver. The report examines how these demand vectors interact with regional supply capacity, helping readers anticipate which application segments will see tightening supply, which will benefit from formulation innovation, and where substitution risk warrants proactive portfolio planning.
Strategic Value for 2026 Decision-Making
The 2026-2032 window is not a period for passive observation. It is a window in which capacity commitments, formulation roadmaps, and sourcing architectures will determine which organizations capture margin and which concede share. Our study is built to convert market complexity into actionable clarity.
- For procurement and supply chain leaders, the report provides the regional price context and supply-concentration data needed to negotiate from an informed position, evaluate supplier risk, and structure resilient sourcing networks amid divergent raw material trends.
- For product development and engineering teams, the segmentation analysis highlights where novolac versus resol architectures, reinforcement strategies, and certification pathways create differentiation opportunities—and where performance thresholds are becoming table stakes.
- For competitive intelligence and corporate strategy functions, the firm-level profiles and concentration metrics reveal who is expanding, who is innovating, and where acquisition, partnership, or capacity investment may shift the balance of power.
- For executive planning, the macro trajectory—anchored in rigorous historical data and a transparent 2026-2032 forecast—offers a defensible baseline for capital allocation, market-entry evaluation, and long-range revenue modeling.
Importantly, the report is structured to support scenario planning rather than rigid forecasting. Market conditions will evolve as feedstock costs fluctuate, regulatory standards tighten, and end-use demand shifts with macroeconomic cycles. By grounding strategy in a detailed, evidence-based view of the market's architecture, organizations can adjust with confidence rather than react under pressure.
Accessing the Full Intelligence Package
The Worldwide Phenolic Molding Compound Market study goes far beyond the macro trajectory and competitive overview outlined here. It delivers detailed segmentation assessments, regional supply-demand equilibria, firm-level strategic evaluations, raw material cost scenarios, and certification-impact analysis—all calibrated to support decisive action in 2026 and throughout the 2032 horizon. Core quantitative breakdowns, sub-segment growth rates, and granular regional revenue splits are integrated into the complete report, enabling readers to model outcomes specific to their portfolios and geographies.
Organizations that treat this market as a single homogeneous block will miss the nuanced opportunities hidden in type-specific demand, regional pricing divergence, and application-level performance requirements. The firms that thrive will be those that combine technical precision with strategic foresight. This report is designed to supply both.
To access the full dataset, segmentation matrices, competitive deep dives, and forward-looking scenario analysis, request the complete Worldwide Phenolic Molding Compound Market research. The full intelligence package is available through our research portal, where you can review the complete forecast model, examine detailed firm profiles, and align the findings directly with your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Phenolic Molding Compound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Liquid Cooling Fast Connection Market Hits $1.24B in 2025, Forecast 18.25% CAGR to $4.01B by 2032
By pmarketresearch, 2026-09-16
Powering the Liquid Cooling Revolution: Strategic Intelligence for the Fast Connection Solutions Market
The thermal management landscape is undergoing a structural transformation. As artificial intelligence workloads intensify and data center power densities surge, the industry's reliance on air cooling has reached its physical and economic limits. Direct liquid cooling (DLC) and immersion cooling have transitioned from niche alternatives to essential infrastructure, driving unprecedented demand for reliable, high-performance fluid transfer components. At the heart of this shift lies the fast connection solutions ecosystem, a critical enabler of leak-free, high-flow, and rapid deployment cooling architectures.
PW Consulting's latest worldwide market research on Fast Connection Solutions for Liquid Cooling Systems offers a comprehensive, data-driven lens into this rapidly expanding sector. This article outlines the strategic imperatives shaping the 2026 decision-making environment, contextualizes the macroeconomic trajectory of the market, and previews the analytical depth available in the full report. For executives, engineers, and investors navigating the thermal infrastructure value chain, understanding the connective tissue of liquid cooling is no longer optional—it is a competitive necessity.
The Macro Trajectory: A Market in Hypergrowth
The financial signals from the past half-decade tell a clear story of acceleration. Valued at approximately 585.3 million USD in 2020, the global fast connection solutions market for liquid cooling systems has expanded consistently, closing 2025 at an estimated 1,241.18 million USD. The forward-looking projection is equally compelling: revenues are expected to surpass the 1,498 million USD threshold in 2026 and climb steadily toward 4,012.79 million USD by 2032. This translates to a compound annual growth rate of 18.25 percent throughout the 2026–2032 forecast horizon, placing the sector among the fastest-growing subsegments within the broader thermal management and fluid handling industries.
Worldwide Liquid Cooling Couplings Market
Such sustained expansion is not merely cyclical. It is fundamentally anchored in the architectural redesign of computing and energy infrastructure. As hyperscale operators, colocation providers, and industrial facilities migrate toward high-density thermal solutions, the requirement for quick disconnects, blind-mate connectors, and push-to-connect fittings has evolved from a maintenance convenience to a core design specification. The market's trajectory reflects a structural reordering of priorities: downtime minimization, pressure-drop optimization, coolant purity, and interoperability now dictate component selection as much as upfront cost.
Technology Architectures and Segment Dynamics
The market's growth is distributed across three primary connection architectures, each addressing distinct operational requirements. Non-spill quick disconnects dominate the volume landscape, engineered to maintain fluid integrity during mating and unmating cycles—a non-negotiable feature in live data center environments where coolant leaks can trigger immediate operational shutdowns. Blind-mate connectors address the need for automated, alignment-tolerant connections in high-density rack deployments, while push-to-connect fittings serve applications prioritizing rapid manual installation and serviceability.
Material science continues to shape segment performance. Metallic solutions, particularly those fabricated from stainless steel, aluminum, and brass, maintain a dominant position due to their structural strength, thermal resilience, and compatibility with high-pressure cooling loops. Simultaneously, polymer-based valve and piping architectures—leveraging materials such as PVDF, PP-H, and PE100—are gaining traction for their ability to reduce weight, optimize flow characteristics, and deliver leak-tight performance in precision cooling circuits. This dual-material evolution reflects a broader industry trend: component selection is increasingly driven by application-specific thermal loads, coolant chemistry, and facility layout constraints rather than one-size-fits-all specifications.
Geographic Distribution and Application Diversification
Demand is not evenly distributed across the globe, nor is it concentrated in a single end-use vertical. The market exhibits a clear geographic weighting that mirrors regional data center build-out, semiconductor fab expansion, and electric vehicle infrastructure deployment. Supply chains, manufacturing footprints, and local compliance environments further differentiate regional demand patterns, creating both localized opportunities and cross-border procurement considerations for multinational operators.
On the application side, data centers and high-performance computing environments represent the most substantial demand driver, reflecting the direct correlation between AI accelerator density and liquid cooling adoption. Electric vehicle charging and energy storage infrastructure contributes a meaningful secondary demand stream, particularly where rapid coolant routing and field-serviceability are prioritized. Semiconductor manufacturing and medical/industrial equipment round out the application portfolio, each introducing specialized requirements around cleanliness, thermal stability, and connection reliability. The interplay between these verticals creates a diversified demand base that insulates the market from single-sector volatility while simultaneously raising the bar for component standardization.
Porter's Five Forces and Competitive Intensity
The competitive structure of the fast connection solutions market reflects a moderately concentrated landscape with room for both established incumbents and specialized challengers. Top-tier players collectively account for a substantial share of revenue, underscoring the importance of engineering reputation, certification portfolios, and long-term supply agreements in securing anchor contracts. At the same time, the fifth and sixth forces—substitute threats and new entrant potential—remain active. Standardization initiatives, modular cooling designs, and cross-vendor interoperability programs are gradually lowering switching costs, pressuring suppliers to compete on total cost of ownership, flow efficiency, and integration support rather than brand loyalty alone.
Bargaining power varies across the value chain. Large data center operators and hyperscale buyers wield considerable leverage in specifying connection standards and demanding compliance with open frameworks, while mid-tier integrators and facility contractors often rely on supplier-led engineering guidance to navigate fluid dynamics, pressure ratings, and material compatibility. Supplier power is moderated by a healthy pipeline of qualified manufacturers across North America, Europe, and Asia Pacific, though lead-time reliability, quality assurance, and post-installation support remain critical differentiators. The threat of substitutes is muted by the physical specificity of liquid cooling loops, yet the rise of polymer-based valve assemblies and hybrid metal-polymer designs keeps the innovation frontier active.
Competitive Landscape: Leaders and Strategic Moves
The market features a cohort of well-established industrial coupling manufacturers and thermal management specialists, each carving distinct positioning within the liquid cooling ecosystem. CPC (Colder Products Company) continues to advance its Everis series quick disconnect couplings, including blind-mate and high-flow variants engineered for electronics and data center thermal management, backed by rigorous reliability testing protocols. Parker Hannifin's Quick Coupling Division emphasizes dripless, non-spill performance under pressure, targeting server and rack cooling applications where thermal loads and uptime expectations are exceptionally high.
CEJN has strengthened its footprint in data center CDU applications by supplying high-flow, low-pressure-drop quick connect couplings, including OCP-compliant series developed alongside industry leaders to enable blind-mate and interchangeable deployment scenarios. Danfoss, through its Hansen thermal management line, focuses on optimized flow paths that reduce pressure drop while maintaining robust thermal control for electronics and liquid-cooled infrastructure. Stäubli brings clean-break, quick and dry disconnect solutions to both industrial and data center environments, with recent product introductions targeting compact liquid-cooled optical architectures where space constraints and high-temperature performance intersect.
Amphenol Industrial Operations supports a broad portfolio of liquid cooling quick disconnect connectors spanning blind-mate, quick-connect, and high-flow architectures, serving data centers, EV infrastructure, and energy storage systems. Gates Corporation advances full-flow quick disconnect couplings tailored for direct-to-chip liquid cooling, prioritizing secure and simple connections compatible with existing facility infrastructure. Specialty Manufacturing Co. contributes custom and standard thermal management quick disconnects, including the Universal Quick Disconnect series, with an emphasis on reliability in electronics cooling contexts. TITAN Fluid has emerged as a notable player offering stainless steel quick disconnect couplings that align with OCP and NVIDIA specifications, targeting zero-downtime connection requirements in high-performance data centers. Motivair, operating under Schneider Electric, supplies Everis quick connects and Dynamic Cold Plates designed for seamless water transfer in direct-to-chip cooling architectures.
Recent product and partnership activity underscores how actively this competitive field is evolving. In early 2026, GF and Rittal announced a full-scope polymer cooling infrastructure solution, featuring a patented dual-ball valve in PVDF designed for direct-to-chip liquid cooling with optimized flow paths and leak-tight operation. Around the same period, Stäubli unveiled a compact quick disconnect variant aimed at liquid-cooled optical modules during a major industry keynote, highlighting the push toward miniaturization in high-density photonic cooling. Earlier initiatives included trade show showcases and technical publications addressing leakage-free connections for battery energy storage systems, low-pressure-loss coupling demonstrations for semiconductor and data center cooling, and engineering guidance on reducing pressure drops to improve thermal management energy efficiency. These moves illustrate a market where product differentiation, standards alignment, and application-specific validation are accelerating simultaneously.
Regulatory and Standards-Driven Demand Catalysts
External mandates and industry guidelines are acting as powerful adoption accelerants. Updated thermal guidelines for data processing environments and dedicated liquid cooling recommendations have codified the viability of higher supply temperatures and energy-efficient loop designs, reinforcing the case for liquid cooling in high-density server environments. Complementary standards defining data center efficiency metrics place cooling system performance under continuous scrutiny, while regional energy efficiency mandates increasingly favor infrastructure choices that support lower power usage effectiveness targets. In parallel, the broader shift toward direct liquid cooling and immersion cooling is being driven by AI and HPC power density increases, with documented energy savings potential relative to traditional air cooling and the ability to support ultra-low facility efficiency ratios. These dynamics do not merely influence procurement preferences; they reshape engineering specifications, architectural planning, and capital allocation timelines across the digital infrastructure sector.
Worldwide Fast Connection Solutions for Liquid Cooling System Market
What the Full Report Delivers
The PW Consulting Worldwide Fast Connection Solutions for Liquid Cooling System Market study is designed to convert this complex landscape into actionable intelligence. Beyond the headline growth trajectory, the report deconstructs historical performance, forecast pathways, and the operational variables that will determine market outcomes through 2032. It provides a structured assessment of connection architecture demand, end-use application priorities, and regional demand weighting, while mapping the strategic behavior of leading manufacturers and emerging participants.
Practitioners will find detailed analysis of product development directions, materials and flow-optimization trends, and the regulatory and standards environment shaping specification requirements. The research also evaluates competitive positioning, partnership activity, and the practical implications of interoperability frameworks for supply chain planning and product selection. For organizations evaluating market entry, capacity expansion, component standardization, or supplier negotiation strategy, the report offers a decision-ready framework that connects market-level signals with segment-level execution considerations.
Strategic Takeaways for 2026 Decision-Makers
As liquid cooling transitions from specialized deployment to mainstream infrastructure, fast connection solutions have become a defining component of thermal reliability, serviceability, and system efficiency. The market's growth path reflects more than rising compute demand; it signals a fundamental rethinking of how facilities are designed, maintained, and scaled. Decision-makers who align their product roadmaps, procurement standards, and partnership strategies with this evolving reality will be better positioned to capture value in a market where performance, compliance, and interoperability increasingly determine competitive outcomes.
To obtain the full dataset, granular segmentation analysis, forecast breakdowns, and complete competitive profiles, we invite you to explore the complete PW Consulting market report. The detailed intelligence contained within provides the precision required to translate macro trends into executable strategy across engineering, commercial, and investment functions.
For detailed analysis of this topic, please visit the official page: Worldwide Fast Connection Solutions for Liquid Cooling System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide High Temp Thermocouples Market Hits $582.45 Million in 2025 to Reach $829.45 Million by 2032
By pmarketresearch, 2026-09-16
Navigating the Heat: Strategic Intelligence for the Worldwide High Temperature Thermocouples Market (2026-2032)
In the complex landscape of industrial instrumentation, precision is not merely a technical specification; it is a critical determinant of operational safety, efficiency, and profitability. As global industries push the boundaries of thermal processing, the demand for reliable temperature sensing solutions has never been more paramount. PW Consulting is proud to unveil our latest comprehensive study: the Worldwide High Temperature Thermocouples Market analysis. This report is designed not just as a collection of numbers, but as a strategic compass for stakeholders navigating the thermal instrumentation sector through 2032.
For executives, investors, and strategic planners, understanding the trajectory of this market is essential. The ability to measure extreme temperatures accurately underpins everything from semiconductor fabrication to aerospace propulsion. Our latest research provides a granular yet holistic view of where the market has been, where it stands today, and where it is headed. This article serves as an executive overview, highlighting the strategic value embedded within our full dataset and analysis, while outlining the broader industrial context shaping the competitive landscape.
Macro Growth Trajectory and Market Valuation
The economic narrative for high temperature thermocouples is one of steady, resilient expansion. Our analysis tracks historical performance from 2020 through the base year of 2025, projecting forward into the forecast period ending in 2032. After demonstrating robust recovery and growth in the early 2020s, the market stabilized around a valuation of approximately 582.45 Million USD in 2025. Looking ahead, the market is poised for consistent valuation growth, with projections indicating a rise to 647.47 Million USD in 2026 and climbing steadily toward 829.45 Million USD by the end of the forecast window in 2032.
Worldwide High Temperature Thermocouples Market
This growth trajectory is underpinned by a Compound Annual Growth Rate (CAGR) of 5.17 Percent. While this figure indicates stability rather than explosive volatility, it reflects the specialized nature of the industry. High temperature thermocouples are critical components, not discretionary spend. Consequently, growth is tied closely to foundational industrial output and technological upgrades in extreme environments. For decision-makers, this suggests a market characterized by predictable demand cycles, where strategic investment should focus on long-term capacity planning and R&D rather than short-term market timing. The currency valuation remains standardized in USD, facilitating global comparison across regions and segments for international stakeholders.
Segmentation Landscape Overview
The market is diversified across three primary dimensions, each offering distinct opportunities and challenges for players in the value chain. Understanding the interplay between type, application, and geography is crucial for targeted strategy development.
Mineral Insulated Thermocouple Cables Market
- The market is divided by type into three key categories: Noble Metal Thermocouples, Refractory Metal Thermocouples, and High-Temp Base Metal Thermocouples. Noble metals typically dominate high-end precision applications, while refractory metals serve extreme thermal environments.
- Application segmentation reveals heavy reliance on core industrial sectors. Key verticals include Iron and Steel Manufacturing, Aerospace and Defense, Glass and Ceramics, Semiconductor Processing, and Power Generation. Each sector imposes unique durability and accuracy requirements on sensor assemblies.
- Regional analysis covers major global theaters, including Asia Pacific, North America, Europe, Latin America, and the Mideast and Africa. While specific regional shares fluctuate based on manufacturing shifts and infrastructure investment, the global footprint remains widespread, with industrial hubs driving localized demand.
It is important to note that the specific revenue breakdowns and percentage splits within these segments are detailed exclusively in the full report. These granular figures are critical for identifying niche growth pockets and assessing relative market penetration potential, but they require the depth of our full proprietary modeling to interpret correctly.
Competitive Dynamics and Industry Leaders
The competitive landscape is moderately concentrated, with a competitive environment that rewards technical specialization and supply chain reliability. Our data indicates a CR3 of approximately 38.45 Percent and a CR5 of 52.12 Percent. This structure suggests that while market leaders hold significant sway, there is ample room for specialized players to carve out niches through innovation and customization.
Several key companies define the current operational standard. Omega Engineering, a subsidiary of Spectris plc, offers an extensive range of high temperature options including exotic metal and Super OMEGACLAD probes designed for demanding industrial and laboratory applications. Similarly, WIKA Alexander Wiegand SE & Co. KG in Germany manufactures high-temperature thermometers and thermocouples such as the TC82 and TC80 series, targeting extreme high temperature measurement in industrial processes. Watlow, based in St. Louis, provides high-heat thermocouples including surface mount and multipoint assemblies for demanding thermal applications in industrial heating systems.
Other significant contributors include Pyromation, which specializes in thermocouples, RTDs, and thermowells for industrial process control, and Thermo Electric Company, Inc., which has been manufacturing temperature measurement solutions optimized for high temperature environments since 1941. Nanmac stands out as a world leader in high temperature thermocouples and RTDs with a focus on extreme environment performance. Conax Technologies offers high temperature thermocouples with various termination styles and sealing solutions for harsh industrial conditions. International players like Okazaki Manufacturing Company produce sheathed thermocouples specifically engineered for high temperature applications, while Tempsens Instruments manufactures high temperature variants for industries such as cement, glass, petrochemical, and steel.
Further down the specialized chain, Marlin Manufacturing produces high-quality industrial thermocouples and custom assemblies, particularly for semiconductor applications. ARi Industries, Inc. produces standard and custom high temperature and ultra high temperature thermocouples including mineral insulated types. Eustis/Pyrocom manufactures industrial thermocouples for high temperature requirements in metal, glass, oil and gas, and power generation sectors.
Recent developments highlight the active nature of this competitive field. In January 2025, Pyromation participated in the International Production and Processing Expo, showcasing temperature sensors including thermocouples. Around the same time, Ashcroft announced in March 2025 that additional models of RTDs and thermocouples are now FM approved for use in hazardous locations, a critical certification for safety-sensitive markets. Looking toward mid-2026, Temprel is scheduled to exhibit temperature measurement solutions including high temperature capabilities at Space Tech Expo 2026, signaling continued innovation in the aerospace sector.
Regulatory and Technical Frameworks
Any strategic assessment of this market must account for the regulatory and technical standards that govern product specification and acceptance. Compliance is not optional; it is a barrier to entry and a baseline for trust. ASTM E839-23 provides standard test methods for sheathed thermocouples and sheathed thermocouple cable used in high temperature applications. This standard is vital for quality assurance in procurement. Additionally, IEC 60584-1 and ASTM E230/E230M define accuracy classes and EMF-temperature relationships for standardized thermocouples including high temperature types. These regulations ensure interoperability and precision across different manufacturers and systems.
On the materials front, the industry relies heavily on advanced metallurgy. High temperature thermocouples, particularly Types R, S, and B, rely on platinum-rhodium alloys as the primary core component for operation above 1000 Degrees Celsius. The precious metal aspect introduces cost volatility linked to raw material markets. Analysts Insights noted in October 2025 that the Precious Metal Thermocouple market, encompassing platinum-rhodium types, was valued at USD 264 Million in 2024 and is projected to reach USD 363 Million by 2032. This sub-segment dynamic is a crucial input for cost modeling and pricing strategies in the broader high temperature market.
Market Drivers and Strategic Opportunities
Demand for high temperature thermocouples is driven by requirements for precise temperature control in semiconductor fabrication and high-temperature industrial processes. As semiconductor nodes shrink and processing temperatures increase, the tolerance for error diminishes. Similarly, the resurgence in heavy industry and the push for advanced materials in aerospace and defense create sustained pressure on the supply chain to deliver sensors that can withstand harsher conditions for longer durations.
Strategic opportunities exist at the intersection of these demands. Companies that can offer not just the sensor, but the integration expertise and certification compliance, will capture greater value. The shift toward automation in power generation and the constant upgrades in glass and ceramics manufacturing provide additional avenues for growth. However, success depends on accurate forecasting of capacity needs and raw material sourcing, specifically regarding platinum and rhodium.
Value of the Full Study
While this overview outlines the structural pillars of the market, the complete PW Consulting report offers the actionable intelligence required to execute strategy. The full document provides detailed revenue breakdowns by region and type, allowing for precise market sizing for specific business units. It includes comprehensive competitor profiles, analyzing market share stability and strategic moves. Furthermore, the forecast models incorporate sensitivity analysis regarding raw material costs and regulatory changes, giving stakeholders a range of scenarios rather than a single point estimate.
For procurement specialists, the report identifies supply chain concentration risks. For investors, it highlights growth segments beyond the headline CAGR. For product developers, it maps the regulatory landscape to prevent costly compliance errors. The data regarding segment splits and specific regional valuations is curated to support these specific use cases, providing a layer of detail that general market summaries cannot match.
To access the complete dataset, including the specific regional revenue figures, type-specific growth rates, and detailed competitor benchmarking, we invite you to explore the full Worldwide High Temperature Thermocouples Market research on our website. Understanding the heat map of this industry requires more than just surface temperature readings; it requires deep thermal imaging. Let PW Consulting provide the clarity you need to make informed decisions in this critical sector.
For detailed analysis of this topic, please visit the official page: Worldwide High Temperature Thermocouples Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Mobile UC&C Hits $27.78B in 2025, Forecast to $85.99B by 2032 at 17.52% CAGR
By pmarketresearch, 2026-09-16
Navigating the Mobile Unified Communications and Collaboration Landscape: Strategic Imperatives for 2026 and Beyond
The enterprise communication paradigm has undergone a fundamental transformation. What began as a response to remote work requirements has matured into a permanent architectural shift in how organizations connect, collaborate, and serve customers. Mobile unified communications and collaboration (UCC) is no longer a peripheral capability—it is the backbone of modern enterprise operations. As we enter 2026, leadership teams face a market characterized by accelerating consolidation, AI-driven feature expansion, and intensifying regulatory scrutiny. Understanding the trajectory of this market is not merely an exercise in forecasting; it is a strategic necessity for technology procurement, competitive positioning, and long-term organizational resilience.
Our latest Worldwide Mobile Unified Communications and Collaboration Market study delivers the comprehensive intelligence that executives, investors, and technology strategists require to navigate this complex environment. Drawing on extensive primary research, supplier interviews, and granular demand-side analysis, this report maps the market from its historical foundations through a detailed forecast period extending to the end of the decade. What follows is an overview of the strategic insights contained within, designed to demonstrate the report's value as a decision-support instrument.
The Macro Trajectory: A Market Defined by Sustained Acceleration
The numbers tell a story of relentless growth. From a baseline in the mid-2020s, the global mobile UCC market has expanded at a pace that has consistently outpaced traditional enterprise software categories. Historical data from the early 2020s through the present reveals a compound annual growth rate that underscores the structural demand underpinning mobile collaboration tools. The market has surpassed significant thresholds, with total revenue climbing from approximately $11.8 billion in 2020 to over $27.7 billion by 2025.
Worldwide Mobile Unified Communications and Collaboration Market
Looking forward, the trajectory remains steep. The study projects that market expansion will continue at a compound annual growth rate of 17.52 percent across the forecast horizon, with revenues projected to approach $33.4 billion in 2026 and steadily climb toward the $86 billion mark by 2032. This sustained growth reflects more than cyclical recovery; it signals the deep integration of mobile UCC capabilities into enterprise workflows, customer engagement models, and regulatory compliance frameworks. Decision-makers must understand that this growth is not diffuse—it is concentrated around specific solution categories and vertical applications that our report dissects in detail.
Such magnitude of expansion carries profound implications. Infrastructure investment, vendor partnerships, licensing strategies, and workforce training must all be calibrated against a market that is growing nearly twice as fast as many adjacent technology segments. Organizations that fail to align their communication architectures with this growth trajectory risk falling behind competitors who are leveraging mobile collaboration as a productivity and innovation multiplier.
Strategic Segmentation: Where Growth Is Concentrated
The headline figures, while compelling, only tell part of the story. The true strategic value of our analysis lies in its breakdown of the market across multiple dimensions—solution types, end-user verticals, and geographic regions—each revealing distinct demand drivers, competitive intensity, and adoption barriers.
Solution-Level Dynamics
Within the solution landscape, mobile video conferencing and unified messaging represent the largest revenue pools, reflecting the enduring demand for rich, synchronous collaboration and the continued migration of legacy messaging systems to cloud-native platforms. Presence and mobility solutions, while smaller in absolute terms, serve as critical enablers for workforce agility, allowing organizations to maintain context-aware collaboration regardless of device or location. Contact center as a service (CCaaS) and audio conferencing round out the solution mix, with the former experiencing particular momentum as enterprises rebuild customer engagement infrastructures around digital-first, mobile-optimized experiences.
The report does not merely list these categories; it evaluates them. Our analysis examines the pricing dynamics, feature differentiation, integration requirements, and adoption curves that define each solution segment. For procurement leaders, this means being able to identify which capabilities warrant premium investment and which can be sourced from commoditized providers. For product strategists, it means understanding where feature gaps are likely to emerge and where consolidation pressure will intensify.
Vertical-Specific Demand Patterns
No enterprise communication strategy exists in a vacuum. Different industries face different regulatory environments, workforce structures, and customer engagement models, all of which shape their mobile UCC requirements. The IT and telecommunications sector remains the largest consumer of mobile UCC capabilities, driven by internal collaboration needs and the requirement to support customer-facing communication infrastructure. The BFSI sector follows closely, with compliance mandates, secure communication requirements, and the need for seamless omnichannel customer interactions driving significant investment.
Healthcare organizations are increasingly adopting mobile UCC platforms to support telemedicine workflows, clinician collaboration, and patient engagement—all while navigating stringent data protection regulations. Government and public sector entities face their own unique pressures, including the need for sovereign infrastructure, disaster recovery capabilities, and secure inter-agency communication. Retail and manufacturing organizations are leveraging mobile UCC to connect distributed workforces, streamline supply chain coordination, and enhance customer service operations. Educational institutions round out the vertical landscape, with hybrid learning models driving sustained demand for mobile video and messaging capabilities.
Our report provides a detailed examination of each vertical, analyzing not just current spend levels but the underlying drivers, barriers, and growth catalysts that will shape adoption over the forecast period. This vertical lens is essential for organizations seeking to benchmark their own communication strategies against industry peers and for vendors aiming to refine their go-to-market motions.
Geographic Dispersion and Infrastructure Realities
The global nature of this market means that regional dynamics play an outsized role in shaping both demand and competitive intensity. Our analysis segments the market across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, revealing how infrastructure maturity, regulatory environments, and enterprise digitization rates influence adoption patterns.
North America and Europe represent mature, high-spend markets where competition is fierce and differentiation increasingly hinges on AI capabilities, ecosystem integration, and regulatory compliance. Asia Pacific presents a high-growth opportunity shaped by rapid enterprise digitization, expanding mobile broadband coverage, and the emergence of local champions alongside global vendors. Latin America and the Middle East and Africa reflect markets in earlier stages of adoption, where infrastructure development—particularly around broadband capacity and mobile network evolution—will determine the pace of UCC deployment.
Decision-makers must be careful not to treat these regions as monolithic. Our report provides the granularity needed to understand the specific demand drivers, competitive dynamics, and infrastructural prerequisites that define each regional market. Organizations operating across multiple geographies will find this analysis invaluable for tailoring their communication strategies to local realities while maintaining global operational coherence.
Competitive Dynamics: Navigating a Consolidating Field
The competitive landscape for mobile UCC is characterized by a mix of established platform giants, specialized UCaaS providers, and infrastructure players seeking to extend their relevance into the collaboration layer. The report includes detailed profiles of the key companies shaping this market, examining their product portfolios, partnership strategies, and recent strategic moves.
Microsoft Corporation continues to leverage its Microsoft 365 ecosystem to embed Teams as a comprehensive mobile UCC platform, with recent feature releases— including the bundling of intelligent recaps and sentiment analysis for premium subscribers—demonstrating the company's commitment to differentiating through AI. Cisco Systems, Inc. maintains a strong position through Webex and Unified Communications Manager, with strategic acquisitions such as Lightico expanding its contact center capabilities into e-signature and document collection workflows. Zoom Video Communications, Inc. remains a formidable force in mobile video and collaboration, with its Zoom Workplace and Zoom Phone offerings continuing to attract enterprises seeking streamlined, high-quality video experiences.
RingCentral, Inc. has positioned its cloud-based RingCentral MVP platform as a comprehensive UCaaS solution, while its recent unveiling of the AIR Pro agentic voice AI platform signals a strategic push into AI-driven customer engagement. 8x8, Inc. offers its XCaaS platform as a unified cloud delivery model spanning communications, contact center, and collaboration, optimized for mobile access. Avaya Inc. and Mitel Networks Corporation continue to serve enterprise and hybrid environments with their respective experience platforms and hybrid UC solutions, each emphasizing continuity and control for organizations navigating mixed deployment models.
Alcatel-Lucent Enterprise, Verizon Communications Inc., Google LLC, NEC Corporation, and Nextiva round out the competitive field, each bringing distinct positioning—from enterprise networking integration and mobile connectivity bundling to workspace collaboration suites and all-in-one UCaaS platforms. The report provides a comparative analysis of these players, evaluating their market share positions, strategic differentiation, and the implications of their recent developments for enterprise buyers.
A critical insight from our competitive analysis is the high level of market concentration. The data indicates that a relatively small number of players command a significant share of total market revenue, with the top three firms accounting for over 44 percent of the market and the top five collectively capturing nearly 60 percent. This concentration has important implications for procurement leverage, vendor risk management, and the pace of innovation. Enterprise buyers must understand how concentration affects pricing dynamics, integration ecosystems, and the likelihood of future consolidation.
Regulatory and Infrastructure Currents Shaping the Market
No analysis of the mobile UCC market would be complete without addressing the regulatory and infrastructural forces that are reshaping the operating environment. In 2024, regulatory reclassification efforts by the FCC regarding broadband Internet access services introduced new complexities, though subsequent legal challenges have created uncertainty about the ultimate regulatory framework. Simultaneously, the transformation of the Disaster Information Reporting System from voluntary to mandatory compliance in 2025 has raised the bar for provider resilience and reporting obligations, with direct implications for UCaaS and mobile communication providers.
On the infrastructure front, network capacity expansions are enabling the multi-gigabit speeds that mobile UCC applications increasingly require. Spectrum expansions, high-split architectures, Distributed Access Architecture deployments, and DOCSIS 4.0 rollouts are all contributing to the broadband foundation that supports seamless mobile collaboration. At the same time, European telecom operators are investing in sovereign infrastructure pathways, including evolution paths for SIP applications, unified communications, and IP Multimedia Subsystem components, in response to data sovereignty and security concerns. These developments are not peripheral—they directly influence the performance, compliance posture, and total cost of ownership of mobile UCC deployments.
The FCC's ongoing efforts to identify and make available mid-band spectrum for mobile broadband and advanced wireless services further underscore the infrastructural dependencies that underpin mobile UCC performance. Our report contextualizes these regulatory and infrastructure developments within the broader market dynamics, helping decision-makers anticipate compliance requirements, assess infrastructure readiness, and evaluate vendor claims about network performance and security.
What the Full Study Delivers: A Roadmap for Informed Decision-Making
The Worldwide Mobile Unified Communications and Collaboration Market study is designed to serve as a comprehensive decision-support instrument for a wide range of stakeholder groups. Technology procurement leaders will find the detailed segmentation analysis essential for aligning license investments with actual usage patterns and vertical-specific requirements. Competitive intelligence teams will benefit from the granular profiling of key players, recent developments tracking, and market concentration metrics that reveal the structural dynamics of the competitive field. Investor and financial analysts will find the historical-to-forecast revenue trajectory, CAGR analysis, and regional breakdowns critical for modeling growth scenarios and assessing market opportunity.
Push-To-Talk Market
Beyond these core analytical components, the report includes actionable strategic recommendations, demand-side survey insights, and scenario-based forecasting that account for varying assumptions about macroeconomic conditions, regulatory outcomes, and technology adoption rates. The study also examines the impact of agentic AI platforms, hybrid deployment models, and sovereign infrastructure requirements on the competitive positioning of major vendors—topics that are rapidly becoming central to enterprise UCC strategy discussions.
Every section of the report is built on primary research, validated supplier data, and rigorous demand modeling. The result is a resource that goes beyond descriptive market sizing to provide the analytical depth required for strategic planning, budget allocation, and competitive positioning.
Why 2026 Demands Deeper Intelligence
As we move deeper into 2026, the window for passive observation of the mobile UCC market has closed. Organizations are making procurement decisions that will shape their communication architecture for years to come. Vendors are executing product roadmaps and acquisition strategies that will determine competitive positioning for the remainder of the decade. Regulatory frameworks are evolving in ways that will affect compliance costs, data handling requirements, and network performance expectations.
In this environment, surface-level market awareness is insufficient. Decision-makers need access to detailed segmentation data, competitive benchmarking, vertical-specific adoption analysis, and forward-looking scenario modeling. They need to understand not just where the market is headed, but why it is headed there, what the key variables are, and how different strategic choices will play out across varying conditions.
Our full study provides this depth. It delivers the granular data, the competitive intelligence, and the strategic framing that executives need to make informed, confident decisions. The summary insights presented here offer a glimpse of the analysis contained within, but the complete picture—complete with detailed segmentation breakdowns, supplier profiles, regional dynamics, and forecast scenarios—awaits those who engage with the full report.
To access the complete Worldwide Mobile Unified Communications and Collaboration Market study, including all segmentation data, competitor profiles, regional analyses, and strategic recommendations, visit our research portal. The full intelligence is available now, and the strategic advantage it provides begins with a single decision to dig deeper.
For detailed analysis of this topic, please visit the official page: Worldwide Mobile Unified Communications and Collaboration Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global AI Infrastructure Market to Hit $1.68T by 2032, 27.14% CAGR
By pmarketresearch, 2026-09-16
Navigating the 2026 AI Infrastructure Supercycle: Strategic Intelligence for Enterprise Decision-Makers
The global artificial intelligence infrastructure market has entered a phase of unprecedented expansion, fundamentally reshaping how enterprises approach technology investment, capital allocation, and competitive positioning. As organizations worldwide race to deploy generative AI workloads, build sovereign cloud capabilities, and optimize inference economics, the need for rigorous, forward-looking market intelligence has never been more critical. Our latest Worldwide Modern AI Infrastructure Market research offers a comprehensive analytical framework designed specifically to guide executive decision-making through the 2026-2032 forecast period.
Worldwide AI GPU Market
The market has demonstrated remarkable momentum over the past five years, with total revenue climbing from $142.8 billion in 2023 to $312.6 billion in 2025. This trajectory reflects not merely cyclical demand but a structural transformation in how computational resources are procured, deployed, and monetized. Looking ahead, the forecast period projects continued acceleration, with market valuation expected to surpass $1 trillion by the end of the decade. The compound annual growth rate of 27.14 percent underscores the intensity of this expansion, yet raw figures alone tell only part of the story. The real strategic challenge lies in understanding the underlying composition of growth, the competitive forces shaping supply dynamics, and the operational constraints that will determine which organizations capture value and which face costly delays.
This research brief serves as an introduction to our full market study. It outlines the analytical architecture of the report, highlights the competitive and regulatory forces currently reshaping the landscape, and demonstrates how executives can translate granular intelligence into actionable capital and procurement strategies. As you review the insights that follow, consider how systematic exposure to these dynamics will influence your organization's infrastructure roadmap, vendor selection criteria, and risk mitigation frameworks.
Market Architecture: Component, Deployment, and Regional Dynamics
A rigorous understanding of the modern AI infrastructure market requires disaggregating revenue flows across three fundamental dimensions: component categories, deployment models, and geographic distribution. Each dimension reveals distinct growth drivers, pricing pressures, and procurement considerations that collectively determine the shape of enterprise investment portfolios.
Within the component landscape, compute hardware dominates the revenue composition, reflecting the relentless demand for accelerator chips, high-performance networking equipment, and specialized data storage systems. Organizations building training clusters or scaling inference endpoints must navigate a complex procurement environment where silicon availability, interconnect bandwidth, and storage throughput intersect with total cost of ownership calculations. High-performance networking has emerged as a critical enabler, as the latency and throughput requirements of distributed AI workloads place unprecedented strain on cluster interconnects. Data storage systems, while representing a smaller share of overall revenue, are experiencing structural growth as enterprises architecting retrieval-augmented generation pipelines and vector databases require low-latency, high-capacity storage layers that can sustain continuous inference operations.
The deployment dimension further clarifies where capital is flowing and where innovation is concentrated. Hyperscale and public cloud environments command the largest share of infrastructure spending, driven by the scale economics of major cloud providers and the flexibility they offer enterprises migrating AI workloads without upfront capital expenditure. Enterprise data centers represent a significant and growing segment, as organizations with sensitive data requirements, regulatory constraints, or existing on-premises investments pursue hybrid architectures that balance performance with data sovereignty. Edge AI infrastructure, while currently the smallest deployment category by revenue, is attracting strategic attention from organizations seeking to reduce inference latency, mitigate cloud egress costs, and deploy AI capabilities in environments where continuous connectivity cannot be guaranteed.
Geographic distribution reveals the uneven pace of infrastructure buildout across global markets. North America continues to anchor a substantial portion of worldwide revenue, supported by concentrated hyperscaler investment, mature semiconductor supply chains, and a dense ecosystem of AI-native startups. Asia Pacific represents the second-largest regional revenue pool, fueled by sovereign AI initiatives, rapidly expanding cloud capacity, and the manufacturing ecosystem that underpins global chip production. Europe, the Middle East and Africa, and Latin America each present distinct adoption profiles shaped by local regulatory frameworks, energy availability, and the maturity of domestic cloud and colocation markets. Our full report maps these regional dynamics in detail, providing the granular context necessary to calibrate market entry strategies, partnership decisions, and localized procurement plans.
Competitive Intensity and Vertical Specialization
The competitive landscape of the modern AI infrastructure market is defined by a small number of dominant players commanding significant market concentration, alongside a growing cohort of specialized firms advancing adjacent layers of the stack. Understanding this structure is essential for executives evaluating supplier risk, negotiating long-term contracts, and anticipating shifts in pricing and availability.
At the foundation of the compute layer, NVIDIA Corporation maintains a commanding position through its integrated portfolio of graphics processing units, networking technologies, and software ecosystems that have become de facto standards for large-scale AI training and inference. The company's product roadmap, including successive generations of accelerator architectures and high-speed interconnect solutions, continues to set performance benchmarks that shape enterprise procurement cycles. Advanced Micro Devices Corporation has carved out a meaningful competitive position through its MI-series accelerators and high-performance computing solutions, offering alternative silicon paths for organizations seeking to diversify their supplier base or optimize workload-specific performance. Intel Corporation continues to advance its AI infrastructure capabilities through accelerator architectures, central processing unit platforms, and specialized inference technologies designed for data center environments.
Networking and interconnect technologies represent another critical competitive frontier. Broadcom Inc. supplies high-speed networking chips, application-specific integrated circuits, and custom silicon that are indispensable for interconnecting GPU clusters at hyperscale. Arista Networks provides high-speed Ethernet switching platforms engineered for ultra-low latency AI cluster interconnects, addressing the stringent networking requirements of distributed training workloads. These suppliers operate at the intersection of performance and reliability, where incremental improvements in throughput or latency can translate into material differences in training time and inference responsiveness.
On the cloud and infrastructure services side, hyperscale providers dominate the deployment landscape. Amazon Web Services delivers AI infrastructure through elastic compute instances, custom accelerator chips, and managed services that streamline model training and deployment. Microsoft Corporation's Azure platform provides extensive GPU capacity, custom silicon investments, and integrated cloud services tailored to enterprise and hyperscale AI workloads. Alphabet Inc.'s Google Cloud Platform leverages custom tensor processing unit accelerators and infrastructure optimized for large-scale training and inference. Oracle Corporation has expanded its cloud infrastructure capacity through significant financing commitments, targeting major AI customers with bare-metal GPU clusters and dedicated cloud services. These hyperscalers collectively represent a defining force in infrastructure economics, influencing pricing, availability, and the pace at which new capabilities reach enterprise customers.
Specialized providers are also reshaping the market. TSMC, as the leading semiconductor foundry, manufactures advanced AI chips and accelerators for multiple industry participants, making it a critical node in the global supply chain. CoreWeave operates as a specialized GPU cloud provider, offering high-density infrastructure clusters optimized for training and inference workloads. Vertiv Holdings Co. delivers power management, thermal management, and liquid cooling solutions that address the intensifying energy and cooling demands of high-density AI data centers. Equinix enables private and hybrid AI infrastructure deployments through global colocation and interconnection services. Cerebras Systems develops wafer-scale accelerators designed for large-scale model training, while Groq focuses on inference-optimized language processing units engineered for high-speed deployment scenarios.
Recent developments underscore the velocity of competitive and strategic activity. In early 2026, four major hyperscalers signaled combined capital expenditure guidance approaching $650-690 billion for the year, concentrated heavily on AI infrastructure and data center expansion. NVIDIA advanced significant investments and GPU supply agreements with leading AI models developers as part of major infrastructure buildouts. Oracle announced plans to raise substantial debt and equity financing in 2026 to expand cloud infrastructure capacity serving prominent AI customers. These capital commitments signal a multi-year construction and procurement cycle that will influence equipment availability, pricing dynamics, and the strategic positioning of infrastructure providers for years to come.
Market Dynamics: Power, Regulation, and Efficiency Imperative
Beyond component architecture and competitive positioning, the modern AI infrastructure market is being reshaped by structural constraints and regulatory developments that carry direct implications for deployment timelines, cost structures, and strategic risk. Executives who internalize these dynamics early will be better positioned to navigate procurement delays, negotiate favorable terms, and align infrastructure plans with evolving compliance requirements.
Power availability has emerged as the most consequential bottleneck for AI data center deployment. Electrical infrastructure constraints, including large power transformers with multi-year lead times and grid interconnection queues that now exceed 2,100 gigawatts, have created a capacity shortfall that threatens to delay a significant portion of planned 2026 capacity into 2028. This reality forces organizations to confront the fact that AI infrastructure planning can no longer be divorced from energy strategy. Executives must evaluate site selection criteria, power procurement contracts, and the potential role of on-site generation or advanced cooling technologies as integral components of infrastructure roadmaps rather than peripheral considerations.
Material intensity further compounds deployment complexity. Each megawatt of AI data center capacity requires approximately 27 tons of copper for wiring and cooling systems, placing additional strain on global supply chains already navigating constraints in power infrastructure components. These material requirements interact with lead times, logistics costs, and geopolitical supply chain risks, creating a procurement environment where early contracting and diversified sourcing strategies can yield meaningful competitive advantage.
Regulatory frameworks are simultaneously reshaping the market landscape. The U.S. Bureau of Industry and Security maintains export controls on advanced computing integrated circuits and, for the first time, on frontier AI model weights exceeding 10 to the 26th power of operations. These controls require licenses for transfers involving potential military-intelligence end uses in designated country groups, introducing compliance complexity for organizations engaged in cross-border collaboration, model sharing, or hardware deployment. Updated export control measures also address advanced computing items and AI model weights with case-by-case licensing provisions for certain shipments, creating a regulatory environment that demands ongoing monitoring and adaptive procurement strategies.
Standardization efforts provide additional context for infrastructure evaluation. The ISO/IEC 30134 series defines key performance indicators for data center resource efficiency, including power usage effectiveness, water usage effectiveness, and carbon usage effectiveness. These metrics are increasingly used to benchmark the energy consumption of AI-driven facilities, influencing procurement criteria, investor expectations, and regulatory scrutiny. Organizations that embed efficiency metrics into their infrastructure planning and vendor evaluation processes will be better positioned to demonstrate operational responsibility and manage long-term operational costs.
Worldwide Modern AI Infrastructure Market
On the innovation frontier, modular and specialized approaches are gaining traction. Recent patent allowances covering canopy-based distributed edge AI data centers with modular GPU cartridges, liquid cooling, and advanced power management illustrate the industry's exploration of alternative deployment architectures capable of scaling to massive GPU counts. These developments signal a broadening of design thinking around how AI infrastructure can be architected for density, efficiency, and flexibility, themes that our full report examines in depth.
What the Full Report Delivers: From Macro Trends to Operational Strategy
The Worldwide Modern AI Infrastructure Market research is structured to translate high-level market intelligence into decision-grade insights. Rather than offering static snapshots, the report integrates historical performance data, forward-looking forecasts, segmentation analysis, and competitive assessment into a cohesive framework that executives can apply directly to capital planning, vendor negotiations, and risk management.
The report begins with a robust market sizing and forecast methodology, anchoring historical revenue data from 2020 through 2025 and extending projections through 2032. This temporal span enables readers to evaluate growth trajectories against multiple scenarios, assess the durability of demand drivers, and calibrate internal forecasts against externally validated market estimates. Revenue projections are presented in a format that supports scenario planning, allowing organizations to model capital allocation under varying assumptions about deployment pace, pricing dynamics, and supply availability.
Segmentation analysis provides the granularity necessary to understand where growth is concentrated and where pricing or availability pressures are most acute. Readers gain visibility into component-level revenue composition, deployment model trends, and regional distribution patterns, enabling targeted evaluation of procurement categories, partnership opportunities, and geographic expansion considerations. The segmentation framework is designed to support cross-functional decision-making, bridging the perspectives of engineering, procurement, finance, and strategy teams.
The competitive analysis section profiles the core companies shaping the market, examining their product portfolios, strategic positioning, recent developments, and implications for enterprise customers. By evaluating supplier capabilities, capital commitments, and competitive dynamics, the report equips readers to assess supplier risk, identify alternative sourcing paths, and anticipate shifts in the supply landscape that may affect procurement timelines or pricing.
Regulatory and operational dynamics are integrated throughout the analysis, ensuring that market projections are contextualized within the constraints that actually govern deployment. Discussions of power availability, grid interconnection queues, material intensity, export controls, and efficiency standards are woven into the market narrative rather than appended as afterthoughts, reflecting the reality that these factors are inseparable from infrastructure strategy.
Strategic Imperatives for 2026 Executive Decision-Making
As organizations navigate the current phase of AI infrastructure expansion, several strategic imperatives emerge from the market evidence. First, capital allocation must be grounded in a clear-eyed assessment of deployment bottlenecks, particularly power availability and grid interconnection timelines, rather than assuming that equipment procurement alone determines project velocity. Early engagement with power providers, proactive site evaluation, and realistic scheduling buffers are essential to avoiding costly delays.
Second, supply chain resilience requires deliberate diversification and long-term contracting where feasible. Given the concentration of market revenue among a small number of dominant suppliers and the intensity of capital expenditure across hyperscale and enterprise buyers, equipment availability and pricing will remain volatile. Organizations that establish clear supplier evaluation criteria, maintain alternative sourcing options, and align procurement timing with realistic deployment schedules will be better insulated against disruptions.
Third, regulatory compliance and efficiency considerations must be embedded into infrastructure planning from the outset. Export control frameworks, model weight restrictions, and efficiency benchmarking standards are evolving rapidly, and organizations that treat these factors as peripheral compliance tasks risk encountering delays, cost overruns, or reputational exposure. Integrating regulatory monitoring and efficiency metrics into infrastructure evaluation processes strengthens both operational resilience and strategic positioning.
Fourth, competitive intelligence should inform partnership and vendor selection decisions. The market is characterized by intense investment activity, product roadmap acceleration, and strategic partnerships that reshape supply dynamics. Organizations that maintain awareness of supplier financing plans, capacity commitments, and technology investments will be better positioned to negotiate favorable terms and align infrastructure choices with long-term strategic objectives.
Conclusion: Turning Market Intelligence into Strategic Advantage
The Worldwide Modern AI Infrastructure Market research is designed to provide the analytical depth, segmentation clarity, and competitive context that executives need to make informed decisions in a rapidly evolving market. The macro trajectory is clear: total market revenue has expanded dramatically over the past two years and is projected to continue its ascent through 2032, driven by sustained demand for compute hardware, high-performance networking, data storage, and diverse deployment models across global regions. Yet the strategic value of this research lies not in confirming that the market is growing, but in illuminating the structural forces, competitive dynamics, and operational constraints that will determine how individual organizations capture value within that growth.
Market concentration among leading suppliers, the intensity of hyperscaler capital expenditure, the persistence of power and grid interconnection bottlenecks, and the evolution of regulatory frameworks collectively create a landscape where disciplined intelligence translates directly into competitive advantage. Organizations that approach infrastructure planning with a clear understanding of these dynamics will be better equipped to sequence investments, negotiate effectively, manage risk, and align technology deployment with broader business objectives.
The full report provides the comprehensive data, segmentation detail, competitive profiles, and forward-looking analysis necessary to support these decisions. We invite you to explore the complete research on our website, where you will find the full forecast tables, regional breakdowns, supplier assessments, and dynamic scenario analysis that underpin the insights summarized here. In a market moving at this pace, timely and rigorous intelligence is not merely an informational asset; it is a strategic necessity.
For detailed analysis of this topic, please visit the official page: Worldwide Modern AI Infrastructure Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Automotive Clamp Market to Hit $5.92B by 2032, 4.6% CAGR
By pmarketresearch, 2026-09-16
Unlocking the Next Wave: Strategic Intelligence for the Global Automotive Clamp Market (2026–2032)
The automotive industry is undergoing one of the most profound structural transformations in its history, driven by electrification, stringent emission standards, and relentless pursuit of lightweight efficiency. Within this complex ecosystem, a seemingly peripheral component—the automotive clamp—plays a critical role in ensuring the integrity, safety, and performance of fluid, airflow, and exhaust systems. As original equipment manufacturers (OEMs) and tier suppliers navigate supply chain recalibrations and material cost volatilities, access to precise, forward-looking market intelligence is no longer optional; it is a strategic imperative.
Our latest comprehensive research report, Worldwide Automotive Clamp Market, equips industry leaders with the analytical depth required to make informed decisions in 2026 and beyond. This article provides a strategic preview of the market trajectory, competitive dynamics, and operational forces shaping the sector, demonstrating why a granular understanding of this market is essential for capital allocation, product development, and regional expansion planning.
The Macro Trajectory: Sustained Growth Anchored by Engineering Evolution
The global automotive clamp market has demonstrated remarkable resilience and steady expansion over the past half-decade. Historical revenue data from 2020 through 2025 reveals consistent upward momentum, with the sector crossing the four-billion-dollar threshold and establishing a robust baseline for future growth. Looking ahead, the forecast period spanning 2026 to 2032 projects a compound annual growth rate of 4.6 percent, reflecting sustained demand across internal combustion, hybrid, and next-generation electric vehicle platforms.
While headline revenue figures provide a useful compass, the true value of our research lies in the underlying structural drivers. Market expansion is not merely a function of vehicle production volumes; it is increasingly dictated by engineering pivots. As automakers transition toward higher-voltage thermal management architectures and adopt advanced exhaust gas recirculation strategies, the specifications demanded of clamping solutions are evolving. Growth is thus bifurcated: traditional volume-driven demand from established platforms continues to anchor baseline revenues, while specialized, high-performance clamping technologies are capturing premium margins in emerging applications. Understanding how these two streams interact—and where capital should be deployed to capture the higher-yield segment—is a central focus of our analysis.
Decoding the Product and Application Landscape
Automotive clamps are far from commoditized fasteners. The market is segmented across multiple product architectures, each engineered to address distinct operational environments. Worm gear clamps remain a cornerstone for general-purpose fluid and cooling line connections, valued for their adjustable torque characteristics and broad OEM acceptance. Spring and constant-tension clamps have gained significant traction in charge-air, turbocharging, and high-vibration environments where maintaining sealing integrity under thermal cycling is paramount. T-bolt and V-band configurations dominate heavy-duty exhaust and high-temperature manifold applications, while ear clamps serve precision fluid routing needs in compact engine bays and electrified thermal loops.
The application matrix further illustrates how clamping requirements are diverging. Engine and powertrain systems continue to represent the largest demand pool, but the rapid proliferation of battery thermal management, inverter cooling circuits, and cabin HVAC integration is reshaping consumption patterns. Exhaust systems remain heavily dependent on high-temperature profile and V-band solutions, particularly as emissions regulations push back-pressure and catalyst efficiency thresholds higher. Even steering, suspension, and braking subsystems—historically niche consumers of clamping hardware—are seeing incremental demand as vehicle architectures integrate more hydraulic and electronic control lines.
Worldwide Automotive Clamp Market
Our report dissects these segments with granular revenue tracking, volume-to-value conversion analysis, and cross-segment substitution trends. Readers will gain clarity on which product families are experiencing margin compression due to standardization, and which specialized geometries are commanding price premiums as OEMs prioritize reliability over lowest-bit cost. We deliberately refrain from publishing exact regional or application-level breakdowns in this preview; those granular matrices are reserved for clients who require precise portfolio alignment and go-to-market targeting.
Competitive Dynamics: A Consolidated Field of Specialized Leaders
The automotive clamp sector is characterized by a moderately concentrated competitive landscape, where scale, engineering heritage, and certification compliance act as formidable barriers to entry. A handful of established manufacturers command roughly half of total industry revenue, leveraging long-standing OEM relationships, globally distributed production footprints, and continuous process automation. Yet the market is far from static. Mid-tier specialists and regional producers continue to carve out defensible niches by focusing on custom torque profiles, rapid prototyping, or high-volume standardized lines for cost-sensitive platforms.
European firms have historically set the benchmark for engineered joining technologies, particularly in worm-drive, constant-tension, and high-temperature profile clamps designed for demanding European powertrain and exhaust architectures. Swiss manufacturers have built reputations around precision pinch and spring band clamps that prioritize vibration resistance and rapid assembly on automated line systems. North American players contribute deep domain expertise across worm gear, T-bolt, and constant-torque solutions, often serving both passenger vehicle and heavy-duty truck segments with modular product families that can be rapidly adapted to fluid, fuel, and exhaust requirements.
In Asia-Pacific and emerging manufacturing hubs, production capabilities have matured significantly. Several Indian and Taiwanese suppliers now export globally, offering standardized worm-drive, T-bolt, and spring-loaded configurations that align with price-sensitive OEM programs without sacrificing baseline durability. Meanwhile, American-owned manufacturing operations in China and specialized stainless-steel coupling producers in the United States are bridging the gap between performance-grade materials and cost-efficient scale.
Recent corporate developments underscore the strategic agility required to compete. One major European manufacturer expanded automated clamp production lines in early 2025, boosting manufacturing capacity by nearly twenty percent to absorb surging demand from updated cooling and exhaust platforms. A prominent North American supplier subsequently widened its global distribution networks, increasing international supply coverage by more than thirty percent and positioning itself to capture cross-border program wins. Simultaneously, a lightweighting-focused product launch in mid-2025 introduced clamps that reduce component weight by approximately fifteen percent, directly addressing OEM targets for mass reduction and improved overall vehicle efficiency.
Our competitive analysis maps these moves against pricing strategies, capacity utilization rates, and regional program win rates, providing a clear picture of who is gaining share, where margin erosion is most acute, and which suppliers are best positioned to benefit from electrification-driven redesign cycles.
Forces Reshaping the Value Chain: Materials, Regulations, and Performance Demands
Three interlocking forces are redefining competitive advantage in the automotive clamp sector. First, raw material economics exert continuous pressure on cost structures. Steel and stainless steel constitute nearly seventy percent of production inputs for automotive clamps, and price volatility in these commodities can inflate manufacturing costs by fifteen to twenty percent in any given cycle. Suppliers that fail to hedge material exposure, optimize scrap rates, or transition efficiently to alternative alloys risk margin erosion, particularly when OEMs push back on price increases during program renegotiations.
Second, regulatory and quality compliance frameworks are becoming increasingly stringent. Automotive clamps must satisfy IATF 16949 quality management standards and, for worm-drive types, meet SAE J1508 specifications to guarantee reliable performance under vibration, pressure fluctuations, and extreme temperature ranges. Non-compliance is not merely a technical risk; it results in program disqualification, warranty exposure, and reputational damage. Suppliers with robust certification portfolios and documented process controls hold a distinct advantage when qualifying for next-generation vehicle platforms.
Third, engineering performance requirements are escalating. Constant-tension and spring-loaded designs are increasingly specified to accommodate thermal expansion and contraction in cooling and charge-air systems, ensuring long-term sealing integrity without overtightening or relaxation. High-temperature profile clamps engineered to withstand component temperatures approaching nine hundred degrees Celsius are becoming essential for modern exhaust and turbocharger architectures. Meanwhile, lightweighting trends are accelerating the adoption of advanced materials and thinner-gauge constructions, enabling overall vehicle weight reduction that directly improves fuel economy in internal combustion platforms and extends driving range in electric vehicles.
These forces do not operate in isolation. A supplier that masters material cost mitigation, maintains rigorous certification compliance, and delivers thermally optimized, lightweight clamping solutions simultaneously will capture disproportionate value in the coming years. Our report quantifies these capability gaps and maps which competitors are best positioned to navigate the intersection of cost, compliance, and performance.
What the Report Delivers: Actionable Intelligence for 2026 Decision-Making
The Worldwide Automotive Clamp Market report is structured to serve as a practical decision-support tool rather than a static data repository. Key deliverables include:
Hose Clamps Market
- Baseline and forecast revenue tracking from 2020 through 2032, with clear delineation of historical performance versus projected trajectories under multiple adoption scenarios.
- Detailed segmentation analysis across product types and end-use applications, highlighting volume-to-value ratios, substitution patterns, and margin characteristics for each category.
- Regional market structure evaluation, identifying where production localization, import dependency, and OEM consolidation are reshaping supply-demand balances.
- Competitive benchmarking of leading manufacturers, including capacity expansion timelines, distribution network growth, product launch cadence, and program-win positioning.
- Value chain mapping that tracks raw material exposure, manufacturing process automation trends, and logistics bottlenecks affecting lead times and cost-to-serve.
- Regulatory and technical compliance checklists, ensuring that strategic planning accounts for IATF 16949, SAE J1508, and evolving thermal and pressure testing requirements.
- Scenario-based strategic recommendations for suppliers, OEMs, and tier-one partners seeking to optimize sourcing strategies, portfolio mix, and regional footprint.
Each section is designed to translate market data into executable strategy. Whether the objective is to evaluate a potential acquisition target, calibrate production capacity for a new clamp geometry, or identify underserved application niches in electrified thermal management, the report provides the evidentiary foundation required to move with confidence.
Why This Intelligence Matters Now
2026 represents a pivotal inflection point. Vehicle architectures are being finalized for production cycles that will extend well into the next decade, and clamping specifications locked in today will dictate cost structures, assembly line efficiency, and long-term reliability outcomes. Organizations that delay strategic planning until program launches are already behind; those that integrate market intelligence into portfolio planning, sourcing negotiations, and R&D prioritization will secure a compounding advantage.
Material volatility, regulatory complexity, and performance escalation are not temporary headwinds; they are structural features of the modern automotive supply chain. The ability to anticipate how these forces will redistribute value across product segments, geographic markets, and competitor portfolios is precisely what separates reactive suppliers from proactive market leaders.
Navigate the Outlook with Precision
The Worldwide Automotive Clamp Market report offers a complete, data-rich map of a sector in transition. From historical baselines and multi-year forecasts to competitive positioning, material economics, and technical compliance requirements, every insight is calibrated for executive decision-making. We have outlined the macro trajectory, the competitive architecture, and the operational forces reshaping the industry; the full report goes further, delivering the precise segment-level revenue matrices, regional growth differentials, and company-specific capability assessments that inform capital allocation and strategic prioritization.
To access the complete dataset, detailed segmentation breakdowns, and proprietary competitive benchmarking, visit the official research page for Worldwide Automotive Clamp Market. Equip your team with the intelligence required to turn market complexity into strategic clarity.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Clamp Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Reformer Unit Market to Hit $1,383.65M by 2032, 6.95% CAGR
By pmarketresearch, 2026-09-16
Global Reformer Unit Market Outlook 2026: Strategic Intelligence for Industrial Decision Makers
Market Trajectory and Structural Resilience
The Worldwide Reformer Unit Market represents a critical nexus in global industrial infrastructure, underpinning hydrogen generation, ammonia synthesis, methanol production, and oil refining operations. As organizations navigate capital allocation decisions through the late 2020s, understanding the revenue trajectory and structural drivers within this sector has become indispensable. Our latest market research delivers a comprehensive assessment of an industry that expanded from 620.5 Million USD in 2020 to an estimated 864.5 Million USD in 2025, reflecting consistent year-over-year momentum through evolving feedstock landscapes and shifting regulatory environments.
Worldwide Reformer Unit Market
Looking ahead, the forecast horizon spanning 2026 through 2032 projects sustained expansion with a compound annual growth rate of 6.95 percent. This trajectory points toward a market exceeding 1.3 Billion USD by the close of the forecast window. The underlying demand architecture is multifaceted, driven by expanding hydrogen economy initiatives, low-carbon ammonia ventures, and ongoing refinery modernization programs. Critically, this growth narrative is not a simplistic extrapolation of historical volumes. It reflects transformative shifts in reformer technology selection, geographic deployment patterns, and the commercial calculus surrounding decarbonization compliance.
For executives evaluating procurement strategies, capacity expansion plans, or technology licensing partnerships, the distinction between historical performance and forward-looking inflection points carries substantial financial weight. The market's acceleration trajectory is increasingly tied to regulatory timelines, feedstock flexibility requirements, and the competitive positioning of engineering firms that can deliver integrated, low-emission reformer solutions at commercial scale. Our research dissects these variables with granular precision while maintaining the analytical ambiguity necessary for proprietary advantage.
Segmentation Architecture and Demand Concentration
Reformer unit procurement decisions are inherently segmented across type, application, and geographic deployment zones, each carrying distinct technical specifications and commercial implications. The market ecosystem encompasses steam methane reforming configurations, catalytic reforming platforms, and autothermal reformer designs, with procurement volumes and revenue contribution varying across industrial end-uses including hydrogen production, ammonia manufacturing, methanol synthesis, and oil refining operations. Understanding the precise weighting of these segments informs everything from supplier negotiation leverage to long-term technology roadmapping.
Geographic distribution patterns further complicate strategic planning. Industrial development across Asia Pacific, North America, Europe, the Middle East and Africa, and Latin America exhibits divergent pacing driven by localized energy transition mandates, feedstock availability, and infrastructure investment cycles. Buyers operating across multiple jurisdictions must reconcile these regional variances against centralized procurement targets, a complexity that standard industry summaries rarely capture with sufficient operational granularity.
Market concentration metrics offer additional insight into the competitive equilibrium. The industry remains moderately consolidated, with the top three firms commanding significant revenue share and the top five collectively representing a substantial majority of market activity. This concentration shapes pricing dynamics, licensing negotiations, and the strategic behavior of both incumbent technology providers and emerging equipment manufacturers. Organizations seeking to enter supplier relationships or evaluate partnership opportunities must account for the bargaining power embedded within this concentration structure.
Competitive Landscape: Major Players and Strategic Moves
The reformer unit market features a diversified competitive field spanning engineering contractors, technology licensors, catalyst specialists, and high-temperature component manufacturers. Each participant brings distinct capability profiles that influence procurement decisions across different application verticals and project scales.
Linde Engineering has established a formidable footprint through the delivery of over 250 reforming furnaces worldwide, offering top-fired, side-fired, and wall-fired configurations alongside its HYDROPRIME modular cylindrical and skid-mounted solutions. The company's emphasis on heat recovery optimization and low-emission revamps positions it favorably within hydrogen, syngas, ammonia, and methanol applications. Recent activity underscores this strategic direction: in February 2025, Linde Engineering secured a record number of small on-site solutions including hydrogen-related plants driven by decarbonization priorities, and in June 2025, Linde signed a long-term industrial gas supply agreement for a world-scale low-carbon ammonia facility incorporating autothermal reforming.
Honeywell UOP and Axens dominate the catalytic reforming segment, supplying process technologies, catalysts, and modular equipment for refinery reformer units. Honeywell UOP focuses on semi-regenerative and continuous catalytic reforming licensing with high-octane gasoline and aromatics as primary outputs. Axens contributes its Octanizing CCR processes and semi-regenerative solutions, supported by over 130 licenses globally, with integrated offerings spanning gasoline production, aromatics, and residue upgrading. Both firms remain central to refinery modernization strategies as operators seek to balance throughput targets against emissions constraints.
Worldwide Steam Reformers Market
KBR and Technip Energies provide complementary engineering and licensing capabilities across steam methane reforming and autothermal reforming for hydrogen and syngas applications, with Technip Energies also delivering comprehensive EPC services. Johnson Matthey addresses the catalyst layer through its KATALCO series and pre-reforming formulations optimized for ammonia, methanol, hydrogen, and gas-to-liquid production, directly influencing reformer efficiency and operational lifespan.
Component-level suppliers such as MetalTek International and Kubota Corporation supply centrifugally cast reformer tubes, outlet manifolds, and heat-resistant cast steel components designed for extended creep-resistant service life of 10 to 12 years or more in high-temperature and high-pressure environments. Wood plc and Larsen & Toubro Limited round out the competitive field through engineering, consulting, and construction engagements spanning refining and hydrogen production contexts. Topsoe's October 2025 conference presentation on electrifying steam reformers as a sustainable hydrogen pathway signals growing industry focus on next-generation process electrification, reinforcing the competitive imperative around innovation velocity.
Industry Dynamics Shaping 2026 Decision-Making
Several converging forces are reshaping procurement timelines and technology selection criteria across the reformer unit ecosystem. Energy efficiency mandates and decarbonization requirements are accelerating adoption of electrified steam reformer configurations capable of reducing direct flue gas carbon dioxide emissions by substantial margins while improving thermal efficiency in existing ammonia plant installations. Concurrently, stricter greenhouse gas emission regulations and carbon pricing mechanisms are exerting financial pressure on conventional fuel-fired reformer architectures, prompting operators to evaluate electrification pathways and carbon capture integration as viable compliance strategies.
Hydrogen economy initiatives and low-carbon ammonia and hydrogen project pipelines continue to sustain demand for advanced reformer designs characterized by enhanced efficiency metrics and carbon capture compatibility. These project-level drivers interact with macroeconomic variables, particularly raw material cost trajectories. Global steel prices, which serve as the primary input for reformer tubes and pressure vessels, are positioned at or near the bottom of the current price cycle entering 2026, with subdued recovery anticipated through the year and a more meaningful upturn projected from 2027 onward. This cost dynamic carries direct implications for equipment procurement budgets, contract timing, and vendor negotiation leverage.
The interplay between regulatory pressure, technology availability, and input cost cycles creates a decision environment where timing and specificity matter enormously. Organizations that delay evaluation of electrified or hybrid reformer configurations risk exposure to rising compliance costs and potential capacity constraints as supplier order books fill. Conversely, premature commitment without accurate segment-level intelligence can result in suboptimal capital deployment, misaligned technology selection, or unfavorable commercial terms.
Research Methodology and Report Scope
Our Worldwide Reformer Unit Market research is structured to deliver actionable intelligence across multiple decision dimensions. The report integrates quantitative market sizing with qualitative technology and competitive analysis, providing a single reference point for strategic planning teams. Key components include detailed segmentation breakdowns by type, application, and region, with revenue estimates and growth trajectories mapped across the historical 2020 through 2025 period and the forecast 2026 through 2032 window.
The competitive profiling section delivers individualized company assessments encompassing headquarters location, core technology offerings, recent project activity, and strategic positioning within specific reformer sub-markets. These profiles are supplemented by a curated timeline of recent industry developments, capturing conference presentations, project award milestones, long-term supply agreements, and regulatory announcements that signal near-term market direction.
Demand-side analysis examines application-specific drivers across hydrogen, ammonia, methanol, and oil refining verticals, while regional assessments contextualize deployment pacing against localized policy frameworks, infrastructure investment cycles, and feedstock economics. The report further integrates upstream cost dynamics, including steel and alloy material trends, to inform procurement timing strategies and budget forecasting. Market concentration metrics and competitive equilibrium analysis support supplier evaluation and partnership structuring decisions.
Strategic Implications for Corporate Planning
The reformer unit market sits at the intersection of energy transition imperatives, refinery modernization requirements, and industrial gas demand growth. For executives navigating 2026 planning cycles, the strategic question is no longer whether this market will grow, but how the growth will be distributed across technologies, geographies, and supplier ecosystems. Our research provides the depth required to answer that question with confidence.
Organizations evaluating new capacity investments must weigh the technical trade-offs between steam methane, catalytic, and autothermal configurations against localized regulatory timelines and feedstock economics. Procurement teams negotiating with engineering contractors and component suppliers must incorporate steel price cycle projections and concentration-driven pricing dynamics into cost models. Technology strategists assessing electrification and carbon capture integration pathways require precise benchmarks on efficiency gains, emission reduction potential, and commercial availability timelines.
Contact our research team to access the full Worldwide Reformer Unit Market report and secure the granular data, segmentation breakdowns, and competitive intelligence necessary to sharpen your 2026 strategic positioning. The complete dataset, detailed regional and application-level analysis, and extended company profiles are available exclusively through our direct research portal.
For detailed analysis of this topic, please visit the official page: Worldwide Reformer Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Cake Pans Market Hits $1.59B in 2025, Forecasted to Reach $2.46B by 2032
By pmarketresearch, 2026-09-16
Navigating the Global Cake Pans Market: Strategic Intelligence for 2026 and Beyond
The global kitchenware sector is experiencing a renaissance, driven by a resurgence in home baking, the expansion of artisanal bakery chains, and evolving consumer preferences for specialized cookware. At the heart of this ecosystem lies the cake pans market, a foundational segment that bridges raw material manufacturing, retail distribution, and end-user culinary performance. As we move further into the mid-2020s, understanding the trajectory, competitive architecture, and regulatory contours of this market is no longer optional for stakeholders. It is a prerequisite for resilient growth.
PW Consulting is pleased to introduce our latest comprehensive study: the Worldwide Cake Pans Market. This report is engineered to convert macro-level industry signals into actionable strategic intelligence. Designed for executives in manufacturing, supply chain management, retail leadership, and investment analysis, our research provides a rigorous, data-driven foundation for navigating the forecast period from 2026 to 2032.
Market Trajectory and the 2026 Inflection Point
The cake pans market has demonstrated remarkable resilience and growth over the past half-decade. Drawing on historical data from 2020 through 2025 and projecting forward, our analysis reveals a sector moving from a global valuation of approximately 1.1 billion USD in 2020 to a substantial 1.58 billion USD by 2025. This expansion underscores a consistent upward demand curve, influenced by heightened culinary engagement, the proliferation of baking content across digital platforms, and steady commercial bakery investments.
Looking ahead, the forecast period from 2026 to 2032 is positioned for sustained momentum. The market is projected to continue its growth trajectory, reaching a valuation that will underscore the segment's increasing strategic weight within the broader houseware and specialty retail categories. A compound annual growth rate of 6.48 percent reflects not only steady consumer demand but also the ongoing maturation of distribution networks and product innovation cycles. For decision-makers, this CAGR is more than a numerical indicator; it represents the pace at which capital allocation, inventory planning, and product development strategies must be calibrated to maintain competitive parity.
Structural Dynamics: Material, Channel, and Regional Interplay
The evolution of the cake pans market is fundamentally shaped by three intersecting forces: material innovation, channel transformation, and regional divergence in purchasing behavior. Our research dissects these dimensions to reveal how value is created, captured, and contested across the supply chain.
Material composition remains a critical battleground. The market is anchored by a diverse array of substrates, each offering distinct performance profiles, cost structures, and end-user value propositions. Metal-based solutions continue to dominate a significant portion of total revenue, driven by their thermal conductivity, durability, and compatibility with both home and commercial baking environments. Within this category, aluminum-based products, including anodized variants, command a prominent share, reflecting their widespread adoption among professional bakeries and discerning home users alike. Carbon steel and aluminum-composite alternatives further expand the material landscape, offering manufacturers flexible pathways to balance performance, weight, and production costs. Meanwhile, non-metallic categories such as silicone, glass, and ceramic have cultivated dedicated followings, appealing to consumers and artisans who prioritize non-stick convenience, aesthetic presentation, and specialized heat-retention properties. This multi-material ecosystem creates a complex value matrix where product positioning, price tiering, and target-user segmentation are inextricably linked.
Worldwide Cake Pans Market
The distribution architecture is undergoing a parallel transformation. Traditional brick-and-mortar formats, particularly supermarkets and hypermarkets, remain powerful engines of volume, leveraging their broad foot traffic and one-stop shopping appeal. At the same time, online retail channels have matured into formidable growth vectors, accelerated by improved logistics infrastructure, social commerce integration, and the consumer shift toward digital discovery and direct purchasing. Specialty stores and direct-to-consumer models further enrich the channel mix, offering niche products, curated assortments, and brand storytelling opportunities that resonate with premium and enthusiast segments. The interplay between these channels dictates not only revenue allocation but also the strategic priorities around brand visibility, inventory velocity, and customer acquisition cost management.
Regionally, the market exhibits distinct demand characteristics that reflect local baking traditions, economic conditions, retail maturity, and import-export dynamics. North America and Europe together represent mature, high-value arenas where brand differentiation, product quality, and regulatory compliance are paramount. Asia Pacific presents a compelling growth narrative, fueled by urbanization, rising disposable incomes, and the expanding footprint of modern retail and e-commerce. Latin America and the Middle East and Africa, while representing more nascent but promising spaces, offer long-term potential tied to the gradual formalization of retail channels and the growing visibility of global baking culture. Our report maps these regional nuances without reducing them to static snapshots, instead providing the contextual intelligence necessary to prioritize market entry, expansion, or resource reallocation with confidence.
Competitive Architecture: Incumbents, Innovation, and Strategic Positioning
The global cake pans market is characterized by a moderately concentrated competitive landscape, with a handful of leading players capturing a meaningful portion of total industry revenue, while a broader tier of specialized and regional manufacturers competes on differentiation, pricing, and channel access. Our analysis identifies a diverse set of enterprises that collectively define the market's strategic contours.
Established North American manufacturers such as Nordic Ware and Wilton Brands LLC have long been synonymous with reliable, design-forward bakeware, serving both professional decorators and home bakers through iconic product lines that span round layer pans, Bundt varieties, and seasonal formats. USA Pan and Fat Daddio's compete in the commercial-grade and performance-oriented segments, emphasizing aluminized steel and anodized aluminum constructions engineered for even heating, non-stick efficacy, and durability under repeated professional use. Calphalon LLC extends this premium logic into the broader consumer space, leveraging its reputation for high-end non-stick bakeware to capture users who prioritize longevity and consistent results.
International manufacturers contribute critical depth to the competitive field. Emile Henry and Le Creuset, rooted in French craftsmanship traditions, offer ceramic and enameled cast iron alternatives that appeal to artisanal and premium home baking audiences seeking superior heat retention and distinctive culinary aesthetics. Kaiser Bakeware, based in Germany, reinforces the market's emphasis on engineered quality, supplying bakeware designed for both home and professional environments. On the industrial and supply-chain side, American Pan and Parrish Magic Line focus on the commercial bakery and stock-pan segment, providing scalable aluminum and coated solutions for high-volume production. China-based Wuxi Hongbei Bakeware Co., Ltd. represents the growing presence of industrial-scale manufacturers capable of delivering custom and stock configurations for bakery operations that prioritize cost efficiency and production flexibility.
This competitive mosaic is neither static nor frictionless. Recent market events underscore the volatility that can ripple through adjacent product categories and influence broader consumer confidence. In February 2026, for instance, regulatory actions escalated a product recall involving certain cake mix varieties due to undeclared allergens, highlighting the critical importance of stringent quality control, transparent labeling, and supply chain traceability for any company operating in the baked goods ecosystem. Although such recalls originate within the mix segment, they send ripple effects across the entire value chain, reinforcing the need for pan manufacturers and distributors to align their quality assurance protocols, packaging integrity, and compliance frameworks with the highest industry standards.
Regulatory Pressures, Input Costs, and the External Environment
Strategic decision-making in the cake pans market cannot be divorced from the external environment in which it operates. Raw material economics, regulatory mandates, and trade policy dynamics all exert direct or indirect pressure on manufacturing costs, pricing strategies, and market access.
Input cost volatility remains a persistent consideration. Global wheat prices, for example, have experienced notable fluctuations, reflecting broader agricultural market conditions that influence the economics of baking at large. While cake pans are not directly derived from agricultural commodities, their demand is closely tied to the overall baking activity of households, bakeries, and foodservice operators. When input costs for core baking ingredients rise or become unpredictable, end-users may adjust purchasing frequency, recipe complexity, or equipment investment cycles. Manufacturers and channel partners must therefore anticipate these demand-side elasticity effects when forecasting volume, planning production runs, and setting price architectures.
Regulatory compliance represents another layer of strategic complexity. Food safety authorities in major markets, including the U.S. FDA, mandate clear labeling of major food allergens such as wheat, eggs, and milk for packaged baked goods. For cottage food operations and small-scale producers, labeling requirements extend to producer identification, product naming, and applicable allergen declarations. Although these mandates primarily target food products rather than cookware, they shape the broader operating environment in which cake pans are purchased, used, and evaluated. Manufacturers that supply professional bakeries or partner with commercial food producers must ensure their product documentation, coating specifications, and material disclosures support rigorous compliance workflows downstream.
Trade policy developments further complicate the landscape. The implementation of broad additional ad valorem import tariffs, beginning at a baseline of 10 percent on goods from a range of trading partners, introduces new cost and sourcing considerations for an industry that relies on international supply chains, cross-border component flows, and globally distributed manufacturing footprints. Companies must evaluate how tariff exposure affects landed costs, supplier diversification strategies, inventory positioning, and final price pass-through to consumers. In this environment, the ability to model tariff scenarios, stress-test margin assumptions, and identify alternative sourcing pathways becomes a core competitive capability rather than a peripheral administrative function.
What the Report Delivers: A Toolkit for Strategic Action
Our Worldwide Cake Pans Market report is structured to move beyond descriptive analysis and toward executive-grade decision support. It is designed to be a practical reference for shaping product roadmaps, refining market entry tactics, optimizing channel strategies, and anticipating competitive responses. The report's scope encompasses, but is not limited to, the following areas of actionable insight:
- Comprehensive market sizing and historical tracking from 2020 through 2025, establishing a validated baseline for assessing growth momentum and structural shifts.
- Forward-looking revenue projections through 2032, enabling scenario planning, target setting, and investment prioritization across the forecast horizon.
- Deep segmentation analysis across material types, sales channels, and geographic regions, revealing where value concentrates, where growth accelerates, and where differentiation is most defensible.
- Competitive profiling of leading manufacturers, including product positioning, brand strategy cues, channel emphasis, and capabilities relevant to commercial and consumer segments.
- Assessment of market concentration dynamics, providing context on the balance of power between dominant incumbents and emerging or niche players.
- Evaluation of external drivers and constraints, including raw material economics, regulatory frameworks, import tariff implications, and consumer behavior trends that influence demand cycles.
- Strategic implications and strategic recommendations tailored to manufacturers, distributors, retail operators, and investors seeking to align their portfolios with the most promising growth vectors.
By integrating quantitative rigor with qualitative industry intelligence, the report equips readers to answer the questions that directly affect enterprise performance: Which segments offer the most favorable risk-adjusted growth? Where should product innovation and material investment be focused? How should channel strategies evolve in response to shifting retail dynamics and digital commerce acceleration? What competitive moves are likely from incumbents and smaller challengers? And how should organizations prepare for regulatory and trade-policy scenarios that could reshape cost structures and market access?
Non-Stick Pans Market
Why This Research Matters for 2026 Decision-Making
The 2026 to 2032 window will be defined by organizations that can translate market signals into disciplined execution. As the global cake pans market continues to expand at a measured but meaningful pace, stakeholders face a dual mandate: capture share in high-potential segments while defending against cost pressures, competitive intensification, and external shocks that can erode margin and disrupt planning cycles. Success in this environment requires more than intuition; it requires a structured understanding of market size, growth rate, segmentation patterns, competitor capabilities, and the macro forces shaping the operating terrain.
Our research is built to serve that need. It provides the evidentiary foundation for strategic choices, from long-range capacity planning and product development investment to pricing architecture, channel mix optimization, and market prioritization. It also highlights the operational discipline required to navigate an environment where input costs fluctuate, regulatory expectations intensify, and trade policy introduces new uncertainty into cross-border commerce.
Access the Full Intelligence Suite
This article offers a strategic preview of the landscape, but the complete analytical depth, detailed segmentation breakdowns, granular competitive assessments, and forward-looking scenario analysis reside within the full Worldwide Cake Pans Market report. For executives and analysts who require precise data, comprehensive segmentation detail, and actionable strategic guidance to inform 2026 planning and beyond, the full study is essential.
To explore the complete findings, access detailed market size trajectories, review in-depth competitor profiles, and unlock the strategic recommendations designed to support informed decision-making, we invite you to visit the source webpage and obtain the full report. Equip your organization with the intelligence needed to navigate the market's next phase of growth with clarity, confidence, and strategic advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Cake Pans Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Acute Care EHR Market to Hit $50.57B by 2032, Growing at 6.52% CAGR
By pmarketresearch, 2026-09-16
Navigating the Global Acute Care EHR Landscape: Strategic Imperatives for 2026 Decision-Makers
The worldwide acute care electronic health record market stands at a critical inflection point. As health systems allocate multi-year capital budgets and navigate shifting regulatory frameworks, the choice of EHR platform has evolved from an IT procurement decision into a foundational strategic maneuver. Our latest Worldwide Acute Care Electronic Health Recorder Market research synthesizes historical performance, forward-looking projections, and granular competitive intelligence to equip executives with the analytical clarity required for 2026 and beyond.
Acute Care Telemedicine Services Market
This report is designed as a decision-support instrument rather than a static market snapshot. It maps the structural forces shaping procurement cycles, evaluates the competitive positioning of dominant and emerging vendors, and benchmarks operational priorities against real-world spending behavior. The objective is straightforward: translate complex market signals into actionable intelligence for hospital administrators, health system strategists, technology investors, and policy advisors who must justify capital allocation in an environment of compressed margins and accelerated digital transformation.
Market Trajectory and Structural Growth Drivers
The global acute care EHR market has demonstrated consistent expansion over the past half-decade, reflecting the industry-wide imperative to digitize clinical workflows, strengthen interoperability, and support value-based care models. From a 2020 baseline of USD 24,500 million, the market advanced through 2021 at USD 26,878.16 million, reached USD 28,211.83 million in 2022, and climbed to USD 29,500.61 million in 2023. Growth momentum continued as 2024 recorded USD 31,923.36 million, followed by a 2025 valuation of USD 32,500.0 million.
These historical figures establish a clear trajectory of sustained adoption, but the forward-looking data is where strategic planning gains its most practical utility. Our forecast period spans 2026 through 2032, anchored by a compound annual growth rate of 6.52 percent. This growth profile translates to a 2026 estimate of USD 33,762.2 million, progressing to USD 37,576.93 million in 2027, USD 37,960.9 million in 2028, USD 41,469.16 million in 2029, USD 45,333.3 million in 2030, USD 47,227.17 million in 2031, and a projected 2032 valuation of USD 50,570.0 million.
The persistence of this growth curve is not merely a function of technological modernization. It reflects deeper structural pressures: ongoing interoperability mandates, the integration of AI-enabled clinical decision support, heightened cybersecurity requirements, and the financial volatility that forces health systems to optimize operational efficiency without sacrificing care quality. Our forecast methodology isolates these drivers and models their cumulative impact on procurement cycles, upgrade timelines, and platform migration activity across diverse facility profiles.
Capital expenditure patterns confirm this strategic prioritization. Enterprise technology investments, including EHR implementations and upgrades, remain embedded in multi-year capital budgets that routinely reach billions of dollars. At the same time, spending priorities are recalibrating. AI-based clinical technology solutions have emerged as the leading planned technology initiative for health systems at 57 percent for the 2026-2027 horizon, while EHR optimization spending share has shifted to 43 percent. This rebalancing does not diminish the EHR's centrality; rather, it signals a maturation phase in which foundational digital infrastructure must interoperate seamlessly with next-generation clinical tools.
Competitive Landscape and Vendor Positioning
Market concentration remains pronounced, with the top three players commanding 72.5 percent of total market share and the top five collectively holding 84.2 percent. This concentration shapes negotiation leverage, integration roadmaps, and the risk-reward calculus of platform selection. The competitive field is anchored by organizations with distinct operational philosophies, deployment footprints, and target constituencies.
Epic Systems Corporation, headquartered in Verona, Wisconsin, provides a comprehensive acute care EHR platform distinguished by deep inpatient, surgical, emergency department, and enterprise-wide integration functionality. Its dominance in large hospital systems and academic medical centers is reinforced by a strong focus on seamless clinical documentation and interoperability. Epic's market momentum remains significant, having recorded its largest net gain in US acute care EHR market share by adding 176 multispecialty hospitals and nearly 30,000 beds in 2024 decisions. This trajectory underscores the vendor's ability to capture large-scale migrations and consolidate complex enterprise workflows.
Oracle Health, formerly operating under the Cerner brand and now integrated within Oracle's Austin, Texas headquarters, offers the Millennium platform with strong acute care capabilities spanning inpatient, surgical, and emergency department functionality. The platform serves hospitals of varying sizes with an emphasis on cloud infrastructure integration and large-scale deployments. Recent independent analysis positions Oracle Health at a critical juncture, highlighting ongoing product developments in acute care EHR alongside complex partnership dynamics that warrant close monitoring by organizations evaluating long-term vendor stability and roadmap alignment.
Medical Information Technology, Inc., known as MEDITECH, is based in Westwood, Massachusetts and delivers the Expanse platform as a full acute care EHR suited for community hospitals, rural facilities, and smaller organizations. Its value proposition centers on cost-effective inpatient solutions with stable support for 1-200 bed facilities. For health systems seeking predictable total cost of ownership without sacrificing core clinical functionality, MEDITECH's positioning remains a strategically relevant benchmark.
Evident, operating under CPSI in Mobile, Alabama, specializes in TruBridge and Thrive acute care EHR platforms targeted at community hospitals with fewer than 400 beds. Its focus on comprehensive solutions for smaller acute care organizations and affiliated clinics addresses a segment where workflow simplicity, integration with ambulatory networks, and administrative efficiency often outweigh the complexities of enterprise-scale architectures.
Altera Digital Health, formerly known as the Allscripts Hospitals and Large Physician Practice business and based in Chicago, Illinois, provides the Sunrise Enterprise suite for acute care EHR including clinical and financial solutions. The platform targets hospitals and health systems with flexible, open architectures supporting inpatient workflows. Its design philosophy appeals to organizations that prioritize modularity and third-party interoperability within a unified clinical and financial framework.
Veradigm, also headquartered in Chicago and formerly Allscripts, offers ambulatory and select acute care EHR solutions with a focused emphasis on interoperability and integration with third-party applications. It maintains a presence across hospital and practice settings following its strategic divestiture, serving use cases where cross-continuum data exchange and application extensibility are paramount.
Beyond individual vendor profiles, the market exhibits sustained migration activity. Throughout 2025 and into 2026, multiple hospitals and health systems have announced EHR platform changes and migrations in acute care settings. These migrations are rarely purely technical exercises; they are strategic re-alignments driven by cost pressures, workflow dissatisfaction, interoperability gaps, and the desire to future-proof infrastructure against emerging clinical technology requirements.
Operational and Financial Dynamics Shaping Procurement Decisions
Strategic procurement cannot be evaluated in isolation from the financial and operational environment in which it occurs. Total hospital expenses grew 7.5 percent in 2025, a pace more than twice the rate of growth in hospital prices, driven by labor, drugs, and supplies. This expense compression forces executive teams to scrutinize every capital deployment for measurable return on investment, workflow efficiency gains, and risk mitigation potential.
Simultaneously, cybersecurity has become a non-negotiable line item. Hospitals spent roughly USD 30 billion in 2025 on technology and services to protect systems, data, and operations from cyber threats. This expenditure directly intersects with EHR strategy, as clinical platforms operate at the center of protected health information flows, device integrations, and network-dependent care delivery. Procurement decisions increasingly require explicit evaluation of security architecture, vendor incident response capabilities, and alignment with enterprise-wide resilience frameworks.
Regulatory and reimbursement dynamics add further complexity. The Medicare IPPS proposed rule for acute care hospitals revises inpatient prospective payment systems for operating and capital-related costs, influencing how health systems budget for technology investments and evaluate reimbursement alignment. These changes modulate the financial rationale behind platform upgrades, particularly when capital-related cost structures intersect with depreciation schedules, implementation timelines, and long-term total cost of ownership models.
Under these conditions, the decision to standardize on a platform, migrate to a new environment, or optimize an existing deployment becomes a multi-variable optimization problem. Executives must weigh clinical workflow compatibility, interoperability roadmaps, cloud versus on-premise deployment economics, vendor stability, integration readiness for AI-based clinical tools, and the financial implications of migration downtime. Each of these variables carries distinct risk profiles depending on hospital type, facility size, regional regulatory exposure, and existing technology debt.
Depth of Report Coverage and Strategic Application
This market research is structured to support applied decision-making rather than abstract market observation. The analysis integrates historical performance data with forward-looking projections and contextualizes them within the operational realities that govern purchasing behavior. The report examines deployment model dynamics, hospital type segmentation, regional adoption patterns, and competitive concentration to reveal where growth is concentrated and where strategic opportunity lies.
Deployment architecture remains a central axis of evaluation. Cloud-based implementations and on-premise deployments each present distinct governance, cost, scalability, and control trade-offs that influence how health systems structure multi-year technology roadmaps. The relative share of these deployment models provides insight into shifting infrastructure preferences, particularly as organizations balance capital efficiency against data sovereignty, integration complexity, and long-term scalability requirements.
Hospital type segmentation further clarifies demand patterns. General acute care hospitals and specialty hospitals exhibit differentiated clinical workflows, financial structures, and interoperability priorities, which in turn shape platform fit and procurement rationale. Understanding how market value distributes across these facility categories enables more precise targeting of implementation strategies, vendor negotiations, and optimization investments.
Regional analysis adds an additional strategic layer. Geographic variation in regulatory mandates, reimbursement environments, digital maturity, and competitive intensity affects both the pace of adoption and the vendor mix favored in each territory. The report contextualizes these regional dynamics without reducing them to simplistic rankings, instead highlighting how local market structures influence migration patterns, partnership opportunities, and implementation risk.
Competitive monitoring is embedded throughout the analysis. Recent developments indicate that Epic continues to expand its footprint in large-scale acute care environments, Oracle Health is executing product advancements amid partnership complexities that require careful vendor diligence, MEDITECH maintains strong relevance for smaller and community-based settings, Evident addresses niche acute care configurations, and Altera and Veradigm sustain differentiated positions around open-platform flexibility and interoperability-focused integration. These dynamics are evaluated not as static profiles but as evolving strategic postures that affect procurement leverage and long-term vendor reliability.
Strategic Implications for 2026 Planning Cycles
As health systems finalize 2026 capital plans and extend technology roadmaps into the late decade, several strategic implications emerge from the market structure.
- Platform selection must be evaluated against migration risk and total cost of ownership, not only initial functionality. The concentration of market share among leading vendors means that organizations can benefit from mature interoperability networks and broader implementation experience, but they must also assess vendor dependency, contract flexibility, and long-term roadmap alignment.
- AI-enabled clinical technology is becoming the planning anchor for health system innovation. With AI-based clinical solutions leading planned technology initiatives, EHR platforms must demonstrate readiness for integration, data structuring, and workflow augmentation. Optimization spending remains substantial, but its role is increasingly defined by how well the platform supports adjacent clinical intelligence investments.
- Cybersecurity and regulatory alignment are procurement prerequisites, not add-ons. The significant expenditure on cyber protection and the evolving IPPS reimbursement environment mean that security architecture, compliance readiness, and capital cost modeling belong at the center of evaluation frameworks.
- Migration activity is a strategic signal, not merely an operational event. Continued announcements of EHR platform changes reflect structural dissatisfaction, expansion ambitions, and the pursuit of interoperability and workflow efficiency. Organizations monitoring these migrations can extract benchmarks for negotiation, implementation sequencing, and risk mitigation.
- Capital allocation discipline will separate durable strategies from reactive purchases. Expense growth outpacing price growth, combined with multi-year budget commitments, requires executives to justify EHR investments through measurable efficiency gains, reduced rework, improved documentation quality, and enhanced integration with enterprise technology objectives.
Conclusion
The worldwide acute care EHR market is expanding along a defined growth trajectory while simultaneously undergoing strategic recalibration in how platforms are evaluated, integrated, and defended against evolving operational and financial pressures. The convergence of sustained adoption, competitive concentration, migration momentum, cybersecurity imperatives, and AI-centric planning priorities creates a market environment where informed decision-making offers tangible competitive advantage.
Our research provides the depth and structure needed to navigate that environment. It translates historical performance into forward-looking perspective, situates vendor dynamics within broader market concentration patterns, and aligns procurement considerations with real-world financial and regulatory forces. For executives responsible for 2026 capital planning, platform strategy, and long-term digital transformation, the report offers a framework for reducing uncertainty and increasing the strategic precision of technology investment decisions.
Worldwide Acute Care Electronic Health Recorder (EHR) Market
To access the complete segmentation analysis, regional breakdowns, deployment model comparisons, hospital type distributions, competitive intelligence detail, and full forecast tables, we invite you to explore the source page for the complete Worldwide Acute Care Electronic Health Recorder Market research. The full dataset and methodological documentation are available there for teams that require granular intelligence to support executive briefings, vendor evaluations, and capital allocation decisions throughout 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Acute Care Electronic Health Recorder (EHR) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Foot Traffic Market Hits $8.62B in 2025, Poised to Reach $26.9B by 2032
By pmarketresearch, 2026-09-16
Unlocking Customer Location Intelligence: Strategic Imperatives for the 2026 Market Landscape
Introduction: The Evolution of Physical-Digital Convergence
The boundary between digital strategy and physical presence has dissolved. In 2026, organizations that operate solely on online engagement metrics while ignoring in-person footfall dynamics are operating with half a map. The Worldwide Foot Traffic and Customer Location Intelligence Solution Market has matured rapidly from a niche analytics supplement into a core infrastructure layer for retail, real estate, transportation, healthcare, and smart city operations. This article serves as an executive preview of our latest market research, designed to illuminate the strategic vectors that will define enterprise decision-making through 2032. Readers seeking granular segmentation matrices, proprietary survey findings, and competitor benchmarking tables are invited to explore the full report via the source portal.
The modern enterprise must answer questions that were once dismissed as anecdotal: Where do consumers originate before visiting a store? How do seasonal mobility shifts alter trade area profitability? Which physical touchpoints deliver measurable conversion lift versus dead weight? Location intelligence answers these questions with precision. It fuses anonymized mobility data, sensor-derived counts, geospatial mapping, and behavioral modeling into operational intelligence that directly informs site selection, staffing allocation, inventory planning, marketing spend optimization, and asset valuation.
Macro Trajectory: Why the Growth Curve Matters for Decision-Makers
The market has demonstrated sustained expansion across the historical observation window and is positioned for an accelerated trajectory in the forthcoming forecast horizon. From a base exceeding four billion USD in 2020, revenue climbed past 8.6 billion USD by 2025, reflecting heightened enterprise demand for actionable proximity insights. This momentum carries forward sharply, with the projected annual growth rate of approximately 15.65 percent driving valuation toward nearly 10.2 billion USD in 2026 and surpassing 26.8 billion USD by 2032.
The implications are clear. Capital is flowing into location intelligence not as an experimental capability but as a structural requirement for competitive resilience. Procurement leaders must evaluate vendor ecosystems with long-term scalability in mind. Strategy teams should anticipate that early-mover advantages in foot traffic analytics will compound as data networks deepen and AI-driven inference models become more sophisticated. Investors and board members need visibility into whether their organization's current data architecture can absorb the kind of continuous, high-frequency spatial insights that the market trajectory implies will become table stakes within half a decade.
Crowd Management Solution Market
Solution Architecture and Technology Interplay
Location intelligence solutions are delivered through a layered stack that combines software and analytics platforms, hardware and sensor systems, and professional and managed services. The software layer typically anchors the value proposition: it ingests multi-source data, normalizes disparate formats, applies machine learning models, and surfaces dashboards that translate raw observations into decision-ready intelligence. Hardware components range from in-store sensors and computer-vision counters to environmental and proximity detection units that feed ground-truth signals into broader platforms. Managed services bridge the gap between tool deployment and business outcomes, offering implementation guidance, custom modeling, and ongoing analytical support.
Technology selection is no longer a binary choice between beacon-based tracking and satellite positioning. Wi-Fi and Bluetooth/BLE frameworks continue to provide accurate micro-level presence detection within controlled environments. GPS and satellite positioning supply macro-mobility context, enabling organizations to understand catchment areas, route behaviors, and regional visitation flows. AI-powered video analytics represent a fast-evolving frontier, converting visual streams into demographic, dwell-time, and pathing insights while raising distinct considerations around privacy-by-design architecture. Infrared and thermal sensor approaches complement these methods where lighting conditions, occlusion, or data governance constraints make optical processing less practical. The sophisticated buyer evaluates not single technologies but the interoperability of heterogeneous signals, seeking platforms that can triangulate insights rather than rely on a single sensing modality.
End-User Demand: How Different Verticals Convert Location Data into Operating Leverage
Foot traffic intelligence is not a monolithic use case. Demand patterns diverge considerably across sectors, each extracting a distinct form of economic value from spatial data.
- Retail and shopping centers use location analytics to optimize store layouts, calibrate promotional calendars, evaluate cannibalization risk, and refine trade area definitions. Site selection teams increasingly treat footfall velocity and visitation composition as non-negotiable inputs for new openings and lease negotiations.
- Transportation and logistics operators leverage movement intelligence to align service frequency with passenger and freight flows, reduce idle capacity, and improve last-mile planning. The discipline of matching supply to actual demand patterns rather than assumed averages is a direct productivity driver.
- Real estate and smart buildings apply occupancy metrics to manage tenant mix, forecast amenity utilization, and enhance property-level operational efficiency. As commercial portfolios adapt to evolving work and consumption habits, asset managers increasingly require visitation evidence to validate pricing and leasing strategies.
- Tourism and entertainment venues utilize flow analytics to manage crowd density, time-entry pacing, and experiential offerings, aligning throughput with guest satisfaction and safety tolerances.
- Healthcare and public venues deploy people counting and zone-level occupancy insights to improve patient flow, staff allocation, and space utilization, especially in environments where congestion directly affects service quality and safety.
What unites these verticals is the realization that spatial behavior is a lagging indicator of past planning assumptions and a leading indicator of future performance. The enterprises that institutionalize location intelligence treat it as an operational thermostat rather than a periodic dashboard.
Competitive Landscape: Differentiated Approaches in a Consolidating Field
The vendor ecosystem spans data aggregators, analytics platform builders, sensor manufacturers, GIS specialists, and managed-services providers. Market concentration remains moderate, meaning that no single vendor dominates the entire value chain, but a cadre of well-capitalized public and private players is actively extending their stack depth and ecosystem reach.
Several archetypes have emerged. Platform-first analytics providers construct multi-source data pipelines and partner networks to deliver visitation trends, trade area modeling, and consumer behavior insights. GIS and spatial analysis specialists contribute foundational mapping, spatial statistics, and site-performance evaluation capabilities that complement mobility datasets. Sensor and in-store analytics vendors focus on ground-truth measurement within physical environments, converting visual or proximity signals into people counts, heatmaps, pathing, and conversion metrics. Data infrastructure and mobility data firms supply anonymized movement records and points-of-interest context that feed third-party platforms. The most competitive vendors increasingly differentiate through ecosystem integrations, privacy-compliant data sourcing, and domain-specific model tuning rather than raw data volume alone.
Recent market activity underscores this orientation toward integration, thought leadership, and product deepening. In early 2026, major platform participants continued to emphasize the bifurcation of retail performance and the need for nuanced consumer behavior interpretation in economic development and commercial strategy forums. Simultaneously, data integrations between foot traffic intelligence providers and commercial real estate platforms have accelerated, reflecting demand for asset- and REIT-level consumer behavior insights that connect physical visitation patterns to valuation, leasing, and asset management workflows. Parallel product enhancements in retail site selection tooling have introduced more rigorous cannibalization rate calculations and trade area overlap modeling, signaling that the market is moving from descriptive footfall reporting to prescriptive optimization.
Regulatory and Structural Dynamics Shaping Deployment Strategy
The commercial upside of location intelligence is inseparable from the regulatory environment in which it operates. Data sovereignty and localization requirements in certain jurisdictions mandate that mobility and location data be stored and processed within national borders, constraining cross-border intelligence architectures and forcing vendors and buyers to design regional data residency strategies. In parallel, cross-jurisdictional legal frameworks such as the U.S. CLOUD Act affect how international enterprises evaluate data-handling practices, particularly when platform providers operate under multiple legal exposures simultaneously. These forces are not peripheral compliance footnotes; they influence vendor selection, contractual data processing terms, and architecture decisions around where analytics workloads run.
Spectrum management policy also intersects with the sensing layer. Ongoing regulatory and technical efforts to improve wireless spectrum sharing and utilization have relevance for the transmission reliability and density of Bluetooth, Wi-Fi, and other proximity sensing modalities that underpin parts of the location intelligence stack. While these developments may appear abstract, they affect real-world signal quality, deployment cost curves, and the long-term robustness of sensor-dependent installations in dense urban and indoor environments.
Worldwide Foot Traffic and Customer Location Intelligence Solution Market
Forward-looking enterprises are therefore embedding regulatory diligence into procurement cycles. They are asking vendors about data provenance, anonymization standards, retention policies, regional processing options, and the governance audits available to support compliance teams. In this market, trust is a competitive asset, and privacy-preserving design is increasingly a purchasing requirement rather than a desirability factor.
Strategic Implications for Enterprise Decision-Makers in 2026
For executives shaping 2026 plans, the central question is not whether to use location intelligence but how to operationalize it at the right scale and with the right governance.
- Align foot traffic intelligence with core KPIs. Location data should be wired into the metrics that already drive board-level attention: sales per square foot, conversion rates, labor productivity, asset occupancy, site cannibalization, and customer lifetime value. Insights that live in isolated analytics sandboxes do not inform capital allocation.
- Adopt a layered sensing strategy. No single data source captures the full picture. Combining macro-mobility context with in-store or in-venue sensing, and supplementing both with geospatial analytics, produces more resilient inference than any standalone feed.
- Invest in integration before customization. Platforms that connect cleanly to existing CRM, ERP, lease management, and workforce scheduling systems deliver faster time-to-value than bespoke models that require permanent specialized maintenance.
- Treat privacy and compliance as architecture, not add-ons. Evaluate vendors on data sourcing transparency, anonymization rigor, regional processing capability, and auditability. In a market with rising regulatory scrutiny, procurement documentation should reflect these dimensions explicitly.
- Plan for compounding data network effects. As more entities adopt location intelligence, benchmark data, model accuracy, and comparative context improve. Organizations that deploy early and steadily expand usage will benefit from richer baselines and more refined predictive signals than those who defer.
Conclusion: From Market Intelligence to Operational Advantage
The Worldwide Foot Traffic and Customer Location Intelligence Solution Market is moving from rapid expansion to functional maturation. Revenue scales, technology diversification, and ecosystem integration all point toward a market where spatial insight becomes embedded in everyday operational decision-making rather than treated as a specialized analytics project. The strategic winners in 2026 and beyond will be those who translate location intelligence into measurable operating improvements: sharper site selection, more efficient staffing and space utilization, better trade area understanding, and more defensible asset valuation supported by empirical visitation evidence.
This executive overview has outlined the market trajectory, solution architecture, vertical demand patterns, competitive archetypes, and regulatory dynamics that frame the decision environment. It is necessarily a high-level synthesis. The full market research report provides the detailed segmentation analysis, granular segmentation breakdowns, vendor profiling depth, regional dynamics, technology adoption patterns, and forward scenarios required for precise procurement, investment, and strategic planning decisions. Readers seeking that complete intelligence should access the source report to obtain the full dataset, segmentation matrices, and actionable end-user profiles that accompany this analysis.
For detailed analysis of this topic, please visit the official page: Worldwide Foot Traffic and Customer Location Intelligence Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com