

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Liquid Cooling Fast Connection Market Hits $1.24B in 2025, Forecast 18.25% CAGR to $4.01B by 2032

Powering the Liquid Cooling Revolution: Strategic Intelligence for the Fast Connection Solutions Market
The thermal management landscape is undergoing a structural transformation. As artificial intelligence workloads intensify and data center power densities surge, the industry's reliance on air cooling has reached its physical and economic limits. Direct liquid cooling (DLC) and immersion cooling have transitioned from niche alternatives to essential infrastructure, driving unprecedented demand for reliable, high-performance fluid transfer components. At the heart of this shift lies the fast connection solutions ecosystem, a critical enabler of leak-free, high-flow, and rapid deployment cooling architectures.
PW Consulting's latest worldwide market research on Fast Connection Solutions for Liquid Cooling Systems offers a comprehensive, data-driven lens into this rapidly expanding sector. This article outlines the strategic imperatives shaping the 2026 decision-making environment, contextualizes the macroeconomic trajectory of the market, and previews the analytical depth available in the full report. For executives, engineers, and investors navigating the thermal infrastructure value chain, understanding the connective tissue of liquid cooling is no longer optional—it is a competitive necessity.
The Macro Trajectory: A Market in Hypergrowth
The financial signals from the past half-decade tell a clear story of acceleration. Valued at approximately 585.3 million USD in 2020, the global fast connection solutions market for liquid cooling systems has expanded consistently, closing 2025 at an estimated 1,241.18 million USD. The forward-looking projection is equally compelling: revenues are expected to surpass the 1,498 million USD threshold in 2026 and climb steadily toward 4,012.79 million USD by 2032. This translates to a compound annual growth rate of 18.25 percent throughout the 2026–2032 forecast horizon, placing the sector among the fastest-growing subsegments within the broader thermal management and fluid handling industries.
Worldwide Liquid Cooling Couplings Market
Such sustained expansion is not merely cyclical. It is fundamentally anchored in the architectural redesign of computing and energy infrastructure. As hyperscale operators, colocation providers, and industrial facilities migrate toward high-density thermal solutions, the requirement for quick disconnects, blind-mate connectors, and push-to-connect fittings has evolved from a maintenance convenience to a core design specification. The market's trajectory reflects a structural reordering of priorities: downtime minimization, pressure-drop optimization, coolant purity, and interoperability now dictate component selection as much as upfront cost.
Technology Architectures and Segment Dynamics
The market's growth is distributed across three primary connection architectures, each addressing distinct operational requirements. Non-spill quick disconnects dominate the volume landscape, engineered to maintain fluid integrity during mating and unmating cycles—a non-negotiable feature in live data center environments where coolant leaks can trigger immediate operational shutdowns. Blind-mate connectors address the need for automated, alignment-tolerant connections in high-density rack deployments, while push-to-connect fittings serve applications prioritizing rapid manual installation and serviceability.
Material science continues to shape segment performance. Metallic solutions, particularly those fabricated from stainless steel, aluminum, and brass, maintain a dominant position due to their structural strength, thermal resilience, and compatibility with high-pressure cooling loops. Simultaneously, polymer-based valve and piping architectures—leveraging materials such as PVDF, PP-H, and PE100—are gaining traction for their ability to reduce weight, optimize flow characteristics, and deliver leak-tight performance in precision cooling circuits. This dual-material evolution reflects a broader industry trend: component selection is increasingly driven by application-specific thermal loads, coolant chemistry, and facility layout constraints rather than one-size-fits-all specifications.
Geographic Distribution and Application Diversification
Demand is not evenly distributed across the globe, nor is it concentrated in a single end-use vertical. The market exhibits a clear geographic weighting that mirrors regional data center build-out, semiconductor fab expansion, and electric vehicle infrastructure deployment. Supply chains, manufacturing footprints, and local compliance environments further differentiate regional demand patterns, creating both localized opportunities and cross-border procurement considerations for multinational operators.
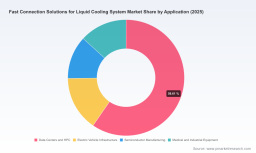
On the application side, data centers and high-performance computing environments represent the most substantial demand driver, reflecting the direct correlation between AI accelerator density and liquid cooling adoption. Electric vehicle charging and energy storage infrastructure contributes a meaningful secondary demand stream, particularly where rapid coolant routing and field-serviceability are prioritized. Semiconductor manufacturing and medical/industrial equipment round out the application portfolio, each introducing specialized requirements around cleanliness, thermal stability, and connection reliability. The interplay between these verticals creates a diversified demand base that insulates the market from single-sector volatility while simultaneously raising the bar for component standardization.
Porter's Five Forces and Competitive Intensity
The competitive structure of the fast connection solutions market reflects a moderately concentrated landscape with room for both established incumbents and specialized challengers. Top-tier players collectively account for a substantial share of revenue, underscoring the importance of engineering reputation, certification portfolios, and long-term supply agreements in securing anchor contracts. At the same time, the fifth and sixth forces—substitute threats and new entrant potential—remain active. Standardization initiatives, modular cooling designs, and cross-vendor interoperability programs are gradually lowering switching costs, pressuring suppliers to compete on total cost of ownership, flow efficiency, and integration support rather than brand loyalty alone.
Bargaining power varies across the value chain. Large data center operators and hyperscale buyers wield considerable leverage in specifying connection standards and demanding compliance with open frameworks, while mid-tier integrators and facility contractors often rely on supplier-led engineering guidance to navigate fluid dynamics, pressure ratings, and material compatibility. Supplier power is moderated by a healthy pipeline of qualified manufacturers across North America, Europe, and Asia Pacific, though lead-time reliability, quality assurance, and post-installation support remain critical differentiators. The threat of substitutes is muted by the physical specificity of liquid cooling loops, yet the rise of polymer-based valve assemblies and hybrid metal-polymer designs keeps the innovation frontier active.
Competitive Landscape: Leaders and Strategic Moves
The market features a cohort of well-established industrial coupling manufacturers and thermal management specialists, each carving distinct positioning within the liquid cooling ecosystem. CPC (Colder Products Company) continues to advance its Everis series quick disconnect couplings, including blind-mate and high-flow variants engineered for electronics and data center thermal management, backed by rigorous reliability testing protocols. Parker Hannifin's Quick Coupling Division emphasizes dripless, non-spill performance under pressure, targeting server and rack cooling applications where thermal loads and uptime expectations are exceptionally high.
CEJN has strengthened its footprint in data center CDU applications by supplying high-flow, low-pressure-drop quick connect couplings, including OCP-compliant series developed alongside industry leaders to enable blind-mate and interchangeable deployment scenarios. Danfoss, through its Hansen thermal management line, focuses on optimized flow paths that reduce pressure drop while maintaining robust thermal control for electronics and liquid-cooled infrastructure. Stäubli brings clean-break, quick and dry disconnect solutions to both industrial and data center environments, with recent product introductions targeting compact liquid-cooled optical architectures where space constraints and high-temperature performance intersect.
Amphenol Industrial Operations supports a broad portfolio of liquid cooling quick disconnect connectors spanning blind-mate, quick-connect, and high-flow architectures, serving data centers, EV infrastructure, and energy storage systems. Gates Corporation advances full-flow quick disconnect couplings tailored for direct-to-chip liquid cooling, prioritizing secure and simple connections compatible with existing facility infrastructure. Specialty Manufacturing Co. contributes custom and standard thermal management quick disconnects, including the Universal Quick Disconnect series, with an emphasis on reliability in electronics cooling contexts. TITAN Fluid has emerged as a notable player offering stainless steel quick disconnect couplings that align with OCP and NVIDIA specifications, targeting zero-downtime connection requirements in high-performance data centers. Motivair, operating under Schneider Electric, supplies Everis quick connects and Dynamic Cold Plates designed for seamless water transfer in direct-to-chip cooling architectures.
Recent product and partnership activity underscores how actively this competitive field is evolving. In early 2026, GF and Rittal announced a full-scope polymer cooling infrastructure solution, featuring a patented dual-ball valve in PVDF designed for direct-to-chip liquid cooling with optimized flow paths and leak-tight operation. Around the same period, Stäubli unveiled a compact quick disconnect variant aimed at liquid-cooled optical modules during a major industry keynote, highlighting the push toward miniaturization in high-density photonic cooling. Earlier initiatives included trade show showcases and technical publications addressing leakage-free connections for battery energy storage systems, low-pressure-loss coupling demonstrations for semiconductor and data center cooling, and engineering guidance on reducing pressure drops to improve thermal management energy efficiency. These moves illustrate a market where product differentiation, standards alignment, and application-specific validation are accelerating simultaneously.
Regulatory and Standards-Driven Demand Catalysts
External mandates and industry guidelines are acting as powerful adoption accelerants. Updated thermal guidelines for data processing environments and dedicated liquid cooling recommendations have codified the viability of higher supply temperatures and energy-efficient loop designs, reinforcing the case for liquid cooling in high-density server environments. Complementary standards defining data center efficiency metrics place cooling system performance under continuous scrutiny, while regional energy efficiency mandates increasingly favor infrastructure choices that support lower power usage effectiveness targets. In parallel, the broader shift toward direct liquid cooling and immersion cooling is being driven by AI and HPC power density increases, with documented energy savings potential relative to traditional air cooling and the ability to support ultra-low facility efficiency ratios. These dynamics do not merely influence procurement preferences; they reshape engineering specifications, architectural planning, and capital allocation timelines across the digital infrastructure sector.
Worldwide Fast Connection Solutions for Liquid Cooling System Market
What the Full Report Delivers
The PW Consulting Worldwide Fast Connection Solutions for Liquid Cooling System Market study is designed to convert this complex landscape into actionable intelligence. Beyond the headline growth trajectory, the report deconstructs historical performance, forecast pathways, and the operational variables that will determine market outcomes through 2032. It provides a structured assessment of connection architecture demand, end-use application priorities, and regional demand weighting, while mapping the strategic behavior of leading manufacturers and emerging participants.
Practitioners will find detailed analysis of product development directions, materials and flow-optimization trends, and the regulatory and standards environment shaping specification requirements. The research also evaluates competitive positioning, partnership activity, and the practical implications of interoperability frameworks for supply chain planning and product selection. For organizations evaluating market entry, capacity expansion, component standardization, or supplier negotiation strategy, the report offers a decision-ready framework that connects market-level signals with segment-level execution considerations.
Strategic Takeaways for 2026 Decision-Makers
As liquid cooling transitions from specialized deployment to mainstream infrastructure, fast connection solutions have become a defining component of thermal reliability, serviceability, and system efficiency. The market's growth path reflects more than rising compute demand; it signals a fundamental rethinking of how facilities are designed, maintained, and scaled. Decision-makers who align their product roadmaps, procurement standards, and partnership strategies with this evolving reality will be better positioned to capture value in a market where performance, compliance, and interoperability increasingly determine competitive outcomes.
To obtain the full dataset, granular segmentation analysis, forecast breakdowns, and complete competitive profiles, we invite you to explore the complete PW Consulting market report. The detailed intelligence contained within provides the precision required to translate macro trends into executable strategy across engineering, commercial, and investment functions.
For detailed analysis of this topic, please visit the official page: Worldwide Fast Connection Solutions for Liquid Cooling System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com