

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Automotive Clamp Market to Hit $5.92B by 2032, 4.6% CAGR

Unlocking the Next Wave: Strategic Intelligence for the Global Automotive Clamp Market (2026–2032)
The automotive industry is undergoing one of the most profound structural transformations in its history, driven by electrification, stringent emission standards, and relentless pursuit of lightweight efficiency. Within this complex ecosystem, a seemingly peripheral component—the automotive clamp—plays a critical role in ensuring the integrity, safety, and performance of fluid, airflow, and exhaust systems. As original equipment manufacturers (OEMs) and tier suppliers navigate supply chain recalibrations and material cost volatilities, access to precise, forward-looking market intelligence is no longer optional; it is a strategic imperative.
Our latest comprehensive research report, Worldwide Automotive Clamp Market, equips industry leaders with the analytical depth required to make informed decisions in 2026 and beyond. This article provides a strategic preview of the market trajectory, competitive dynamics, and operational forces shaping the sector, demonstrating why a granular understanding of this market is essential for capital allocation, product development, and regional expansion planning.
The Macro Trajectory: Sustained Growth Anchored by Engineering Evolution
The global automotive clamp market has demonstrated remarkable resilience and steady expansion over the past half-decade. Historical revenue data from 2020 through 2025 reveals consistent upward momentum, with the sector crossing the four-billion-dollar threshold and establishing a robust baseline for future growth. Looking ahead, the forecast period spanning 2026 to 2032 projects a compound annual growth rate of 4.6 percent, reflecting sustained demand across internal combustion, hybrid, and next-generation electric vehicle platforms.
While headline revenue figures provide a useful compass, the true value of our research lies in the underlying structural drivers. Market expansion is not merely a function of vehicle production volumes; it is increasingly dictated by engineering pivots. As automakers transition toward higher-voltage thermal management architectures and adopt advanced exhaust gas recirculation strategies, the specifications demanded of clamping solutions are evolving. Growth is thus bifurcated: traditional volume-driven demand from established platforms continues to anchor baseline revenues, while specialized, high-performance clamping technologies are capturing premium margins in emerging applications. Understanding how these two streams interact—and where capital should be deployed to capture the higher-yield segment—is a central focus of our analysis.
Decoding the Product and Application Landscape
Automotive clamps are far from commoditized fasteners. The market is segmented across multiple product architectures, each engineered to address distinct operational environments. Worm gear clamps remain a cornerstone for general-purpose fluid and cooling line connections, valued for their adjustable torque characteristics and broad OEM acceptance. Spring and constant-tension clamps have gained significant traction in charge-air, turbocharging, and high-vibration environments where maintaining sealing integrity under thermal cycling is paramount. T-bolt and V-band configurations dominate heavy-duty exhaust and high-temperature manifold applications, while ear clamps serve precision fluid routing needs in compact engine bays and electrified thermal loops.
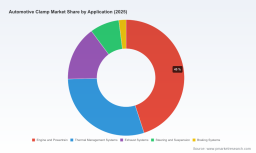
The application matrix further illustrates how clamping requirements are diverging. Engine and powertrain systems continue to represent the largest demand pool, but the rapid proliferation of battery thermal management, inverter cooling circuits, and cabin HVAC integration is reshaping consumption patterns. Exhaust systems remain heavily dependent on high-temperature profile and V-band solutions, particularly as emissions regulations push back-pressure and catalyst efficiency thresholds higher. Even steering, suspension, and braking subsystems—historically niche consumers of clamping hardware—are seeing incremental demand as vehicle architectures integrate more hydraulic and electronic control lines.
Worldwide Automotive Clamp Market
Our report dissects these segments with granular revenue tracking, volume-to-value conversion analysis, and cross-segment substitution trends. Readers will gain clarity on which product families are experiencing margin compression due to standardization, and which specialized geometries are commanding price premiums as OEMs prioritize reliability over lowest-bit cost. We deliberately refrain from publishing exact regional or application-level breakdowns in this preview; those granular matrices are reserved for clients who require precise portfolio alignment and go-to-market targeting.
Competitive Dynamics: A Consolidated Field of Specialized Leaders
The automotive clamp sector is characterized by a moderately concentrated competitive landscape, where scale, engineering heritage, and certification compliance act as formidable barriers to entry. A handful of established manufacturers command roughly half of total industry revenue, leveraging long-standing OEM relationships, globally distributed production footprints, and continuous process automation. Yet the market is far from static. Mid-tier specialists and regional producers continue to carve out defensible niches by focusing on custom torque profiles, rapid prototyping, or high-volume standardized lines for cost-sensitive platforms.
European firms have historically set the benchmark for engineered joining technologies, particularly in worm-drive, constant-tension, and high-temperature profile clamps designed for demanding European powertrain and exhaust architectures. Swiss manufacturers have built reputations around precision pinch and spring band clamps that prioritize vibration resistance and rapid assembly on automated line systems. North American players contribute deep domain expertise across worm gear, T-bolt, and constant-torque solutions, often serving both passenger vehicle and heavy-duty truck segments with modular product families that can be rapidly adapted to fluid, fuel, and exhaust requirements.
In Asia-Pacific and emerging manufacturing hubs, production capabilities have matured significantly. Several Indian and Taiwanese suppliers now export globally, offering standardized worm-drive, T-bolt, and spring-loaded configurations that align with price-sensitive OEM programs without sacrificing baseline durability. Meanwhile, American-owned manufacturing operations in China and specialized stainless-steel coupling producers in the United States are bridging the gap between performance-grade materials and cost-efficient scale.
Recent corporate developments underscore the strategic agility required to compete. One major European manufacturer expanded automated clamp production lines in early 2025, boosting manufacturing capacity by nearly twenty percent to absorb surging demand from updated cooling and exhaust platforms. A prominent North American supplier subsequently widened its global distribution networks, increasing international supply coverage by more than thirty percent and positioning itself to capture cross-border program wins. Simultaneously, a lightweighting-focused product launch in mid-2025 introduced clamps that reduce component weight by approximately fifteen percent, directly addressing OEM targets for mass reduction and improved overall vehicle efficiency.
Our competitive analysis maps these moves against pricing strategies, capacity utilization rates, and regional program win rates, providing a clear picture of who is gaining share, where margin erosion is most acute, and which suppliers are best positioned to benefit from electrification-driven redesign cycles.
Forces Reshaping the Value Chain: Materials, Regulations, and Performance Demands
Three interlocking forces are redefining competitive advantage in the automotive clamp sector. First, raw material economics exert continuous pressure on cost structures. Steel and stainless steel constitute nearly seventy percent of production inputs for automotive clamps, and price volatility in these commodities can inflate manufacturing costs by fifteen to twenty percent in any given cycle. Suppliers that fail to hedge material exposure, optimize scrap rates, or transition efficiently to alternative alloys risk margin erosion, particularly when OEMs push back on price increases during program renegotiations.
Second, regulatory and quality compliance frameworks are becoming increasingly stringent. Automotive clamps must satisfy IATF 16949 quality management standards and, for worm-drive types, meet SAE J1508 specifications to guarantee reliable performance under vibration, pressure fluctuations, and extreme temperature ranges. Non-compliance is not merely a technical risk; it results in program disqualification, warranty exposure, and reputational damage. Suppliers with robust certification portfolios and documented process controls hold a distinct advantage when qualifying for next-generation vehicle platforms.
Third, engineering performance requirements are escalating. Constant-tension and spring-loaded designs are increasingly specified to accommodate thermal expansion and contraction in cooling and charge-air systems, ensuring long-term sealing integrity without overtightening or relaxation. High-temperature profile clamps engineered to withstand component temperatures approaching nine hundred degrees Celsius are becoming essential for modern exhaust and turbocharger architectures. Meanwhile, lightweighting trends are accelerating the adoption of advanced materials and thinner-gauge constructions, enabling overall vehicle weight reduction that directly improves fuel economy in internal combustion platforms and extends driving range in electric vehicles.
These forces do not operate in isolation. A supplier that masters material cost mitigation, maintains rigorous certification compliance, and delivers thermally optimized, lightweight clamping solutions simultaneously will capture disproportionate value in the coming years. Our report quantifies these capability gaps and maps which competitors are best positioned to navigate the intersection of cost, compliance, and performance.
What the Report Delivers: Actionable Intelligence for 2026 Decision-Making
The Worldwide Automotive Clamp Market report is structured to serve as a practical decision-support tool rather than a static data repository. Key deliverables include:
Hose Clamps Market
- Baseline and forecast revenue tracking from 2020 through 2032, with clear delineation of historical performance versus projected trajectories under multiple adoption scenarios.
- Detailed segmentation analysis across product types and end-use applications, highlighting volume-to-value ratios, substitution patterns, and margin characteristics for each category.
- Regional market structure evaluation, identifying where production localization, import dependency, and OEM consolidation are reshaping supply-demand balances.
- Competitive benchmarking of leading manufacturers, including capacity expansion timelines, distribution network growth, product launch cadence, and program-win positioning.
- Value chain mapping that tracks raw material exposure, manufacturing process automation trends, and logistics bottlenecks affecting lead times and cost-to-serve.
- Regulatory and technical compliance checklists, ensuring that strategic planning accounts for IATF 16949, SAE J1508, and evolving thermal and pressure testing requirements.
- Scenario-based strategic recommendations for suppliers, OEMs, and tier-one partners seeking to optimize sourcing strategies, portfolio mix, and regional footprint.
Each section is designed to translate market data into executable strategy. Whether the objective is to evaluate a potential acquisition target, calibrate production capacity for a new clamp geometry, or identify underserved application niches in electrified thermal management, the report provides the evidentiary foundation required to move with confidence.
Why This Intelligence Matters Now
2026 represents a pivotal inflection point. Vehicle architectures are being finalized for production cycles that will extend well into the next decade, and clamping specifications locked in today will dictate cost structures, assembly line efficiency, and long-term reliability outcomes. Organizations that delay strategic planning until program launches are already behind; those that integrate market intelligence into portfolio planning, sourcing negotiations, and R&D prioritization will secure a compounding advantage.
Material volatility, regulatory complexity, and performance escalation are not temporary headwinds; they are structural features of the modern automotive supply chain. The ability to anticipate how these forces will redistribute value across product segments, geographic markets, and competitor portfolios is precisely what separates reactive suppliers from proactive market leaders.
Navigate the Outlook with Precision
The Worldwide Automotive Clamp Market report offers a complete, data-rich map of a sector in transition. From historical baselines and multi-year forecasts to competitive positioning, material economics, and technical compliance requirements, every insight is calibrated for executive decision-making. We have outlined the macro trajectory, the competitive architecture, and the operational forces reshaping the industry; the full report goes further, delivering the precise segment-level revenue matrices, regional growth differentials, and company-specific capability assessments that inform capital allocation and strategic prioritization.
To access the complete dataset, detailed segmentation breakdowns, and proprietary competitive benchmarking, visit the official research page for Worldwide Automotive Clamp Market. Equip your team with the intelligence required to turn market complexity into strategic clarity.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Clamp Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com