

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Mobile UC&C Hits $27.78B in 2025, Forecast to $85.99B by 2032 at 17.52% CAGR

Navigating the Mobile Unified Communications and Collaboration Landscape: Strategic Imperatives for 2026 and Beyond
The enterprise communication paradigm has undergone a fundamental transformation. What began as a response to remote work requirements has matured into a permanent architectural shift in how organizations connect, collaborate, and serve customers. Mobile unified communications and collaboration (UCC) is no longer a peripheral capability—it is the backbone of modern enterprise operations. As we enter 2026, leadership teams face a market characterized by accelerating consolidation, AI-driven feature expansion, and intensifying regulatory scrutiny. Understanding the trajectory of this market is not merely an exercise in forecasting; it is a strategic necessity for technology procurement, competitive positioning, and long-term organizational resilience.
Our latest Worldwide Mobile Unified Communications and Collaboration Market study delivers the comprehensive intelligence that executives, investors, and technology strategists require to navigate this complex environment. Drawing on extensive primary research, supplier interviews, and granular demand-side analysis, this report maps the market from its historical foundations through a detailed forecast period extending to the end of the decade. What follows is an overview of the strategic insights contained within, designed to demonstrate the report's value as a decision-support instrument.
The Macro Trajectory: A Market Defined by Sustained Acceleration
The numbers tell a story of relentless growth. From a baseline in the mid-2020s, the global mobile UCC market has expanded at a pace that has consistently outpaced traditional enterprise software categories. Historical data from the early 2020s through the present reveals a compound annual growth rate that underscores the structural demand underpinning mobile collaboration tools. The market has surpassed significant thresholds, with total revenue climbing from approximately $11.8 billion in 2020 to over $27.7 billion by 2025.
Worldwide Mobile Unified Communications and Collaboration Market
Looking forward, the trajectory remains steep. The study projects that market expansion will continue at a compound annual growth rate of 17.52 percent across the forecast horizon, with revenues projected to approach $33.4 billion in 2026 and steadily climb toward the $86 billion mark by 2032. This sustained growth reflects more than cyclical recovery; it signals the deep integration of mobile UCC capabilities into enterprise workflows, customer engagement models, and regulatory compliance frameworks. Decision-makers must understand that this growth is not diffuse—it is concentrated around specific solution categories and vertical applications that our report dissects in detail.
Such magnitude of expansion carries profound implications. Infrastructure investment, vendor partnerships, licensing strategies, and workforce training must all be calibrated against a market that is growing nearly twice as fast as many adjacent technology segments. Organizations that fail to align their communication architectures with this growth trajectory risk falling behind competitors who are leveraging mobile collaboration as a productivity and innovation multiplier.
Strategic Segmentation: Where Growth Is Concentrated
The headline figures, while compelling, only tell part of the story. The true strategic value of our analysis lies in its breakdown of the market across multiple dimensions—solution types, end-user verticals, and geographic regions—each revealing distinct demand drivers, competitive intensity, and adoption barriers.
Solution-Level Dynamics
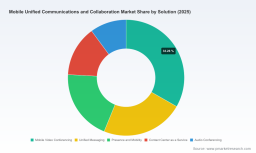
Within the solution landscape, mobile video conferencing and unified messaging represent the largest revenue pools, reflecting the enduring demand for rich, synchronous collaboration and the continued migration of legacy messaging systems to cloud-native platforms. Presence and mobility solutions, while smaller in absolute terms, serve as critical enablers for workforce agility, allowing organizations to maintain context-aware collaboration regardless of device or location. Contact center as a service (CCaaS) and audio conferencing round out the solution mix, with the former experiencing particular momentum as enterprises rebuild customer engagement infrastructures around digital-first, mobile-optimized experiences.
The report does not merely list these categories; it evaluates them. Our analysis examines the pricing dynamics, feature differentiation, integration requirements, and adoption curves that define each solution segment. For procurement leaders, this means being able to identify which capabilities warrant premium investment and which can be sourced from commoditized providers. For product strategists, it means understanding where feature gaps are likely to emerge and where consolidation pressure will intensify.
Vertical-Specific Demand Patterns
No enterprise communication strategy exists in a vacuum. Different industries face different regulatory environments, workforce structures, and customer engagement models, all of which shape their mobile UCC requirements. The IT and telecommunications sector remains the largest consumer of mobile UCC capabilities, driven by internal collaboration needs and the requirement to support customer-facing communication infrastructure. The BFSI sector follows closely, with compliance mandates, secure communication requirements, and the need for seamless omnichannel customer interactions driving significant investment.
Healthcare organizations are increasingly adopting mobile UCC platforms to support telemedicine workflows, clinician collaboration, and patient engagement—all while navigating stringent data protection regulations. Government and public sector entities face their own unique pressures, including the need for sovereign infrastructure, disaster recovery capabilities, and secure inter-agency communication. Retail and manufacturing organizations are leveraging mobile UCC to connect distributed workforces, streamline supply chain coordination, and enhance customer service operations. Educational institutions round out the vertical landscape, with hybrid learning models driving sustained demand for mobile video and messaging capabilities.
Our report provides a detailed examination of each vertical, analyzing not just current spend levels but the underlying drivers, barriers, and growth catalysts that will shape adoption over the forecast period. This vertical lens is essential for organizations seeking to benchmark their own communication strategies against industry peers and for vendors aiming to refine their go-to-market motions.
Geographic Dispersion and Infrastructure Realities
The global nature of this market means that regional dynamics play an outsized role in shaping both demand and competitive intensity. Our analysis segments the market across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, revealing how infrastructure maturity, regulatory environments, and enterprise digitization rates influence adoption patterns.
North America and Europe represent mature, high-spend markets where competition is fierce and differentiation increasingly hinges on AI capabilities, ecosystem integration, and regulatory compliance. Asia Pacific presents a high-growth opportunity shaped by rapid enterprise digitization, expanding mobile broadband coverage, and the emergence of local champions alongside global vendors. Latin America and the Middle East and Africa reflect markets in earlier stages of adoption, where infrastructure development—particularly around broadband capacity and mobile network evolution—will determine the pace of UCC deployment.
Decision-makers must be careful not to treat these regions as monolithic. Our report provides the granularity needed to understand the specific demand drivers, competitive dynamics, and infrastructural prerequisites that define each regional market. Organizations operating across multiple geographies will find this analysis invaluable for tailoring their communication strategies to local realities while maintaining global operational coherence.
Competitive Dynamics: Navigating a Consolidating Field
The competitive landscape for mobile UCC is characterized by a mix of established platform giants, specialized UCaaS providers, and infrastructure players seeking to extend their relevance into the collaboration layer. The report includes detailed profiles of the key companies shaping this market, examining their product portfolios, partnership strategies, and recent strategic moves.
Microsoft Corporation continues to leverage its Microsoft 365 ecosystem to embed Teams as a comprehensive mobile UCC platform, with recent feature releases— including the bundling of intelligent recaps and sentiment analysis for premium subscribers—demonstrating the company's commitment to differentiating through AI. Cisco Systems, Inc. maintains a strong position through Webex and Unified Communications Manager, with strategic acquisitions such as Lightico expanding its contact center capabilities into e-signature and document collection workflows. Zoom Video Communications, Inc. remains a formidable force in mobile video and collaboration, with its Zoom Workplace and Zoom Phone offerings continuing to attract enterprises seeking streamlined, high-quality video experiences.
RingCentral, Inc. has positioned its cloud-based RingCentral MVP platform as a comprehensive UCaaS solution, while its recent unveiling of the AIR Pro agentic voice AI platform signals a strategic push into AI-driven customer engagement. 8x8, Inc. offers its XCaaS platform as a unified cloud delivery model spanning communications, contact center, and collaboration, optimized for mobile access. Avaya Inc. and Mitel Networks Corporation continue to serve enterprise and hybrid environments with their respective experience platforms and hybrid UC solutions, each emphasizing continuity and control for organizations navigating mixed deployment models.
Alcatel-Lucent Enterprise, Verizon Communications Inc., Google LLC, NEC Corporation, and Nextiva round out the competitive field, each bringing distinct positioning—from enterprise networking integration and mobile connectivity bundling to workspace collaboration suites and all-in-one UCaaS platforms. The report provides a comparative analysis of these players, evaluating their market share positions, strategic differentiation, and the implications of their recent developments for enterprise buyers.
A critical insight from our competitive analysis is the high level of market concentration. The data indicates that a relatively small number of players command a significant share of total market revenue, with the top three firms accounting for over 44 percent of the market and the top five collectively capturing nearly 60 percent. This concentration has important implications for procurement leverage, vendor risk management, and the pace of innovation. Enterprise buyers must understand how concentration affects pricing dynamics, integration ecosystems, and the likelihood of future consolidation.
Regulatory and Infrastructure Currents Shaping the Market
No analysis of the mobile UCC market would be complete without addressing the regulatory and infrastructural forces that are reshaping the operating environment. In 2024, regulatory reclassification efforts by the FCC regarding broadband Internet access services introduced new complexities, though subsequent legal challenges have created uncertainty about the ultimate regulatory framework. Simultaneously, the transformation of the Disaster Information Reporting System from voluntary to mandatory compliance in 2025 has raised the bar for provider resilience and reporting obligations, with direct implications for UCaaS and mobile communication providers.
On the infrastructure front, network capacity expansions are enabling the multi-gigabit speeds that mobile UCC applications increasingly require. Spectrum expansions, high-split architectures, Distributed Access Architecture deployments, and DOCSIS 4.0 rollouts are all contributing to the broadband foundation that supports seamless mobile collaboration. At the same time, European telecom operators are investing in sovereign infrastructure pathways, including evolution paths for SIP applications, unified communications, and IP Multimedia Subsystem components, in response to data sovereignty and security concerns. These developments are not peripheral—they directly influence the performance, compliance posture, and total cost of ownership of mobile UCC deployments.
The FCC's ongoing efforts to identify and make available mid-band spectrum for mobile broadband and advanced wireless services further underscore the infrastructural dependencies that underpin mobile UCC performance. Our report contextualizes these regulatory and infrastructure developments within the broader market dynamics, helping decision-makers anticipate compliance requirements, assess infrastructure readiness, and evaluate vendor claims about network performance and security.
What the Full Study Delivers: A Roadmap for Informed Decision-Making
The Worldwide Mobile Unified Communications and Collaboration Market study is designed to serve as a comprehensive decision-support instrument for a wide range of stakeholder groups. Technology procurement leaders will find the detailed segmentation analysis essential for aligning license investments with actual usage patterns and vertical-specific requirements. Competitive intelligence teams will benefit from the granular profiling of key players, recent developments tracking, and market concentration metrics that reveal the structural dynamics of the competitive field. Investor and financial analysts will find the historical-to-forecast revenue trajectory, CAGR analysis, and regional breakdowns critical for modeling growth scenarios and assessing market opportunity.
Push-To-Talk Market
Beyond these core analytical components, the report includes actionable strategic recommendations, demand-side survey insights, and scenario-based forecasting that account for varying assumptions about macroeconomic conditions, regulatory outcomes, and technology adoption rates. The study also examines the impact of agentic AI platforms, hybrid deployment models, and sovereign infrastructure requirements on the competitive positioning of major vendors—topics that are rapidly becoming central to enterprise UCC strategy discussions.
Every section of the report is built on primary research, validated supplier data, and rigorous demand modeling. The result is a resource that goes beyond descriptive market sizing to provide the analytical depth required for strategic planning, budget allocation, and competitive positioning.
Why 2026 Demands Deeper Intelligence
As we move deeper into 2026, the window for passive observation of the mobile UCC market has closed. Organizations are making procurement decisions that will shape their communication architecture for years to come. Vendors are executing product roadmaps and acquisition strategies that will determine competitive positioning for the remainder of the decade. Regulatory frameworks are evolving in ways that will affect compliance costs, data handling requirements, and network performance expectations.
In this environment, surface-level market awareness is insufficient. Decision-makers need access to detailed segmentation data, competitive benchmarking, vertical-specific adoption analysis, and forward-looking scenario modeling. They need to understand not just where the market is headed, but why it is headed there, what the key variables are, and how different strategic choices will play out across varying conditions.
Our full study provides this depth. It delivers the granular data, the competitive intelligence, and the strategic framing that executives need to make informed, confident decisions. The summary insights presented here offer a glimpse of the analysis contained within, but the complete picture—complete with detailed segmentation breakdowns, supplier profiles, regional dynamics, and forecast scenarios—awaits those who engage with the full report.
To access the complete Worldwide Mobile Unified Communications and Collaboration Market study, including all segmentation data, competitor profiles, regional analyses, and strategic recommendations, visit our research portal. The full intelligence is available now, and the strategic advantage it provides begins with a single decision to dig deeper.
For detailed analysis of this topic, please visit the official page: Worldwide Mobile Unified Communications and Collaboration Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com