

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global AI Infrastructure Market to Hit $1.68T by 2032, 27.14% CAGR

Navigating the 2026 AI Infrastructure Supercycle: Strategic Intelligence for Enterprise Decision-Makers
The global artificial intelligence infrastructure market has entered a phase of unprecedented expansion, fundamentally reshaping how enterprises approach technology investment, capital allocation, and competitive positioning. As organizations worldwide race to deploy generative AI workloads, build sovereign cloud capabilities, and optimize inference economics, the need for rigorous, forward-looking market intelligence has never been more critical. Our latest Worldwide Modern AI Infrastructure Market research offers a comprehensive analytical framework designed specifically to guide executive decision-making through the 2026-2032 forecast period.
Worldwide AI GPU Market
The market has demonstrated remarkable momentum over the past five years, with total revenue climbing from $142.8 billion in 2023 to $312.6 billion in 2025. This trajectory reflects not merely cyclical demand but a structural transformation in how computational resources are procured, deployed, and monetized. Looking ahead, the forecast period projects continued acceleration, with market valuation expected to surpass $1 trillion by the end of the decade. The compound annual growth rate of 27.14 percent underscores the intensity of this expansion, yet raw figures alone tell only part of the story. The real strategic challenge lies in understanding the underlying composition of growth, the competitive forces shaping supply dynamics, and the operational constraints that will determine which organizations capture value and which face costly delays.
This research brief serves as an introduction to our full market study. It outlines the analytical architecture of the report, highlights the competitive and regulatory forces currently reshaping the landscape, and demonstrates how executives can translate granular intelligence into actionable capital and procurement strategies. As you review the insights that follow, consider how systematic exposure to these dynamics will influence your organization's infrastructure roadmap, vendor selection criteria, and risk mitigation frameworks.
Market Architecture: Component, Deployment, and Regional Dynamics
A rigorous understanding of the modern AI infrastructure market requires disaggregating revenue flows across three fundamental dimensions: component categories, deployment models, and geographic distribution. Each dimension reveals distinct growth drivers, pricing pressures, and procurement considerations that collectively determine the shape of enterprise investment portfolios.
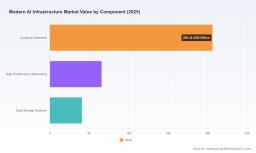
Within the component landscape, compute hardware dominates the revenue composition, reflecting the relentless demand for accelerator chips, high-performance networking equipment, and specialized data storage systems. Organizations building training clusters or scaling inference endpoints must navigate a complex procurement environment where silicon availability, interconnect bandwidth, and storage throughput intersect with total cost of ownership calculations. High-performance networking has emerged as a critical enabler, as the latency and throughput requirements of distributed AI workloads place unprecedented strain on cluster interconnects. Data storage systems, while representing a smaller share of overall revenue, are experiencing structural growth as enterprises architecting retrieval-augmented generation pipelines and vector databases require low-latency, high-capacity storage layers that can sustain continuous inference operations.
The deployment dimension further clarifies where capital is flowing and where innovation is concentrated. Hyperscale and public cloud environments command the largest share of infrastructure spending, driven by the scale economics of major cloud providers and the flexibility they offer enterprises migrating AI workloads without upfront capital expenditure. Enterprise data centers represent a significant and growing segment, as organizations with sensitive data requirements, regulatory constraints, or existing on-premises investments pursue hybrid architectures that balance performance with data sovereignty. Edge AI infrastructure, while currently the smallest deployment category by revenue, is attracting strategic attention from organizations seeking to reduce inference latency, mitigate cloud egress costs, and deploy AI capabilities in environments where continuous connectivity cannot be guaranteed.
Geographic distribution reveals the uneven pace of infrastructure buildout across global markets. North America continues to anchor a substantial portion of worldwide revenue, supported by concentrated hyperscaler investment, mature semiconductor supply chains, and a dense ecosystem of AI-native startups. Asia Pacific represents the second-largest regional revenue pool, fueled by sovereign AI initiatives, rapidly expanding cloud capacity, and the manufacturing ecosystem that underpins global chip production. Europe, the Middle East and Africa, and Latin America each present distinct adoption profiles shaped by local regulatory frameworks, energy availability, and the maturity of domestic cloud and colocation markets. Our full report maps these regional dynamics in detail, providing the granular context necessary to calibrate market entry strategies, partnership decisions, and localized procurement plans.
Competitive Intensity and Vertical Specialization
The competitive landscape of the modern AI infrastructure market is defined by a small number of dominant players commanding significant market concentration, alongside a growing cohort of specialized firms advancing adjacent layers of the stack. Understanding this structure is essential for executives evaluating supplier risk, negotiating long-term contracts, and anticipating shifts in pricing and availability.
At the foundation of the compute layer, NVIDIA Corporation maintains a commanding position through its integrated portfolio of graphics processing units, networking technologies, and software ecosystems that have become de facto standards for large-scale AI training and inference. The company's product roadmap, including successive generations of accelerator architectures and high-speed interconnect solutions, continues to set performance benchmarks that shape enterprise procurement cycles. Advanced Micro Devices Corporation has carved out a meaningful competitive position through its MI-series accelerators and high-performance computing solutions, offering alternative silicon paths for organizations seeking to diversify their supplier base or optimize workload-specific performance. Intel Corporation continues to advance its AI infrastructure capabilities through accelerator architectures, central processing unit platforms, and specialized inference technologies designed for data center environments.
Networking and interconnect technologies represent another critical competitive frontier. Broadcom Inc. supplies high-speed networking chips, application-specific integrated circuits, and custom silicon that are indispensable for interconnecting GPU clusters at hyperscale. Arista Networks provides high-speed Ethernet switching platforms engineered for ultra-low latency AI cluster interconnects, addressing the stringent networking requirements of distributed training workloads. These suppliers operate at the intersection of performance and reliability, where incremental improvements in throughput or latency can translate into material differences in training time and inference responsiveness.
On the cloud and infrastructure services side, hyperscale providers dominate the deployment landscape. Amazon Web Services delivers AI infrastructure through elastic compute instances, custom accelerator chips, and managed services that streamline model training and deployment. Microsoft Corporation's Azure platform provides extensive GPU capacity, custom silicon investments, and integrated cloud services tailored to enterprise and hyperscale AI workloads. Alphabet Inc.'s Google Cloud Platform leverages custom tensor processing unit accelerators and infrastructure optimized for large-scale training and inference. Oracle Corporation has expanded its cloud infrastructure capacity through significant financing commitments, targeting major AI customers with bare-metal GPU clusters and dedicated cloud services. These hyperscalers collectively represent a defining force in infrastructure economics, influencing pricing, availability, and the pace at which new capabilities reach enterprise customers.
Specialized providers are also reshaping the market. TSMC, as the leading semiconductor foundry, manufactures advanced AI chips and accelerators for multiple industry participants, making it a critical node in the global supply chain. CoreWeave operates as a specialized GPU cloud provider, offering high-density infrastructure clusters optimized for training and inference workloads. Vertiv Holdings Co. delivers power management, thermal management, and liquid cooling solutions that address the intensifying energy and cooling demands of high-density AI data centers. Equinix enables private and hybrid AI infrastructure deployments through global colocation and interconnection services. Cerebras Systems develops wafer-scale accelerators designed for large-scale model training, while Groq focuses on inference-optimized language processing units engineered for high-speed deployment scenarios.
Recent developments underscore the velocity of competitive and strategic activity. In early 2026, four major hyperscalers signaled combined capital expenditure guidance approaching $650-690 billion for the year, concentrated heavily on AI infrastructure and data center expansion. NVIDIA advanced significant investments and GPU supply agreements with leading AI models developers as part of major infrastructure buildouts. Oracle announced plans to raise substantial debt and equity financing in 2026 to expand cloud infrastructure capacity serving prominent AI customers. These capital commitments signal a multi-year construction and procurement cycle that will influence equipment availability, pricing dynamics, and the strategic positioning of infrastructure providers for years to come.
Market Dynamics: Power, Regulation, and Efficiency Imperative
Beyond component architecture and competitive positioning, the modern AI infrastructure market is being reshaped by structural constraints and regulatory developments that carry direct implications for deployment timelines, cost structures, and strategic risk. Executives who internalize these dynamics early will be better positioned to navigate procurement delays, negotiate favorable terms, and align infrastructure plans with evolving compliance requirements.
Power availability has emerged as the most consequential bottleneck for AI data center deployment. Electrical infrastructure constraints, including large power transformers with multi-year lead times and grid interconnection queues that now exceed 2,100 gigawatts, have created a capacity shortfall that threatens to delay a significant portion of planned 2026 capacity into 2028. This reality forces organizations to confront the fact that AI infrastructure planning can no longer be divorced from energy strategy. Executives must evaluate site selection criteria, power procurement contracts, and the potential role of on-site generation or advanced cooling technologies as integral components of infrastructure roadmaps rather than peripheral considerations.
Material intensity further compounds deployment complexity. Each megawatt of AI data center capacity requires approximately 27 tons of copper for wiring and cooling systems, placing additional strain on global supply chains already navigating constraints in power infrastructure components. These material requirements interact with lead times, logistics costs, and geopolitical supply chain risks, creating a procurement environment where early contracting and diversified sourcing strategies can yield meaningful competitive advantage.
Regulatory frameworks are simultaneously reshaping the market landscape. The U.S. Bureau of Industry and Security maintains export controls on advanced computing integrated circuits and, for the first time, on frontier AI model weights exceeding 10 to the 26th power of operations. These controls require licenses for transfers involving potential military-intelligence end uses in designated country groups, introducing compliance complexity for organizations engaged in cross-border collaboration, model sharing, or hardware deployment. Updated export control measures also address advanced computing items and AI model weights with case-by-case licensing provisions for certain shipments, creating a regulatory environment that demands ongoing monitoring and adaptive procurement strategies.
Standardization efforts provide additional context for infrastructure evaluation. The ISO/IEC 30134 series defines key performance indicators for data center resource efficiency, including power usage effectiveness, water usage effectiveness, and carbon usage effectiveness. These metrics are increasingly used to benchmark the energy consumption of AI-driven facilities, influencing procurement criteria, investor expectations, and regulatory scrutiny. Organizations that embed efficiency metrics into their infrastructure planning and vendor evaluation processes will be better positioned to demonstrate operational responsibility and manage long-term operational costs.
Worldwide Modern AI Infrastructure Market
On the innovation frontier, modular and specialized approaches are gaining traction. Recent patent allowances covering canopy-based distributed edge AI data centers with modular GPU cartridges, liquid cooling, and advanced power management illustrate the industry's exploration of alternative deployment architectures capable of scaling to massive GPU counts. These developments signal a broadening of design thinking around how AI infrastructure can be architected for density, efficiency, and flexibility, themes that our full report examines in depth.
What the Full Report Delivers: From Macro Trends to Operational Strategy
The Worldwide Modern AI Infrastructure Market research is structured to translate high-level market intelligence into decision-grade insights. Rather than offering static snapshots, the report integrates historical performance data, forward-looking forecasts, segmentation analysis, and competitive assessment into a cohesive framework that executives can apply directly to capital planning, vendor negotiations, and risk management.
The report begins with a robust market sizing and forecast methodology, anchoring historical revenue data from 2020 through 2025 and extending projections through 2032. This temporal span enables readers to evaluate growth trajectories against multiple scenarios, assess the durability of demand drivers, and calibrate internal forecasts against externally validated market estimates. Revenue projections are presented in a format that supports scenario planning, allowing organizations to model capital allocation under varying assumptions about deployment pace, pricing dynamics, and supply availability.
Segmentation analysis provides the granularity necessary to understand where growth is concentrated and where pricing or availability pressures are most acute. Readers gain visibility into component-level revenue composition, deployment model trends, and regional distribution patterns, enabling targeted evaluation of procurement categories, partnership opportunities, and geographic expansion considerations. The segmentation framework is designed to support cross-functional decision-making, bridging the perspectives of engineering, procurement, finance, and strategy teams.
The competitive analysis section profiles the core companies shaping the market, examining their product portfolios, strategic positioning, recent developments, and implications for enterprise customers. By evaluating supplier capabilities, capital commitments, and competitive dynamics, the report equips readers to assess supplier risk, identify alternative sourcing paths, and anticipate shifts in the supply landscape that may affect procurement timelines or pricing.
Regulatory and operational dynamics are integrated throughout the analysis, ensuring that market projections are contextualized within the constraints that actually govern deployment. Discussions of power availability, grid interconnection queues, material intensity, export controls, and efficiency standards are woven into the market narrative rather than appended as afterthoughts, reflecting the reality that these factors are inseparable from infrastructure strategy.
Strategic Imperatives for 2026 Executive Decision-Making
As organizations navigate the current phase of AI infrastructure expansion, several strategic imperatives emerge from the market evidence. First, capital allocation must be grounded in a clear-eyed assessment of deployment bottlenecks, particularly power availability and grid interconnection timelines, rather than assuming that equipment procurement alone determines project velocity. Early engagement with power providers, proactive site evaluation, and realistic scheduling buffers are essential to avoiding costly delays.
Second, supply chain resilience requires deliberate diversification and long-term contracting where feasible. Given the concentration of market revenue among a small number of dominant suppliers and the intensity of capital expenditure across hyperscale and enterprise buyers, equipment availability and pricing will remain volatile. Organizations that establish clear supplier evaluation criteria, maintain alternative sourcing options, and align procurement timing with realistic deployment schedules will be better insulated against disruptions.
Third, regulatory compliance and efficiency considerations must be embedded into infrastructure planning from the outset. Export control frameworks, model weight restrictions, and efficiency benchmarking standards are evolving rapidly, and organizations that treat these factors as peripheral compliance tasks risk encountering delays, cost overruns, or reputational exposure. Integrating regulatory monitoring and efficiency metrics into infrastructure evaluation processes strengthens both operational resilience and strategic positioning.
Fourth, competitive intelligence should inform partnership and vendor selection decisions. The market is characterized by intense investment activity, product roadmap acceleration, and strategic partnerships that reshape supply dynamics. Organizations that maintain awareness of supplier financing plans, capacity commitments, and technology investments will be better positioned to negotiate favorable terms and align infrastructure choices with long-term strategic objectives.
Conclusion: Turning Market Intelligence into Strategic Advantage
The Worldwide Modern AI Infrastructure Market research is designed to provide the analytical depth, segmentation clarity, and competitive context that executives need to make informed decisions in a rapidly evolving market. The macro trajectory is clear: total market revenue has expanded dramatically over the past two years and is projected to continue its ascent through 2032, driven by sustained demand for compute hardware, high-performance networking, data storage, and diverse deployment models across global regions. Yet the strategic value of this research lies not in confirming that the market is growing, but in illuminating the structural forces, competitive dynamics, and operational constraints that will determine how individual organizations capture value within that growth.
Market concentration among leading suppliers, the intensity of hyperscaler capital expenditure, the persistence of power and grid interconnection bottlenecks, and the evolution of regulatory frameworks collectively create a landscape where disciplined intelligence translates directly into competitive advantage. Organizations that approach infrastructure planning with a clear understanding of these dynamics will be better equipped to sequence investments, negotiate effectively, manage risk, and align technology deployment with broader business objectives.
The full report provides the comprehensive data, segmentation detail, competitive profiles, and forward-looking analysis necessary to support these decisions. We invite you to explore the complete research on our website, where you will find the full forecast tables, regional breakdowns, supplier assessments, and dynamic scenario analysis that underpin the insights summarized here. In a market moving at this pace, timely and rigorous intelligence is not merely an informational asset; it is a strategic necessity.
For detailed analysis of this topic, please visit the official page: Worldwide Modern AI Infrastructure Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com