
Blogs
Aquaculture Cages Market: Why 6.8% CAGR and Asia Pacific’s 126.14M Dominance Redefine Market Dynamics
By pmarketresearch, 2026-09-21
Navigating the Aquaculture Cages Market: Strategic Shifts, Competitive Realignment, and Commercial Opportunities
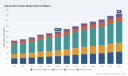
The aquaculture cages market has evolved from a niche equipment segment into a critical infrastructure layer for global protein production. As of 2025, the market stands at approximately $298 billion in revenue, reflecting a steady upward trajectory from $214 billion in 2020. The compound annual growth rate of 6.8 percent through 2032 signals more than linear expansion; it points to a structural shift in how finfish and shellfish are cultivated at scale. Over the next seven years, the market is projected to cross $464 billion, driven by intensifying demand for controlled aquatic production, evolving regulatory expectations, and the gradual replacement of aging cage infrastructure with higher-performing systems. This momentum is not uniform across all segments or geographies, but the underlying direction is clear: aquaculture is moving toward more robust, compliant, and technologically integrated cage architectures.
For executives and investors, the scale of this market is only the starting point. The real strategic value lies in understanding where capital efficiency, regulatory alignment, and technological readiness converge. Cages are no longer passive containment structures; they function as platforms that influence disease exposure, environmental footprint, operational labor, and ultimately, the economic viability of farms. The market’s growth is being shaped by a combination of cyclical replacement cycles, long-term expansion in high-density farming regions, and a growing emphasis on systems that can withstand harsher marine conditions while meeting stricter compliance thresholds. These forces are creating new decision points for manufacturers, farm operators, and capital allocators who must balance short-term procurement costs against long-term operational resilience.
Key Challenges and Inflection Points Shaping the Market
The industry is navigating several structural challenges that will redefine competitive advantage over the next few years. First, environmental compliance and waste management pressures are accelerating the retirement of legacy cage designs. Stricter oversight around water quality, nutrient dispersion, and disease control is pushing operators to adopt cage configurations that support better monitoring, improved water exchange, and reduced localized impact. This transition is not merely a regulatory checkbox; it directly affects permitting timelines, community acceptance, and access to premium buyer channels. Operators that continue to rely on outdated containment approaches face increasing operational friction, while those that modernize early can secure faster approvals and build stronger market positioning.
Second, the durability-versus-cost equation is creating a procurement inflection point. High-density polyethylene (HDPE) cages have become the dominant choice in marine environments because of their resilience under rough sea conditions, flexibility in large-scale deployments, and extended service life. In marine settings, HDPE typically delivers seven to ten years of effective operation, while freshwater applications can stretch that range to ten to fifteen years. This longevity reduces replacement frequency and total cost of ownership, even though the initial material outlay runs 25 to 35 percent higher than alternative options. For farm operators, the decision is increasingly about lifecycle economics rather than upfront price. For equipment suppliers, it means that differentiation is shifting toward proven longevity, corrosion resistance, and ease of maintenance rather than simple cost competition.
Third, regulatory and certification dynamics are reshaping market access. Standards associated with responsible aquaculture practices and environmental stewardship are incentivizing producers to upgrade infrastructure in order to qualify for premium market segments. At the same time, tighter restrictions tied to biomass limits, overfishing concerns, and cage placement rules are introducing constraints that can temper growth in certain regions or applications. These dual pressures create a strategic paradox: compliance and certification open doors to higher-value channels, but they also raise the bar for entry and increase the cost of non-compliant operations. Companies that treat regulatory alignment as a core engineering requirement rather than a downstream compliance task are better positioned to scale without disruption.
Key Drivers of Market Change
The market’s growth trajectory is being propelled by a combination of technological, regulatory, demand-side, and supply-chain forces. Each driver has distinct implications for equipment strategy, risk management, and commercial positioning.
Technological innovation remains one of the most visible catalysts. Manufacturers are moving beyond basic containment toward integrated cage systems that support semi-closed or closed configurations, improved structural stability, and stronger compatibility with monitoring and handling equipment. Recent product supply agreements illustrate this shift in practice. For example, in late 2024, a supplier committed to providing semi-closed fish cages for floating closed cage systems, reinforcing the trend toward containment designs that offer better control over water quality and biological risk. Such arrangements are not isolated transactions; they reflect a broader preference for systems that can reduce environmental leakage, improve biosecurity, and support more predictable production cycles.
Policy and regulatory environments are equally influential. Stringent rules around water quality, waste management, and disease control are making advanced cage designs and integrated monitoring systems more attractive, and in many cases necessary. Certification frameworks and recognized stewardship standards add further momentum by rewarding infrastructure upgrades that unlock premium pricing or preferred supplier status. This regulatory layer is especially important for operators seeking to expand in regions where permitting, environmental impact assessment, and community scrutiny are becoming more rigorous. The practical implication is clear: cage design decisions are increasingly tied to long-term license to operate, not just short-term production needs.
Demand-side behavior is also reshaping the market. Consumers, food retailers, and foodservice buyers are paying greater attention to sourcing practices, environmental impact, and traceability. This shifts commercial value toward producers who can demonstrate consistent quality, lower environmental risk, and more controlled production conditions. Cage systems that support better biological management, reduced escape risk, and cleaner production profiles can become enablers of brand differentiation. For equipment providers, this means that product value is increasingly linked to the operational outcomes their systems help customers achieve, including yield stability, compliance readiness, and market access.
Supply chain and cost structure changes are adding another layer of complexity. Material availability, fabrication capacity, and logistics for large marine-grade components influence both lead times and pricing. The dominance of HDPE reflects not only performance advantages but also a mature supply base that can support large-scale production and replacement programs. At the same time, the higher upfront cost of durable materials requires financing-aware procurement strategies, especially for mid-sized operators. Companies that can offer lifecycle cost clarity, service support, and modular replacement options are gaining an edge in markets where operators need to manage capital constraints while maintaining operational continuity.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a moderate level of concentration, with the top three players accounting for roughly 24.5 percent of the market and the top five reaching about 28.5 percent. This structure suggests a market that is still open to regional specialists and targeted innovators, but where scale, product breadth, and technical credibility increasingly matter. The leading companies are not competing on cage volume alone; they are building differentiated positions around material expertise, structural design, and containment technology.
Several Norwegian and European firms anchor the high-end segment of the market. One global leader has built a strong reputation in plastic pens and cage systems, offering HDPE cages and broader technology solutions for marine and inland fish farming. Its positioning reflects an emphasis on complete system capability rather than isolated component supply. Another European specialist focuses on net cages and submersible cage systems, including models designed for exposed sea sites. This capability highlights a strategic focus on environments where structural stability and containment performance under demanding conditions are critical. A third Norwegian supplier contributes additional differentiation through a broad material range, including nylon, HDPE, Dyneema®, and UHMWPE, across circular, rectangular, and specialized cage formats. This material versatility allows the company to address varied operational conditions and customer preferences, particularly where strength-to-weight characteristics or specific environmental tolerances matter.
Worldwide Fish Farming Equipment Market
In parallel, Mediterranean and Asian manufacturers are expanding the market’s regional depth and cost-performance options. An Italian group has strengthened its portfolio by broadening its aquaculture containment solutions, including a recent acquisition that extended its offer set. This type of consolidation signals a move toward broader solution capabilities and more integrated customer offerings. Chinese manufacturers are also playing a growing role, particularly in offshore HDPE cages and net cage systems for neritic and deeper water applications, alongside suppliers focused on HDPE and related net cage products. Another Chinese manufacturer emphasizes marine and freshwater cage and netting products, reinforcing the region’s broad production capacity. Meanwhile, an Indian manufacturer has carved out a distinct position through high-performance synthetic netting materials and solutions, underscoring the importance of material science in cage durability and performance. A separate Israeli provider illustrates the convergence of cage systems with broader recirculating technology, offering floating closed fish cage systems and integrated approaches that bridge offshore and land-based production needs.
The strategic takeaway is that competition is fragmenting by application environment, material specialization, and system integration. Leading players are differentiating in three main ways: engineering for durability and stability in challenging sea conditions, expanding containment and closed-system capabilities, and broadening portfolios through acquisition or product expansion. At the same time, the moderate concentration levels indicate room for agile entrants, especially those targeting niche applications, specific materials, or regional demand pools. The market is therefore unlikely to consolidate into a single dominant model; instead, it will likely continue to reward companies that can align product strengths with clear operational outcomes and compliance requirements.
Recent corporate activity reinforces this direction. In late 2024, one supplier agreed to continue supplying semi-closed fish cages for floating closed cage systems, indicating renewed demand for containment approaches that improve biological and environmental control. Around the same period, another group completed an acquisition to expand its aquaculture containment solutions portfolio. These moves are not merely incremental; they reflect a strategic preference for broader solution coverage, stronger positioning in higher-value system configurations, and closer alignment with operators seeking more controlled production environments.
Future Trends and Commercial Opportunities
Looking ahead to the 2026–2032 period, three trends are likely to define the market’s next phase of development. The first is the continued shift toward higher-performance, longer-life cage systems in marine and exposed environments. As operations scale and site conditions become more demanding, the practical value of durable HDPE and advanced netting materials will increase. Commercial opportunities will accrue to suppliers that can prove service-life advantages, reduce downtime, and provide replacement and maintenance strategies that lower total cost of ownership. For operators, the opportunity lies in standardizing on cage architectures that can be deployed across multiple sites with consistent performance, thereby simplifying training, maintenance, and procurement.
The second trend is the growing importance of containment and semi-closed or closed cage solutions. Biosecurity, waste management, and site permitting pressures are making controlled-environment cage systems more relevant, especially where environmental sensitivity or disease risk is high. This trend creates opportunities for equipment providers that can integrate cage design with monitoring, handling, and operational support, as well as for operators that can use these systems to strengthen their market positioning. The commercial logic is straightforward: systems that help reduce biological and environmental risk also help stabilize production and improve access to buyers that value predictable, responsibly sourced supply.
PW Consulting Health Care Research Center
The third trend is regulatory-driven infrastructure modernization. As water quality, waste, and disease-related requirements become more rigorous, and as certification and stewardship expectations influence market access, cage upgrades will increasingly be treated as strategic investments rather than discretionary purchases. This trend favors suppliers that can help operators navigate compliance requirements through design choices, documentation, and operational compatibility. It also favors operators that modernize early enough to avoid permitting delays and to secure access to premium market channels. The uncertainty here lies in the pace and variability of regulatory enforcement across regions, which can create uneven adoption curves and affect near-term demand patterns.
Alongside these opportunities, there are risks that decision-makers should monitor. Overly restrictive placement rules or biomass constraints could limit expansion in certain areas, even as demand continues to grow elsewhere. Material cost volatility and fabrication bottlenecks could affect project timing, particularly for large offshore deployments. In addition, the market’s moderate concentration means competitive intensity may increase as regional players expand portfolios or as new entrants target specific applications with lower-cost or higher-specialization offerings. Companies that rely on narrow product lines or single-region exposure may face more pressure than those with diversified application coverage and stronger lifecycle support capabilities.
Strategic Actions for Decision-Makers
For manufacturers and equipment suppliers, the priority is to align product roadmaps with the market’s shift toward durability, containment, and compliance-enabling design. This means investing not only in HDPE and advanced netting capabilities, but also in system configurations that support monitoring, maintenance, and modular replacement. Differentiation will increasingly come from demonstrating measurable operational outcomes, such as reduced replacement frequency, improved structural resilience, and easier integration with farm workflows. Suppliers should also prepare for a competitive environment where portfolio breadth and targeted acquisitions can strengthen positioning in higher-value containment segments.
For investors, the most relevant question is where growth will be most defensible. The market’s projected expansion suggests continued demand, but value capture will depend on exposure to the right applications, materials, and system types. Investments in companies with strong marine durability expertise, containment system capabilities, and credible service and support models are better aligned with the market’s structural direction than those focused solely on low-cost commodity exposure. At the same time, regulatory uncertainty and regional variability mean that portfolio diversification and scenario planning are essential, particularly when evaluating companies with concentrated geographic or application dependence.
Laboratory Animal Housing Cage Market
For procurement leaders and farm operators, the strategic focus should be on lifecycle economics and compliance readiness rather than initial price alone. Selecting cage systems with longer service life, stronger material performance, and better compatibility with monitoring or containment requirements can reduce long-term disruption and support expansion plans. Early alignment with certification and stewardship expectations can also improve market access and reduce the risk of future retrofit costs. Where possible, operators should evaluate suppliers based on total cost of ownership, service availability, and the ability to support standardized deployment across multiple sites.
The pace of change in this market makes detailed, segment-level intelligence increasingly valuable. Regional demand patterns, material substitution trends, regulatory timing, and competitive moves can alter procurement timing, pricing assumptions, and investment priorities in ways that broad market figures alone cannot capture. Decision-makers who need clearer visibility into application-specific demand, regional dynamics, and company-level positioning will benefit from deeper coverage that translates market growth into operational and commercial choices. For those evaluating expansion, procurement strategy, or capital allocation, a more detailed research view can help convert the market’s momentum into a practical plan.
For detailed analysis of this topic, please visit the official page: Aquaculture Cages Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
DNA Microarray for Agriculture Market 2026: Why 6.98% CAGR Reshapes Competitive Growth
By pmarketresearch, 2026-09-21
DNA Microarray for Agriculture Market: Strategic Trends and Commercial Opportunities
The DNA microarray market for agriculture has evolved from a niche research tool into a foundational technology for modern agrigenomics. Valued at USD 215.0 million in 2025, the market has demonstrated consistent growth over the historical period from 2020 to 2025, expanding from USD 153.44 million at the start of the decade. As the industry looks toward the forecast period spanning 2026 to 2032, the trajectory points toward a projected valuation of USD 344.79 million by 2032, reflecting a compound annual growth rate of 6.98 percent. This growth trajectory signals more than incremental expansion. It indicates a structural shift in how agricultural genomics is deployed across crop improvement, livestock breeding, and disease monitoring. For executives and investors operating in this space, the numbers tell a clear story. The market is maturing, adoption is broadening, and the competitive dynamic is moving from fragmented experimentation toward coordinated commercial scaling.
Market Landscape and Core Challenges
The baseline data establishes a market that has already crossed the USD 200 million threshold and is on a clear upward path. Revenue generation is distributed across mature and emerging geographies, with North America anchoring the largest share, followed by Europe and Asia Pacific, while Latin America and the Middle East and Africa represent smaller but progressively more relevant pockets of demand. By platform type, oligonucleotide-based microarrays command the larger revenue pool, with complementary DNA microarrays forming a substantial secondary segment. In application terms, rice and potato dominate the crop-focused usage, bovine applications lead the animal genetics segment, and sheep plus a broader others category complete the deployment landscape. Despite these encouraging structural indicators, the industry is navigating a set of interconnected challenges that will shape how value is captured over the next several years.
Three challenge areas stand out as particularly consequential. First, the market remains moderately fragmented from a concentration standpoint. The top three players account for roughly 24.6 percent of revenue, and the top five reach approximately 26.2 percent. This level of concentration suggests that no single organization dominates the space, which creates both opportunity and instability. Fragmentation can accelerate innovation through diverse product approaches, but it also complicates standardization, slows interoperability, and places a burden on end users who must evaluate multiple platforms with differing performance characteristics. For commercial leaders, this means that credibility, reproducibility, and service reliability are becoming differentiators rather than optional features.
Second, the transition from research-grade adoption to operational deployment is uneven. While academic and breeding programs have integrated microarray-based genotyping and gene expression profiling into their workflows, broader commercial agriculture often lags due to the need for field-validated assays, cost sensitivity, and integration with existing bioinformatics pipelines. The gap between proof-of-concept and routine use is where many projects stall. Closing that gap requires not only technically robust arrays but also clear guidance on sample handling, data interpretation, and decision support that links genomic output to agronomic or husbandry outcomes.
Third, the competitive threat from alternative genomic technologies is real and growing. Next-generation sequencing continues to expand its footprint in genotyping and transcriptome analysis, particularly where high resolution or discovery-oriented work is required. Microarrays retain advantages in throughput, cost predictability, and targeted assay design, but they must continuously demonstrate relative value. The strategic question is not whether sequencing will displace arrays, but where arrays will hold or extend their position through specialization, speed, and application-specific optimization.
Worldwide Agricultural Nanotechnology Market
Key Drivers of Market Change
Market movement is being shaped by a set of reinforcing drivers that span technology, policy, demand behavior, and cost dynamics. These forces interact rather than operate in isolation, and together they explain why the sector continues to expand at a steady pace even as the broader agricultural technology landscape faces macroeconomic and regulatory headwinds.
Technological Innovation and Platform Specialization
The most direct driver is the ongoing refinement of microarray platforms toward application-specific performance. In crop science, arrays designed for whole transcriptome analysis and targeted exon profiling are enabling more precise studies of plant gene expression across key species. Plant-focused arrays for crops such as tomato, rice, barley, cotton, and potato have broadened the practical utility of the technology by aligning probe content with breeding priorities. In animal genetics, high-throughput genotyping arrays are increasingly used to accelerate selection decisions, screen for traits of interest, and support consortium-derived marker panels. The trend is toward arrays that are not generic tools but tailored solutions built around the genetic architecture of specific organisms and the operational needs of breeding programs.
This specialization matters commercially because it reduces the friction between data generation and decision-making. When an array is designed with a clear use case in mind, the downstream interpretation becomes more actionable, and the value proposition becomes easier to communicate to end users. For technology providers, the implication is that product roadmaps should prioritize biological relevance and workflow integration alongside raw analytical performance.
Policy and Regulatory Environment
Policy dynamics are increasingly influencing where and how agrigenomics tools are adopted. Regulatory frameworks around genetic improvement, traceability, and food safety are pushing breeding programs and supply chain actors toward more rigorous characterization of genetic material. At the same time, public and private investment in food security, climate resilience, and sustainable crop and livestock production has created a favorable environment for genomic tools that can accelerate trait development and verification. Where regulatory or policy pressure is high, there is often an accompanying demand for reproducible genotyping and expression data that can support compliance, certification, or breeding records.
The practical effect is that policy is acting as both a demand catalyst and a design constraint. Arrays used in regulated or semi-regulated settings must deliver consistent results, clear documentation, and data formats that can be integrated into broader quality and traceability systems. This favors providers that offer not only hardware and probe content but also the supporting services and data structures needed for operational readiness.
Demand-Side Shifts in Breeding and Production
On the demand side, the behavior of breeding organizations, seed companies, and livestock operations is shifting toward faster cycle times and more data-driven selection. The pressure to improve yield stability, disease resistance, and climate adaptability is encouraging earlier and more frequent use of genomic information in selection pipelines. In parallel, there is growing recognition that targeted genotyping can provide a cost-effective bridge between low-resolution screening and more expensive discovery methods. For many programs, microarrays offer a practical balance of throughput and affordability, especially when the marker content is well matched to the breeding objectives.
Consumer and downstream market expectations also indirectly influence adoption. As downstream buyers and food brands place greater emphasis on traceability and attribute verification, upstream genetic characterization becomes more valuable as a supporting data layer. This does not mean microarrays are a consumer-facing product, but it does mean that the broader push for transparency and quality assurance can increase the relevance of genomic tools in breeding and production environments.
Cost Structure and Workflow Efficiency
Cost considerations continue to shape procurement and platform selection. Agricultural programs often operate under tight budgets and must justify every analytical expense in terms of breeding progress or operational efficiency. Here, the economic appeal of microarrays lies in the combination of predictable per-sample economics, established workflow maturity, and the ability to process meaningful sample volumes without the variable cost structures that can accompany more open-ended sequencing approaches. As labor, reagent, and informatics costs evolve, platforms that reduce hands-on time and simplify data handling gain an advantage.
Supply-side efficiency is equally important. Providers that can maintain consistent manufacturing quality, offer reliable custom content, and support rapid turnaround for specialized projects are better positioned to retain and expand their user base. In practice, the cost narrative is not simply about price per array. It is about total cost of ownership, including assay design, validation effort, interpretation support, and the risk of failed or ambiguous results.
Competitive Landscape and Leading Strategies
The competitive environment reflects a mix of established life science companies, specialized microarray manufacturers, and service-oriented genomics providers. Each brings a different angle of value, and the strategic differences among them reveal how the market is being shaped.
Strategic Positioning Among Core Players
Agilent Technologies has built a position around plant-focused expression and exon microarrays, with particular relevance to transcriptome analysis in agricultural species such as tomato. This positions the company as a resource for researchers and breeding teams that need detailed gene expression profiling rather than purely genotyping-oriented solutions. The emphasis on plant-specific content suggests a strategy rooted in biological relevance and depth of content for targeted crop applications.
DNA Microarray Market
Thermo Fisher Scientific offers genotyping microarray platforms for plant and animal agrigenomics, with high-throughput screening 옵션이 crop improvement workflows. The strategic strength here is scale and breadth. By supporting both plant and animal applications and emphasizing high-throughput use cases, Thermo Fisher is aligned with larger breeding and screening operations that value throughput consistency and platform maturity.
Illumina Inc. supplies consortium-derived and off-the-shelf genotyping arrays for important crops including barley, cotton, rice, and potato. This positions the company at the intersection of community-driven marker development and practical deployment. The availability of ready-to-use arrays for key crops reduces the design burden for end users and supports standardization across programs that rely on shared marker sets. Illumina’s approach reflects an understanding that adoption often depends on convenience, community validation, and access to well-characterized content.
Arrayit Corporation focuses on custom DNA and protein microarrays optimized for agricultural gene expression, genotyping, and crop research. The custom orientation is a distinct strategic choice. Rather than competing primarily on broad standardized catalogs, Arrayit positions itself to serve projects that need tailored content or specialized configurations. This can be especially valuable in early-stage research, niche crop programs, or situations where existing arrays do not match the biological question.
Eurofins Genomics provides genotyping and gene expression microarray platforms and services for plant breeding and agrigenomics applications. The service-forward model is a meaningful differentiator. By combining platform access with operational support, Eurofins addresses the practical reality that many organizations want genomic results without building all of the surrounding workflow internally. This service angle can be particularly attractive to teams that need flexibility, project-based engagement, and expert assistance in assay selection and data interpretation.
Market Evolution: Consolidation, Specialization, and Entrants
The current landscape is not dominated by a single winner, and the moderate concentration levels suggest room for both consolidation and continued specialization. Over the next several years, three movements are likely to shape the competitive structure.
- Consolidation pressure will increase as larger platforms and service organizations seek to broaden their agrigenomics offerings and capture more of the workflow. This may lead to more bundled value propositions that combine array content, informatics support, and project services.
- Specialization will remain a viable and attractive strategy, especially for providers that can align content closely with specific crops, livestock species, or breeding objectives. Niche depth can defend against generalist competition when the biological application is well defined and the performance bar is high.
- New entrants will continue to test the market, particularly where custom design, rapid turnaround, or regional support creates an opening. Entrants that can demonstrate credible performance and clear workflow integration may capture meaningful pockets of demand even in a crowded field.
For buyers and partners, this evolving structure means that vendor evaluation should go beyond catalog breadth. The relevant questions include how well the platform matches the intended application, how efficiently the provider supports custom or project-based needs, and whether the organization can sustain consistent quality and service over time.
Future Trends and Commercial Implications
Looking ahead across the 2026 to 2032 window, several trends are likely to define the next phase of market development. These trends are not isolated predictions. They are logical extensions of the current drivers and competitive dynamics, and they carry direct implications for how commercial value is created.
Trend One: Convergence of Standardized and Custom Solutions
The market is likely to move toward a hybrid model in which standardized arrays provide the baseline for high-volume applications, while custom or semi-custom designs address specialized breeding goals, regional crop varieties, and emerging animal traits. This convergence reflects the practical reality that no single array portfolio can optimally serve every use case. Standardized offerings reduce design cost and support broader interoperability, while custom solutions preserve flexibility for programs with unique genetic targets. The commercial opportunity lies in helping customers choose the right mix, and in building platforms that can transition smoothly between standard and customized content as needs evolve.
Trend Two: Integration with Decision Support and Informatics
As microarray data becomes more embedded in breeding and production workflows, the value of the data will increasingly depend on how easily it can be interpreted and acted upon. Tools and services that translate array output into breeding recommendations, trait prioritization, or quality records will become more important. This does not necessarily mean that every provider must build full informatics suites, but it does mean that the most competitive offerings will connect more seamlessly to downstream decision processes. Organizations that can reduce the gap between raw signal and operational decision will be better positioned to retain users and expand share of wallet.
Trend Three: Targeted Growth in Climate-Resilient and High-Value Applications
Demand is likely to strengthen in areas where genetic characterization supports climate resilience, disease resistance, input efficiency, and quality attributes valued by downstream markets. Rice and potato applications, along with bovine genotyping, already represent significant usage, and these areas are well placed to benefit from ongoing pressures on food production and livestock performance. Growth may also come from expanding the scope of what arrays are used to monitor, including more nuanced trait panels and integrated expression-plus-genotyping approaches where appropriate. The associated opportunity is to align product development and service offerings with the applications that are both technically suitable and economically important.
Risks and Uncertainties
These trends are accompanied by real uncertainties. Alternative genomic technologies will continue to improve in cost and accessibility, which could compress the role of microarrays in applications where sequencing becomes more advantageous. Standardization challenges may persist if platform diversity outpaces the development of shared reference frameworks or comparable performance benchmarks. Demand may also vary by region and by crop or livestock sector, meaning that aggregate growth will not be uniform across all segments. Finally, regulatory and policy shifts can alter adoption speed, particularly where genetic improvement, traceability, or data usage requirements change. Mitigating these risks requires a clear view of where microarrays retain a durable advantage and where the market is likely to shift toward other modalities.
PW Consulting
Actionable Guidance for Decision Makers
For executives, planners, and investors, the strategic priority is to convert market awareness into targeted action. The following recommendations are intended to help different stakeholder groups navigate the current landscape and prepare for the next phase of development.
For Manufacturers and Platform Providers
- Invest in application-specific differentiation. Broad catalogs are useful, but durable advantage increasingly comes from content and workflow that match the needs of key crops, livestock species, and breeding objectives. Prioritize designs that reduce interpretation burden and improve operational relevance.
- Strengthen service and project support. Many users value assistance with assay selection, validation, and data interpretation. Expanding reliable support capabilities can convert technical capability into commercial stickiness, especially for custom or semi-custom engagements.
- Build for interoperability and scale. As adoption grows, customers will look for consistent performance, manageable cost structures, and compatibility with existing data systems. Scalable process design and clear documentation will be assets in winning and retaining larger programs.
For Investors and Strategic Partners
- Focus on where microarrays hold a clear value advantage. The strongest opportunities are likely in targeted genotyping, expression profiling for defined biological questions, and workflows that benefit from throughput predictability and cost stability. Assess opportunities against these criteria rather than treating the market as uniformly interchangeable with sequencing.
- Evaluate the service and integration layer. Companies that can couple platform capability with practical workflow support may capture more value than those offering instruments or arrays alone. The ability to reduce adoption friction is a meaningful commercial attribute.
- Monitor consolidation and specialization dynamics. Both pathways can create value, but they imply different risk profiles. Consolidation plays depend on execution and integration, while specialization plays depend on sustained relevance in a defined application space. Align investment theses with the pathway that best fits the asset or partner under consideration.
For Procurement and End-User Organizations
- Match platform choice to use case, not just to catalog size. A well-matched array for the target species and biological question will often deliver better outcomes than a larger but less relevant offering. Define the decision context first, then evaluate platforms against that context.
- Assess total workflow cost and risk. Include assay design, validation effort, turnaround time, data interpretation support, and the consequences of ambiguous results in the evaluation. The cheapest per-unit option is not always the lowest-risk or lowest-cost choice overall.
- Plan for future data use. As genomic data becomes more integrated into breeding records, quality systems, and downstream decision support, consider how the chosen platform will fit into longer-term data management and interpretation needs. Early alignment can reduce rework and improve the long-term value of the data generated.
The strategic picture is clear enough to act on, but the details matter. Regional demand patterns, application-level adoption readiness, platform-specific performance trade-offs, and provider-level service capabilities can materially change the outcome of any market entry, investment, or procurement decision. Organizations that need a sharper read on these details will benefit from a more granular assessment of segments, competition, and forward scenarios. A complete research report can provide that level of specificity, including deeper segmentation data, company-level positioning, and customized recommendations tied to particular business objectives.
In a market moving toward both scale and specialization, the most effective decisions will come from combining high-level trend awareness with precise, use-case-relevant intelligence. The DNA microarray market for agriculture is not simply expanding. It is reconfiguring around application focus, workflow integration, and practical value creation. For leaders operating in this space, that reconfiguration is the real opportunity.
For detailed analysis of this topic, please visit the official page: DNA Microarray for Agriculture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Non-Magnetic Alloy Drill Collar Market: 5.0% CAGR & 73% Oil Drilling Share
By pmarketresearch, 2026-09-21
Strategic Horizons: Navigating the Non-Magnetic Alloy Drill Collar Market
The global market for non-magnetic alloy drill collars has entered a phase of measured expansion, characterized by steady capital expenditure in directional drilling and an increasing emphasis on measurement-while-drilling (MWD) and logging-while-drilling (LWD) compatibility. Over the 2020 to 2025 period, revenue grew from approximately 80.15 million to 101.0 million, reflecting a compound annual growth rate that positions the sector for continued upward momentum through 2032. The forward trajectory suggests a sustained climb toward the 142 million range by the end of the forecast horizon, with a five-year compound annual growth rate hovering around 5.0 percent. This pace is neither explosive nor stagnant; it reflects a mature, application-critical segment where performance requirements, material science, and operational economics converge.
Beneath these headline figures lies a more nuanced reality. Demand is not uniform across geographies or applications, and growth is increasingly shaped by how operators balance magnetic interference mitigation, corrosion resistance, and total cost of ownership. The market has evolved beyond a simple commodity interchange model. Tool designers, drilling contractors, and service companies now evaluate non-magnetic drill collars as integral components of bottomhole assemblies, where permeability thresholds below 1.01 and strict chemical composition control are non-negotiable for M/LWD instrument fidelity. This technical baseline has raised the barrier to entry and shifted competitive advantage toward manufacturers that can consistently deliver certified alloys with predictable mechanical behavior under downhole stress.
The current landscape also reveals structural tension points that will define the next cycle of investment and product strategy.
Key Challenges and Inflection Points
First, cost asymmetry between alloy grades is reshaping procurement behavior. Lower-carbon stainless steel variants have gained traction as a practical compromise, offering adequate non-magnetic performance at a more accessible price point than higher-grade titanium alloys. This divergence is not merely a pricing preference; it reflects operational reality for many drilling programs that must justify material upgrades against well economics and risk tolerance. The trade-off between grade selection and long-term reliability is becoming a central procurement decision, particularly for operators managing multiple well types or operating in cost-sensitive basins.
Second, the technical standardization landscape is tightening, reinforcing quality expectations across the supply chain. Requirements tied to API specification 7-1 have become a de facto benchmark, with manufacturers needing to demonstrate consistent magnetic permeability control, chemical composition discipline, and mechanical integrity. Compliance is no longer a checkbox exercise; it is a market access condition. Companies that can document repeatable process control and provide verifiable material performance data are gaining preference in tenders where measurement accuracy and downhole durability are paramount.
Third, the market is experiencing a gradual reallocation of innovation focus. The industry is moving from broad alloy availability toward application-specific optimization. Tool manufacturers are increasingly designing collar geometries, surface treatments, and metallurgical grades to address sour gas environments, directional drilling stress profiles, and extended-reach well conditions. This shift creates opportunities for differentiation, but it also demands closer collaboration between material suppliers, tool designers, and end operators. The inflection point is clear: generic product catalogs are giving way to performance-engineered solutions aligned with specific drilling programs.
Worldwide Drill Stabilizer Market
Key Drivers Shaping Market Direction
Technological Innovation and Material Science
The most consequential driver in this market is the continuous refinement of austenitic and nickel-based alloy systems. Advances in low-carbon chromium-manganese steels have expanded the practical use cases for non-magnetic drill collars by improving weldability, reducing susceptibility to stress corrosion cracking, and lowering raw material exposure relative to higher-cost alternatives. At the same time, premium alloys continue to occupy niches where extreme corrosion resistance and high mechanical strength are required. This bifurcation is enabling more granular product strategies, where manufacturers tailor grades to well environment, drilling method, and instrument sensitivity.
Process innovation is also playing a role. Shot-peening, precision forging, and controlled heat treatment are increasingly standard for high-performance collars, improving fatigue resistance and surface durability. In parallel, software-assisted tool selection is emerging as a differentiator. Recent technical presentations have highlighted how digital evaluation tools can support the scientific selection of non-magnetic drill collars for directional drilling optimization. These developments point to a broader trend: the market is placing greater value on data-backed tool matching and lifecycle performance predictability, not just material grade alone.
Policy, Standards, and Regulatory Expectations
Standards and certification regimes are shaping competitive dynamics as much as raw material availability. Compliance with API specification 7-1 has become a baseline expectation for operators deploying M/LWD systems, with emphasis on magnetic permeability limits and controlled chemistry. In practice, this means suppliers must maintain rigorous quality documentation, traceability, and consistency across production runs. The regulatory environment does not create demand by itself, but it does raise the cost of underperformance and rewards manufacturers with established quality systems. For buyers, this translates into greater reliance on suppliers that can provide certified conformance and predictable delivery performance.
Demand-Side Shifts in Drilling Practice
Demand is being reshaped by the broader evolution of well design and drilling efficiency. Directional and extended-reach wells are becoming more common in complex reservoirs, where magnetic interference can compromise downhole measurement integrity. This has reinforced the need for non-magnetic bottomhole assembly components in many operating environments. At the same time, operators are increasingly sensitive to total installed cost and lifecycle reliability. Upgrades to premium alloys are often deferred when the perceived incremental benefit does not justify the added expense, especially among smaller operators with tighter capital constraints. The result is a demand profile that is expanding in technical importance but remains selective in material grade adoption.
Rental and service-based models also influence demand patterns. Some suppliers are expanding offerings that combine manufactured collars with rental, machining, and BHA support services. This approach lowers upfront capital exposure for customers and aligns supplier incentives with tool performance over time. In markets where flexibility and service responsiveness matter, such models can be as important as the alloy itself.
Supply Chain and Cost Structure Dynamics
Material cost volatility continues to shape product economics. Titanium alloy variants, while offering specific performance advantages, carry higher manufacturing and material costs that limit broader adoption. In contrast, certain austenitic steel grades have become more economically attractive because of favorable raw material cost positioning and established production pathways. This cost structure encourages a tiered market in which lower-cost grades capture volume in many programs, while premium alloys remain reserved for conditions where their properties are essential.
Supply chain resilience is also under scrutiny. Manufacturers with localized production capabilities, diversified sourcing, and strong machining capacity are better positioned to manage lead-time variability and service demand. For end users, this has increased the importance of supplier stability, inventory readiness, and technical support. In a segment where tool failure or magnetic interference can disrupt entire drilling operations, supply reliability is a strategic consideration rather than a logistical detail.
Competitive Landscape and Leading Strategies
The market remains concentrated, with a limited number of established manufacturers holding significant share. This concentration reflects the technical barriers to entry, the importance of certified alloy production, and the value of long-standing customer relationships in drilling services and tool rental networks. Leading firms are competing not simply on price, but on grade breadth, application readiness, and the ability to support M/LWD deployments with consistent quality.
Strategic Positioning of Core Players
Several manufacturers have built recognizable positions by emphasizing different aspects of the value proposition.
Worldwide Casing Collar Locator Market
- Schoeller-Bleckmann Oilfield Technology has positioned itself around a broad family of non-magnetic drill collar and stabilizer grades, with an emphasis on austenitic Mn-Cr-N steels optimized for MWD/LWD and directional drilling. Its product range and API 7-1 alignment support customers seeking predictable magnetic performance and standardized compatibility.
- SBO is known for high-strength, corrosion-resistant non-magnetic alloy steels across multiple grades, targeting downhole tools and drill collars where mechanical robustness and resistance to corrosive environments are priorities.
- Drilling Tools International has focused on both manufactured and rental offerings, including slick, flex, spiral, and pony collars, with shot-peening aimed at sour gas stress corrosion resistance. This mix of product and rental capability supports operators looking to reduce capital exposure while maintaining performance standards.
- Tri Wave LLC supplies non-magnetic drill collars forged from premium austenitic stainless steels, differentiating on stress corrosion cracking resistance and enhanced mechanical properties. Its positioning appeals to programs where environmental aggressiveness and mechanical margin are central concerns.
- NTS Amega Global integrates non-magnetic drill collars and carriers into broader BHA rental and machining services, leveraging high-strength alloys for MWD/LWD applications. Its service-oriented model reflects the growing relevance of flexible, performance-supported procurement.
- Vigor Drilling Oil Tools And Equipment Co., Ltd. has developed a professional manufacturing footprint using Monel K500, Inconel 725, and austenitic steels to API and ISO standards, targeting directional drilling applications with an emphasis on material-grade flexibility.
These positions illustrate a market where differentiation is less about a single product feature and more about alloy range, process quality, service integration, and application focus. Companies that can align material offer with drilling environment and customer operating model are gaining traction.
PW Consulting
Market Evolution: Consolidation, Fragmentation, and New Entrants
The competitive structure is likely to evolve along two parallel paths. On one side, established players may continue to strengthen through service expansion, localized support, and deeper integration with drilling contractors and tool rental networks. On the other, new entrants can find opportunities by specializing in particular grades, regions, or application segments rather than competing across the full spectrum. Recent market activity reinforces this pattern. Participation in industry events and technical presentations has highlighted growing attention to tool selection methodologies, regional demand visibility, and application-specific solutions.
The presence of manufacturers from multiple regions also suggests that geographic coverage and supply responsiveness will become more important over time. Buyers increasingly evaluate suppliers not only on product specifications but also on delivery reliability, technical support, and the ability to adapt to local drilling conditions. This dynamic creates space for both consolidation among broad-line suppliers and fragmentation into niche specialists.
Future Trends and Commercial Opportunities
Gradual Grade Differentiation and Use-Case Alignment
Over the next three to five years, the market is likely to see more deliberate grade segmentation aligned with well environment and instrument requirements. Lower-carbon stainless steel solutions are expected to retain a strong volume position where cost efficiency and adequate non-magnetic performance are sufficient. Premium alloys will remain important for demanding conditions, but adoption will be driven by specific risk profiles and operational justification rather than uniform upgrade programs. For manufacturers, this trend favors portfolios that make grade selection easier for buyers while preserving margins through application-focused engineering.
Service-Integrated Offerings Will Gain Relevance
As operators seek flexibility and predictability, service-linked models will continue to grow in importance. Rental, machining, BHA support, and performance-backed service packages can reduce upfront cost and improve asset utilization. Suppliers that can combine certified product quality with responsive service and technical advisory will be well placed to capture share in segments where operational continuity matters more than initial purchase price. This also creates an opportunity to build longer-term customer relationships based on measurable performance outcomes.
Digital Tool Selection and Performance Data as Differentiators
Technical software and data-driven selection methods are becoming more visible in the market. As operators seek to optimize directional drilling outcomes and reduce trial-and-error in tool choices, the ability to recommend collar grades and configurations based on downhole conditions and performance data will be increasingly valuable. Suppliers that invest in selection support, documentation, and application knowledge can convert technical credibility into commercial advantage. This trend is not about replacing hardware with software; it is about strengthening the link between material choice and drilling results.
Risks and Uncertainties
Several factors could alter the trajectory of growth and competition. Persistent raw material cost pressure, especially for premium alloys, may continue to constrain adoption among cost-sensitive operators. If supply chain disruptions or production bottlenecks affect lead times, buyers may shift toward suppliers with stronger inventory positioning or regional manufacturing capacity. In parallel, if drilling activity patterns shift due to capital discipline or changes in exploration focus, demand for specialized non-magnetic components could moderate in some basins. Finally, any tightening of performance expectations or certification rigor could raise compliance costs and reward only those manufacturers with mature quality systems.
Actionable Guidance for Decision-Makers
For Manufacturers and Suppliers
Portfolio strategy should emphasize clarity of grade application rather than breadth alone. Differentiating through process consistency, surface treatment capability, and verified performance data will matter more than expanding product lists without application context. Investing in service integration, technical advisory, and selection support can help convert engineering credibility into repeat business. Suppliers should also evaluate where regional production, inventory readiness, and responsive machining can reduce customer friction and improve competitiveness in tenders.
For Investors
The market offers exposure to a technically constrained, application-critical segment with steady rather than speculative growth. Evaluation should focus on suppliers with strong certification discipline, defensible alloy and process capabilities, and the ability to serve M/LWD-driven demand. Business models that combine manufacturing with rental, service, or application-specific engineering may offer more durable revenue characteristics than pure hardware sales. Attention to cost structure, especially the balance between premium and lower-cost grades, is important for understanding margin resilience across market cycles.
For Procurement and Operations Leaders
Buying decisions should be structured around total operational risk and performance reliability, not alloy price alone. Establishing clear requirements for magnetic permeability, chemical control, and mechanical suitability can reduce the likelihood of instrument interference or premature failure. Where capital flexibility is important, rental and service-supported models can provide access to certified equipment while managing upfront exposure. Engaging suppliers with strong documentation practices and application knowledge can improve consistency across wells and reduce procurement risk over time.
The non-magnetic alloy drill collar market is at a point where technical precision, material economics, and service readiness are increasingly intertwined. Growth is real, but it is being shaped by selective adoption, standards-driven quality expectations, and the operational need to match collar performance to well conditions. For organizations operating in this space, the most valuable edge will come from understanding where grade selection, application engineering, and supply reliability create durable advantage. Detailed segment-level data, competitive tracking, and tailored strategic recommendations can further sharpen these decisions and support more confident planning across the forecast period.
For detailed analysis of this topic, please visit the official page: Non-magnetic Alloy Drill Collar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Gas Purifier Market: Why 6.2% CAGR and Asia Pacific’s Rise Change Everything
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Gas Purifier Market
The global gas purifier market has entered a phase of steady, structurally driven expansion, with total revenue projected to grow from approximately USD 162.0 million in 2025 to USD 244.0 million by 2032, reflecting a compound annual growth rate of 6.2 percent. This trajectory is not merely a function of incremental demand; it signals a broader industrial recalibration where gas purity, reliability, and regulatory compliance have become central to operational economics. Over the 2020-2025 period, the market navigated supply chain disruptions, shifting regulatory expectations, and accelerated technological maturation. The forecast horizon through 2032 suggests that these forces will continue to reshape procurement strategies, product architectures, and competitive positioning across multiple end-use sectors.
For executives and strategic planners, the gas purifier market presents a paradox of maturity and transformation. While the core purification technologies have been commercially established for decades, the convergence of stricter emission standards, advanced manufacturing tolerances, and supply chain localization pressures is creating new demand vectors. The market’s dispersion across regions and application segments indicates that growth is neither uniform nor predictable without granular contextual analysis. Understanding where value is being captured, which technological pathways are gaining commercial traction, and how incumbents are adapting their portfolios will be critical for organizations seeking to align capital allocation, R&D direction, and go-to-market strategies with emerging opportunities.
Market Snapshot and Structural Dynamics
The market’s expansion from roughly USD 125.0 million in 2020 to the current baseline reflects a recovery and acceleration pattern that underscores the essential nature of gas purification across industrial and high-precision applications. Revenue distribution across geographic regions shows a clear concentration in developed markets, with North America accounting for the largest share, followed by Europe and Asia Pacific. Latin America and the Middle East & Africa collectively represent smaller but strategically relevant segments, often driven by localized industrial projects, resource extraction activities, and gradual manufacturing capacity shifts.
The competitive structure remains moderately fragmented, with the top three players holding approximately 28.5 percent of total revenue and the top five capturing around 42.0 percent. This concentration level indicates that while scale advantages and brand recognition matter, niche specialization, regional service networks, and application-specific engineering capabilities continue to enable smaller players to secure meaningful market positions. The absence of a single dominant entity suggests that innovation, customization, and post-sale support will remain decisive factors in winning and retaining contracts, particularly in environments where downtime costs or purity deviations carry significant operational risk.
Core Challenges and Inflection Points
Despite the constructive growth outlook, the industry faces several structural challenges that are shaping how companies design, price, and deploy purification systems. First, the tension between performance specifications and total cost of ownership is intensifying. End-users increasingly evaluate purifiers not merely on initial capital expenditure but on lifecycle efficiency, regeneration frequency, waste handling, and integration complexity with existing process streams. This shift is forcing suppliers to move beyond component-level selling toward system-level value propositions, which requires deeper engineering engagement and more transparent cost modeling.
Second, regulatory and compliance pressures are creating divergent demand patterns across regions and industries. Stricter limits on contaminant levels in industrial gases, semiconductor manufacturing environments, and energy processing facilities are pushing purity thresholds higher, which in turn demands more sophisticated adsorption media, membrane configurations, or cryogenic separation approaches. However, compliance-driven demand can be lumpy and policy-dependent, introducing variability in project pipelines and complicating long-term capacity planning for manufacturers.
Third, supply chain resilience and raw material volatility are reshaping cost structures. The production of high-performance filtration media, specialized adsorbents, and precision membrane materials depends on a concentrated supplier base and, in some cases, geopolitically sensitive inputs. Companies that have historically relied on just-in-time procurement or single-source relationships are encountering margin pressure and delivery risk, prompting a broader reassessment of inventory strategy, alternative material qualification, and regional sourcing architectures.
Key Drivers Reshaping the Market
Technological innovation continues to be the most reliable catalyst for market differentiation. Advancements in adsorption media formulations, membrane material science, and integrated control systems are enabling purifiers to operate with higher selectivity, longer service intervals, and reduced energy consumption. In particular, hybrid purification approaches that combine complementary mechanisms are gaining attention in applications where single-technology solutions struggle to balance purity, throughput, and cost. These innovations are not only improving operational reliability but also expanding the addressable range of gas streams that can be treated economically.
PW Consulting
Policy and regulatory environments are acting as both a catalyst and a constraint. In industrial gas processing and energy refining, tightening emission and purity standards are accelerating replacement cycles and encouraging upgrades to higher-capacity or higher-efficiency units. At the same time, regulatory fragmentation across jurisdictions creates compliance complexity for multinational operators, rewarding suppliers that can offer standardized platforms with localized configuration options and documented certification support. The policy trajectory suggests that purification will increasingly be treated as a compliance-critical infrastructure component rather than a peripheral process accessory.
Demand-side behavior is shifting as end-users prioritize process stability and risk mitigation. In electronics manufacturing and high-precision industrial processing, even minor contaminant variations can translate into yield losses, rework, or equipment damage. This has elevated gas purification from a cost-center consideration to a quality-assurance priority, strengthening the business case for premium systems, predictive maintenance capabilities, and rapid-response service models. Simultaneously, the broader industrial trend toward modular and decentralized production is generating demand for compact, scalable purification units that can be deployed in distributed facilities or mobile operations.
On the supply side, cost structure evolution is pushing manufacturers toward design optimization and materials efficiency. Companies are investing in media regeneration strategies, modular component architectures, and digital monitoring tools that reduce unplanned downtime and extend service life. These efforts are gradually reshaping the economic model of gas purification, moving it toward recurring service revenue and performance-based contracts rather than purely transactional equipment sales. The net effect is a market where competitive advantage increasingly derives from operational integration and service reliability as much as from hardware specifications.
Competitive Landscape and Strategic Positioning
The competitive environment reflects a mix of established specialists, application-focused entrants, and regional service providers. Leaders in this space typically differentiate through a combination of proprietary media or membrane technology, robust application engineering, and strong field service networks. Rather than competing solely on price, successful players emphasize purity consistency, integration support, and lifecycle cost transparency. This approach is particularly effective in sectors where purification failures carry high operational or regulatory consequences, as it aligns supplier incentives with long-term customer performance.
A notable trend in the competitive landscape is the gradual shift from standalone product competition toward solution-oriented positioning. Companies are expanding their portfolios to include monitoring, control integration, media management, and preventive maintenance offerings. This bundling strategy helps stabilize revenue streams, deepen customer relationships, and create switching costs that are based on operational familiarity rather than contractual lock-in. At the same time, it requires stronger cross-functional capabilities in software, service logistics, and customer success management, which are becoming key markers of strategic maturity.
Worldwide Hydrogen Purifier Market
Market consolidation and fragmentation are unfolding simultaneously in different segments. In mature application areas with standardized requirements, scale and distribution strength are becoming more important, encouraging mergers, partnerships, or regional roll-ups. In contrast, emerging or highly specialized applications continue to reward agility, rapid customization, and deep domain expertise, enabling focused players to secure defensible niches. This dual dynamic suggests that the market will not converge toward a single competitive model; instead, successful organizations will need to decide where to compete on scale, where to compete on specialization, and how to structure their operating model accordingly.
New entrants are also finding opportunities by targeting underserved gas streams, underserved geographies, or underserved service models. Rather than attempting to displace incumbents across the entire value chain, many are focusing on specific pain points such as rapid deployment, reduced regeneration waste, lower energy footprints, or enhanced diagnostic capabilities. These targeted approaches can create footholds that later expand into broader platform offerings if the underlying technology and service model prove repeatable.
Air Purifiers Market
Forward Outlook: Trends Shaping the Next Three to Five Years
Over the next three to five years, the gas purifier market is likely to be shaped by three interrelated trends. The first is the continued integration of purification systems with digital monitoring and predictive maintenance capabilities. As operational teams seek to reduce unplanned outages and optimize media usage, purifiers equipped with real-time performance indicators, usage-based alerts, and remote diagnostics will become more commercially attractive. This trend creates opportunities for vendors that can combine hardware reliability with data-enabled service models, while also raising the bar for competitors that remain reliant on reactive maintenance paradigms.
The second trend is the gradual standardization of high-purity requirements across a widening set of applications. As industries such as advanced electronics, specialty chemicals, and refined energy processing converge on tighter purity expectations, purification systems will need to demonstrate repeatable performance under variable feed conditions. This will favor designs that are modular, configurable, and supported by strong quality assurance processes. For commercial strategy, it means that manufacturers will increasingly be evaluated on their ability to guarantee consistency across multiple installations rather than on nominal specifications alone.
The third trend is the realignment of supply chains toward resilience and regional adaptability. Organizations are likely to place greater emphasis on multi-source media procurement, localized assembly or integration, and alternative material qualification to mitigate disruption risk. This shift will not eliminate cost competition, but it will change how cost competitiveness is achieved, placing more weight on design efficiency, inventory planning, and supplier relationship management. Companies that invest early in resilient architectures and transparent sourcing strategies will be better positioned to maintain margin stability during periods of volatility.
These trends intersect with meaningful commercial opportunities. Providers that can deliver predictable purity performance, lower total cost of ownership, and responsive service support will be well placed to capture share in upgrade-driven demand cycles. Investors evaluating the sector should look beyond headline growth rates and assess which companies are building durable advantages in technology repeatability, service economics, and regional execution capability. Procurement leaders, meanwhile, should treat purification not as a commodity purchase but as a process-critical investment where specification clarity, service terms, and lifecycle modeling directly influence operational outcomes.
Strategic Implications for Decision-Makers
For manufacturers and technology developers, the priority is to align product roadmaps with where purity, reliability, and integration demands are converging. This means investing in designs that support modular scaling, media optimization, and diagnostics, while also building the field service and technical support infrastructure needed to back up performance claims. Differentiation will increasingly come from the ability to reduce lifecycle complexity for customers, not simply from offering the highest nominal specification.
For investors and strategic acquirers, the market’s moderate concentration and application diversity create a landscape where value can be created through targeted partnerships, capability acquisitions, or regional expansions rather than broad-based consolidation alone. Due diligence should focus on recurrence of revenue, service margin quality, customer retention in compliance-driven segments, and the scalability of the underlying technology platform. Companies that can demonstrate repeatable deployment economics and a credible path to broader application coverage are likely to offer more resilient value propositions over the forecast period.
For procurement teams and operational leaders, the most effective approach is to structure evaluation criteria around total cost of ownership, purity consistency under real operating conditions, and service responsiveness. Requesting performance data under representative feed conditions, clarifying media replacement and regeneration economics, and defining service-level expectations upfront can reduce downstream risk and improve vendor accountability. In environments where purity deviations carry high costs, the procurement process should be treated as a risk-management exercise as much as a sourcing decision.
As the gas purifier market continues to evolve across regions, applications, and technology pathways, the organizations that make informed decisions early will be best positioned to capture value and manage uncertainty. Detailed segmentation data, company-level benchmarks, and application-specific scenario analysis can further sharpen strategy development and execution timing. For decision-makers seeking a deeper, customized view of the market landscape and forward opportunities, the complete research report provides expanded segmentation detail, competitive profiling, and region-specific guidance to support more precise planning and investment choices.
For detailed analysis of this topic, please visit the official page: Gas Purifier Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Stone Paper Market: Why 6.5% CAGR and Packaging Demand Redefine the 2032 Outlook
By pmarketresearch, 2026-09-21
The Stone Paper Market: Strategic Trends and Commercial Opportunities (2026–2032)
Market Landscape and Core Challenges
The stone paper market has evolved from a niche sustainable material into a measurable commercial segment with clear growth trajectory. Valued at 640.0 million in 2020, the market expanded to 737.24 million by 2023 and reached 850.0 million in 2025, reflecting a compound annual growth rate of approximately 6.5 percent through 2032. By the end of the forecast period, revenue is projected to approach 1.3 billion, signaling sustained commercial momentum rather than short-term experimentation. This trajectory is anchored in a tangible shift away from conventional pulp-based and petroleum-derived alternatives, particularly in application areas where durability, moisture resistance, and reduced fiber dependency align with procurement priorities.
The composition of demand further clarifies where commercial attention is concentrating. Packaging-related uses represent the largest application share, followed by labeling and self-adhesive formats, indicating that stone paper is increasingly evaluated not as a general-purpose substitute but as a purpose-fit material for specific functional and sustainability requirements. On the supply side, the market is moderately consolidated. The top three participants account for roughly 35 percent of revenue, while the top five collectively hold just above 52 percent. This concentration suggests that scale advantages, formulation expertise, and regulatory readiness are becoming differentiating factors, even as regional demand continues to diversify across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa.
Key Challenges and Inflection Points
Despite the constructive growth outlook, the market is navigating several structural pressures that will shape profitability and adoption speed over the next few years.
The first challenge lies in cost arithmetic and raw material sensitivity. Stone paper does not eliminate cost exposure; it shifts it. Production depends on mineral fillers and resin systems, meaning margin stability is tied to feedstock pricing and energy inputs rather than fiber markets. When input costs rise, manufacturers must absorb volatility or pass it through to buyers who may still compare stone paper against established alternatives on price alone. This creates a persistent tension between sustainability positioning and commercial competitiveness, especially in price-sensitive segments where environmental claims must be matched by total cost-of-ownership logic.
The second challenge is performance perception versus application reality. Stone paper offers distinct advantages in waterproofing, durability, and tree-free production, but it is not a universal replacement for every paper grade. Adoption depends on matching the material to the right use case, printing conditions, converting requirements, and end-of-life pathways. Overgeneralization can create disappointment in contexts where stone paper underperforms expectations, while selective deployment can build credible reference accounts and repeat demand. The market is therefore moving through an inflection point where technical education and application-specific validation matter as much as regulatory tailwinds.
The third challenge is regulatory and standards complexity. The same policies that accelerate interest in stone paper also raise the bar for substantiation. Extended producer responsibility frameworks, single-use packaging obligations, and recycling-target-driven procurement increasingly require documented environmental performance rather than broad eco-friendly positioning. In practice, this means manufacturers and buyers must navigate varying regional expectations, verify food-contact suitability where relevant, and ensure that sustainability claims hold up under procurement scrutiny. Companies that treat compliance as a core capability rather than a backend activity are better positioned to convert demand into durable contracts.
Core Drivers of Market Change
The expansion of the stone paper market is not driven by a single force. It is being shaped by overlapping technical, regulatory, behavioral, and supply-side dynamics that reinforce one another in specific application spaces.
Technological Innovation and Material Refinement
Material formulation remains the most direct lever of market progress. Recent developments point to a pattern of incremental but commercially meaningful refinement rather than sudden breakthrough rhetoric. For example, Taiwan Lung Meng completed installation of an advanced production line that reduced carbon footprint by 15 percent while improving efficiency, reinforcing that process optimization is becoming a competitive necessity as buyers evaluate environmental impact alongside operational performance. Similarly, TBM expanded its LIMEX-based offerings with a sheet designed for global packaging applications, emphasizing durability and sustainability in a format that aligns with converting and handling requirements. These moves matter because they bridge the gap between laboratory-level green promise and production-ready reliability.
At the same time, product launches are becoming more application-specific. Shenzhen Stone Paper introduced wholesale stone powder synthetic paper for vegetable packaging in the printing and packaging industry, illustrating how stone paper is being tailored to fresh-produce and food-adjacent contexts where moisture resistance, printability, and material safety are critical. This kind of targeted innovation increases the likelihood of adoption because it reduces the burden on buyers to adapt the material to their processes. The broader lesson is that stone paper's commercial relevance is increasing as suppliers narrow the gap between material properties and real-world packaging needs.
Policy and Regulatory Dynamics
Regulatory pressure is acting as a demand catalyst, particularly in regions where packaging waste and single-use materials are being re-priced through policy. Extended producer responsibility policies for packaging and printed paper in North America and Europe are encouraging organizations to evaluate stone paper as a plastic alternative that can support recycling targets and reduce single-use plastic waste. In parallel, California's EPR regulations for single-use packaging require producers to bear recycling costs, accelerating adoption of lower-impact alternatives by changing the economic calculus of material selection.
These developments do not automatically translate into demand, but they alter procurement logic. When producers internalize end-of-life costs, materials with lower embedded environmental liability become more attractive in business cases that previously favored the cheapest upfront option. This regulatory context is especially relevant for packaging and labeling applications, where compliance exposure is high and sustainability commitments are increasingly tied to measurable policy outcomes rather than voluntary branding.
Demand-Side Shifts in Consumer and Corporate Behavior
Demand is also being reshaped by procurement behavior. Corporate buyers are increasingly treating sustainable packaging as an operational requirement rather than a differentiator, particularly when customer expectations, retail specifications, or internal targets push them toward reduced plastic use and lower environmental impact. Stone paper is benefiting from this shift because it can be presented as a tree-free, waterproof, and durable option with clear narrative appeal, especially in labeling, retail packaging, and industrial applications where material performance must coexist with sustainability storytelling.
Importantly, demand growth is strongest where the value proposition is concrete. Labeling and adhesive-backed formats, for instance, benefit from stone paper's durability and moisture resistance, while packaging applications gain from its alternative-to-plastic positioning. This suggests that adoption will continue to be opportunistic and segment-specific rather than uniform, with the most successful deployments tied to contexts where performance and policy alignment reinforce each other.
Supply Chain and Cost Structure Dynamics
The cost environment for stone paper production is influenced by the pricing of key raw materials, especially calcium carbonate. Recent pricing signals show meaningful regional variation, with calcium carbonate prices in the USA reaching 437 USD per metric ton in March 2026, the European price index averaging 0.33 USD per kilogram in May 2026, and Chinese prices at 317.10 USD per metric ton FOB in April 2026. These differences matter because they shape regional competitiveness and sourcing strategy.
Asian-based producers, for example, benefit from comparatively lower feedstock costs, which can support price competitiveness in export-oriented or regionally focused operations. European and North American producers, by contrast, must manage higher input costs while still meeting local regulatory and customer expectations. The net effect is that supply chain strategy is becoming a differentiator: companies that secure stable feedstock access, optimize formulation ratios, and manage energy intensity are better positioned to protect margins without sacrificing performance. In this environment, cost leadership is less about raw price cutting and more about input stability, process efficiency, and formulation discipline.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a small group of focused manufacturers with differentiated positioning, alongside ongoing room for specialization and regional expansion. Taiwan Lung Meng, TBM, and Shenzhen Stone Paper each illustrate a different pathway to commercial relevance.
Strategic Positioning and Differentiation
Taiwan Lung Meng is positioned around tree-free, waterproof stone composite material based on calcium carbonate and non-toxic resin, serving packaging, labels, and stationery. Its Cradle-to-Cradle certification and export presence across more than 40 countries indicate a strategy rooted in verified sustainability credentials and international reach. In a market where claims must withstand procurement scrutiny, certification and export scale can function as trust multipliers.
Worldwide Flexible Stone Market
TBM is building its case around LIMEX mineral paper for packaging, with emphasis on food and non-food applications and eco-friendly properties. Its recent activities suggest a dual strategy: expanding product formats for global packaging use while also engaging broader corporate decarbonization ecosystems. The memorandum of understanding with Vietnam's FPT Group in August 2025, aimed at supporting corporate decarbonization efforts, reflects an approach that connects material offering with wider sustainability programs rather than treating stone paper as a standalone product transaction.
Shenzhen Stone Paper is pursuing customization and food-contact-safe formulations, targeting industrial and retail packaging with rich mineral paper and high-durability labels. Its wholesale stone powder synthetic paper for vegetable packaging indicates a strategy focused on application-specific solutions, where formulation control and customization can create defensible accounts in niche but commercially meaningful segments.
Market Structure and Evolution Trends
The market is likely to evolve along three interconnected lines. First, consolidation pressure may increase as scale, compliance readiness, and cost control become more important, especially in applications where buyers require dependable supply and documented performance. Second, segmentation will probably deepen, with more specialized offerings for food packaging, labeling, and industrial uses, because generic stone paper positioning is increasingly insufficient for complex procurement decisions. Third, new entrants may find traction not by challenging incumbents directly across all applications, but by targeting specific regional cost advantages, formulation needs, or niche packaging requirements.
This does not imply a winner-take-all structure. Instead, it suggests a landscape where advantage accrues to companies that can combine credible environmental credentials, application-fit formulation, and stable input economics. SMEs and regional players can still compete by serving localized demand or specialized converting needs, while larger or more globally connected participants can leverage certification, export reach, and process efficiency.
Future Outlook: Trends and Commercial Implications
Over the next three to five years, the stone paper market is likely to be shaped by trends that reward precision, credibility, and supply chain discipline.
Trend 1: Application-First Adoption Will Outpace Broad Substitution Narratives
The market will probably move further toward use-case-led deployment. Packaging, labeling, and adhesive applications will continue to generate the strongest pull because they align with stone paper's functional strengths and with regulatory pressure on plastic alternatives. Broad claims that stone paper can replace conventional paper across the board will become less persuasive as buyers demand evidence in specific conditions. Commercially, this creates opportunity for suppliers and end-users who invest in application validation, pilot programs, and reference deployments rather than relying on category-level sustainability messaging.
PW Consulting Chemical & Energy Research Center
Trend 2: Regulatory Pressure Will Keep Raising the Stakes for Substantiation
Policy momentum in packaging and printed paper is expected to intensify the need for credible documentation. Extended producer responsibility and single-use packaging regulations will continue to shift cost considerations toward materials that support recycling targets and reduce disposal liability. This will advantage participants that can clearly articulate environmental performance, food-contact suitability where needed, and recycling or end-of-life compatibility. The commercial implication is that sustainability claims will increasingly need to be operationalized into procurement specifications, not just marketing narratives.
Trend 3: Regional Cost Dispersion Will Shape Sourcing and Competitive Positioning
Because calcium carbonate pricing varies by region, competitive dynamics will remain geographically uneven. Asian producers may retain feedstock cost advantages, while North American and European players will need to compete on efficiency, certification, local compliance alignment, and service differentiation. Procurement teams may also increasingly consider regional sourcing as part of broader supply chain resilience and carbon-reduction strategies. For investors and manufacturers, this means that feedstock access, formulation control, and regional regulatory fit will be central to margin stability and market access.
Worldwide Natural Stone Market
Potential risks and uncertainties should not be understated. Raw material price volatility can still compress margins if not managed through contracts, formulation adjustments, or efficiency gains. Performance misapplication remains a risk if stone paper is positioned where it does not fit technical requirements. In addition, the regulatory environment can evolve in ways that change the relative attractiveness of different materials, especially if recycling infrastructure, compostability rules, or packaging compliance definitions shift. These uncertainties do not undermine the market's direction, but they do require active monitoring and scenario planning.
Strategic Implications for Decision-Makers
For Manufacturers and Material Suppliers
- Prioritize application-specific differentiation. Develop formulations and product formats that solve concrete packaging, labeling, or adhesive challenges rather than competing on generic eco-friendly positioning.
- Treat process efficiency as a market-facing capability. Production improvements that reduce carbon footprint and improve yield are not just internal gains; they support pricing resilience and customer trust in a market where both cost and sustainability claims are scrutinized.
- Strengthen documentation and compliance readiness. Certification, food-contact safety where relevant, and clear end-of-life or recycling alignment can become decisive in procurement decisions, especially under extended producer responsibility and single-use packaging obligations.
For Investors and Strategic Backers
- Focus on players with defensible feedstock strategy and formulation expertise. Cost volatility and performance fit are the principal swing factors, so businesses that can manage input economics and tailor material properties to real applications are more likely to sustain competitiveness.
- Watch for consolidation and specialization signals. Moderately concentrated markets with clear application leadership may present acquisition, partnership, or capacity-extension opportunities, especially where regional cost structures or certification capabilities differ.
- Assess regulatory exposure by region. Procurement shifts driven by EPR and single-use packaging rules can accelerate adoption in some markets faster than others, creating uneven but potentially high-value opportunities.
For Procurement and Business Leaders Evaluating Stone Paper
- Match the material to the task. Evaluate stone paper against the specific functional requirements of the application, including moisture exposure, converting needs, printability, durability, and end-of-life expectations, rather than adopting it as a blanket paper replacement.
- Use total cost and compliance logic in the business case. Where recycling costs, single-use obligations, or packaging compliance raise the cost of conventional options, stone paper's value may be strongest when assessed across the full procurement and disposal picture.
- Demand evidence and reference use cases. Ask for application-appropriate testing, food-contact compatibility where relevant, and documented environmental performance to ensure that procurement decisions are based on verifiable attributes.
Conclusion
The stone paper market is moving from early-stage curiosity to a more structured commercial segment defined by application fit, regulatory pressure, and input economics. Growth to nearly 1.3 billion by 2032 is plausible within the current trajectory, but the more important question for decision-makers is not whether the market is expanding, but where expansion will be most profitable and durable. The strongest opportunities are likely to emerge where material performance, sustainability substantiation, and regional cost dynamics align in packaging, labeling, and adhesive applications. Companies that build differentiation through formulation, process efficiency, certification, and targeted use-case validation are better positioned to convert momentum into repeatable commercial advantage. For leaders seeking to act on these dynamics with greater precision, more granular segmentation data and customized strategic guidance will be essential to move from directional confidence to execution-ready decisions.
For detailed analysis of this topic, please visit the official page: Stone Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cabinet Hardware Market’s 6.8% CAGR to $16.4B: The Real Growth Drivers Shaping 2026–2032
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Cabinet Hardware Market: A 2025–2032 Outlook
The global cabinet hardware market has moved beyond a purely functional support role and is now a value-creating component of residential and commercial interior design. Current revenue trajectories place the market at approximately $10.58 billion in 2025, with a historical growth path from $8.30 billion in 2020 reflecting steady expansion despite periodic disruptions. Forward projections indicate a compound annual growth rate of 6.8 percent through 2032, pushing total market size beyond $16.38 billion by the end of the forecast period. This growth profile signals a maturing market that is increasingly shaped by material economics, design psychology, and regulatory shifts rather than by simple volume expansion. For decision makers, the immediate implication is that cabinet hardware strategy can no longer be built on incremental assortment updates or cost-only sourcing decisions. Competitive advantage now depends on anticipating which hardware attributes will command premium pricing, where supply risk is concentrating, and how regional demand patterns are diverging.
The current industry environment is defined by three interconnected challenges that are reshaping how manufacturers, distributors, and buyers approach the category.
The first challenge is the realignment of input costs around trade policy and raw material volatility. Hardware producers rely heavily on steel, aluminum, and engineered alloys, and recent tariff structures have introduced a step-change in landed costs for many imported components. This is not a temporary price fluctuation but a structural recalibration of the cost base that forces manufacturers to choose between margin compression, price increases, or accelerated supplier diversification. The broader consequence is that cost leadership alone is becoming harder to sustain without geographic or specification flexibility.
The second challenge is demand erosion in specific segments that is altering near-term volume assumptions. Recent industry indicators show cabinet sales declining year over year in certain months, reflecting a mix of affordability pressure, project timing shifts, and cautious purchasing behavior. Because hardware demand is closely tied to cabinet installation cycles, even short-term slowdowns can cascade into inventory misalignment, uneven order books, and more selective buying by remodelers and specifiers. In this environment, demand forecasting needs to account for timing risk, not just end-market growth.
The third challenge is a design-driven shift in finish and form expectations that is changing what buyers consider acceptable hardware. Professional design preferences are moving toward warm neutrals and tonal coherence, which directly influences hardware finish selection, decorative detailing, and the balance between visible and concealed components. This trend compresses the window for commodity-style hardware and rewards manufacturers and suppliers that can align product aesthetics with prevailing interior design language. The market is increasingly rewarding assets that combine functional reliability with aesthetic integration.
PW Consulting
Key Drivers Reshaping the Cabinet Hardware Market
The market’s direction is being shaped by a small number of high-impact forces that interact with one another and often change the competitive priority order for hardware suppliers and buyers.
Technology Innovation and Performance Differentiation
Performance engineering continues to be one of the strongest differentiators in cabinet hardware, especially in hinges, drawer runners, and soft-close mechanisms. Advanced tolerance control, corrosion-resistant coatings, and higher-cycle testing standards are increasingly treated as baseline expectations in premium segments. The practical effect is that hardware is being evaluated less as a commodity attachment and more as a long-life system component that contributes to cabinet durability and user satisfaction. For manufacturers, innovation attention is shifting toward reducing noise, improving load consistency, and making installation more forgiving, all of which support repeat purchasing in renovations and specification-driven projects. For buyers, this raises the importance of verified performance data and consistent finish integrity over time.
Policy and Regulatory Environment
Trade policy has become a first-order variable in cabinet hardware economics. New tariff actions on steel and aluminum imports, together with additional duties on certain sourced hardware and finished cabinet products, have altered sourcing logic across multiple channels. These measures affect more than direct input prices; they influence supplier selection, inventory positioning, lead-time planning, and the geographic balance of manufacturing and assembly. In practice, companies are being pushed to assess whether exposure is concentrated in specific material classes or in particular sourcing lanes, and whether that exposure can be reduced through design changes, alternate materials, or regional supply relationships. This environment favors organizations that can respond with flexible specifications and diversified procurement rather than those locked into single-source dependency.
Furniture Hardware Market
Demand-Side Behavior and Aesthetic Alignment
Consumer and professional specifier behavior is changing the hardware value proposition in two ways. First, renovation and replacement activity remains an important revenue engine, but the pace and mix of projects are increasingly influenced by affordability constraints and discretionary spending patterns. Second, finish and style preferences are evolving quickly enough that product assortments must be updated with greater frequency to remain relevant. The growing preference for warm neutrals and coordinated interior palettes means that hardware is being chosen not only for tactile function but also for visual integration with cabinetry, wall treatments, and fixtures. This creates an opportunity for suppliers and brands that can offer coherent finish families, repeatable quality, and design-aligned presentation. It also raises the risk of slow-moving inventory for assortments that are narrowly tied to older style conventions.
Supply Chain and Cost Structure Changes
The supply chain is being reevaluated around resilience, total landed cost, and service reliability. Hardware buyers and manufacturers are increasingly weighing the trade-off between lowest unit cost and the risk of disruption, especially where component sourcing is concentrated or sensitive to trade measures. At the same time, logistics costs, working capital requirements, and inventory carrying risk remain significant in a market where demand can shift by channel and region. The strategic response is moving toward broader supplier coverage, more disciplined SKU management, and closer alignment between specification, production planning, and distribution. For leading operators, this creates a pathway to defend margin while maintaining availability, but it requires operational discipline as much as negotiation skill.
Competitive Landscape and Leading Strategies
The cabinet hardware market is characterized by a meaningful concentration of revenue among established multinational and regional specialists, with a long tail of distributors and niche product houses serving design-led and value-oriented channels. Top-tier players hold a combined share that reflects the advantage of broad product systems, established specifier relationships, and the ability to offer integrated solutions across hinges, runners, handles, locks, and concealed mechanisms. This concentration does not imply a static market. Instead, it highlights how competitive advantage is increasingly determined by the ability to combine technical reliability, aesthetic relevance, and supply stability.
Several strategic positions stand out among leading companies.
- Leading European hinge and fitting specialists emphasize concealed mechanisms, soft-close performance, and high-cycle durability. Their differentiation comes from engineering depth and system-level integration, which appeals to manufacturers and specifier channels that prioritize long-term cabinet performance over initial purchase price.
- Global hardware suppliers with broad catalogsposition themselves across handles, hinges, fittings, and complete systems. Their advantage lies in assortment breadth, channel reach, and the ability to serve both functional and decorative applications through integrated offerings.
- Security and access-hardware players bring lock, handle, and security solution expertise into the cabinet context. Their relevance grows where cabinets are specified with access control, privacy, or integrated locking requirements, especially in commercial and multi-unit residential environments.
- Regional and value-oriented manufacturers compete by offering strong pricing, localized service, and targeted product families. Their strategic opportunity is to capture demand in price-sensitive channels and to expand into higher-specification segments through product upgrades and improved finish consistency.
- Decorative hardware specialists support design-led specification by emphasizing knob, pull, and bath hardware variety. Their value is strongest where finish, silhouette, and visual coordination matter as much as mechanical performance, particularly in residential renovation and luxury residential projects.
The market is evolving along two overlapping paths. One is consolidation of capability, where larger players strengthen system offerings, expand geographic coverage, and invest in product development that spans both performance and appearance. The other is fragmentation of demand, where specialized buyer groups seek distinct finishes, application-specific mechanisms, and faster assortment turnover. This dual dynamic creates room for incumbents to defend share through breadth and reliability, while also opening entry points for focused competitors that can move quickly in a specific finish category, region, or channel. New entrants and smaller manufacturers can succeed if they reduce friction in specification, improve lead-time predictability, or target underserved aesthetic and functional niches. At the same time, the cost impact of tariffs and input volatility raises the barrier for players without flexible sourcing or strong margin management.
Strategic Trends Shaping the Next 3–5 Years
Looking ahead, three trends are likely to define how cabinet hardware value is created and captured through the end of the decade.
The first trend is the premiumization of performance and finish integration. As buyers increasingly evaluate hardware alongside overall cabinet quality and interior design coherence, there is a growing divide between purely functional hardware and hardware positioned as part of a coordinated system. Products that combine consistent soft-close behavior, durable finishing, and design-aligned appearance are more likely to retain pricing power. The commercial opportunity lies in collections that reduce specifier decision complexity while maintaining technical credibility, especially where kitchens, baths, and commercial interiors are being refreshed for longevity rather than short-term cost savings.
Builder Hardware Market
The second trend is supply-chain reconfiguration in response to material tariffs and sourcing risk. Companies that can blend regional sourcing, material substitution where feasible, and more disciplined stocking strategies will be better positioned to stabilize margins and service levels. This creates a strategic opportunity for manufacturers and distributors to build more resilient input pipelines while also offering buyers greater predictability. The counter-risk is that tariff exposure and freight variability can compress flexibility, making it harder for smaller players to compete on availability and price at the same time.
The third trend is channel-specific demand divergence. Residential and commercial applications are unlikely to move in lockstep, and even within each channel, project timing and specification practices will differ by geography and customer type. This means that successful strategies will need to distinguish between volume-driven commodity supply and specification-driven performance supply. The opportunity is to tailor assortment depth, finish availability, and service models to the distinct buying logic of each channel. The risk is over-investing in a single demand narrative, which can leave a business exposed if renovation timing shifts or if commercial project pipelines slow.
Actionable Guidance for Decision Makers
For manufacturers and product developers, the priority is to align engineering and design decisions with the market’s shift toward durability, finish coherence, and reduced specification friction. This means investing in performance consistency, offering finish families that match prevailing interior trends, and reviewing SKU complexity to reduce slow-moving inventory. It also means stress-testing sourcing plans against tariff exposure and identifying which components or materials create the greatest cost sensitivity. Businesses that treat hardware as a design-integrated system rather than a interchangeable attachment are better positioned to defend margin and relevance.
For investors, the most useful lens is to evaluate exposure to the three forces that matter most: tariff-sensitive inputs, design-led assortment velocity, and channel mix. Companies with diversified sourcing, strong performance credentials, and the ability to serve both residential and commercial applications typically offer more resilient earnings profiles than those dependent on a narrow cost-leadership model or a single style cycle. Equally important is the pace at which a target can update finishes, respond to specifier preferences, and maintain supply continuity in a higher-cost input environment. These attributes often determine whether a business can convert market growth into durable profitability.
For procurement and purchasing teams, the strategic task is to balance unit cost against availability, specification fit, and total risk. In a period of elevated input costs and shifting demand timing, purchasing decisions should account for lead-time reliability, finish consistency, and the ability to source alternate materials or suppliers when trade measures change. Consolidating around suppliers that can provide system-level performance and predictable service may reduce hidden costs associated with returns, replacement, and project delays. At the same time, maintaining a degree of sourcing flexibility helps protect against concentrated exposure in any single material or origin.
The cabinet hardware market is moving into a phase where success depends less on reacting to volume growth alone and more on anticipating how cost structures, design preferences, and supply risk will reshape competitive priorities. The most valuable intelligence is the kind that connects these forces to specific decisions: which product attributes will hold pricing power, where sourcing exposure is most acute, and how regional and channel demand will diverge over the forecast period. Access to detailed segmentation data, company-level strategy mapping, and scenario-based market modeling can sharpen those decisions and reduce the cost of misjudging timing or exposure. For leaders seeking a more complete view of segmentations, competitive positioning, and forward risk, a fuller market study provides the deeper detail needed to turn these strategic themes into actionable planning.
For detailed analysis of this topic, please visit the official page: Cabinet Hardware Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Industrial Chocolate Market: Why 4.39% CAGR Through 2032 Changes Everything
By pmarketresearch, 2026-09-21
Navigating the Industrial Chocolate Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The industrial chocolate market has established itself as a resilient yet complex segment within the broader food ingredients landscape. From 2020 through 2025, the market expanded from approximately USD 49.3 billion to USD 59.7 billion, reflecting steady growth driven by consistent demand across baked goods, confectionery, and beverage applications. Looking ahead to the forecast period of 2026 through 2032, the trajectory projects a market value reaching USD 80.4 billion by 2032, supported by a compound annual growth rate of 4.39 percent. This pace suggests that industrial chocolate will continue to benefit from foundational consumption patterns while facing structural shifts that separate high-performing players from stagnant operations. The growth is not uniform across all product forms and end uses, and understanding where value concentrates requires looking beyond headline figures to the underlying dynamics shaping procurement, formulation, and distribution.
Several critical challenges are reshaping how manufacturers and suppliers approach the market. First, raw material volatility remains a persistent pressure point. Cocoa pricing has experienced significant swings, moving from elevated levels in prior years to notable declines in early 2026 as improved harvest outlooks and surplus expectations in West Africa altered the cost environment. While falling prices can relieve margin compression for downstream buyers, they also introduce planning complexity for suppliers who must manage inventory, hedging, and long-term contracting in a shifting landscape. Second, food safety and compliance oversight has intensified, with multiple recalls across different companies in early to mid-2026 highlighting the industry's exposure to microbiological contamination and undeclared ingredient risks. These incidents underscore the operational fragility that can disrupt supply continuity and erode buyer confidence, particularly for bulk industrial buyers who depend on consistent quality and traceability. Third, the industry must navigate a concentration dynamic where a relatively small number of large players account for a disproportionate share of market activity, creating both barriers to entry and opportunities for differentiation through specialization, technical service, and regional agility.
Cocoa Market
- Raw material price volatility creates planning uncertainty for both suppliers and bulk buyers, requiring more sophisticated hedging and contract strategies
- Food safety incidents and regulatory recalls highlight the need for robust traceability, supplier auditing, and rapid response capabilities across the value chain
- Market concentration among major players raises the importance of differentiation through formulation expertise, regional service, and flexible supply arrangements
Key Drivers of Market Change
Technical Innovation and Formulation Advances
Innovation continues to redefine what industrial chocolate suppliers can deliver, particularly as manufacturers seek cleaner labels, consistent performance, and cost-efficient formulations. Advanced cocoa processing, precision conching, and enhanced particle refinement allow ingredient suppliers to offer compounds, coatings, and fillings with tighter control over texture, viscosity, and flavor stability. Equally important is the growth of functional and flavor-modulation solutions. Ingredient specialists are increasingly providing cocoa extracts, flavor boosters, and formulation aids that enable manufacturers to reduce cocoa usage without sacrificing sensory quality. This approach is gaining traction in an environment where cost optimization and ingredient efficiency matter more than ever, especially for confectionery and bakery producers operating on thin margins. Innovation is also visible in product versatility: compound chocolate and specialty blends are being positioned to meet demands for thermal stability, ease of handling, and compatibility with different processing lines, supporting broader adoption in high-volume manufacturing environments.
Policy and Regulatory Environment
Regulatory oversight and food safety expectations are becoming more influential in shaping procurement and product design decisions. Recent recall activity involving potential Salmonella contamination and undeclared active ingredients has drawn attention to supplier compliance, ingredient sourcing, and quality control rigor. For industrial buyers, these events reinforce the importance of documented traceability, validated sanitation practices, and proactive supplier monitoring. In parallel, regulatory frameworks in key markets are encouraging greater transparency around allergens, labeling, and ingredient origin, which affects how industrial chocolate products are specified and documented. Companies that invest in quality management systems and clear compliance communication are better positioned to maintain trust with food manufacturers and foodservice customers. The regulatory environment is not merely a risk factor; it is also a filter that rewards organizations with disciplined operations and transparent supply practices.
Demand-Side Shifts in Consumer and Business Behavior
End-market demand is being shaped by changing consumer preferences and the operational needs of food manufacturers. Bakery products and confectionery remain central usage channels for industrial chocolate, but the way these categories evolve is changing. Consumers continue to seek indulgence, yet they also expect cleaner ingredient lists, consistent texture, and reliable flavor delivery. For industrial buyers, this translates into demand for ingredients that perform well in high-speed production while supporting product positioning around quality and simplicity. The rise of private label and contract manufacturing further influences demand, as retailers and brands look for suppliers capable of delivering consistent bulk formats with flexible customization. Beverage and frozen dessert applications, while smaller in share, are expanding in relevance as manufacturers explore new use occasions and flavor experiences. These demand-side shifts reward suppliers that can combine technical support with formulation flexibility, helping customers adapt products quickly to changing market expectations.
Supply Chain and Cost Structure Evolution
The cost structure of industrial chocolate is closely tied to cocoa supply dynamics, logistics, and processing capacity. Early 2026 data showed cocoa bean prices declining more than 10 percent year-on-year in some assessments, reflecting improved harvest expectations and changing supply balances in West Africa. At the same time, futures market movements indicated notable day-to-day and month-to-month swings, which reminds participants that even in periods of declining prices, volatility can persist. For industrial buyers, cost relief does not eliminate the need for strategic sourcing; rather, it shifts focus toward supplier reliability, hedging approaches, and contract structures that balance price and continuity. On the supply side, investments in processing capacity and regional facilities are shaping availability and service levels. For example, new pilot bakery and chocolate-related facilities in the United States reflect efforts to strengthen local support for industrial production and shorten response times for nearby customers. These developments suggest a gradual shift toward more regionally attuned service models, which can improve lead-time reliability and technical collaboration for manufacturers seeking closer supplier partnerships.
PW Consulting Health Care Research Center
- Cocoa price movements may ease some input costs, but volatility still demands disciplined sourcing, hedging, and inventory planning
- Food safety recalls reinforce the commercial value of traceability, supplier auditing, and rapid quality response across the industrial supply chain
- Demand for cleaner labels, formulation efficiency, and processing reliability is expanding the role of specialized ingredients and technical service
- Regional capacity additions and pilot facilities indicate a move toward closer supplier proximity and faster support for industrial customers
Competitive Landscape and Leading Strategies
The competitive field in industrial chocolate is defined by a mix of global cocoa processors, bulk ingredient suppliers, and specialists with strong formulation and application capabilities. Companies such as Barry Callebaut, Cargill, Blommer Chocolate Company, and Cémoi occupy prominent positions as large-scale suppliers of bulk dark, milk, and white chocolates, compounds, and cocoa-derived ingredients. Their scale provides advantages in sourcing, processing efficiency, and the ability to serve high-volume industrial and foodservice customers across multiple regions. At the same time, firms like Puratos, Fuji Oil, Guittard, and Natra compete with emphasis on specific application strengths, premium couverture options, and tailored ingredient solutions for bakery, patisserie, and professional manufacturing. A separate layer of competition comes from ingredient technology providers such as Kerry Group, which focuses on cocoa extracts and flavor boosters that help manufacturers achieve desired sensory outcomes while managing cocoa usage. This multi-layered structure means that competition is not only about price and volume; it is also about technical value, application expertise, and the ability to solve customer formulation challenges.
Leading players are pursuing distinct strategic positions. Global processors generally emphasize supply reliability, broad product portfolios, and the capacity to support large-scale manufacturing with consistent bulk formats. Their differentiation often rests on integrated sourcing, processing scale, and the ability to serve diverse end markets through a unified ingredient platform. Application-focused suppliers, by contrast, tend to compete on formulation support, specialty coatings, and solutions designed for specific production environments. Their advantage lies in helping customers achieve desired texture, stability, and flavor with greater precision, particularly in bakery and confectionery operations where processing conditions vary widely. Ingredient innovation specialists contribute another angle: by offering flavor modulation and cocoa-reduction solutions, they address cost and formulation efficiency directly, making them valuable partners for manufacturers looking to optimize recipes without compromising consumer appeal. These strategic differences suggest that the market is increasingly segmented by value proposition rather than by product category alone.
The competitive landscape is likely to evolve through a combination of consolidation, specialization, and selective new entry. Consolidation remains plausible among companies seeking broader geographic reach, ingredient breadth, or enhanced processing capacity. At the same time, specialization will continue to matter for suppliers that can deliver unique functional benefits, stronger application support, or more responsive regional service. New entrants may find opportunity in niche segments such as compound chocolate systems, bakery premix integration, or flavor-modulation ingredients, especially where they can address specific pain points in formulation, shelf stability, or cost control. Recent operational developments illustrate these dynamics: recalls have prompted renewed attention to safety and process control across multiple firms, while capacity additions such as new pilot bakery facilities in the United States indicate strategic investment in closer customer support. For decision-makers, the practical implication is that supplier selection should weigh not only price and availability, but also technical capability, compliance discipline, and the ability to adapt to product and process requirements.
- Global processors differentiate through scale, sourcing breadth, and consistent bulk supply across multiple industrial applications
- Application-focused suppliers compete on formulation precision, specialty coatings, and close support for bakery and confectionery production
- Flavor and ingredient technology providers create value by enabling cocoa usage optimization without sacrificing sensory quality
- Market evolution favors firms that combine compliance rigor, regional responsiveness, and technical service with competitive pricing
Forward Outlook: Three Trends to Watch
Cost Discipline and Ingredient Efficiency Will Become Central to Formulation Strategy
Even with periods of lower cocoa prices, the broader cost environment for food manufacturing remains sensitive to logistics, energy, labor, and compliance expenses. This means industrial chocolate buyers will continue to prioritize ingredient efficiency and formulation flexibility. Suppliers that can offer solutions designed to reduce cocoa dependence, improve handling characteristics, or streamline production steps are likely to capture stronger interest from cost-conscious manufacturers. Over the next three to five years, ingredient strategy will increasingly revolve around achieving target sensory profiles while controlling input costs and maintaining processing reliability. The commercial opportunity lies in partnerships that combine product performance with measurable efficiency gains, especially for high-volume bakery and confectionery operations. The risk is that cost pressure may intensify competition on price alone, squeezing margins for suppliers that cannot demonstrate differentiated value or technical support.
Food Safety, Traceability, and Compliance Will Act as Competitive Filters
Recent recall events have made it clear that food safety performance is not a back-office concern; it directly affects brand trust, supply continuity, and buyer willingness to commit to long-term supply arrangements. Over the coming years, buyers are likely to place greater weight on documented traceability, supplier quality systems, and rapid incident response. Companies that can provide transparent process controls, clear audit trails, and proactive communication will be better positioned to secure and retain industrial contracts. This trend benefits suppliers with mature quality infrastructure and creates headwinds for those with weaker controls. The commercial opportunity for well-prepared suppliers is to use compliance strength as a differentiator in procurement decisions. The uncertainty lies in the possibility of further regulatory scrutiny and the need to adapt quickly to new expectations around labeling, ingredient purity, and contamination prevention.
Regional Proximity and Application-Specific Service Will Gain Importance
Industrial chocolate buyers are increasingly looking for faster response, closer technical collaboration, and supply arrangements that align with local production needs. Capacity investments near key markets, along with pilot and application facilities, suggest that suppliers are responding to demand for more immediate support and better integration with customer workflows. In the next few years, regional service capability may become as important as product range, particularly for manufacturers that need formulation tweaks, troubleshooting, or shorter lead times. The opportunity is for suppliers to build regional footprints and application expertise that reduce friction in product development and production scaling. The risk is that regional expansion requires disciplined execution; without strong operational control, proximity alone will not deliver the reliability or technical value customers expect.
- Ingredient efficiency and formulation flexibility will be central as manufacturers balance sensory goals with cost and processing constraints
- Compliance and traceability capability will increasingly influence supplier selection and long-term contracting decisions
- Regional proximity and application support are likely to become stronger differentiators for suppliers serving industrial production environments
Strategic Actions for Decision-Makers
For Industrial Manufacturers and Formulators
Treat ingredient selection as a multidimensional decision rather than a simple price comparison. Evaluate suppliers on their ability to support formulation targets, maintain processing consistency, and respond quickly when products or production conditions change. Prioritize partners that can demonstrate strong quality systems, traceable sourcing, and clear communication around safety and compliance. Where possible, build relationships that include technical collaboration, whether for recipe optimization, compound chocolate handling, or coatings performance. In a market where volatility and regulatory attention remain elevated, the most resilient sourcing strategies combine cost awareness with reliability and application expertise.
For Investors and Corporate Strategists
Focus on business models that can convert technical value into durable competitive advantage. Scale alone is unlikely to guarantee outperformance if it is not paired with differentiated service, formulation capability, or strong compliance infrastructure. Look for companies that are expanding regional support, strengthening quality systems, and offering ingredient solutions that address cost efficiency or sensory optimization. Pay attention to how firms manage raw material volatility through hedging, contracting, and inventory discipline, as these capabilities influence margin stability. The most compelling opportunities are likely to emerge where suppliers can align product performance with the practical needs of high-volume manufacturing and evolving end-market expectations.
For Procurement and Supply Chain Leaders
Strengthen sourcing resilience by diversifying supplier options where feasible, while maintaining rigorous qualification standards. Incorporate food safety performance, traceability documentation, and incident response capability into supplier evaluation frameworks. Use contract structures that balance price exposure with supply continuity, especially in a market where raw material prices can move sharply over short periods. Establish clear expectations around audit access, documentation, and communication so that compliance becomes a shared operational standard rather than a reactive obligation. In practice, procurement teams that combine cost discipline with risk awareness are best positioned to protect production continuity and support product quality across changing market conditions.
Worldwide Chocolate Machines Market
- Evaluate suppliers on formulation support, processing reliability, and compliance discipline, not only on unit price
- Identify business models that combine scale, regional service, and technical differentiation to assess long-term resilience
- Build sourcing frameworks that integrate traceability, audit readiness, and flexible contracting to manage volatility and continuity risk
For executives seeking deeper segmentation, regional breakdowns, company-level benchmarks, and scenario-based planning inputs, a full research report can provide the detail needed to translate these market-wide observations into operational decisions. Access to more granular data on product forms, application flows, pricing dynamics, and supplier positioning enables more precise strategy design across manufacturing, sourcing, and investment priorities.
For detailed analysis of this topic, please visit the official page: Industrial Chocolate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Adipic Acid Market 2026: The Real Drivers Behind 4.2% CAGR Growth to $6.8B
By pmarketresearch, 2026-09-21
Strategic Horizons in the Adipic Acid Market: Navigating Complexity and Capturing Value
The global adipic acid market stands at a critical inflection point. Valued at approximately USD 5.15 billion in 2025, the sector has demonstrated consistent expansion from its 2020 baseline of USD 4.36 billion, projecting a compound annual growth rate of 4.2 percent through 2032. While the top-line trajectory appears orderly, the underlying dynamics reveal a market undergoing structural realignment. Demand fundamentals remain anchored in traditional nylon 66 applications, yet the pathway to sustained growth is being reshaped by regulatory pressure, supply chain fragility, and technological disruption. For executives and investors operating in this space, understanding these layered forces is no longer optional; it is a prerequisite for strategic positioning.
Several structural challenges are currently testing the resilience of established market participants. First, the sector faces mounting regulatory and sustainability mandates that directly impact production economics. Environmental protocols increasingly require stringent nitrous oxide abatement, effectively raising the compliance baseline for manufacturing operations and favoring integrators with capital to modernize. Second, raw material cost volatility has become a persistent margin pressure point. Suppliers are responding with aggressive pricing actions, but the lag between input cost spikes and pass-through mechanisms creates cash flow strain for mid-tier producers. Third, the supply base remains vulnerable to operational disruptions. Technical restart failures and force majeure declarations underscore how concentrated production footprints can amplify ripple effects across downstream nylon and polyurethane value chains. These factors collectively compress the margin for error and elevate the importance of operational agility.
Key Drivers Reshaping Market Trajectories
The market's evolution is being propelled by a convergence of technological, regulatory, and demand-side shifts. Technological innovation is steadily redefining production efficiency and environmental footprints. Process intensification, catalytic pathway optimization, and integrated abatement systems are enabling manufacturers to decouple output growth from emissions intensity. Companies operating integrated chemical complexes are leveraging shared infrastructure to improve energy efficiency and reduce per-unit compliance costs, creating a structural advantage that standalone producers struggle to match.
Regulatory and policy developments are simultaneously acting as both a constraint and a catalyst. Environmental frameworks that mandate high-efficiency nitrous oxide abatement are compelling capital reallocation toward cleaner production routes. At the same time, trade policy dynamics are adding complexity to cross-border supply flows. Investigations into import pricing practices from major exporting regions are prompting buyers to reassess sourcing dependencies and prioritize supply security over pure cost optimization. These policy movements are accelerating a broader shift toward regionalized production footprints and diversified supplier bases.
On the demand side, end-user behavior is evolving in ways that create both volume expansion and specification upgrades. The automotive, textile, and engineering plastics sectors continue to anchor core demand, but emerging applications in high-performance materials and specialty polyurethanes are pushing buyers toward higher-purity grades and more consistent supply reliability. Food-grade and pharma-adjacent specification requirements, while representing a smaller volume slice, command premium pricing and tighter quality control, incentivizing producers to segment their output and protect margin profiles. This demand differentiation is gradually reshaping procurement strategies, with volume buyers increasingly willing to pay for reliability and specification assurance rather than chasing the lowest spot price.
Finally, supply chain and cost structure dynamics are forcing a reevaluation of vertical integration strategies. The interplay between feedstock pricing, energy costs, and logistical bottlenecks is amplifying the value of regional production hubs. Producers with co-located intermediate supply, flexible capacity ramps, and diversified customer portfolios are better positioned to absorb shocks and manage price transmission. Conversely, assets reliant on single-stream feedstocks or distant logistics corridors face heightened exposure to margin erosion and delivery risk.
Succinic Acid Market
Competitive Landscape and Strategic Positioning
The competitive architecture of the adipic acid market reflects a blend of integrated global majors, regionally focused specialists, and high-purity niche suppliers. A handful of multinational chemical firms anchor the top tier, leveraging vertically integrated complexes, long-standing production footprints, and diversified downstream relationships to stabilize volume and margin profiles. These players benefit from scale, shared infrastructure, and the ability to shift production across applications based on relative value. Their strategic advantage lies not merely in capacity, but in the operational flexibility to manage cost cycles and specification requirements simultaneously.
Alongside these integrators, specialized producers have carved out defensible positions by focusing on purity, application-specific grades, or regional supply reliability. One North American supplier dominates large-scale food-grade output, capitalizing on world-scale capacity and strict quality controls to serve premium downstream markets. In Europe, specialty chemical producers emphasize responsiveness and pricing agility, often adjusting contract terms quickly to reflect raw material cost movements. Asian production remains concentrated around a single major producer with dedicated plants and consignment-linked operations, supplying both adipic acid and adjacent intermediates such as hexamethylenediamine salts. This regional concentration gives that producer a unique role in the Asia-Pacific supply chain, but it also concentrates risk should operational or regulatory disruptions arise.
Recent market events highlight how quickly stability can be disrupted. One global producer implemented a substantial price increase in early 2026 to offset cumulative raw material cost pressure, signaling the intensity of input cost transmission across the value chain. Shortly thereafter, another European producer declared force majeure on shipments following technical difficulties during a production restart, exposing the fragility of restart-dependent capacity and the cascading impact on buyers reliant on just-in-time supply. These incidents reinforce a broader pattern: pricing power is real but uneven, and supply reliability has become a decisive competitive differentiator.
PW Consulting
Market structure appears to be moving toward selective consolidation in core production corridors, while fragmentation persists in specialty and high-purity segments. Buyers are increasingly assessing suppliers not only on price but on compliance readiness, restart resilience, and the ability to honor long-term specification commitments. This shift creates openings for producers that can demonstrate operational robustness and transparent cost pass-through mechanisms. Conversely, it raises the bar for entrants that lack integrated feedstock access, abatement infrastructure, or established customer relationships. New entrants will likely find the most viable pathways through differentiated grades, regional supply partnerships, or technology-enabled process improvements rather than head-on capacity competition.
Industrial Grade Adipic Acid Market
Future Outlook and Commercial Opportunities
Looking ahead to the 2026 to 2032 horizon, three interconnected trends are likely to define the market's trajectory. The first is the acceleration of sustainability-linked production economics. As environmental protocols tighten and buyer preferences shift toward lower-emission supply, producers that embed high-efficiency abatement and energy optimization into their operating models will secure preferential access to regulated and brand-sensitive downstream markets. This trend creates commercial opportunity for investments in modernization, process upgrades, and credible sustainability credentials that can be monetized through premium contracts or long-term offtake agreements.
The second trend is the continued regionalization of supply chains. Trade scrutiny, logistics volatility, and buyer desire for supply security are encouraging a shift toward nearer-term production hubs and diversified sourcing strategies. This movement favors producers located in regions with stable energy access, integrated intermediate supply, and clear regulatory pathways. For downstream manufacturers, the opportunity lies in restructuring procurement to balance cost, resilience, and specification reliability, potentially through multi-source agreements, regional inventory buffers, and supplier performance frameworks that reward consistency.
The third trend is demand-side segmentation and grade specialization. As end-use applications diversify and quality requirements tighten, the market's value is increasingly captured through differentiated products rather than commodity volume alone. High-purity grades, consistent crystalline specifications, and odorless or low-impurity variants can command stronger pricing and deeper customer lock-in. Commercial opportunities here include targeted product development, quality certification investments, and application engineering support that helps buyers optimize performance while reducing total cost of ownership.
These trends are not without risk. Policy uncertainty around trade measures and environmental baselines could alter sourcing economics abruptly. Operational disruptions at key production sites may trigger short-term shortages and price spikes, followed by demand softening if buyers accelerate substitution or inventory drawdown. Raw material cost swings will continue to test margin resilience, especially for producers with limited pricing flexibility or constrained pass-through terms. Navigating this landscape requires contingency planning, contract structuring that shares cost risk more equitably, and scenario-based capacity planning rather than static volume assumptions.
Strategic Implications for Decision-Makers
For manufacturers and producers, the priority is to strengthen operational resilience while protecting margin integrity. Investments that improve energy efficiency, abatement performance, and restart reliability translate directly into lower cost volatility and stronger supplier credibility. Producers should also consider segmenting their portfolios to capture premium value in high-specification grades, using quality assurance and consistent delivery as the basis for long-term contracts rather than competing solely on spot pricing. Scenario planning for raw material cost shocks and trade policy shifts should be embedded into capacity and pricing strategy, ensuring that contractual terms and inventory positioning can absorb disruption without eroding customer trust.
For investors, the value-creation path is increasingly tied to assets with integrated infrastructure, clear sustainability positioning, and diversified demand exposure. Capital allocation should favor operations that combine scale with flexibility, especially where shared complexes reduce per-unit compliance costs and improve energy utilization. Equally important is scrutiny of supply concentration risk: assets dependent on single-stream feedstocks, distant logistics, or restart-prone operations carry hidden downside that can materialize quickly. Due diligence should extend beyond headline capacity to include abatement readiness, customer contract quality, pricing pass-through mechanisms, and regional regulatory exposure.
For procurement and supply chain leaders, the strategic imperative is to move from transactional buying toward resilience-oriented sourcing. Diversifying the supplier base across regions and grade profiles reduces exposure to single-point disruptions, while structured agreements that include transparency on cost drivers and scheduled pass-through reviews can mitigate surprise margin impacts. Qualification of alternative grades and backward integration assessments can provide leverage in negotiations and reduce dependence on any single specification or origin. Maintaining strategic inventory buffers for critical applications, paired with supplier performance metrics that reward reliability, helps balance cost efficiency with continuity risk.
Given the pace of regulatory change, operational volatility, and demand-side specialization, detailed segmentation data and customized scenario modeling are increasingly valuable for translating these dynamics into concrete business decisions. Comprehensive research that breaks down regional supply patterns, application-specific demand shifts, grade-level pricing behavior, and competitor response trajectories can sharpen planning and reveal opportunities that broad market figures alone cannot surface. For organizations seeking to position themselves ahead of structural change, deeper intelligence on capacity pipelines, compliance benchmarks, and contract structuring options provides the foundation for decisive action.
For detailed analysis of this topic, please visit the official page: Adipic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hydrazine Hydrate Market: Why the 5.5% CAGR Shift Reshapes 2032 Forecasts
By pmarketresearch, 2026-09-21
Hydrazine Hydrate Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The global hydrazine hydrate market has demonstrated steady expansion over the 2020–2025 period, driven by consistent demand across industrial, agricultural, and specialty chemical applications. Valued at approximately USD 215.0 million in 2020, the market grew to an estimated USD 280.6 million by 2025. Forward-looking projections indicate a compound annual growth rate of 5.5 percent through 2032, with revenues expected to approach USD 408.8 million by the end of the forecast horizon. This trajectory reflects a maturing but still dynamic market where volume growth is increasingly intertwined with regulatory adaptation and technological refinement rather than raw demand expansion alone.
While the aggregate figures point to resilience, the underlying structure reveals a market navigating several inflection points. First, regulatory scrutiny has intensified significantly across major jurisdictions. Hydrazine is classified as a substance of very high concern under the European Union REACH framework, placing producers and downstream users under continuous pressure to maintain authorization dossiers and justify continued use. This regulatory posture does not eliminate demand, but it raises compliance costs and compresses margins for operators with weaker regulatory infrastructure. Second, logistics and handling constraints remain a persistent bottleneck. Transporting hydrazine hydrate requires insulated, pressure-rated containers and certified handlers under United Nations Model Regulations, which limits supply chain flexibility and increases operational overhead for regional distributors and end-users alike. Third, feedstock cost volatility has emerged as a structural challenge. Recent periods have seen upstream raw material costs for hydrazine hydrate production rise by roughly 15 percent, squeezing profitability and forcing manufacturers to recalibrate pricing strategies without alienating price-sensitive industrial customers.
These challenges are not merely operational friction points; they are reshaping competitive boundaries. Companies that can absorb compliance costs, secure reliable feedstock contracts, and maintain rigorous handling standards are gradually separating themselves from smaller or less integrated players. The market is therefore transitioning from a capacity-driven growth phase to one where operational sophistication, regulatory readiness, and supply chain resilience determine long-term positioning. For decision-makers, the practical implication is clear: market entry or expansion now requires a holistic view of compliance, logistics, and input cost management rather than a narrow focus on production volume or end-market demand alone.
Key Drivers Shaping Market Direction
Technological Innovation and Product Specialization
Technological advancement in hydrazine hydrate is less about breakthrough chemistry and more about precision, purity, and application-specific differentiation. Industry participants have increasingly moved toward high-purity formulations tailored for demanding sectors such as aerospace and specialty synthesis. In February 2024, LANXESS AG introduced a high-purity 100 percent hydrazine hydrate variant specifically developed for aerospace applications, signaling a deliberate shift toward niche, performance-driven segments where tolerance for impurities is extremely low and customers are willing to pay for reliability. Alongside product refinement, trade platforms have become conduits for showcasing integrated value propositions. In May 2025, Arkema S.A. and LANXESS AG both participated in Chemspec Europe 2025, highlighting hydrazine hydrate alongside complementary chemicals such as thionyl chloride for crop protection agent synthesis. These engagements underscore a broader trend: manufacturers are positioning hydrazine hydrate not as a standalone commodity but as a critical input within larger synthetic and formulation workflows. For businesses, this implies that competitive advantage increasingly comes from offering application-ready specifications, technical support, and integrated chemical solutions rather than competing solely on base grade volume.
Regulatory and Policy Environment as a Market Filter
Regulatory dynamics are functioning as a market filter rather than a blanket constraint. In the United States, domestic rules were harmonized with updated international standards in 2024, prompting relabeling requirements and additional training across the supply chain. While such measures raise short-term operational burdens, they also formalize handling expectations and reduce variability in compliance practices. In parallel, EU REACH continues to require producers and users to prepare costly authorization dossiers, which disproportionately affects operators with limited regulatory resources or fragmented application portfolios. The practical effect is a consolidation of compliant supply bases and a higher barrier for new entrants who lack established regulatory track records. For procurement and sourcing leaders, this environment rewards long-term partnerships with manufacturers that can demonstrate consistent authorization status, transparent documentation, and robust safety protocols. For producers, the strategic imperative is to invest in regulatory capacity early, since compliance credentials are becoming as commercially relevant as technical specifications.
Demand-Side Evolution in End-Use Industries
Demand for hydrazine hydrate is being shaped by evolving priorities within core application sectors. Water treatment continues to be a substantial demand center, supported by ongoing infrastructure maintenance and chemical dosing requirements in industrial and municipal systems. At the same time, polymerization and blowing agent applications represent a significant share of consumption, reflecting the material’s role in foam generation and specialty polymer processing. Agrochemical synthesis remains another critical driver, where hydrazine hydrate serves as a key inorganic input for crop protection agents and related intermediates. Pharmaceutical manufacturing, while smaller in absolute terms, demands higher specifications and more controlled supply conditions. The common thread across these segments is a growing preference for suppliers who can provide grade consistency, technical documentation, and reliable delivery schedules. End-users are increasingly less willing to accept variability in feedstock quality or unpredictable lead times, particularly when production downtime or formulation failures carry high costs. This behavioral shift is pushing manufacturers to strengthen quality assurance systems, expand technical service capabilities, and align production planning more closely with downstream consumption patterns.
Supply Chain and Cost Structure Realignment
The cost structure of hydrazine hydrate production is undergoing noticeable realignment. Upstream feedstock costs have risen by approximately 15 percent in recent periods, placing pressure on conversion economics and prompting manufacturers to explore procurement optimization, energy efficiency improvements, and strategic inventory management. At the same time, shipping and handling requirements continue to add layered costs, particularly for long-distance distribution and cross-border transactions. These factors are encouraging a re-evaluation of network design, with some operators consolidating regional supply points, investing in specialized packaging, and pursuing long-term feedstock agreements to reduce exposure to spot price swings. For commercial teams, the implication is that cost competitiveness is increasingly determined by supply chain architecture as much as by production efficiency. Businesses that can stabilize input costs, optimize logistics, and maintain buffer capacity for demand fluctuations are better positioned to protect margins while preserving customer relationships in a price-sensitive environment.
Competitive Landscape and Leading Strategies
The competitive structure of the hydrazine hydrate market is moderately concentrated, with the top three companies accounting for approximately 26.8 percent of market revenue and the top five collectively representing about 29.4 percent. This concentration level indicates a landscape where established players hold meaningful share but where fragmentation still exists, particularly across regional distribution and specialty grades. The presence of multiple Japanese manufacturers alongside European incumbents reflects a geographically diverse supply base, with each group emphasizing different strengths in product specification, application focus, and regional service networks.
Arkema S.A., headquartered in France, offers hydrazine hydrate at 100 percent concentration along with a full range of dilutions and derivatives, positioning itself as a flexible supplier for polymer foam blowing agent applications and active ingredient synthesis. This breadth allows Arkema to serve customers who require customized dilution levels or derivative formats rather than a one-size-fits-all product. LANXESS AG, based in Germany, supplies hydrazine hydrate as a key inorganic input for the synthesis of crop protection agents and other agrochemical applications. Its emphasis on agrochemical synthesis aligns with one of the market’s most consistent demand streams, and its February 2024 launch of a high-purity 100 percent variant for aerospace applications demonstrates a willingness to extend into highly specification-sensitive segments. Otsuka-MGC Chemical Company, Inc., based in Japan, is recognized as the largest global maker of hydrazine hydrate and the only manufacturer based in Japan, giving it a distinctive domestic production advantage and a broad industrial application footprint. Nippon Carbide Industries Co., Inc., also in Japan, focuses on hydrazine hydrate as a synthetic raw material for pharmaceutical and agrochemical fields, while also supplying boiler cleaning chemicals, which diversifies its end-use exposure. Japan Finechem Co., Inc. produces hydrazine hydrate through its Sakaide plant operations, adding further capacity and regional depth within the Japanese supply base. Kanto Chemical Co., Inc. supplies hydrazine hydrate in technical and analytical grades, catering to customers who require precise grade differentiation for laboratory, quality control, and specialized industrial use.
Sodium Borohydride Market
The strategic positioning of these leaders reveals several differentiating advantages. First, product range flexibility matters. Companies that can supply both concentrated and diluted formats, plus relevant derivatives, reduce the need for customers to manage multiple suppliers for related grades and applications. Second, application specialization is increasingly valuable. Firms that align their capabilities with high-priority end-use areas such as agrochemicals, aerospace-grade purity, or pharmaceutical synthesis can command stronger customer loyalty and more resilient demand. Third, regional manufacturing presence can serve as a strategic asset, particularly where handling regulations, logistics complexity, and customer service expectations vary by market. Japanese manufacturers, for example, benefit from domestic production capabilities that support stable supply and localized technical support, while European players leverage integrated chemical portfolios and established regulatory infrastructure.
Looking ahead, the market structure is likely to continue evolving through a combination of consolidation, specialization, and selective new entry. Regulatory compliance costs and feedstock volatility will make it harder for under-resourced entrants to compete on undifferentiated volume, which may encourage 인수합병 activity or strategic partnerships among mid-tier players seeking scale and compliance capacity. At the same time, the growing importance of specialized grades and application-specific support creates space for focused competitors who can outperform on quality, documentation, and technical service rather than on price alone. New entrants that bring differentiated capabilities—such as advanced purification processes, specialized packaging, or strong regional regulatory readiness—could capture niche positions, but broad-based commodity competition is likely to intensify only where regulatory and logistics barriers are lower. For incumbents, the strategic task is to defend share in core applications while selectively expanding into higher-value specifications where customer willingness to pay is stronger and switching costs are higher.
Worldwide Potassium Carbonate Hydrate Market
Future Trends and Commercial Implications
Over the next three to five years, several trends are likely to shape how the hydrazine hydrate market evolves and where commercial opportunities emerge. The first trend is the continued elevation of regulatory and safety compliance as a core competitive dimension. As authorization requirements, labeling standards, and handling protocols become more entrenched, suppliers with mature compliance systems will gain an advantage in securing long-term contracts with risk-averse end-users. This creates an opportunity for companies to differentiate through documented safety performance, transparent regulatory status, and robust technical support, particularly in regions where compliance expectations are tightening. Businesses that treat compliance as a strategic capability rather than a cost center are better positioned to retain customers and defend pricing during periods of input cost pressure.
The second trend is the gradual shift toward higher-value, application-specific grades and integrated chemical solutions. Demand from sectors such as aerospace, pharmaceutical synthesis, and advanced agrochemical manufacturing is likely to sustain interest in high-purity and precisely specified products. This trend opens commercial pathways for suppliers that can offer tailored concentrations, reliable analytical certification, and close technical collaboration with downstream formulators. It also suggests that pure commoditization pressure may be partially offset by segmentation, where customers in specification-sensitive applications place greater weight on consistency and support than on marginal price differences. Companies that can clearly articulate grade performance, handle documentation efficiently, and align production with customer qualification requirements are more likely to capture these higher-margin positions.
PW Consulting Chemical & Energy Research Center
The third trend is supply chain resilience and cost management becoming central to market competitiveness. With feedstock costs elevated and logistics requirements demanding specialized handling, businesses will continue to optimize procurement, inventory, and distribution strategies. This may lead to more long-term feedstock agreements, regional supply consolidation, and investment in packaging and transport capabilities that reduce downtime and compliance risk. The commercial opportunity here lies in building supply arrangements that provide predictability for both suppliers and customers, especially in applications where production continuity is critical. At the same time, potential risks remain. Regulatory decisions could further constrain certain uses or increase documentation burdens, feedstock cost spikes could compress margins if unable to be passed through, and logistics disruptions could affect delivery reliability in tight markets. Decision-makers should therefore monitor regulatory calendar developments, input cost trends, and regional handling requirements as part of ongoing strategic planning.
Strategic Recommendations for Decision-Makers
For manufacturers and producers, the priority is to strengthen regulatory readiness, product differentiation, and supply chain stability in tandem. Building and maintaining rigorous authorization documentation, expanding high-purity or application-specific offerings, and securing more stable feedstock arrangements can help protect margins while improving customer retention. Companies should also evaluate whether their current grade portfolio matches the direction of end-use demand, particularly where aerospace, agrochemical, and pharmaceutical customers increasingly expect precise specifications and reliable technical support. Investing in handling and packaging capabilities that reduce logistics friction can further enhance competitiveness, especially in markets where certified transport and storage are limiting factors.
For investors, the key is to assess exposure not only to top-line demand growth but also to the regulatory and cost-structure dynamics that determine profitability. Businesses with strong compliance infrastructure, diversified application bases, and resilient logistics are better positioned to withstand feedstock volatility and regulatory pressure. Evaluation should consider whether a company’s product mix is shifting toward higher-value specifications, whether its regional presence supports stable service and compliance, and whether its cost management practices can absorb input price fluctuations without eroding competitive position. In a market where concentration is moderate and differentiation is increasing, long-term value is likely to accrue to operators that can combine scale with specialized capabilities rather than those competing purely on volume.
For procurement and sourcing leaders, the practical focus should be on supplier qualification, grade consistency, and supply continuity. Given the handling complexity and regulatory sensitivity of hydrazine hydrate, sourcing decisions should weigh documented authorization status, safety protocols, packaging standards, and delivery reliability alongside price. Building longer-term relationships with suppliers that can demonstrate stable compliance and technical support can reduce the risk of disruptions and specification mismatches, particularly in applications where production downtime or formulation issues are costly. Procurement teams should also monitor regional regulatory updates and logistics requirements, since changes in labeling, training, or transport standards can affect total landed cost and operational readiness.
As the hydrazine hydrate market continues to evolve through regulatory refinement, product specialization, and supply chain recalibration, the businesses that succeed will be those that treat these dynamics as strategic levers rather than external constraints. Detailed segmentation data, company-level assessments, and application-specific forecasts can provide the granularity needed to convert these trends into concrete sourcing, investment, and production decisions. For a more comprehensive view of regional breakdowns, application splits, competitive benchmarks, and forward-looking scenarios, the full PW Consulting research report offers a deeper evidence base and tailored guidance for specific strategic contexts.
For detailed analysis of this topic, please visit the official page: Hydrazine Hydrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hydrogen Cyanide Market: Navigating Structural Shifts as Revenue Rebases
By pmarketresearch, 2026-09-21
Strategic Shifts and Commercial Horizons in the Hydrogen Cyanide Market
The hydrogen cyanide (HCN) market stands at a complex inflection point, characterized by a mature but gradually contracting revenue base and a structural transformation in how the chemical is produced, transported, and consumed. Valued at approximately USD 2.2 billion in 2025, the market has experienced a measured decline from its 2020 level of USD 2.43 billion, reflecting a compound annual growth rate of roughly 2.2 percent through 2032. This trajectory is not a simple story of demand erosion; rather, it signals a market where value creation is shifting away from volume expansion toward efficiency, integration, and regulatory resilience. For executives and investors, the core question is no longer whether HCN will remain relevant, but how its role as a chemical intermediate will be reshaped by policy, logistics constraints, and the evolving economics of downstream manufacturing.
The industry now operates within a landscape where top-line revenues are stabilizing at lower levels, while capital allocation and strategic partnerships are being redirected toward process innovation and on-site supply architectures. The market remains moderately concentrated, with a limited number of producers holding meaningful share, yet the competitive dynamics are increasingly defined by operational flexibility and the ability to manage regulatory and safety-related costs. Understanding this environment requires moving beyond headline figures and examining the underlying forces that are compressing traditional revenue streams while simultaneously creating pockets of strategic advantage for well-positioned players.
Reality Check: Structural Pressures Reshaping the HCN Landscape
A Market in Gradual Contraction, Not Collapse
The revenue profile of the HCN market over the past half-decade reflects a slow but persistent drawdown, with the 2025 baseline sitting below the 2020 starting point and modest year-over-year movements extending into the forecast window. This pattern indicates that demand growth has not kept pace with prior expectations, and in several downstream applications, substitution pressures and capacity rationalization are weighing on consumption. At the same time, the decline is shallow enough to suggest that HCN remains embedded in essential chemical value chains rather than facing existential displacement. The market is therefore best understood as one undergoing structural recalibration, where producers must reconcile a flattening revenue curve with the need to sustain margins in a cost-sensitive and heavily regulated environment.
For decision-makers, this means that historical growth assumptions are no longer reliable planning anchors. Forecasts that treat the market as a stable volume game risk overstating revenue potential and underestimating the capital and compliance burdens that shape actual profitability. The more relevant lens is one of selective resilience: identifying which application segments, geographies, and supply models can sustain demand even as aggregate revenues drift lower.
Logistics, Regulation, and the Rising Cost of Moving HCN
One of the most consequential pressures in the current environment is the tightening of transport and storage regulations, which is quietly reshaping the economics of HCN distribution. As rules around hazardous chemical movement become more stringent, the cost and complexity of off-site logistics are rising, making remote supply arrangements less attractive relative to co-located production. This dynamic is not a temporary operational nuisance; it represents a structural shift in where value can be captured. Producers that previously relied on centralized manufacturing and widespread distribution are now facing a calculation in which proximity to end use increasingly dictates competitive viability.
PW Consulting Automotive & Machinery Research Center
The implication for the market is a gradual tilt toward integrated, on-site, or regionally co-located supply models. This shift raises barriers for purely merchant suppliers and rewards organizations that can anchor HCN production within or adjacent to downstream operations. It also amplifies the importance of maintenance capital and storage infrastructure, since operational continuity depends not just on production capacity but on the ability to safely buffer and manage inventory under evolving compliance requirements.
Maintenance Capex and Infrastructure Fragility
A second, less visible challenge is the growing burden of maintenance capital in an aging asset base. Several operators have recently emphasized that storage and handling infrastructure projects are being executed to reduce future maintenance expenditure, signaling that legacy facilities are reaching a point where deferred upkeep translates into operational risk and cost volatility. In a market where revenues are not expanding rapidly, the ability to manage fixed-cost drag becomes a decisive factor in margin preservation. Producers that continue to run older infrastructure without targeted modernization may find themselves exposed to unplanned downtime, regulatory friction, and rising unit costs, even if demand for their output remains intact.
This dynamic creates a subtle but important divergence within the competitive set. Companies that proactively address storage, containment, and process reliability can convert these investments into a cost advantage and a reputational buffer, while laggards risk a gradual erosion of competitiveness that is difficult to reverse through pricing alone. The market is therefore beginning to reward infrastructure discipline as much as production volume.
Sodium Cyanide Market
Core Drivers: What Is Really Moving the Market
Technology and Process Innovation as Margin Defenders
In an environment of modest revenue growth, technology is emerging as the primary lever for protecting profitability and extending asset life. Process innovations that improve yield, reduce energy intensity, and enable more flexible feed handling are becoming central to competitive strategy, particularly where producers seek to differentiate on reliability and cost rather than on market share alone. The relevance of such advances is amplified by the fact that HCN is often produced as an intermediate within broader chemical complexes, meaning that incremental improvements can cascade into better economics across multiple product lines.
Recent industry activity underscores this focus. One major player brought a demonstration-scale renewable chemicals plant online in early 2025, a move that strengthened future process options for HCN-related value chains. While still at an early stage, such initiatives signal that the industry is exploring production pathways and feedstock configurations that could alter cost structures over time. For executives, the strategic takeaway is that process innovation is no longer optional; it is becoming the mechanism through which producers defend margins when top-line expansion is limited.
Worldwide Sodium Ferrocyanide Market
Policy, Regulation, and the Geography of Compliance
The regulatory calendar is increasingly shaping where and how HCN can be produced and moved. Rather than acting as a uniform constraint, regulation is creating a differentiated landscape in which some jurisdictions and supply configurations face higher compliance burdens than others. Tightening transport rules, for example, are reinforcing the case for regionalized, on-site, or pipeline-linked supply, while simultaneously raising the value of facilities that already operate with integrated logistics. This means that regulatory trends are not merely a risk factor to be managed; they are actively steering capital toward particular operating models.
At the same time, facility-level operational changes illustrate how structural adjustments are being made to align with longer-term cost and governance objectives. A notable example is the transfer of infrastructure operations at major production sites to a dedicated operations entity, a step that reflects a broader industry tendency to separate process expertise from site management in order to improve focus, accountability, and capital efficiency. These moves suggest that the market is entering a phase where organizational design and operational governance are as strategically relevant as the chemistry itself.
Demand-Side Realignment in Downstream Applications
On the demand side, the HCN market is being shaped by the fortunes of its downstream anchors. Applications tied to nylon intermediates, specialty chemicals, and mining-related cyanide derivatives continue to represent significant consumption bases, but their growth trajectories are uneven. In several cases, demand is influenced less by end-market volume growth and more by capacity decisions, formulation shifts, and the relative economics of alternative chemistries. This creates a situation where HCN demand can persist in absolute terms while losing relative weight within broader chemical portfolios.
For commercial leaders, the practical implication is that segmentation assumptions must be tested against current downstream investment cycles rather than historical consumption patterns. Where downstream capacity is expanding and where HCN remains difficult to substitute, demand is likely to remain anchored. Where alternative pathways are gaining ground or where downstream operations are rationalizing, the HCN link may weaken more quickly than aggregate market data would suggest. This nuanced view matters for both production planning and partnership strategy.
Supply Chain Integration and the Economics of Proximity
Supply chain configuration is increasingly decisive because it directly affects both cost and regulatory exposure. The market is seeing a reinforcing cycle: as transport constraints and storage demands rise, the economic case for localized production strengthens, and as localized models become more common, the remaining merchant supply routes face higher relative burdens. This cycle favors operators that can offer on-site production, long-term offtake arrangements tied to integrated complexes, or regionally balanced supply networks. It also raises the strategic importance of asset location, since a facility's proximity to key demand clusters can influence its long-term viability more than marginal differences in production cost.
This dynamic is visible in how some companies are positioning themselves around integrated nitrile production with on-site HCN recovery and supply, while others emphasize calibration-grade specialty gas supply or application-specific offerings. The broader trend is a market in which the definition of a competitive supplier is expanding to include logistics design, operational integration, and the ability to reduce a customer's compliance and handling burden.
Competitive Landscape: Positioning, Differentiation, and Structural Evolution
Established Players and Their Strategic Anchors
The competitive field is anchored by a mix of global chemical groups, industrial gas specialists, and regionally focused producers, each leaning into a distinct value proposition. Several large European and North American organizations have built their HCN relevance around large-scale production and supply as a precursor for specialty chemicals, with advantages derived from scale, complex integration, and the ability to serve downstream customers within broader chemical portfolios. Their strategic positioning rests less on standalone HCN sales than on the role HCN plays within multi-product operations, where reliability and feedstock coordination matter as much as price.
Other participants have emphasized integrated nitrile production with on-site HCN recovery, a model that directly addresses the rising value of proximity and logistical efficiency. By recovering and reusing HCN within the production loop, these operators reduce exposure to transport constraints and lower the marginal cost of supply for adjacent processes. A separate cohort has focused on industrial gases and precursor supply, including HCN distribution for specialized applications, where the competitive edge lies in handling expertise, calibration-grade quality, and the ability to serve customers that require precise delivery and safe handling.
Regional and application-specific players also remain important. Some have built strong positions around HCN-based fumigants and mining chemicals, while others tie their HCN production to nylon-related materials or agricultural and industrial uses. These firms often compete on localized service, application knowledge, and the ability to manage regulatory requirements within specific end markets. Their presence means that the market is not a simple hierarchy of global scale leaders; it is a layered landscape where regional relevance and application specialization can outweigh raw size in certain segments.
Recent Developments as Strategic Signals
Two recent developments illustrate how the competitive agenda is shifting. One major operator launched a demonstration renewable chemicals plant in early 2025, strengthening future process options for HCN-related production. The strategic signal here is not that the market is about to pivot overnight, but that leading players are investing in optionality, exploring process routes that could improve economics or reduce exposure to conventional feedstock and compliance pressures over time. Such moves are best read as preparations for a more uncertain operating environment rather than immediate volume plays.
In parallel, another leading producer completed a hydrogen cyanide storage project expected to ease maintenance capital expenditure in the following year. This is a practical but telling example of how infrastructure investments are being used to reduce future cost drag and improve operational stability. In a market with limited revenue expansion, the ability to lower fixed-cost pressure and improve reliability can create a meaningful competitive edge, especially when paired with integrated supply models that already reduce logistics risk.
Integration, Fragmentation, and the New Entrant Question
The market's evolution is likely to be defined by selective integration rather than broad consolidation. Where value is increasingly tied to proximity, process integration, and compliance management, there is a natural incentive for downstream operators and upstream producers to align more closely, whether through partnerships, captive supply arrangements, or co-location. At the same time, pure merchant models that depend on long-distance transport and independent distribution may face continuing pressure, particularly where regulatory and handling costs keep rising.
New entry is not impossible, but the barriers are shifting. Capital access alone is no longer sufficient; prospective participants must also navigate safety, storage, transport, and community-related constraints, and they must offer a credible integration story or a specialized application angle. As a result, the market is likely to see a continued mix of established incumbents defending integrated positions and smaller, niche specialists competing on service, application expertise, or regional presence. The outcome will be a landscape that rewards differentiation and operational realism over undifferentiated scale.
Looking Ahead: Three Trends Shaping the Next Three to Five Years
Trend One: Locality as a Competitive Moat
Over the next several years, the strategic premium on local or integrated supply is likely to increase. Tightening transport rules and the ongoing emphasis on storage and maintenance efficiency will continue to tilt advantage toward operators that can supply HCN close to point of use or within integrated chemical complexes. For commercial strategy, this suggests that long-term value will accrue to those who can reduce a customer's logistical and compliance burden, not simply those who offer the lowest quoted price for transported product. The opportunity lies in designing supply relationships that are resilient by architecture rather than by contract alone.
Trend Two: Process Optionality and the Search for Cost Redefinition
A second trend is the gradual exploration of alternative process routes and feedstock configurations, still in early form but strategically important. Demonstration efforts and process-option investments indicate that leading companies are preparing for a future in which cost structures and compliance exposure may need to be redefined. Even if these initiatives do not immediately reshape volumes, they expand the option set for later deployment, giving advanced operators the ability to adapt more quickly if conditions shift. The commercial implication is that technology positioning will become a more visible part of market leadership, with early movers gaining insight and operational learning that can translate into future advantage.
Trend Three: Infrastructure Discipline as a Margin Filter
Finally, maintenance and storage infrastructure will increasingly act as a filter for profitability. Companies that complete targeted projects to reduce future maintenance expenditure and improve handling reliability will be better positioned to preserve margins in a flat-to-declining revenue environment. Those that defer such investments may face a compounding penalty in downtime risk, compliance friction, and unit cost. This trend elevates the strategic importance of capital planning that explicitly links infrastructure condition to long-term competitiveness, rather than treating maintenance as a purely tactical expense.
Uncertainty and Risk Factors
These trends are not risk-free. Demand-side assumptions remain sensitive to downstream capacity decisions and to the pace at which alternative chemistries gain acceptance in key applications. Regulatory expectations can also shift quickly, particularly around transport, storage, and community safety, introducing cost and timing uncertainty. In addition, the financial performance of the market will depend heavily on whether maintenance and process investments are timed and scoped effectively; poorly sequenced capital projects could burden operations without delivering the intended cost relief. Executives should therefore treat the outlook as directional rather than deterministic, and build flexibility into both sourcing and investment plans.
What This Means for Decision-Makers
For Manufacturers and Producers
Producers should prioritize the alignment of asset location, process reliability, and supply architecture around where value is most defensible. The most resilient strategies will likely combine disciplined infrastructure investment with clear integration advantages, whether through on-site recovery, co-location with downstream units, or regionally balanced supply that minimizes exposure to transport constraints. Equally important is the need to treat process innovation as a near-term margin issue rather than a distant research topic; early operational learning can determine which players hold cost and reliability advantages as the market matures.
For Investors and Capital Allocators
Investors should focus less on aggregate market size and more on the operating models that are gaining structural advantage. The cases that warrant closer attention are those where integration, proximity, and compliance management create a durable cost or service edge, and where infrastructure decisions are reducing future maintenance drag. A flat revenue backdrop does not preclude attractive economics, but it does raise the importance of distinguishing between companies that are simply maintaining presence and those that are actively improving their cost and risk profile. Due diligence should therefore extend beyond production capacity to include logistics design, storage readiness, and the credibility of process-option investments.
For Procurement and Supply Chain Leaders
Procurement teams should reassess supply assumptions that rely on distant, merchant-sourced HCN without fully accounting for transport, storage, and regulatory exposure. Where possible, the strategic priority should be to secure supply relationships that reduce handling risk and improve continuity, including integrated or regionally proximate arrangements where feasible. It is also wise to treat supplier selection as a multi-year decision, weighing infrastructure commitments and compliance posture alongside price, because the total cost of ownership in hazardous chemical supply is increasingly determined by logistics and reliability rather than by headline procurement price alone.
For those needing to translate these dynamics into concrete segment-level assumptions, regional comparisons, and tailored sourcing or investment scenarios, the full PW Consulting research report provides the deeper segmentation detail and customized analytical frameworks required for precise planning.
For detailed analysis of this topic, please visit the official page: Hydrogen Cyanide (HCN) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com