

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Gas Purifier Market: Why 6.2% CAGR and Asia Pacific’s Rise Change Everything

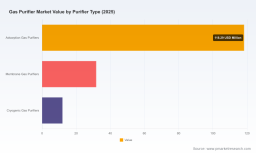
Strategic Trends and Commercial Opportunities in the Gas Purifier Market
The global gas purifier market has entered a phase of steady, structurally driven expansion, with total revenue projected to grow from approximately USD 162.0 million in 2025 to USD 244.0 million by 2032, reflecting a compound annual growth rate of 6.2 percent. This trajectory is not merely a function of incremental demand; it signals a broader industrial recalibration where gas purity, reliability, and regulatory compliance have become central to operational economics. Over the 2020-2025 period, the market navigated supply chain disruptions, shifting regulatory expectations, and accelerated technological maturation. The forecast horizon through 2032 suggests that these forces will continue to reshape procurement strategies, product architectures, and competitive positioning across multiple end-use sectors.
For executives and strategic planners, the gas purifier market presents a paradox of maturity and transformation. While the core purification technologies have been commercially established for decades, the convergence of stricter emission standards, advanced manufacturing tolerances, and supply chain localization pressures is creating new demand vectors. The market’s dispersion across regions and application segments indicates that growth is neither uniform nor predictable without granular contextual analysis. Understanding where value is being captured, which technological pathways are gaining commercial traction, and how incumbents are adapting their portfolios will be critical for organizations seeking to align capital allocation, R&D direction, and go-to-market strategies with emerging opportunities.
Market Snapshot and Structural Dynamics
The market’s expansion from roughly USD 125.0 million in 2020 to the current baseline reflects a recovery and acceleration pattern that underscores the essential nature of gas purification across industrial and high-precision applications. Revenue distribution across geographic regions shows a clear concentration in developed markets, with North America accounting for the largest share, followed by Europe and Asia Pacific. Latin America and the Middle East & Africa collectively represent smaller but strategically relevant segments, often driven by localized industrial projects, resource extraction activities, and gradual manufacturing capacity shifts.
The competitive structure remains moderately fragmented, with the top three players holding approximately 28.5 percent of total revenue and the top five capturing around 42.0 percent. This concentration level indicates that while scale advantages and brand recognition matter, niche specialization, regional service networks, and application-specific engineering capabilities continue to enable smaller players to secure meaningful market positions. The absence of a single dominant entity suggests that innovation, customization, and post-sale support will remain decisive factors in winning and retaining contracts, particularly in environments where downtime costs or purity deviations carry significant operational risk.
Core Challenges and Inflection Points
Despite the constructive growth outlook, the industry faces several structural challenges that are shaping how companies design, price, and deploy purification systems. First, the tension between performance specifications and total cost of ownership is intensifying. End-users increasingly evaluate purifiers not merely on initial capital expenditure but on lifecycle efficiency, regeneration frequency, waste handling, and integration complexity with existing process streams. This shift is forcing suppliers to move beyond component-level selling toward system-level value propositions, which requires deeper engineering engagement and more transparent cost modeling.
Second, regulatory and compliance pressures are creating divergent demand patterns across regions and industries. Stricter limits on contaminant levels in industrial gases, semiconductor manufacturing environments, and energy processing facilities are pushing purity thresholds higher, which in turn demands more sophisticated adsorption media, membrane configurations, or cryogenic separation approaches. However, compliance-driven demand can be lumpy and policy-dependent, introducing variability in project pipelines and complicating long-term capacity planning for manufacturers.
Third, supply chain resilience and raw material volatility are reshaping cost structures. The production of high-performance filtration media, specialized adsorbents, and precision membrane materials depends on a concentrated supplier base and, in some cases, geopolitically sensitive inputs. Companies that have historically relied on just-in-time procurement or single-source relationships are encountering margin pressure and delivery risk, prompting a broader reassessment of inventory strategy, alternative material qualification, and regional sourcing architectures.
Key Drivers Reshaping the Market
Technological innovation continues to be the most reliable catalyst for market differentiation. Advancements in adsorption media formulations, membrane material science, and integrated control systems are enabling purifiers to operate with higher selectivity, longer service intervals, and reduced energy consumption. In particular, hybrid purification approaches that combine complementary mechanisms are gaining attention in applications where single-technology solutions struggle to balance purity, throughput, and cost. These innovations are not only improving operational reliability but also expanding the addressable range of gas streams that can be treated economically.
PW Consulting
Policy and regulatory environments are acting as both a catalyst and a constraint. In industrial gas processing and energy refining, tightening emission and purity standards are accelerating replacement cycles and encouraging upgrades to higher-capacity or higher-efficiency units. At the same time, regulatory fragmentation across jurisdictions creates compliance complexity for multinational operators, rewarding suppliers that can offer standardized platforms with localized configuration options and documented certification support. The policy trajectory suggests that purification will increasingly be treated as a compliance-critical infrastructure component rather than a peripheral process accessory.
Demand-side behavior is shifting as end-users prioritize process stability and risk mitigation. In electronics manufacturing and high-precision industrial processing, even minor contaminant variations can translate into yield losses, rework, or equipment damage. This has elevated gas purification from a cost-center consideration to a quality-assurance priority, strengthening the business case for premium systems, predictive maintenance capabilities, and rapid-response service models. Simultaneously, the broader industrial trend toward modular and decentralized production is generating demand for compact, scalable purification units that can be deployed in distributed facilities or mobile operations.
On the supply side, cost structure evolution is pushing manufacturers toward design optimization and materials efficiency. Companies are investing in media regeneration strategies, modular component architectures, and digital monitoring tools that reduce unplanned downtime and extend service life. These efforts are gradually reshaping the economic model of gas purification, moving it toward recurring service revenue and performance-based contracts rather than purely transactional equipment sales. The net effect is a market where competitive advantage increasingly derives from operational integration and service reliability as much as from hardware specifications.
Competitive Landscape and Strategic Positioning
The competitive environment reflects a mix of established specialists, application-focused entrants, and regional service providers. Leaders in this space typically differentiate through a combination of proprietary media or membrane technology, robust application engineering, and strong field service networks. Rather than competing solely on price, successful players emphasize purity consistency, integration support, and lifecycle cost transparency. This approach is particularly effective in sectors where purification failures carry high operational or regulatory consequences, as it aligns supplier incentives with long-term customer performance.
A notable trend in the competitive landscape is the gradual shift from standalone product competition toward solution-oriented positioning. Companies are expanding their portfolios to include monitoring, control integration, media management, and preventive maintenance offerings. This bundling strategy helps stabilize revenue streams, deepen customer relationships, and create switching costs that are based on operational familiarity rather than contractual lock-in. At the same time, it requires stronger cross-functional capabilities in software, service logistics, and customer success management, which are becoming key markers of strategic maturity.
Worldwide Hydrogen Purifier Market
Market consolidation and fragmentation are unfolding simultaneously in different segments. In mature application areas with standardized requirements, scale and distribution strength are becoming more important, encouraging mergers, partnerships, or regional roll-ups. In contrast, emerging or highly specialized applications continue to reward agility, rapid customization, and deep domain expertise, enabling focused players to secure defensible niches. This dual dynamic suggests that the market will not converge toward a single competitive model; instead, successful organizations will need to decide where to compete on scale, where to compete on specialization, and how to structure their operating model accordingly.
New entrants are also finding opportunities by targeting underserved gas streams, underserved geographies, or underserved service models. Rather than attempting to displace incumbents across the entire value chain, many are focusing on specific pain points such as rapid deployment, reduced regeneration waste, lower energy footprints, or enhanced diagnostic capabilities. These targeted approaches can create footholds that later expand into broader platform offerings if the underlying technology and service model prove repeatable.
Air Purifiers Market
Forward Outlook: Trends Shaping the Next Three to Five Years
Over the next three to five years, the gas purifier market is likely to be shaped by three interrelated trends. The first is the continued integration of purification systems with digital monitoring and predictive maintenance capabilities. As operational teams seek to reduce unplanned outages and optimize media usage, purifiers equipped with real-time performance indicators, usage-based alerts, and remote diagnostics will become more commercially attractive. This trend creates opportunities for vendors that can combine hardware reliability with data-enabled service models, while also raising the bar for competitors that remain reliant on reactive maintenance paradigms.
The second trend is the gradual standardization of high-purity requirements across a widening set of applications. As industries such as advanced electronics, specialty chemicals, and refined energy processing converge on tighter purity expectations, purification systems will need to demonstrate repeatable performance under variable feed conditions. This will favor designs that are modular, configurable, and supported by strong quality assurance processes. For commercial strategy, it means that manufacturers will increasingly be evaluated on their ability to guarantee consistency across multiple installations rather than on nominal specifications alone.
The third trend is the realignment of supply chains toward resilience and regional adaptability. Organizations are likely to place greater emphasis on multi-source media procurement, localized assembly or integration, and alternative material qualification to mitigate disruption risk. This shift will not eliminate cost competition, but it will change how cost competitiveness is achieved, placing more weight on design efficiency, inventory planning, and supplier relationship management. Companies that invest early in resilient architectures and transparent sourcing strategies will be better positioned to maintain margin stability during periods of volatility.
These trends intersect with meaningful commercial opportunities. Providers that can deliver predictable purity performance, lower total cost of ownership, and responsive service support will be well placed to capture share in upgrade-driven demand cycles. Investors evaluating the sector should look beyond headline growth rates and assess which companies are building durable advantages in technology repeatability, service economics, and regional execution capability. Procurement leaders, meanwhile, should treat purification not as a commodity purchase but as a process-critical investment where specification clarity, service terms, and lifecycle modeling directly influence operational outcomes.
Strategic Implications for Decision-Makers
For manufacturers and technology developers, the priority is to align product roadmaps with where purity, reliability, and integration demands are converging. This means investing in designs that support modular scaling, media optimization, and diagnostics, while also building the field service and technical support infrastructure needed to back up performance claims. Differentiation will increasingly come from the ability to reduce lifecycle complexity for customers, not simply from offering the highest nominal specification.
For investors and strategic acquirers, the market’s moderate concentration and application diversity create a landscape where value can be created through targeted partnerships, capability acquisitions, or regional expansions rather than broad-based consolidation alone. Due diligence should focus on recurrence of revenue, service margin quality, customer retention in compliance-driven segments, and the scalability of the underlying technology platform. Companies that can demonstrate repeatable deployment economics and a credible path to broader application coverage are likely to offer more resilient value propositions over the forecast period.
For procurement teams and operational leaders, the most effective approach is to structure evaluation criteria around total cost of ownership, purity consistency under real operating conditions, and service responsiveness. Requesting performance data under representative feed conditions, clarifying media replacement and regeneration economics, and defining service-level expectations upfront can reduce downstream risk and improve vendor accountability. In environments where purity deviations carry high costs, the procurement process should be treated as a risk-management exercise as much as a sourcing decision.
As the gas purifier market continues to evolve across regions, applications, and technology pathways, the organizations that make informed decisions early will be best positioned to capture value and manage uncertainty. Detailed segmentation data, company-level benchmarks, and application-specific scenario analysis can further sharpen strategy development and execution timing. For decision-makers seeking a deeper, customized view of the market landscape and forward opportunities, the complete research report provides expanded segmentation detail, competitive profiling, and region-specific guidance to support more precise planning and investment choices.
For detailed analysis of this topic, please visit the official page: Gas Purifier Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com