

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Hydrogen Cyanide Market: Navigating Structural Shifts as Revenue Rebases

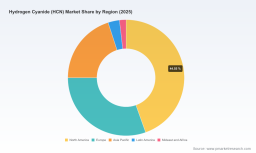
Strategic Shifts and Commercial Horizons in the Hydrogen Cyanide Market
The hydrogen cyanide (HCN) market stands at a complex inflection point, characterized by a mature but gradually contracting revenue base and a structural transformation in how the chemical is produced, transported, and consumed. Valued at approximately USD 2.2 billion in 2025, the market has experienced a measured decline from its 2020 level of USD 2.43 billion, reflecting a compound annual growth rate of roughly 2.2 percent through 2032. This trajectory is not a simple story of demand erosion; rather, it signals a market where value creation is shifting away from volume expansion toward efficiency, integration, and regulatory resilience. For executives and investors, the core question is no longer whether HCN will remain relevant, but how its role as a chemical intermediate will be reshaped by policy, logistics constraints, and the evolving economics of downstream manufacturing.
The industry now operates within a landscape where top-line revenues are stabilizing at lower levels, while capital allocation and strategic partnerships are being redirected toward process innovation and on-site supply architectures. The market remains moderately concentrated, with a limited number of producers holding meaningful share, yet the competitive dynamics are increasingly defined by operational flexibility and the ability to manage regulatory and safety-related costs. Understanding this environment requires moving beyond headline figures and examining the underlying forces that are compressing traditional revenue streams while simultaneously creating pockets of strategic advantage for well-positioned players.
Reality Check: Structural Pressures Reshaping the HCN Landscape
A Market in Gradual Contraction, Not Collapse
The revenue profile of the HCN market over the past half-decade reflects a slow but persistent drawdown, with the 2025 baseline sitting below the 2020 starting point and modest year-over-year movements extending into the forecast window. This pattern indicates that demand growth has not kept pace with prior expectations, and in several downstream applications, substitution pressures and capacity rationalization are weighing on consumption. At the same time, the decline is shallow enough to suggest that HCN remains embedded in essential chemical value chains rather than facing existential displacement. The market is therefore best understood as one undergoing structural recalibration, where producers must reconcile a flattening revenue curve with the need to sustain margins in a cost-sensitive and heavily regulated environment.
For decision-makers, this means that historical growth assumptions are no longer reliable planning anchors. Forecasts that treat the market as a stable volume game risk overstating revenue potential and underestimating the capital and compliance burdens that shape actual profitability. The more relevant lens is one of selective resilience: identifying which application segments, geographies, and supply models can sustain demand even as aggregate revenues drift lower.
Logistics, Regulation, and the Rising Cost of Moving HCN
One of the most consequential pressures in the current environment is the tightening of transport and storage regulations, which is quietly reshaping the economics of HCN distribution. As rules around hazardous chemical movement become more stringent, the cost and complexity of off-site logistics are rising, making remote supply arrangements less attractive relative to co-located production. This dynamic is not a temporary operational nuisance; it represents a structural shift in where value can be captured. Producers that previously relied on centralized manufacturing and widespread distribution are now facing a calculation in which proximity to end use increasingly dictates competitive viability.
PW Consulting Automotive & Machinery Research Center
The implication for the market is a gradual tilt toward integrated, on-site, or regionally co-located supply models. This shift raises barriers for purely merchant suppliers and rewards organizations that can anchor HCN production within or adjacent to downstream operations. It also amplifies the importance of maintenance capital and storage infrastructure, since operational continuity depends not just on production capacity but on the ability to safely buffer and manage inventory under evolving compliance requirements.
Maintenance Capex and Infrastructure Fragility
A second, less visible challenge is the growing burden of maintenance capital in an aging asset base. Several operators have recently emphasized that storage and handling infrastructure projects are being executed to reduce future maintenance expenditure, signaling that legacy facilities are reaching a point where deferred upkeep translates into operational risk and cost volatility. In a market where revenues are not expanding rapidly, the ability to manage fixed-cost drag becomes a decisive factor in margin preservation. Producers that continue to run older infrastructure without targeted modernization may find themselves exposed to unplanned downtime, regulatory friction, and rising unit costs, even if demand for their output remains intact.
This dynamic creates a subtle but important divergence within the competitive set. Companies that proactively address storage, containment, and process reliability can convert these investments into a cost advantage and a reputational buffer, while laggards risk a gradual erosion of competitiveness that is difficult to reverse through pricing alone. The market is therefore beginning to reward infrastructure discipline as much as production volume.
Sodium Cyanide Market
Core Drivers: What Is Really Moving the Market
Technology and Process Innovation as Margin Defenders
In an environment of modest revenue growth, technology is emerging as the primary lever for protecting profitability and extending asset life. Process innovations that improve yield, reduce energy intensity, and enable more flexible feed handling are becoming central to competitive strategy, particularly where producers seek to differentiate on reliability and cost rather than on market share alone. The relevance of such advances is amplified by the fact that HCN is often produced as an intermediate within broader chemical complexes, meaning that incremental improvements can cascade into better economics across multiple product lines.
Recent industry activity underscores this focus. One major player brought a demonstration-scale renewable chemicals plant online in early 2025, a move that strengthened future process options for HCN-related value chains. While still at an early stage, such initiatives signal that the industry is exploring production pathways and feedstock configurations that could alter cost structures over time. For executives, the strategic takeaway is that process innovation is no longer optional; it is becoming the mechanism through which producers defend margins when top-line expansion is limited.
Worldwide Sodium Ferrocyanide Market
Policy, Regulation, and the Geography of Compliance
The regulatory calendar is increasingly shaping where and how HCN can be produced and moved. Rather than acting as a uniform constraint, regulation is creating a differentiated landscape in which some jurisdictions and supply configurations face higher compliance burdens than others. Tightening transport rules, for example, are reinforcing the case for regionalized, on-site, or pipeline-linked supply, while simultaneously raising the value of facilities that already operate with integrated logistics. This means that regulatory trends are not merely a risk factor to be managed; they are actively steering capital toward particular operating models.
At the same time, facility-level operational changes illustrate how structural adjustments are being made to align with longer-term cost and governance objectives. A notable example is the transfer of infrastructure operations at major production sites to a dedicated operations entity, a step that reflects a broader industry tendency to separate process expertise from site management in order to improve focus, accountability, and capital efficiency. These moves suggest that the market is entering a phase where organizational design and operational governance are as strategically relevant as the chemistry itself.
Demand-Side Realignment in Downstream Applications
On the demand side, the HCN market is being shaped by the fortunes of its downstream anchors. Applications tied to nylon intermediates, specialty chemicals, and mining-related cyanide derivatives continue to represent significant consumption bases, but their growth trajectories are uneven. In several cases, demand is influenced less by end-market volume growth and more by capacity decisions, formulation shifts, and the relative economics of alternative chemistries. This creates a situation where HCN demand can persist in absolute terms while losing relative weight within broader chemical portfolios.
For commercial leaders, the practical implication is that segmentation assumptions must be tested against current downstream investment cycles rather than historical consumption patterns. Where downstream capacity is expanding and where HCN remains difficult to substitute, demand is likely to remain anchored. Where alternative pathways are gaining ground or where downstream operations are rationalizing, the HCN link may weaken more quickly than aggregate market data would suggest. This nuanced view matters for both production planning and partnership strategy.
Supply Chain Integration and the Economics of Proximity
Supply chain configuration is increasingly decisive because it directly affects both cost and regulatory exposure. The market is seeing a reinforcing cycle: as transport constraints and storage demands rise, the economic case for localized production strengthens, and as localized models become more common, the remaining merchant supply routes face higher relative burdens. This cycle favors operators that can offer on-site production, long-term offtake arrangements tied to integrated complexes, or regionally balanced supply networks. It also raises the strategic importance of asset location, since a facility's proximity to key demand clusters can influence its long-term viability more than marginal differences in production cost.
This dynamic is visible in how some companies are positioning themselves around integrated nitrile production with on-site HCN recovery and supply, while others emphasize calibration-grade specialty gas supply or application-specific offerings. The broader trend is a market in which the definition of a competitive supplier is expanding to include logistics design, operational integration, and the ability to reduce a customer's compliance and handling burden.
Competitive Landscape: Positioning, Differentiation, and Structural Evolution
Established Players and Their Strategic Anchors
The competitive field is anchored by a mix of global chemical groups, industrial gas specialists, and regionally focused producers, each leaning into a distinct value proposition. Several large European and North American organizations have built their HCN relevance around large-scale production and supply as a precursor for specialty chemicals, with advantages derived from scale, complex integration, and the ability to serve downstream customers within broader chemical portfolios. Their strategic positioning rests less on standalone HCN sales than on the role HCN plays within multi-product operations, where reliability and feedstock coordination matter as much as price.
Other participants have emphasized integrated nitrile production with on-site HCN recovery, a model that directly addresses the rising value of proximity and logistical efficiency. By recovering and reusing HCN within the production loop, these operators reduce exposure to transport constraints and lower the marginal cost of supply for adjacent processes. A separate cohort has focused on industrial gases and precursor supply, including HCN distribution for specialized applications, where the competitive edge lies in handling expertise, calibration-grade quality, and the ability to serve customers that require precise delivery and safe handling.
Regional and application-specific players also remain important. Some have built strong positions around HCN-based fumigants and mining chemicals, while others tie their HCN production to nylon-related materials or agricultural and industrial uses. These firms often compete on localized service, application knowledge, and the ability to manage regulatory requirements within specific end markets. Their presence means that the market is not a simple hierarchy of global scale leaders; it is a layered landscape where regional relevance and application specialization can outweigh raw size in certain segments.
Recent Developments as Strategic Signals
Two recent developments illustrate how the competitive agenda is shifting. One major operator launched a demonstration renewable chemicals plant in early 2025, strengthening future process options for HCN-related production. The strategic signal here is not that the market is about to pivot overnight, but that leading players are investing in optionality, exploring process routes that could improve economics or reduce exposure to conventional feedstock and compliance pressures over time. Such moves are best read as preparations for a more uncertain operating environment rather than immediate volume plays.
In parallel, another leading producer completed a hydrogen cyanide storage project expected to ease maintenance capital expenditure in the following year. This is a practical but telling example of how infrastructure investments are being used to reduce future cost drag and improve operational stability. In a market with limited revenue expansion, the ability to lower fixed-cost pressure and improve reliability can create a meaningful competitive edge, especially when paired with integrated supply models that already reduce logistics risk.
Integration, Fragmentation, and the New Entrant Question
The market's evolution is likely to be defined by selective integration rather than broad consolidation. Where value is increasingly tied to proximity, process integration, and compliance management, there is a natural incentive for downstream operators and upstream producers to align more closely, whether through partnerships, captive supply arrangements, or co-location. At the same time, pure merchant models that depend on long-distance transport and independent distribution may face continuing pressure, particularly where regulatory and handling costs keep rising.
New entry is not impossible, but the barriers are shifting. Capital access alone is no longer sufficient; prospective participants must also navigate safety, storage, transport, and community-related constraints, and they must offer a credible integration story or a specialized application angle. As a result, the market is likely to see a continued mix of established incumbents defending integrated positions and smaller, niche specialists competing on service, application expertise, or regional presence. The outcome will be a landscape that rewards differentiation and operational realism over undifferentiated scale.
Looking Ahead: Three Trends Shaping the Next Three to Five Years
Trend One: Locality as a Competitive Moat
Over the next several years, the strategic premium on local or integrated supply is likely to increase. Tightening transport rules and the ongoing emphasis on storage and maintenance efficiency will continue to tilt advantage toward operators that can supply HCN close to point of use or within integrated chemical complexes. For commercial strategy, this suggests that long-term value will accrue to those who can reduce a customer's logistical and compliance burden, not simply those who offer the lowest quoted price for transported product. The opportunity lies in designing supply relationships that are resilient by architecture rather than by contract alone.
Trend Two: Process Optionality and the Search for Cost Redefinition
A second trend is the gradual exploration of alternative process routes and feedstock configurations, still in early form but strategically important. Demonstration efforts and process-option investments indicate that leading companies are preparing for a future in which cost structures and compliance exposure may need to be redefined. Even if these initiatives do not immediately reshape volumes, they expand the option set for later deployment, giving advanced operators the ability to adapt more quickly if conditions shift. The commercial implication is that technology positioning will become a more visible part of market leadership, with early movers gaining insight and operational learning that can translate into future advantage.
Trend Three: Infrastructure Discipline as a Margin Filter
Finally, maintenance and storage infrastructure will increasingly act as a filter for profitability. Companies that complete targeted projects to reduce future maintenance expenditure and improve handling reliability will be better positioned to preserve margins in a flat-to-declining revenue environment. Those that defer such investments may face a compounding penalty in downtime risk, compliance friction, and unit cost. This trend elevates the strategic importance of capital planning that explicitly links infrastructure condition to long-term competitiveness, rather than treating maintenance as a purely tactical expense.
Uncertainty and Risk Factors
These trends are not risk-free. Demand-side assumptions remain sensitive to downstream capacity decisions and to the pace at which alternative chemistries gain acceptance in key applications. Regulatory expectations can also shift quickly, particularly around transport, storage, and community safety, introducing cost and timing uncertainty. In addition, the financial performance of the market will depend heavily on whether maintenance and process investments are timed and scoped effectively; poorly sequenced capital projects could burden operations without delivering the intended cost relief. Executives should therefore treat the outlook as directional rather than deterministic, and build flexibility into both sourcing and investment plans.
What This Means for Decision-Makers
For Manufacturers and Producers
Producers should prioritize the alignment of asset location, process reliability, and supply architecture around where value is most defensible. The most resilient strategies will likely combine disciplined infrastructure investment with clear integration advantages, whether through on-site recovery, co-location with downstream units, or regionally balanced supply that minimizes exposure to transport constraints. Equally important is the need to treat process innovation as a near-term margin issue rather than a distant research topic; early operational learning can determine which players hold cost and reliability advantages as the market matures.
For Investors and Capital Allocators
Investors should focus less on aggregate market size and more on the operating models that are gaining structural advantage. The cases that warrant closer attention are those where integration, proximity, and compliance management create a durable cost or service edge, and where infrastructure decisions are reducing future maintenance drag. A flat revenue backdrop does not preclude attractive economics, but it does raise the importance of distinguishing between companies that are simply maintaining presence and those that are actively improving their cost and risk profile. Due diligence should therefore extend beyond production capacity to include logistics design, storage readiness, and the credibility of process-option investments.
For Procurement and Supply Chain Leaders
Procurement teams should reassess supply assumptions that rely on distant, merchant-sourced HCN without fully accounting for transport, storage, and regulatory exposure. Where possible, the strategic priority should be to secure supply relationships that reduce handling risk and improve continuity, including integrated or regionally proximate arrangements where feasible. It is also wise to treat supplier selection as a multi-year decision, weighing infrastructure commitments and compliance posture alongside price, because the total cost of ownership in hazardous chemical supply is increasingly determined by logistics and reliability rather than by headline procurement price alone.
For those needing to translate these dynamics into concrete segment-level assumptions, regional comparisons, and tailored sourcing or investment scenarios, the full PW Consulting research report provides the deeper segmentation detail and customized analytical frameworks required for precise planning.
For detailed analysis of this topic, please visit the official page: Hydrogen Cyanide (HCN) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com