

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
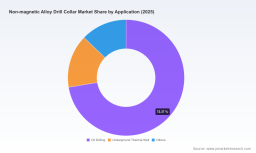
Non-Magnetic Alloy Drill Collar Market: 5.0% CAGR & 73% Oil Drilling Share

Strategic Horizons: Navigating the Non-Magnetic Alloy Drill Collar Market
The global market for non-magnetic alloy drill collars has entered a phase of measured expansion, characterized by steady capital expenditure in directional drilling and an increasing emphasis on measurement-while-drilling (MWD) and logging-while-drilling (LWD) compatibility. Over the 2020 to 2025 period, revenue grew from approximately 80.15 million to 101.0 million, reflecting a compound annual growth rate that positions the sector for continued upward momentum through 2032. The forward trajectory suggests a sustained climb toward the 142 million range by the end of the forecast horizon, with a five-year compound annual growth rate hovering around 5.0 percent. This pace is neither explosive nor stagnant; it reflects a mature, application-critical segment where performance requirements, material science, and operational economics converge.
Beneath these headline figures lies a more nuanced reality. Demand is not uniform across geographies or applications, and growth is increasingly shaped by how operators balance magnetic interference mitigation, corrosion resistance, and total cost of ownership. The market has evolved beyond a simple commodity interchange model. Tool designers, drilling contractors, and service companies now evaluate non-magnetic drill collars as integral components of bottomhole assemblies, where permeability thresholds below 1.01 and strict chemical composition control are non-negotiable for M/LWD instrument fidelity. This technical baseline has raised the barrier to entry and shifted competitive advantage toward manufacturers that can consistently deliver certified alloys with predictable mechanical behavior under downhole stress.
The current landscape also reveals structural tension points that will define the next cycle of investment and product strategy.
Key Challenges and Inflection Points
First, cost asymmetry between alloy grades is reshaping procurement behavior. Lower-carbon stainless steel variants have gained traction as a practical compromise, offering adequate non-magnetic performance at a more accessible price point than higher-grade titanium alloys. This divergence is not merely a pricing preference; it reflects operational reality for many drilling programs that must justify material upgrades against well economics and risk tolerance. The trade-off between grade selection and long-term reliability is becoming a central procurement decision, particularly for operators managing multiple well types or operating in cost-sensitive basins.
Second, the technical standardization landscape is tightening, reinforcing quality expectations across the supply chain. Requirements tied to API specification 7-1 have become a de facto benchmark, with manufacturers needing to demonstrate consistent magnetic permeability control, chemical composition discipline, and mechanical integrity. Compliance is no longer a checkbox exercise; it is a market access condition. Companies that can document repeatable process control and provide verifiable material performance data are gaining preference in tenders where measurement accuracy and downhole durability are paramount.
Third, the market is experiencing a gradual reallocation of innovation focus. The industry is moving from broad alloy availability toward application-specific optimization. Tool manufacturers are increasingly designing collar geometries, surface treatments, and metallurgical grades to address sour gas environments, directional drilling stress profiles, and extended-reach well conditions. This shift creates opportunities for differentiation, but it also demands closer collaboration between material suppliers, tool designers, and end operators. The inflection point is clear: generic product catalogs are giving way to performance-engineered solutions aligned with specific drilling programs.
Worldwide Drill Stabilizer Market
Key Drivers Shaping Market Direction
Technological Innovation and Material Science
The most consequential driver in this market is the continuous refinement of austenitic and nickel-based alloy systems. Advances in low-carbon chromium-manganese steels have expanded the practical use cases for non-magnetic drill collars by improving weldability, reducing susceptibility to stress corrosion cracking, and lowering raw material exposure relative to higher-cost alternatives. At the same time, premium alloys continue to occupy niches where extreme corrosion resistance and high mechanical strength are required. This bifurcation is enabling more granular product strategies, where manufacturers tailor grades to well environment, drilling method, and instrument sensitivity.
Process innovation is also playing a role. Shot-peening, precision forging, and controlled heat treatment are increasingly standard for high-performance collars, improving fatigue resistance and surface durability. In parallel, software-assisted tool selection is emerging as a differentiator. Recent technical presentations have highlighted how digital evaluation tools can support the scientific selection of non-magnetic drill collars for directional drilling optimization. These developments point to a broader trend: the market is placing greater value on data-backed tool matching and lifecycle performance predictability, not just material grade alone.
Policy, Standards, and Regulatory Expectations
Standards and certification regimes are shaping competitive dynamics as much as raw material availability. Compliance with API specification 7-1 has become a baseline expectation for operators deploying M/LWD systems, with emphasis on magnetic permeability limits and controlled chemistry. In practice, this means suppliers must maintain rigorous quality documentation, traceability, and consistency across production runs. The regulatory environment does not create demand by itself, but it does raise the cost of underperformance and rewards manufacturers with established quality systems. For buyers, this translates into greater reliance on suppliers that can provide certified conformance and predictable delivery performance.
Demand-Side Shifts in Drilling Practice
Demand is being reshaped by the broader evolution of well design and drilling efficiency. Directional and extended-reach wells are becoming more common in complex reservoirs, where magnetic interference can compromise downhole measurement integrity. This has reinforced the need for non-magnetic bottomhole assembly components in many operating environments. At the same time, operators are increasingly sensitive to total installed cost and lifecycle reliability. Upgrades to premium alloys are often deferred when the perceived incremental benefit does not justify the added expense, especially among smaller operators with tighter capital constraints. The result is a demand profile that is expanding in technical importance but remains selective in material grade adoption.
Rental and service-based models also influence demand patterns. Some suppliers are expanding offerings that combine manufactured collars with rental, machining, and BHA support services. This approach lowers upfront capital exposure for customers and aligns supplier incentives with tool performance over time. In markets where flexibility and service responsiveness matter, such models can be as important as the alloy itself.
Supply Chain and Cost Structure Dynamics
Material cost volatility continues to shape product economics. Titanium alloy variants, while offering specific performance advantages, carry higher manufacturing and material costs that limit broader adoption. In contrast, certain austenitic steel grades have become more economically attractive because of favorable raw material cost positioning and established production pathways. This cost structure encourages a tiered market in which lower-cost grades capture volume in many programs, while premium alloys remain reserved for conditions where their properties are essential.
Supply chain resilience is also under scrutiny. Manufacturers with localized production capabilities, diversified sourcing, and strong machining capacity are better positioned to manage lead-time variability and service demand. For end users, this has increased the importance of supplier stability, inventory readiness, and technical support. In a segment where tool failure or magnetic interference can disrupt entire drilling operations, supply reliability is a strategic consideration rather than a logistical detail.
Competitive Landscape and Leading Strategies
The market remains concentrated, with a limited number of established manufacturers holding significant share. This concentration reflects the technical barriers to entry, the importance of certified alloy production, and the value of long-standing customer relationships in drilling services and tool rental networks. Leading firms are competing not simply on price, but on grade breadth, application readiness, and the ability to support M/LWD deployments with consistent quality.
Strategic Positioning of Core Players
Several manufacturers have built recognizable positions by emphasizing different aspects of the value proposition.
Worldwide Casing Collar Locator Market
- Schoeller-Bleckmann Oilfield Technology has positioned itself around a broad family of non-magnetic drill collar and stabilizer grades, with an emphasis on austenitic Mn-Cr-N steels optimized for MWD/LWD and directional drilling. Its product range and API 7-1 alignment support customers seeking predictable magnetic performance and standardized compatibility.
- SBO is known for high-strength, corrosion-resistant non-magnetic alloy steels across multiple grades, targeting downhole tools and drill collars where mechanical robustness and resistance to corrosive environments are priorities.
- Drilling Tools International has focused on both manufactured and rental offerings, including slick, flex, spiral, and pony collars, with shot-peening aimed at sour gas stress corrosion resistance. This mix of product and rental capability supports operators looking to reduce capital exposure while maintaining performance standards.
- Tri Wave LLC supplies non-magnetic drill collars forged from premium austenitic stainless steels, differentiating on stress corrosion cracking resistance and enhanced mechanical properties. Its positioning appeals to programs where environmental aggressiveness and mechanical margin are central concerns.
- NTS Amega Global integrates non-magnetic drill collars and carriers into broader BHA rental and machining services, leveraging high-strength alloys for MWD/LWD applications. Its service-oriented model reflects the growing relevance of flexible, performance-supported procurement.
- Vigor Drilling Oil Tools And Equipment Co., Ltd. has developed a professional manufacturing footprint using Monel K500, Inconel 725, and austenitic steels to API and ISO standards, targeting directional drilling applications with an emphasis on material-grade flexibility.
These positions illustrate a market where differentiation is less about a single product feature and more about alloy range, process quality, service integration, and application focus. Companies that can align material offer with drilling environment and customer operating model are gaining traction.
PW Consulting
Market Evolution: Consolidation, Fragmentation, and New Entrants
The competitive structure is likely to evolve along two parallel paths. On one side, established players may continue to strengthen through service expansion, localized support, and deeper integration with drilling contractors and tool rental networks. On the other, new entrants can find opportunities by specializing in particular grades, regions, or application segments rather than competing across the full spectrum. Recent market activity reinforces this pattern. Participation in industry events and technical presentations has highlighted growing attention to tool selection methodologies, regional demand visibility, and application-specific solutions.
The presence of manufacturers from multiple regions also suggests that geographic coverage and supply responsiveness will become more important over time. Buyers increasingly evaluate suppliers not only on product specifications but also on delivery reliability, technical support, and the ability to adapt to local drilling conditions. This dynamic creates space for both consolidation among broad-line suppliers and fragmentation into niche specialists.
Future Trends and Commercial Opportunities
Gradual Grade Differentiation and Use-Case Alignment
Over the next three to five years, the market is likely to see more deliberate grade segmentation aligned with well environment and instrument requirements. Lower-carbon stainless steel solutions are expected to retain a strong volume position where cost efficiency and adequate non-magnetic performance are sufficient. Premium alloys will remain important for demanding conditions, but adoption will be driven by specific risk profiles and operational justification rather than uniform upgrade programs. For manufacturers, this trend favors portfolios that make grade selection easier for buyers while preserving margins through application-focused engineering.
Service-Integrated Offerings Will Gain Relevance
As operators seek flexibility and predictability, service-linked models will continue to grow in importance. Rental, machining, BHA support, and performance-backed service packages can reduce upfront cost and improve asset utilization. Suppliers that can combine certified product quality with responsive service and technical advisory will be well placed to capture share in segments where operational continuity matters more than initial purchase price. This also creates an opportunity to build longer-term customer relationships based on measurable performance outcomes.
Digital Tool Selection and Performance Data as Differentiators
Technical software and data-driven selection methods are becoming more visible in the market. As operators seek to optimize directional drilling outcomes and reduce trial-and-error in tool choices, the ability to recommend collar grades and configurations based on downhole conditions and performance data will be increasingly valuable. Suppliers that invest in selection support, documentation, and application knowledge can convert technical credibility into commercial advantage. This trend is not about replacing hardware with software; it is about strengthening the link between material choice and drilling results.
Risks and Uncertainties
Several factors could alter the trajectory of growth and competition. Persistent raw material cost pressure, especially for premium alloys, may continue to constrain adoption among cost-sensitive operators. If supply chain disruptions or production bottlenecks affect lead times, buyers may shift toward suppliers with stronger inventory positioning or regional manufacturing capacity. In parallel, if drilling activity patterns shift due to capital discipline or changes in exploration focus, demand for specialized non-magnetic components could moderate in some basins. Finally, any tightening of performance expectations or certification rigor could raise compliance costs and reward only those manufacturers with mature quality systems.
Actionable Guidance for Decision-Makers
For Manufacturers and Suppliers
Portfolio strategy should emphasize clarity of grade application rather than breadth alone. Differentiating through process consistency, surface treatment capability, and verified performance data will matter more than expanding product lists without application context. Investing in service integration, technical advisory, and selection support can help convert engineering credibility into repeat business. Suppliers should also evaluate where regional production, inventory readiness, and responsive machining can reduce customer friction and improve competitiveness in tenders.
For Investors
The market offers exposure to a technically constrained, application-critical segment with steady rather than speculative growth. Evaluation should focus on suppliers with strong certification discipline, defensible alloy and process capabilities, and the ability to serve M/LWD-driven demand. Business models that combine manufacturing with rental, service, or application-specific engineering may offer more durable revenue characteristics than pure hardware sales. Attention to cost structure, especially the balance between premium and lower-cost grades, is important for understanding margin resilience across market cycles.
For Procurement and Operations Leaders
Buying decisions should be structured around total operational risk and performance reliability, not alloy price alone. Establishing clear requirements for magnetic permeability, chemical control, and mechanical suitability can reduce the likelihood of instrument interference or premature failure. Where capital flexibility is important, rental and service-supported models can provide access to certified equipment while managing upfront exposure. Engaging suppliers with strong documentation practices and application knowledge can improve consistency across wells and reduce procurement risk over time.
The non-magnetic alloy drill collar market is at a point where technical precision, material economics, and service readiness are increasingly intertwined. Growth is real, but it is being shaped by selective adoption, standards-driven quality expectations, and the operational need to match collar performance to well conditions. For organizations operating in this space, the most valuable edge will come from understanding where grade selection, application engineering, and supply reliability create durable advantage. Detailed segment-level data, competitive tracking, and tailored strategic recommendations can further sharpen these decisions and support more confident planning across the forecast period.
For detailed analysis of this topic, please visit the official page: Non-magnetic Alloy Drill Collar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com