

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
DNA Microarray for Agriculture Market 2026: Why 6.98% CAGR Reshapes Competitive Growth

DNA Microarray for Agriculture Market: Strategic Trends and Commercial Opportunities
The DNA microarray market for agriculture has evolved from a niche research tool into a foundational technology for modern agrigenomics. Valued at USD 215.0 million in 2025, the market has demonstrated consistent growth over the historical period from 2020 to 2025, expanding from USD 153.44 million at the start of the decade. As the industry looks toward the forecast period spanning 2026 to 2032, the trajectory points toward a projected valuation of USD 344.79 million by 2032, reflecting a compound annual growth rate of 6.98 percent. This growth trajectory signals more than incremental expansion. It indicates a structural shift in how agricultural genomics is deployed across crop improvement, livestock breeding, and disease monitoring. For executives and investors operating in this space, the numbers tell a clear story. The market is maturing, adoption is broadening, and the competitive dynamic is moving from fragmented experimentation toward coordinated commercial scaling.
Market Landscape and Core Challenges
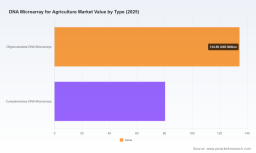
The baseline data establishes a market that has already crossed the USD 200 million threshold and is on a clear upward path. Revenue generation is distributed across mature and emerging geographies, with North America anchoring the largest share, followed by Europe and Asia Pacific, while Latin America and the Middle East and Africa represent smaller but progressively more relevant pockets of demand. By platform type, oligonucleotide-based microarrays command the larger revenue pool, with complementary DNA microarrays forming a substantial secondary segment. In application terms, rice and potato dominate the crop-focused usage, bovine applications lead the animal genetics segment, and sheep plus a broader others category complete the deployment landscape. Despite these encouraging structural indicators, the industry is navigating a set of interconnected challenges that will shape how value is captured over the next several years.
Three challenge areas stand out as particularly consequential. First, the market remains moderately fragmented from a concentration standpoint. The top three players account for roughly 24.6 percent of revenue, and the top five reach approximately 26.2 percent. This level of concentration suggests that no single organization dominates the space, which creates both opportunity and instability. Fragmentation can accelerate innovation through diverse product approaches, but it also complicates standardization, slows interoperability, and places a burden on end users who must evaluate multiple platforms with differing performance characteristics. For commercial leaders, this means that credibility, reproducibility, and service reliability are becoming differentiators rather than optional features.
Second, the transition from research-grade adoption to operational deployment is uneven. While academic and breeding programs have integrated microarray-based genotyping and gene expression profiling into their workflows, broader commercial agriculture often lags due to the need for field-validated assays, cost sensitivity, and integration with existing bioinformatics pipelines. The gap between proof-of-concept and routine use is where many projects stall. Closing that gap requires not only technically robust arrays but also clear guidance on sample handling, data interpretation, and decision support that links genomic output to agronomic or husbandry outcomes.
Third, the competitive threat from alternative genomic technologies is real and growing. Next-generation sequencing continues to expand its footprint in genotyping and transcriptome analysis, particularly where high resolution or discovery-oriented work is required. Microarrays retain advantages in throughput, cost predictability, and targeted assay design, but they must continuously demonstrate relative value. The strategic question is not whether sequencing will displace arrays, but where arrays will hold or extend their position through specialization, speed, and application-specific optimization.
Worldwide Agricultural Nanotechnology Market
Key Drivers of Market Change
Market movement is being shaped by a set of reinforcing drivers that span technology, policy, demand behavior, and cost dynamics. These forces interact rather than operate in isolation, and together they explain why the sector continues to expand at a steady pace even as the broader agricultural technology landscape faces macroeconomic and regulatory headwinds.
Technological Innovation and Platform Specialization
The most direct driver is the ongoing refinement of microarray platforms toward application-specific performance. In crop science, arrays designed for whole transcriptome analysis and targeted exon profiling are enabling more precise studies of plant gene expression across key species. Plant-focused arrays for crops such as tomato, rice, barley, cotton, and potato have broadened the practical utility of the technology by aligning probe content with breeding priorities. In animal genetics, high-throughput genotyping arrays are increasingly used to accelerate selection decisions, screen for traits of interest, and support consortium-derived marker panels. The trend is toward arrays that are not generic tools but tailored solutions built around the genetic architecture of specific organisms and the operational needs of breeding programs.
This specialization matters commercially because it reduces the friction between data generation and decision-making. When an array is designed with a clear use case in mind, the downstream interpretation becomes more actionable, and the value proposition becomes easier to communicate to end users. For technology providers, the implication is that product roadmaps should prioritize biological relevance and workflow integration alongside raw analytical performance.
Policy and Regulatory Environment
Policy dynamics are increasingly influencing where and how agrigenomics tools are adopted. Regulatory frameworks around genetic improvement, traceability, and food safety are pushing breeding programs and supply chain actors toward more rigorous characterization of genetic material. At the same time, public and private investment in food security, climate resilience, and sustainable crop and livestock production has created a favorable environment for genomic tools that can accelerate trait development and verification. Where regulatory or policy pressure is high, there is often an accompanying demand for reproducible genotyping and expression data that can support compliance, certification, or breeding records.
The practical effect is that policy is acting as both a demand catalyst and a design constraint. Arrays used in regulated or semi-regulated settings must deliver consistent results, clear documentation, and data formats that can be integrated into broader quality and traceability systems. This favors providers that offer not only hardware and probe content but also the supporting services and data structures needed for operational readiness.
Demand-Side Shifts in Breeding and Production
On the demand side, the behavior of breeding organizations, seed companies, and livestock operations is shifting toward faster cycle times and more data-driven selection. The pressure to improve yield stability, disease resistance, and climate adaptability is encouraging earlier and more frequent use of genomic information in selection pipelines. In parallel, there is growing recognition that targeted genotyping can provide a cost-effective bridge between low-resolution screening and more expensive discovery methods. For many programs, microarrays offer a practical balance of throughput and affordability, especially when the marker content is well matched to the breeding objectives.
Consumer and downstream market expectations also indirectly influence adoption. As downstream buyers and food brands place greater emphasis on traceability and attribute verification, upstream genetic characterization becomes more valuable as a supporting data layer. This does not mean microarrays are a consumer-facing product, but it does mean that the broader push for transparency and quality assurance can increase the relevance of genomic tools in breeding and production environments.
Cost Structure and Workflow Efficiency
Cost considerations continue to shape procurement and platform selection. Agricultural programs often operate under tight budgets and must justify every analytical expense in terms of breeding progress or operational efficiency. Here, the economic appeal of microarrays lies in the combination of predictable per-sample economics, established workflow maturity, and the ability to process meaningful sample volumes without the variable cost structures that can accompany more open-ended sequencing approaches. As labor, reagent, and informatics costs evolve, platforms that reduce hands-on time and simplify data handling gain an advantage.
Supply-side efficiency is equally important. Providers that can maintain consistent manufacturing quality, offer reliable custom content, and support rapid turnaround for specialized projects are better positioned to retain and expand their user base. In practice, the cost narrative is not simply about price per array. It is about total cost of ownership, including assay design, validation effort, interpretation support, and the risk of failed or ambiguous results.
Competitive Landscape and Leading Strategies
The competitive environment reflects a mix of established life science companies, specialized microarray manufacturers, and service-oriented genomics providers. Each brings a different angle of value, and the strategic differences among them reveal how the market is being shaped.
Strategic Positioning Among Core Players
Agilent Technologies has built a position around plant-focused expression and exon microarrays, with particular relevance to transcriptome analysis in agricultural species such as tomato. This positions the company as a resource for researchers and breeding teams that need detailed gene expression profiling rather than purely genotyping-oriented solutions. The emphasis on plant-specific content suggests a strategy rooted in biological relevance and depth of content for targeted crop applications.
DNA Microarray Market
Thermo Fisher Scientific offers genotyping microarray platforms for plant and animal agrigenomics, with high-throughput screening 옵션이 crop improvement workflows. The strategic strength here is scale and breadth. By supporting both plant and animal applications and emphasizing high-throughput use cases, Thermo Fisher is aligned with larger breeding and screening operations that value throughput consistency and platform maturity.
Illumina Inc. supplies consortium-derived and off-the-shelf genotyping arrays for important crops including barley, cotton, rice, and potato. This positions the company at the intersection of community-driven marker development and practical deployment. The availability of ready-to-use arrays for key crops reduces the design burden for end users and supports standardization across programs that rely on shared marker sets. Illumina’s approach reflects an understanding that adoption often depends on convenience, community validation, and access to well-characterized content.
Arrayit Corporation focuses on custom DNA and protein microarrays optimized for agricultural gene expression, genotyping, and crop research. The custom orientation is a distinct strategic choice. Rather than competing primarily on broad standardized catalogs, Arrayit positions itself to serve projects that need tailored content or specialized configurations. This can be especially valuable in early-stage research, niche crop programs, or situations where existing arrays do not match the biological question.
Eurofins Genomics provides genotyping and gene expression microarray platforms and services for plant breeding and agrigenomics applications. The service-forward model is a meaningful differentiator. By combining platform access with operational support, Eurofins addresses the practical reality that many organizations want genomic results without building all of the surrounding workflow internally. This service angle can be particularly attractive to teams that need flexibility, project-based engagement, and expert assistance in assay selection and data interpretation.
Market Evolution: Consolidation, Specialization, and Entrants
The current landscape is not dominated by a single winner, and the moderate concentration levels suggest room for both consolidation and continued specialization. Over the next several years, three movements are likely to shape the competitive structure.
- Consolidation pressure will increase as larger platforms and service organizations seek to broaden their agrigenomics offerings and capture more of the workflow. This may lead to more bundled value propositions that combine array content, informatics support, and project services.
- Specialization will remain a viable and attractive strategy, especially for providers that can align content closely with specific crops, livestock species, or breeding objectives. Niche depth can defend against generalist competition when the biological application is well defined and the performance bar is high.
- New entrants will continue to test the market, particularly where custom design, rapid turnaround, or regional support creates an opening. Entrants that can demonstrate credible performance and clear workflow integration may capture meaningful pockets of demand even in a crowded field.
For buyers and partners, this evolving structure means that vendor evaluation should go beyond catalog breadth. The relevant questions include how well the platform matches the intended application, how efficiently the provider supports custom or project-based needs, and whether the organization can sustain consistent quality and service over time.
Future Trends and Commercial Implications
Looking ahead across the 2026 to 2032 window, several trends are likely to define the next phase of market development. These trends are not isolated predictions. They are logical extensions of the current drivers and competitive dynamics, and they carry direct implications for how commercial value is created.
Trend One: Convergence of Standardized and Custom Solutions
The market is likely to move toward a hybrid model in which standardized arrays provide the baseline for high-volume applications, while custom or semi-custom designs address specialized breeding goals, regional crop varieties, and emerging animal traits. This convergence reflects the practical reality that no single array portfolio can optimally serve every use case. Standardized offerings reduce design cost and support broader interoperability, while custom solutions preserve flexibility for programs with unique genetic targets. The commercial opportunity lies in helping customers choose the right mix, and in building platforms that can transition smoothly between standard and customized content as needs evolve.
Trend Two: Integration with Decision Support and Informatics
As microarray data becomes more embedded in breeding and production workflows, the value of the data will increasingly depend on how easily it can be interpreted and acted upon. Tools and services that translate array output into breeding recommendations, trait prioritization, or quality records will become more important. This does not necessarily mean that every provider must build full informatics suites, but it does mean that the most competitive offerings will connect more seamlessly to downstream decision processes. Organizations that can reduce the gap between raw signal and operational decision will be better positioned to retain users and expand share of wallet.
Trend Three: Targeted Growth in Climate-Resilient and High-Value Applications
Demand is likely to strengthen in areas where genetic characterization supports climate resilience, disease resistance, input efficiency, and quality attributes valued by downstream markets. Rice and potato applications, along with bovine genotyping, already represent significant usage, and these areas are well placed to benefit from ongoing pressures on food production and livestock performance. Growth may also come from expanding the scope of what arrays are used to monitor, including more nuanced trait panels and integrated expression-plus-genotyping approaches where appropriate. The associated opportunity is to align product development and service offerings with the applications that are both technically suitable and economically important.
Risks and Uncertainties
These trends are accompanied by real uncertainties. Alternative genomic technologies will continue to improve in cost and accessibility, which could compress the role of microarrays in applications where sequencing becomes more advantageous. Standardization challenges may persist if platform diversity outpaces the development of shared reference frameworks or comparable performance benchmarks. Demand may also vary by region and by crop or livestock sector, meaning that aggregate growth will not be uniform across all segments. Finally, regulatory and policy shifts can alter adoption speed, particularly where genetic improvement, traceability, or data usage requirements change. Mitigating these risks requires a clear view of where microarrays retain a durable advantage and where the market is likely to shift toward other modalities.
PW Consulting
Actionable Guidance for Decision Makers
For executives, planners, and investors, the strategic priority is to convert market awareness into targeted action. The following recommendations are intended to help different stakeholder groups navigate the current landscape and prepare for the next phase of development.
For Manufacturers and Platform Providers
- Invest in application-specific differentiation. Broad catalogs are useful, but durable advantage increasingly comes from content and workflow that match the needs of key crops, livestock species, and breeding objectives. Prioritize designs that reduce interpretation burden and improve operational relevance.
- Strengthen service and project support. Many users value assistance with assay selection, validation, and data interpretation. Expanding reliable support capabilities can convert technical capability into commercial stickiness, especially for custom or semi-custom engagements.
- Build for interoperability and scale. As adoption grows, customers will look for consistent performance, manageable cost structures, and compatibility with existing data systems. Scalable process design and clear documentation will be assets in winning and retaining larger programs.
For Investors and Strategic Partners
- Focus on where microarrays hold a clear value advantage. The strongest opportunities are likely in targeted genotyping, expression profiling for defined biological questions, and workflows that benefit from throughput predictability and cost stability. Assess opportunities against these criteria rather than treating the market as uniformly interchangeable with sequencing.
- Evaluate the service and integration layer. Companies that can couple platform capability with practical workflow support may capture more value than those offering instruments or arrays alone. The ability to reduce adoption friction is a meaningful commercial attribute.
- Monitor consolidation and specialization dynamics. Both pathways can create value, but they imply different risk profiles. Consolidation plays depend on execution and integration, while specialization plays depend on sustained relevance in a defined application space. Align investment theses with the pathway that best fits the asset or partner under consideration.
For Procurement and End-User Organizations
- Match platform choice to use case, not just to catalog size. A well-matched array for the target species and biological question will often deliver better outcomes than a larger but less relevant offering. Define the decision context first, then evaluate platforms against that context.
- Assess total workflow cost and risk. Include assay design, validation effort, turnaround time, data interpretation support, and the consequences of ambiguous results in the evaluation. The cheapest per-unit option is not always the lowest-risk or lowest-cost choice overall.
- Plan for future data use. As genomic data becomes more integrated into breeding records, quality systems, and downstream decision support, consider how the chosen platform will fit into longer-term data management and interpretation needs. Early alignment can reduce rework and improve the long-term value of the data generated.
The strategic picture is clear enough to act on, but the details matter. Regional demand patterns, application-level adoption readiness, platform-specific performance trade-offs, and provider-level service capabilities can materially change the outcome of any market entry, investment, or procurement decision. Organizations that need a sharper read on these details will benefit from a more granular assessment of segments, competition, and forward scenarios. A complete research report can provide that level of specificity, including deeper segmentation data, company-level positioning, and customized recommendations tied to particular business objectives.
In a market moving toward both scale and specialization, the most effective decisions will come from combining high-level trend awareness with precise, use-case-relevant intelligence. The DNA microarray market for agriculture is not simply expanding. It is reconfiguring around application focus, workflow integration, and practical value creation. For leaders operating in this space, that reconfiguration is the real opportunity.
For detailed analysis of this topic, please visit the official page: DNA Microarray for Agriculture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com