
Blogs
Doxylamine Market Analysis 2026: Decoding 3.96% CAGR and $625M Growth
By pmarketresearch, 2026-09-18
Doxylamine Market Outlook: Navigating Growth Trajectories and Strategic Opportunities Through 2032
Market Overview and Core Challenges
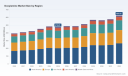
The global doxylamine market has demonstrated resilience and steady expansion over the past half-decade, evolving from a mature antihistamine foundation into a strategically positioned segment within both over-the-counter sleep aids and prescription antiemetic therapies. Valuation trends from 2020 through 2025 reflect a compound annual growth rate of approximately 3.96 percent, with the market reaching a baseline valuation in the mid-470 million dollar range by 2025. Forward projections extend through 2032, indicating a phase of moderate but sustained expansion that will be shaped by formulation diversification, regulatory clarity, and shifting therapeutic demand patterns.
Despite this constructive trajectory, several structural and operational challenges demand careful navigation. Supply chain volatility remains a persistent concern, particularly around the procurement of high-purity active pharmaceutical ingredients and the management of inventory cycles. Seasonal and cyclical demand fluctuations, especially in regions where doxylamine is heavily utilized for cold and allergy relief, can pressure manufacturing planning and create uneven revenue streams. Additionally, regulatory divergence across jurisdictions continues to complicate product positioning. While certain formulations enjoy straightforward OTC classification, others face tighter labeling requirements, evolving safety communications, or payer-specific access protocols that influence downstream adoption and commercial execution.
Product positioning and brand equity present another layer of complexity. The market contains well-established legacy sleep-aid brands alongside newer combination therapies targeting pregnancy-related nausea. This duality creates a bifurcated competitive environment where generic and branded strategies must coexist, and where consumer trust, clinical perception, and reimbursement pathways intersect in ways that can accelerate or constrain growth. Companies that rely solely on volume expansion without differentiated value propositions often face margin compression, especially when raw material cost cycles intersect with pricing competition.
For executives and investors, the central challenge is not whether the doxylamine market will continue to grow, but how efficiently organizations can capture value amid shifting cost structures, regulatory nuance, and patient-consumer behavior changes. Strategic positioning will increasingly depend on supply reliability, formulation agility, and the ability to align commercial models with the specific regulatory and reimbursement realities of each therapeutic application.
Key Growth Drivers Shaping the Market
Technology Innovation and Formulation Advancement
Formulation innovation continues to be a meaningful driver in how doxylamine is positioned and consumed. Oral tablet formats remain the dominant delivery mechanism, reflecting established consumer familiarity and manufacturing efficiency. However, the market is gradually accommodating liquid and syrup formats as well as capsule variations, which expand accessibility for patients with swallowing difficulties or specific dosing preferences. These formulation shifts are not merely cosmetic; they support broader patient adherence, enable more flexible titration, and create opportunities for differentiation in crowded OTC categories. In parallel, process improvements in API synthesis and purification are enhancing batch consistency and reducing variability, which matters particularly in regulated combinations where quality uniformity is tightly scrutinized.
PW Consulting
Regulatory Environment and Approval Pathways
Regulatory clarity has become an increasingly important enabler of market expansion. Doxylamine succinate is widely recognized in OTC nighttime sleep-aid classifications, while combination products with pyridoxine have secured specific pathways for managing nausea and vomiting of pregnancy under appropriate oversight. This dual regulatory identity gives the molecule a broader commercial footprint than many single-indication antipathics. Yet regulatory nuance also creates strategic opportunities for companies that invest in compliance readiness, labeling precision, and documentation discipline. Jurisdictions differ in how they treat doxylamine-containing combinations, and manufacturers that anticipate labeling changes, safety communications, and pharmacovigilance expectations are better positioned to maintain uninterrupted market access. The historical context of earlier product withdrawals in related therapeutic categories also reminds industry participants that reputation, safety communication, and transparent clinical positioning remain critical to long-term brand viability.
Demand-Side Behavior and Therapeutic Adoption
Consumer and clinical demand patterns are evolving in ways that reinforce doxylamine relevance across multiple applications. Sleep disturbances, seasonal allergy burdens, and pregnancy-related nausea continue to drive utilization, but the manner in which these needs are addressed is changing. Patients and clinicians increasingly favor products that balance efficacy with tolerability, predictable onset, and clear usage instructions. In the sleep-aid category, consumers seek accessible nighttime solutions with manageable side-effect profiles, while in the pregnancy nausea segment, the availability of well-characterized combination products helps clinicians and patients navigate symptom management with greater confidence. Reimbursement dynamics add another dimension to demand behavior. Certain payer policies require documented trial and failure of separate OTC components before branded combination therapies are authorized, which influences prescribing behavior, patient access, and the commercial calculus for manufacturers developing dual-channel strategies.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by raw material pricing behavior and manufacturing scale decisions. Producer prices for doxylamine succinate experienced a year-over-year decline in late 2025, partly reflecting inventory accumulation during the third quarter and the broader rhythm of demand planning. While such cost movements can temporarily improve margin flexibility, they also highlight the importance of disciplined procurement strategies and inventory management. Manufacturers with diversified sourcing, strong supplier relationships, and the ability to align production schedules with demand forecasts are better equipped to stabilize costs through cyclical fluctuations. At the same time, the presence of multiple international suppliers across North America, Europe, and Asia creates a competitive cost environment that rewards operational efficiency without sacrificing GMP compliance or regulatory documentation quality.
Scopolamine Market
Competitive Landscape and Leading Strategies
The doxylamine market is moderately concentrated, with a significant share held by a group of established players spanning API suppliers, branded combination product developers, and OTC marketers. This concentration reflects a market where scale, regulatory readiness, and distribution relationships matter, but it also leaves room for specialized manufacturers and regional entrants that can serve distinct therapeutic needs or geographic demand pockets. The competitive environment is best understood as a layered ecosystem rather than a single battleground, with different participant groups competing on different axes.
API-focused suppliers form the foundational layer of the market. Companies with GMP compliance, USDMF and EDMF filings, and broad export capabilities provide essential building blocks for both generic manufacturers and branded developers. Their strategic advantage lies in regulatory documentation, batch reliability, and the ability to serve multiple downstream customers across regions. In this segment, differentiation often comes from certification breadth, quality systems, and the capacity to maintain steady supply through demand cycles. These suppliers compete less on consumer-facing brand recognition and more on cost predictability, compliance consistency, and responsiveness to customer formulation requirements.
Branded and combination product developers occupy a more clinically differentiated position. In the pregnancy nausea segment, for example, companies marketing doxylamine succinate plus pyridoxine combinations have built product identities around specific therapeutic use, targeted messaging, and payer navigation. Their advantage comes from clinical branding, patient support ecosystems, and the ability to manage prior authorization and reimbursement requirements in key markets. This group faces a more complex commercial path than pure OTC marketers because access depends not only on consumer demand but also on clinician adoption and payer policies.
OTC sleep-aid marketers represent another major competitive tier, leveraging established brand recognition, retail channel relationships, and accessible package formats. Their strategic positioning centers on consumer trust, shelf visibility, and pricing dynamics within mass-market channels. In a category where many products rely on similar active ingredients, differentiation can be achieved through branding, formulation presentation, dosing convenience, and channel strategy. The presence of strong legacy brand recognition and retail momentum gives incumbents a durable advantage, but it also raises the bar for new entrants who must compete on trust and distribution as much as product performance.
Recent activity illustrates how these competitive layers interact. Licensing and market-access agreements are expanding regional availability of combination therapies, while localized launches are bringing doxylamine-pyridoxine options to new geographies. At the same time, pricing behavior in raw material markets and the management of inventory cycles are shaping short-term margin narratives for manufacturers across the value chain. The broader trend is one of selective integration and targeted expansion rather than uniform consolidation. Some participants are strengthening their position by combining API capability with downstream product strength, while others are focusing on regional niches or specific therapeutic applications where they can build defensible share.
For decision-makers, the key insight is that success in this market rarely comes from a single lever. Competitive advantage is typically constructed through a combination of supply reliability, regulatory compliance, product positioning, channel access, and reimbursement strategy. Companies that align these elements to a clear therapeutic and geographic focus are better positioned to protect margins and expand relevance as the market matures.
Future Trends and Commercial Opportunities
Looking ahead to the next three to five years, several trends are likely to shape how value is created in the doxylamine market. First, formulation and delivery diversification will remain an important growth lever. While oral tablets will continue to anchor the market, expanded use of liquids, syrups, and capsule variants can open access to patient segments that prefer or require alternative formats. Manufacturers that invest in flexible formulation capabilities and clearly communicate usage benefits may capture incremental share, particularly in categories where adherence and ease of administration influence repeat purchase behavior.
Second, regional access expansion for combination therapies is likely to continue. The normalization of licensing agreements and localized product introductions suggests that doxylamine-pyridoxine combinations will keep extending into new markets where pregnancy-related nausea management can benefit from established, well-characterized options. This trend creates opportunities for partners who can navigate local regulatory requirements, distribution networks, and reimbursement expectations. At the same time, it introduces execution risk, since market entry success depends heavily on regulatory alignment, payer dynamics, and clinician acceptance in each jurisdiction.
Third, cost discipline and supply chain resilience will become increasingly decisive competitive factors. Raw material pricing cycles, inventory timing, and manufacturing efficiency will continue to influence margin outcomes. Organizations that build robust procurement planning, maintain compliance-ready production capacity, and anticipate demand variability will be better positioned to protect profitability when input costs fluctuate. This is especially relevant in a market where concentration is meaningful but not absolute, and where multiple international suppliers create both pricing pressure and sourcing optionality.
Paracetamol Market
These trends point to a set of commercial opportunities for organizations willing to act with precision. There is room to strengthen value in the sleep-aid segment through brand trust, channel execution, and patient-friendly formulation choices. There is also opportunity in the pregnancy nausea segment for companies that can combine clinical credibility, payer navigation, and reliable supply. More broadly, the market favors participants who can integrate upstream API reliability with downstream product strategy, rather than those who compete in only one layer of the value chain. Risks remain, particularly around regulatory communication, reimbursement policy changes, and cost cycles that can compress margins if not managed proactively.
Actionable Guidance for Decision-Makers
For manufacturers and suppliers, the priority is to reinforce supply reliability and regulatory readiness while preserving flexibility in formulation and sourcing. Building stronger quality documentation, maintaining certification breadth, and aligning production planning with demand cycles can reduce exposure to cost volatility and improve customer confidence. Companies should also evaluate where formulation diversification or targeted geographic expansion can add meaningful value without stretching operational focus too broadly.
For investors, the market rewards disciplined exposure to companies with clear therapeutic positioning, credible compliance infrastructure, and realistic reimbursement strategies. It is worth distinguishing between businesses that rely mainly on volume and cost competition and those that combine product differentiation with access management in regulated or payer-sensitive segments. Monitoring raw material pricing trends, licensing activity, and regional launch patterns can provide early signals about where competitive advantage is being built or eroded.
For procurement and purchasing leaders, the emphasis should be on supplier resilience, quality consistency, and predictable pricing rather than short-term cost minimization alone. Diversifying sourcing options, validating documentation readiness, and tracking inventory and pricing signals can help mitigate disruption risk. Procurement strategies that incorporate regulatory and supply continuity considerations are better suited to a market where formulation reliability and compliance readiness directly affect downstream product performance.
As the doxylamine market moves through its next phase of moderate growth and structural refinement, the organizations that succeed will be those that pair market awareness with execution discipline. More granular segmentation data, region-specific dynamics, and customized strategic scenarios can help decision-makers translate these high-level trends into concrete plans. A full market research report offers deeper breakdowns across formulation, application, regional demand patterns, competitive positioning, and pricing context, along with tailored recommendations designed to support practical strategy development.
For detailed analysis of this topic, please visit the official page: Worldwide Doxylamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Lactation Massager Market: Why Home Care Subsidizes Growth in 2025-2032
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Lactation Massager Market
Market Landscape and Core Challenges
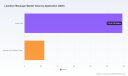
The global lactation massager market has entered a period of sustained expansion, driven by heightened awareness of breastfeeding support and the growing acceptance of at-home therapeutic devices. From 2020 to 2025, the market revenue climbed from approximately $92.2 million to $142.6 million, reflecting a compound annual growth rate of nearly 9.15 percent. Projections extending through 2032 indicate the market will surpass $263 million, with the most pronounced acceleration expected in the mid-to-late forecast window. This trajectory is supported by a convergence of clinical validation, consumer preference for non-invasive comfort solutions, and the broader integration of lactation support into maternal health ecosystems.
Despite the favorable momentum, the industry faces several structural headwinds that will shape competitive outcomes over the next decade. The first challenge revolves around regulatory classification and the resulting compliance burden. Products in this category are typically regulated as Class II therapeutic massagers or vibrators under the FDA’s framework for physical medicine devices. Manufacturers must navigate special controls that specify vibration frequency limits, leakage current thresholds, and skin-surface temperature ranges when heat is applied. These requirements create a non-trivial barrier to rapid product iteration, particularly for startups that lack established regulatory infrastructure. At the same time, the absence of dedicated reimbursement codes means the end-user or healthcare system usually absorbs the full cost, which constrains volume-based adoption in institutional settings.
The second challenge is the tension between feature differentiation and consumer accessibility. As manufacturers introduce warming, vibration, and kneading combinations, the risk of feature creep increases. Overly complex devices can undermine the core value proposition—simple, reliable relief—and complicate usability for new parents who need intuitive, low-learning-curve tools. Manufacturers must balance clinical-grade performance with ergonomic simplicity, a tension that is visible in the growing split between single-function tools and multi-mode integrated devices.
The third challenge lies in market concentration and channel dynamics. The top three players collectively capture a meaningful share of revenue, while the top five expand that footprint further, indicating that brand trust, distribution relationships, and clinical endorsement remain potent moats. New entrants must therefore compete not only on product design but also on evidence generation, retail or direct-to-consumer visibility, and partnerships with lactation professionals. The market is large enough to accommodate multiple players, yet selective enough that undifferentiated offerings struggle to gain traction.
Key Drivers of Market Change
Technological Innovation and Clinical Validation
The most durable driver in this market is the shift from anecdotal comfort products to devices backed by functional design and, increasingly, clinical evidence. Recent developments illustrate this transition. In mid-2025, independent trial results from Amsterdam University Medical Centre quantified breast inflammation outcomes and positioned a clinically validated aid as a breakthrough option for common breastfeeding challenges. This publication builds on earlier hospital pilot data and signals a broader industry move toward measurable efficacy. For manufacturers, the implication is clear: clinical signals are becoming a competitive asset rather than a niche differentiator. Devices that demonstrate reproducible benefits in relieving engorgement, improving milk flow, or reducing pumping discomfort are better positioned to earn trust from lactation consultants, healthcare providers, and discerning consumers.
Technologically, product innovation is progressing along two parallel paths. One path emphasizes integrated multimodal relief, combining heat with vibration or kneading in a single form factor. The other path focuses on ergonomic refinement, compact geometry, and ease of cleaning, which matter deeply for daily use. Some entrants have even introduced smaller warming massagers designed for comfort and convenience, reflecting a consumer demand for discreet, travel-friendly support. The competitive frontier is no longer just about whether a device provides relief, but how precisely it delivers it, how intuitively it is operated, and whether it fits into the routines of nursing and pumping parents.
Policy, Regulatory, and Reimbursement Context
Regulatory dynamics are shaping both entry timing and product architecture. Under current FDA expectations for therapeutic vibrators and massagers, manufacturers must adhere to special controls covering vibration parameters, electrical safety, and temperature limits where heat is applied. These controls do not automatically block market entry, but they do require disciplined design verification and documentation. In practice, this favors companies with established quality systems and the ability to manage 510(k) pathways or exemption qualifications without compromising speed to market.
On the reimbursement side, the landscape remains constrained. There are no dedicated CPT or HCPCS codes for lactation massager devices, and related breastfeeding support services often rely on general evaluation and management codes or breast pump codes. Because massagers themselves are generally not separately reimbursable under standard durable medical equipment policies, commercial adoption depends on out-of-pocket purchasing, bundled offerings, or institutional procurement where clinical value can be justified internally. This reimbursement gap is both a limitation and an opportunity: companies that frame their products as high-value self-care tools, or that integrate them into broader lactation support programs, can still drive adoption without relying on traditional reimbursement channels.
Consumer Behavior and Demand-Side Shifts
Demand-side change is being powered by a cultural and clinical re-framing of breastfeeding support. Parents increasingly view lactation comfort tools as practical, non-invasive aids rather than optional accessories, and they are more willing to invest in devices that reduce pain, shorten pumping sessions, or support regular milk flow. The growth of remote lactation counseling and digital maternal health services is also expanding the addressable audience, because recommendations from professionals can accelerate product awareness and reduce purchase hesitation. In addition, the rise of direct-to-consumer education has made it easier for consumers to compare features, read peer experiences, and seek devices with warming, vibration, and waterproofing attributes that fit lifestyle needs.
From a commercial standpoint, this demand evolution rewards brands that can articulate a clear benefit story and provide consistent quality. Emotional resonance matters, but it must be supported by reliable performance. Products designed by people with direct breastfeeding experience and marketed around practical outcomes such as clogged duct relief, engorgement reduction, and improved lymphatic drainage are gaining attention because they align product claims with real user priorities.
Supply Chain and Cost Structure Evolution
Supply chain considerations are becoming a more prominent part of the strategic conversation. As device portfolios expand from manual tools to electric and heat-integrated models, component selection, battery safety, heating element reliability, and waterproofing requirements influence both unit economics and time-to-market. Manufacturers are increasingly balancing the cost of feature richness against the need to maintain accessible price points. At the same time, channel diversification is reshaping cost structures: direct-to-consumer sales can improve margin control and brand ownership, while retail and professional channel partnerships can accelerate awareness but require trade-offs in discounting and inventory management. Companies that stabilize their supply chains and align product complexity with target price tiers are better positioned to scale without eroding profitability.
Competitive Landscape and Leading Strategies
The competitive set in the lactation massager market blends established consumer health brands with specialized maternal care entrants. Several companies have built their positioning around product architecture, clinical narrative, and ecosystem fit, creating a landscape where differentiation is increasingly multidimensional.
One recurring strategy is multimodal functionality paired with targeted clinical claims. Some leading consumer direct brands have introduced warming and vibrating models, including versions that combine both modalities in a single device, explicitly designed to relieve clogged ducts, engorgement, and mastitis-related discomfort while improving milk flow and reducing pumping time. This approach reflects a move toward comprehensive relief rather than single-mechanism tools. Alongside this, major lactation support brands are offering dedicated massagers to loosen and comfort breast areas, improving both breastfeeding and milk expressing experiences. These portfolios show that the category is no longer about a single product type but a spectrum of solutions adapted to different user preferences.
A second strategy is evidence-led positioning. One Australian company has advanced a clinically validated aid combining temperature, movement, and compression for common breastfeeding challenges, with independent trial results published in a recognized breastfeeding journal. This kind of evidence building strengthens credibility with clinicians and informed consumers, and it can support premium positioning or institutional adoption where internal stakeholders demand substantiation. The April-to-July 2025 trial activity at Amsterdam University Medical Centre, which quantified breast inflammation outcomes and highlighted the device as a breakthrough aid, reinforces this trajectory and suggests that academic collaboration can be a meaningful lever for market trust.
A third strategy is ecosystem integration and bundling. Some manufacturers offer multiple lactation massagers with warming, vibrating, and kneading options, and frequently bundle them with breast pumps. This bundling strategy can increase average order value, simplify consumer choice, and position the massager as part of a holistic expression routine rather than a standalone accessory. Complementary features such as adjustable heat and vibration settings, along with waterproofing, are being used to address practical pain points like cleaning convenience and customizable comfort.
A fourth strategy is specialization by material and usage philosophy. A New Zealand-origin brand known for silicone-based manual breastfeeding products offers massagers and support tools compatible with its broader ecosystem, emphasizing natural, non-toxic relief. Meanwhile, several U.S.-based consumer brands focus on patented or purpose-built designs for nursing and pumping parents, targeting engorgement relief, duct unblocking, milk flow improvement, and lymphatic drainage. This diversity shows that differentiation is not limited to electronics or heat; material choice, form factor, and brand mission all contribute to positioning.
PW Consulting
The market structure is evolving along both consolidating and fragmenting axes. On one hand, the presence of a meaningful concentration among leading players indicates that scale, distribution, and brand recognition matter, and that larger consumer health portfolios can leverage cross-selling and retail relationships. On the other hand, the number of specialized entrants is growing, and innovation is coming from both small focused brands and larger players adding lactation support to their catalogs. New entrants are likely to continue arriving, especially where they can bring a compelling clinical story, a distinctive ergonomic concept, or a channel advantage such as strong professional recommendation networks. Over time, the market may see selective consolidation among smaller brands that struggle to fund regulatory compliance or clinical validation, while successful niche players may be acquired for their product credibility or consumer loyalty.
Future Trends and Commercial Implications
Over the next three to five years, the market is likely to move along three interconnected paths. First, clinical substantiation will become a more standard expectation rather than a rare advantage. As more trial data becomes available and as lactation professionals increasingly reference evidence in recommendations, brands that can demonstrate measurable benefit will be better placed to command trust and, in some contexts, premium pricing. Second, product complexity will keep rising, but winners are likely to emphasize calibrated simplicity: multimodal relief that is easy to operate, easy to clean, and safe for repeated use. Devices that balance heat, vibration, and compression with intuitive controls and clear safety boundaries should outperform overly complicated alternatives. Third, channel and partnership models will diversify. Expect stronger links between device manufacturers, lactation consultants, hospital programs, and digital maternal health platforms, even if reimbursement codes remain limited. Bundling, professional recommendation, and embedded education can all drive adoption without depending solely on direct payback from insurance.
These trends create concrete opportunities. Manufacturers can invest in design-for-compliance, robust thermal and vibration controls, and clinical collaboration to build defensible positions. Investors can look for brands with credible evidence pipelines, stable supply chains, and clear channel strategies rather than feature novelty alone. Procurement and channel partners can evaluate products on usability, safety documentation, and professional endorsement, since these attributes will increasingly influence repeat purchase and recommendation rates.
The main uncertainties relate to regulatory interpretation, reimbursement policy, and consumer price sensitivity. Should expectations around special controls or labeling tighten further, development cycles could lengthen. If reimbursement pathways remain constrained, broader institutional volume may depend on internal procurement logic rather than external coding. And if inflation or category saturation pressures price thresholds, brands will need to justify premium features with demonstrable value.
Actionable Guidance for Decision-Makers
-
For manufacturers, prioritize design that aligns multimodal features with clear regulatory and safety documentation. Invest early in clinical validation or independent testing where feasible, because evidence is becoming a differentiator that supports both consumer trust and professional recommendation. Calibrate product complexity to the target user’s daily routine, and choose channel strategies that balance margin control with visibility among lactation professionals.
Worldwide Breastfeeding Accessories Market -
For investors, evaluate opportunities against three filters: credible differentiation, defensible compliance readiness, and a realistic route to awareness. Favor companies that can articulate measurable user benefits, maintain stable cost structures as they scale multimodal devices, and build relationships with lactation consultants or institutional buyers. Be cautious about plays that rely only on feature announcements without evidence or channel traction.
-
For procurement teams and channel partners, assess products on usability, safety documentation, cleaning practicality, and the strength of professional endorsement. Because reimbursement is generally limited, total value should be judged through the lens of user satisfaction, repeat purchase potential, and compatibility with broader lactation support programs. Device selection should favor options that make daily use easier and that reduce friction for parents and clinicians alike.
For decision-makers seeking detailed segmentation data, company-level profiles, and tailored scenario planning, the full PW Consulting research report provides a deeper breakdown of regional and application dynamics, competitive moves, and forward-looking market scenarios. The complete study is available for teams that need granular inputs to support product planning, investment screening, or procurement decisions.
Breast Pump Market
For detailed analysis of this topic, please visit the official page: Worldwide Lactation Massager Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
DTH Hammer Market: Why the 4.65% CAGR and Asia Pacific's Dominance Change Everything
By pmarketresearch, 2026-09-18
Global DTH Hammer Market: Strategic Trends and Commercial Opportunities (2025–2032)
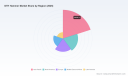
The Worldwide DTH Hammer Market demonstrates steady structural growth, transitioning from a mature equipment segment to a dynamic ecosystem shaped by technological upgrades, shifting mining economics, and evolving end-use requirements. Measured at approximately $822.0 million in 2025, the market expands from $665.4 million in 2020, reflecting consistent value creation across the equipment lifecycle. Over the historical period, annual revenue progression has been influenced by project cycles, capital expenditure pacing, and operator preferences for higher reliability and uptime. Forecasts indicate growth accelerating through the late 2020s, with the market reaching $944.32 million by 2029 and crossing the $1 billion threshold by 2030 at $1022.16 million, before reaching $1129.96 million in 2032. The CAGR of 4.65% over the 2026–2032 forecast window indicates a market that is not merely expanding in nominal terms, but recalibrating around performance, serviceability, and application-specific engineering.
Hydraulic Hammer Market
This trajectory is not uniformly distributed. Revenue concentration remains moderate, with the top three players accounting for 38.5% of the market and the top five reaching 52.1%, indicating a competitive middle tier where regional specialists, application-focused manufacturers, and emerging cost-optimized suppliers continue to compete alongside established global brands. The balance of share across segments reveals where operators allocate spend: large-diameter and high-pressure configurations command a larger portion of revenue, while lower- and medium-pressure variants sustain significant utilization in shallower drilling, water infrastructure, and construction. Application-wise, mining remains the dominant revenue driver, followed by water well drilling and construction, with oil and gas contributing a smaller but strategically important portion tied to well development and geothermal activity.
Several inflection points define the current market environment. First, the shift from equipment replacement to performance-maximizing upgrades is changing purchasing logic. Operators increasingly view down-the-hole hammers as part of an integrated drilling system, weighing air consumption, penetration consistency, and service intervals alongside purchase price. Second, raw material volatility is pressuring cost structures across the supply chain. Tungsten carbide, a critical material in DTH hammer bits and internal components, experienced an average unit price increase of 9% in 2024 due to supply constraints in tungsten mining, and combined fluctuations in carbide and high-grade steel pushed manufacturing expenses for mining drill bits and related DTH tools up by 5–7% annually. These cost dynamics are forcing manufacturers to reevaluate material sourcing, standardize component families, and communicate total cost of ownership more effectively. Third, the operational context for DTH drilling is changing. High metal prices in 2025 sustained elevated activity levels in global mining markets, benefiting demand for DTH drilling equipment, while the ability of DTH hammers to perform effectively in hard rock and relatively populated areas with reduced risk to existing structures expands their role beyond traditional remote operations.
The practical implication for decision-makers is that the market is growing, but competitiveness is increasingly determined by engineering precision, aftermarket strength, and the ability to manage input cost pressure without eroding margins. Companies that treat DTH hammers as commoditized consumables risk losing share to competitors that frame product value around uptime, air efficiency, and configuration flexibility. At the same time, buyers face a widening range of solutions, requiring clearer evaluation criteria to distinguish genuine performance differences from positioning language.
Key Drivers Reshaping the DTH Hammer Market
Technology innovation is moving the market beyond incremental improvements toward measurable drilling efficiency and system-level integration. Recent product and exhibition activity underscores this direction. In early 2026, Sandvik introduced the Leopard DI610i high-performance down-the-hole surface drill rig for open-pit mines, signaling continued investment in rigs optimized for DTH performance in surface operations. Around the same period, Epiroc showcased the Smart Roc T40 rig with DTH hammer and a new integrated OilQuick bracket at CONEXPO-CON/AGG 2026, reinforcing a trend toward smarter rig linkage, quicker tool change methods, and configuration flexibility across surface applications. These launches reflect a broader shift: DTH hammers are no longer evaluated in isolation, but as part of a drilling ecosystem where rig compatibility, bit mechanics, and operator ergonomics jointly determine productivity. The commercial consequence is that manufacturers are competing on integrated performance rather than standalone tool attributes, and buyers are prioritizing solutions that reduce cycle time and simplify field adjustments.
Policy and regulatory dynamics are also shaping demand patterns. Environmental and community considerations increasingly influence site selection and drilling method choice, especially where operations intersect with inhabited or infrastructure-sensitive areas. In this context, DTH hammers are valued for their suitability in hard rock formations and their ability to support drilling in populated areas with reduced risk to existing structures compared to alternative methods. This characteristic expands the pool of viable projects, particularly in water well development, urban construction, and certain mining expansions where vibration, noise, and structural impact are scrutinized. Regulatory expectations do not merely constrain operations; they redirect demand toward equipment that can meet performance requirements under tighter site conditions. As a result, manufacturers that can demonstrate controlled operation, reliable casing compatibility, and predictable penetration behavior are positioned to capture project approvals more readily.
Demand-side behavior reflects both cyclical commodity economics and structural changes in how drilling services are procured. Supportive metal prices in 2025 helped sustain elevated activity in global mining markets, which in turn lifted demand for DTH drilling equipment and related tooling. Beyond the cyclical support, end-users are increasingly focused on operational continuity. Aftermarket solutions remain an important part of the value proposition; Epiroc’s 2025 reporting highlighted sustained demand for tools and attachments, with DTH-related equipment and aftermarket solutions remaining strong. This pattern indicates that buyers are willing to invest in equipment that supports longer service life, easier maintenance, and predictable replacement cycles. The shift is especially meaningful for contractors and producers who manage fleets across multiple sites, where downtime directly affects project economics. Demand is therefore becoming more discerning: price remains relevant, but reliability, parts availability, and configuration adaptability increasingly determine repeat purchasing.
Supply chain and cost structure changes put additional pressure on both producers and buyers. The 5–7% annual increases in manufacturing expenses for mining drill bits and related DTH tools, driven by tungsten carbide and high-grade steel price fluctuations, illustrate how raw material exposure affects product economics. This environment rewards companies that can redesign hammer families with modularity, standardize high-wear components, and negotiate more resilient material supply arrangements. It also matters for buyers, who must weigh whether lower upfront prices translate into higher total cost when wear rates, air consumption, and replacement frequency are considered. The broader trend is a market in which cost discipline and engineering efficiency must be pursued together rather than in isolation. Companies that can balance material cost management with performance retention are better positioned to defend margins while maintaining competitiveness.
Taken together, these drivers suggest a market where growth is supported by application expansion, performance-led procurement, and systemic integration rather than raw volume alone. The most meaningful opportunities are likely to accrue to organizations that can align product development with site constraints, fleet economics, and material cost realities.
Competitive Landscape and Leadership Strategies
The competitive field combines global incumbents with strong aftermarket capabilities and regional specialists offering cost-competitive or application-focused solutions. Sandvik, Epiroc, and Atlas Copco each compete from a position of broad portfolios and established channel networks. Sandvik’s offering centers on high-performance DTH hammers engineered for efficiency, durability, and precise drilling performance across mining and construction applications. Epiroc provides advanced DTH hammers, including COP M-series and DTH 5 hammers with multiple configurations for surface and underground operations in mining, quarrying, and construction. Atlas Copco delivers high-performance DTH hammers designed for demanding operating environments in mining, construction, and water well drilling. Collectively, these companies benefit from the ability to supply integrated rig-tool-support pathways, which reduces integration friction for large operators and supports repeat business through service and parts ecosystems.
Specialist and regional players pursue differentiation through focused engineering or value positioning. Mincon emphasizes precision-engineered DTH hammers that optimize air usage for outstanding drilling performance in mining, waterwell, geothermal, and construction applications, an angle that directly addresses operating cost and efficiency. Halco Rock Tools manufactures DTH hammers, drill bits, and casing systems for mining, quarrying, construction, water wells, and formation sampling, positioning itself around complete hole-making solutions rather than hammer-only offerings. Drill King International produces a comprehensive range of DTH air hammers, water hammers, and reverse circulation hammers for various drilling challenges, broadening its addressable use cases beyond conventional DTH air systems. Mindrill focuses on DTH hammers optimized for hard rock with high penetration rates and low maintenance, a proposition aligned with difficult formation drilling where throughput and service frequency matter. Numa designs and supplies large-diameter DTH hammers for holes from 3.5 to 48 inches in mining and construction, targeting a specialized size segment where capacity and hole diameter justify distinct engineering choices. Ingersoll Rand provides DTH hammers as part of its broader industrial equipment portfolio for drilling operations. Guizhou Sinodrills Equipment (Sinodrills) supplies cost-effective and reliable DTH hammers and drilling tools, including the GSE DHD series, for global rock drilling applications, appealing to buyers seeking dependable performance with a sharper price profile.
Recent company activity illustrates how strategy is evolving in practice. Sandvik’s Leopard DI610i introduction for surface open-pit mining reflects continued emphasis on high-performance surface rigs paired with DTH tooling. Epiroc’s Smart Roc T40 display with DTH hammer and integrated OilQuick bracket demonstrates attention to rig-tool integration and field flexibility. Epiroc’s 2025 reporting on sustained demand for tools and attachments, with aftermarket solutions remaining strong, reinforces the importance of service and replacement cycles in maintaining revenue resilience. Robit’s streamlining of its H-series Down the Hole hammer family into a modular offering, aimed at improving efficiency in the DTH product line, points to a broader industry movement toward modularization as a way to manage complexity, standardize service, and respond faster to configuration demand. These developments indicate that differentiation is increasingly achieved through system compatibility, modularity, and service strength rather than through hammer geometry alone.
Market structure is evolving along multiple lines. Consolidation pressure exists at the top, where established players leverage scale, global distribution, and aftermarket depth. At the same time, the moderate concentration levels leave meaningful room for differentiation in the middle and lower tiers. New entry and expansion are most viable where companies can address a specific size class, formation type, or application requirement more effectively than generalist suppliers. Cost-competitive suppliers continue to expand their reach, especially where buyers prioritize reliable function and favorable pricing over premium brand attachment. However, the rising cost of materials and the growing importance of uptime create a ceiling for pure price competition; sustainable positioning increasingly requires demonstrable efficiency advantages, predictable service intervals, or configuration flexibility that reduces total operating cost. The strategic implication is that incumbents must continue to invest in integration and service ecosystems, while challengers need credible performance claims and a clear application niche to avoid competing solely on price.
Forward Outlook: Trends Defining the Next Three to Five Years
One clear trend is the continued emphasis on system-level performance over component-only specifications. As rigs, hammers, bits, and service practices become more tightly linked in operator evaluations, the market will likely reward solutions that reduce setup time, improve air efficiency, and maintain penetration consistency across varied formations. This favors manufacturers that can demonstrate measurable operating benefits and provide configurations suited to distinct site conditions. Companies that treat the hammer as a standalone consumable will face growing pressure from integrated offerings that tie tooling performance to rig capability and service availability.
PW Consulting
A second trend is the expanding relevance of DTH drilling in applications beyond traditional hard-rock mining. Water well infrastructure, construction-related foundation and blast-hole work, and geothermal-related development can all benefit from DTH’s characteristics in hard formations and its comparatively controlled impact in sensitive settings. If project activity in these segments continues to grow, demand will become more diversified, reducing reliance on any single end-use cycle and creating opportunities for manufacturers with application-specific variants and casing-compatible tooling strategies. The diversification also encourages broader aftermarket demand, since multiple application segments generate ongoing service and replacement needs.
A third trend is cost and supply chain resilience becoming a permanent competitive variable rather than a temporary disruption. With raw material exposure continuing to influence manufacturing expenses, modular product design, standardized high-wear components, and disciplined sourcing will likely remain central to margin protection. Buyers will increasingly scrutinize total cost economics, which could compress margins for suppliers that cannot justify performance premiums and could advantage suppliers that can demonstrate lower operating cost despite higher initial price. This dynamic introduces uncertainty: commodity-driven project pacing can shift demand quickly, and material price swings can alter both supply and purchasing behavior. Still, the direction of travel points toward a market where efficiency, modularity, and service reliability are integral to growth rather than optional enhancements.
Strategic Implications for Decision-Makers
For manufacturers, the priority is to align product strategy with how buyers now evaluate drilling systems. Modular hammer families, air-efficient designs, and clear service intervals can support both cost management and performance claims. Companies should also prepare for a more demanding aftermarket environment by ensuring parts availability, compatibility information, and configuration guidance are easy to access and apply in the field. Differentiation should be anchored in measurable operating benefits rather than broad positioning language, especially as material costs continue to pressure margins.
For investors, the most relevant signals are aftermarket resilience, application diversification, and the ability to manage input cost volatility without eroding value. Businesses that combine credible performance with service depth and a defensible niche in size, formation, or end-use are better positioned to sustain growth through market cycles. Attention should also be paid to integration moves and modularization strategies, since these can reveal where competitive advantage is being built over the next planning horizon.
For procurement and operations leaders, the key is to evaluate DTH solutions against total operating economics rather than first cost alone. Air consumption, penetration stability, service frequency, and compatibility with existing rig setups can materially affect project economics. A disciplined comparison framework that reflects formation requirements, hole diameter needs, and site constraints will help avoid false savings from lower-spec options that increase downtime or wear. Detailed segment-level comparisons of configuration families, application use patterns, and regional pricing dynamics can sharpen procurement decisions and reduce operational risk. For a closer look at the full segmentation, company positioning, and tailored scenarios across regions and applications, the complete PW Consulting report provides structured detail and custom analysis paths to support planning.
DTH Drill Market
For detailed analysis of this topic, please visit the official page: Worldwide DTH Hammer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Eco-Friendly Beneficiation Reagents Market: Why Biodegradable Isolation From 2020–2032 Forecasts a 6.5% Growth Path
By pmarketresearch, 2026-09-18
Navigating the Green Shift: Strategic Insights for the Eco-friendly Beneficiation Reagents Market
Market Landscape and Core Challenges
The global market for eco-friendly beneficiation reagents has entered a phase of sustained expansion, reflecting the mining sector’s broader transition toward lower-impact processing. Over the 2020–2025 period, the industry experienced consistent revenue growth, propelled by incremental adoption of bio-based collectors, non-toxic frothers, and organic depressants. Current trajectories project steady compounding growth well into the early 2030s, signaling that sustainability is no longer a peripheral consideration but a structural requirement for mineral processing operations. The market’s evolution mirrors a broader industrial pivot: rather than treating environmental compliance as a cost center, leading operators increasingly view green reagents as enablers of process efficiency, tailings reduction, and long-term operational license continuity.
Despite this momentum, the industry faces a tightly coupled set of challenges that will shape competitive outcomes over the next decade. First, performance parity remains a persistent tension. Traditional reagents such as xanthates and fossil-derived collectors have decades of operational history, well-understood kinetics, and predictable cost structures. Replacing them with biodegradable collectors or bio-based pH modifiers often requires re-engineering flotation circuits, recalibrating dosage regimes, and retraining plant personnel. For many mid-tier and junior mining companies, the perceived operational risk of switching formulations outweighs the environmental benefits, especially when ore bodies are complex or recovery margins are thin.
Second, the regulatory environment is accelerating adoption but fragmenting demand signals across jurisdictions. Environmental discharge limits, aquatic toxicity standards, and corporate sustainability commitments are pushing procurement teams toward lower-toxicity alternatives. However, regulatory timelines, testing protocols, and compliance expectations differ markedly between established mining regions and emerging resource frontiers. This creates a dual challenge for reagent manufacturers: products must satisfy stringent European and North American chemical safety expectations while remaining cost-competitive and operationally practical in markets where processing infrastructure and waste management capacity vary widely.
General Reagents Market
Third, the supply chain for bio-based feedstocks introduces a new dimension of volatility. Renewable raw materials, including plant-derived oils, lignin-based intermediates, and fermentation-derived biosurfactants, offer compelling environmental profiles. Yet their availability, batch consistency, and pricing are subject to agricultural cycles, logistics constraints, and competing demand from other industrial sectors. For flotation chemical producers, building reliable bio-feedstock pipelines is as critical as formulation innovation. Companies that fail to secure scalable, traceable, and cost-stable inputs risk losing ground to competitors who can deliver consistently performing green reagents without supply disruptions.
Together, these dynamics suggest that the market is moving from early experimentation toward commercial validation. The question is no longer whether eco-friendly reagents will gain share, but which players can deliver the right combination of performance, regulatory alignment, supply reliability, and total cost of ownership.
Key Drivers Reshaping the Market
The expansion of eco-friendly beneficiation reagents is not being driven by a single force. It is the result of overlapping technological, regulatory, demand-side, and supply-side shifts that reinforce one another. Understanding these drivers is essential for companies deciding where to invest, what capabilities to build, and how to position products for different mining segments and geographies.
Technology Innovation and Formulation Breakthroughs
Advancements in green flotation chemistry are steadily narrowing the performance gap with conventional reagents. Research and commercial development increasingly focus on bio-based collectors, safer frothers, and organic depressants that can operate effectively in complex ore environments. Recent academic and industry reviews have introduced classification frameworks for green reagents based on biobased origin, biodegradability, and safer chemical profiles, providing a common language for evaluating alternatives beyond simple toxicity comparisons. This kind of structured assessment is helping procurement teams and process engineers move from qualitative sustainability claims to more rigorous performance benchmarking.
On the commercial side, major reagent developers are showcasing products aimed at both environmental improvement and process efficiency. Advanced collectors and energy-efficient coarse particle flotation formulations are being positioned to improve recovery while reducing energy intensity, particularly for base metals, lithium, nickel, and other minerals tied to the energy transition. At the same time, manufacturers are launching high-performance reagents for industrial minerals and phosphate processing that target higher recovery rates and lower dose requirements. These innovations matter because they reframe green reagents as dual-purpose tools: they address compliance and ESG objectives while also supporting recovery, throughput, and reagent economics.
Policy, Regulation, and the Compliance Accelerator
Regulatory pressure continues to be one of the most powerful catalysts for adoption. Stricter environmental rules and corporate sustainability targets are driving interest in biodegradable, low-toxicity, and bio-based flotation chemicals designed to reduce aquatic toxicity and meet discharge limits. In parallel, evolving chemical safety frameworks and regulatory support for low-toxicity alternatives are encouraging innovation in froth flotation chemistry. The practical effect is that compliance is increasingly shaping formulation priorities, not merely end-of-pipe waste management.
For mining companies, this regulatory momentum translates into procurement shifts and process redesign decisions. Reagents with improved toxicological profiles can reduce permitting friction, simplify wastewater handling, and support broader corporate decarbonization and biodiversity commitments. For reagent suppliers, the regulatory direction rewards products that can demonstrate measurable safety and environmental advantages while maintaining process reliability. The companies that benefit most are those able to align their innovation pipelines with emerging compliance expectations without over-indexing on regional regulatory niches that may not scale.
Demand-Side Shifts Across Mining Business Models
Demand for sustainable beneficiation reagents is being shaped by changing mining business models, ore quality trends, and investor expectations. Lower-grade resources and more complex ore bodies are prompting operators to seek reagents that improve selectivity and recovery without escalating chemical consumption or environmental burden. At the same time, precious metals and base metals mining operations face mounting scrutiny from investors, off-takers, and community stakeholders, all of whom are paying closer attention to water use, chemical discharge, and tailings footprints.
PW Consulting Chemical & Energy Research Center
This demand-side evolution is especially visible in application areas where processing efficiency and environmental risk intersect. Precious metals processing has long been a focus for non-toxic leaching alternatives, while base metals flotation continues to attract interest in collector and frother innovations that can improve recovery and reduce reliance on higher-impact chemistry. Iron ore processing and industrial minerals operations are also part of the equation, particularly where beneficiation decisions influence downstream competitiveness, residue management, and reputational exposure. The overarching trend is that buyers are increasingly evaluating reagents through a total-cost lens that includes compliance risk, operational flexibility, and ESG alignment rather than short-term price alone.
Supply Chain, Cost Structure, and Feedstock Realism
The commercial viability of eco-friendly reagents depends heavily on supply chain maturity and cost structure. Bio-based feedstocks and renewable intermediates can offer strong environmental credentials, but they also introduce variables that traditional chemical supply chains were not designed to manage. Feedstock availability, conversion yields, transportation costs, and supplier concentration can all affect final pricing and consistency. Lignin-based reagents derived from forest biomass and other renewable inputs illustrate both the promise and the complexity of this transition: they can provide biodegradable, non-toxic alternatives for sulfide ore flotation, but scaling them into routine plant use requires dependable sourcing and process validation.
Cost dynamics are further complicated by the need to justify switch-over expenses. Even when a green reagent offers attractive environmental attributes, mines will assess whether it can match recovery, reduce downtime, or lower downstream treatment costs. If the total operating impact is favorable, adoption accelerates. If the switch creates uncertainty in recovery or increases reagent consumption, adoption slows. This reality means that supply chain strategy and product design must advance together. Manufacturers that can stabilize feedstock access, control formulation variability, and demonstrate reliable plant performance are better positioned to convert regulatory and ESG interest into durable demand.
Competitive Landscape and Leading Strategies
The competitive picture in eco-friendly beneficiation reagents is defined by a mix of established chemical leaders, specialized innovators, and regional players targeting specific processing pain points. The market remains moderately concentrated, which gives larger players advantages in formulation scale, application support, and global distribution, while also leaving room for focused entrants with strong technical differentiation. The strategic question for incumbents is how to convert broad portfolios into credible green alternatives; for newer entrants, the challenge is how to prove performance and secure long-term supply commitments.
Worldwide Eco-Friendly Bitumen Market
Incumbents Building on Portfolio Breadth
Large diversified chemical companies are leveraging existing mining solutions portfolios to develop more sustainable flotation products. Nouryon, for example, offers a wide range of flotation collectors for minerals such as phosphate, iron ore, potash, and calcite, with an emphasis on reducing environmental impacts through product reformulation, including efforts to remove certain legacy surfactants and develop lower-impact options. Clariant has similarly built a mining solutions platform around collectors and frothers for sulfide ores, iron ore, phosphate, potash, and a growing set of transition minerals, with a focus on safer alternatives to conventional chemistry, coarse particle flotation, and reduced environmental footprint.
BASF and Syensqo reflect a comparable approach from complementary angles. BASF develops collectors, frothers, and modifiers designed to improve recovery and reduce dose rates while improving safety profiles and incorporating biodegradable options where feasible. Syensqo supports base and precious metals processing with flotation collectors, promoters, and frothers intended to improve sustainability profiles relative to more traditional chemistries while enabling more efficient mineral processing. Arkema, including its associated mineral processing assets, emphasizes enhanced selectivity and recovery through tailored depressants, collectors, frothers, and related products for phosphate, silica sand, iron beneficiation, and industrial minerals.
What distinguishes these players is not simply product volume, but the ability to pair formulation development with application engineering, testing support, and global reach. Their strategies typically center on offering multiple pathways for customers: improving existing circuits with better-performing variants, reducing chemical intensity, and transitioning to greener chemistries without abandoning process reliability. This breadth is a meaningful advantage when mines want to trial alternatives gradually rather than undertake full-scale re-engineering.
Specialized Players Targeting High-Value Problems
At the other end of the competitive spectrum, specialized companies are focusing on discrete but commercially important challenges. Several firms are developing cyanide-replacement leaching reagents for precious metals processing, aiming to provide low-toxicity, non-polluting alternatives with comparable or improved recovery in heap leaching, CIP, and CIL operations. This segment has attracted sustained attention because it directly addresses both environmental risk and process continuity in gold ore beneficiation.
Other innovators are pursuing more fundamental chemistry shifts. Biosurfactant-based additives and fermentation-derived solutions are being explored as ESG-friendly reagents to improve recovery from low-grade ores and tailings. These approaches can offer a different value proposition from conventional chemical formulations: rather than simply substituting one collector or frother for another, they may help unlock recovery from materials that are economically marginal under traditional processing conditions. If scaled effectively, such technologies could expand the economic horizon for both primary extraction and tailings reprocessing.
Market Evolution: Integration, Differentiation, and New Entrants
The competitive landscape appears to be evolving along several lines. First, incumbents with broad reagent portfolios are likely to continue consolidating technical services and application data, using their scale to reduce customer switching costs and accelerate trial-to-commercial pathways. Second, differentiation will increasingly depend on demonstrable attributes: biodegradability, safer chemical handling, reduced dose rates, improved recovery at lower energy intensity, and stronger environmental profiles. Products that can make these claims credible, backed by consistent supply and application evidence, will gain an edge over those competing primarily on price or general sustainability language.
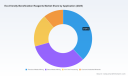
Third, regional specialization remains important. Asia Pacific continues to represent a substantial revenue base, reflecting the scale and diversity of mining and mineral processing activity in the region. Latin America also represents a significant share of market value, driven by active mining economies and expanding mineral processing demand. North America, the Middle East and Africa, and Europe contribute additional, more varied demand profiles shaped by local mineral mixes, regulatory conditions, and processing infrastructure. Companies operating across these regions must navigate different ore types, operating practices, and compliance expectations, which makes localized technical support and flexible product design increasingly valuable.
Finally, the sector is likely to see continued entry by firms targeting specific gaps, such as cyanide alternatives, lignin-based collectors, or biosurfactant additives. Some of these entrants may remain niche players; others may become acquisition targets if their technologies prove scalable and align with the strategic priorities of larger chemical suppliers. The broader trajectory points toward a market where credibility, repeatability, and supply resilience matter as much as formulation novelty.
Future Trends and Commercial Implications
Looking ahead, three interconnected trends are likely to shape the eco-friendly beneficiation reagents market over the next three to five years.
The first trend is the gradual mainstreaming of green reagents in selective applications rather than blanket substitution. Adoption will likely accelerate where the value case is clearest: precious metals leaching substitutions, flotation circuits facing stringent discharge constraints, and processing routes where improved selectivity can reduce downstream costs or tailings burden. In other settings, adoption may proceed more slowly, especially where ore complexity or circuit design makes reformulation riskier. The commercial opportunity lies in targeting the right applications first and building proven performance records that can later be extended to adjacent use cases.
The second trend is deeper integration between formulation innovation and process optimization. Green reagents will increasingly be evaluated not only for their chemical profile, but also for how they interact with recovery targets, energy consumption, water management, and tailings behavior. Coarse particle flotation, lower dose regimes, and improved selectivity are all examples of directions that can blur the line between sustainability and operational efficiency. Companies that position products as part of a broader process improvement strategy, rather than as stand-alone chemical purchases, are likely to win stronger customer commitment.
The third trend is the growing importance of feedstock strategy and lifecycle credibility. As bio-based and biodegradable options become more prominent, procurement and technical teams will pay closer attention to raw material origins, supply consistency, and end-of-life behavior. This creates an opportunity for suppliers that can document renewable sourcing, maintain reliable production, and provide transparent performance data. It also introduces risk for players that depend on volatile feedstocks or cannot guarantee consistent quality across batches.
These trends collectively point to a market that will reward differentiation grounded in real operating value. The upside is significant for suppliers that can demonstrably improve recovery, reduce environmental exposure, and stabilize supply. The downside risk lies in over-promising on sustainability without delivering consistent performance, or in building business models around feedstocks and regulations that may shift faster than commercialization timelines.
Action Priorities for Decision Makers
For manufacturers and product developers, the immediate priority is to align formulation roadmaps with the applications where performance, compliance, and economics reinforce each other. Investment should favor chemistries and delivery models that reduce dose requirements, support safer handling, and can be validated in real flotation or leaching conditions. Equally important is securing supply chains for renewable or lower-impact feedstocks so that product claims can be sustained at commercial scale.
For investors, the most relevant signal is differentiation backed by repeatable customer outcomes. Opportunity exists in companies with strong application data, credible feedstock strategies, and clear relevance to high-stakes segments such as precious metals leaching, base metals flotation, and processing of ores tied to the energy transition. Caution is warranted where growth narratives rely primarily on regulatory optimism or broad sustainability messaging without evidence of process-level benefit and supply resilience.
For procurement and operations leaders in mining and mineral processing, the strategic task is to move beyond simple product substitution and evaluate green reagents within the context of circuit performance, water and tailings management, and long-term permitting exposure. Piloting should be structured to measure recovery, reagent consumption, handling safety, and downstream implications, not just environmental attributes. A disciplined evaluation framework can reduce switching risk while identifying reagent strategies that support both operational and sustainability goals.
Organizations seeking a more granular view of segmentation, regional demand patterns, application-level dynamics, and competitive positioning can benefit from a deeper benchmarking exercise. Detailed market data and customized strategic support are valuable for translating these high-level trends into concrete sourcing, investment, and product decisions. Readers looking for a fuller breakdown of market sizing, segmentation splits, and leading-company strategies are encouraged to consult the comprehensive PW Consulting research report for additional detail and tailored guidance.
For detailed analysis of this topic, please visit the official page: Eco-friendly Beneficiation Reagents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Soft Ice Cream Powder Market: Why the 5.25% CAGR Story Hides Bigger Shifts Through 2032
By pmarketresearch, 2026-09-18
Navigating Momentum and Complexity in the Worldwide Soft Ice Cream Powder Market
Market Status and Critical Inflection Points
The global market for soft ice cream powder has entered a phase of structured expansion, characterized by consistent demand growth and evolving formulation standards across commercial foodservice channels. Between 2020 and 2025, the industry navigated a period of post-pandemic operational normalization, with revenue trajectories reflecting steady adoption in quick-service environments and specialty dessert outlets. Forecasts extending through 2032 point to a compound annual growth rate of approximately 5.25 percent, suggesting that the sector will continue to benefit from institutional menu innovation, increased reliance on powdered formats for operational consistency, and growing appetite for customizable dessert components.
At the macro level, the market has crossed a threshold where powdered soft serve formats are no longer viewed solely as cost-efficient alternatives to liquid mixes. Instead, they are increasingly integrated into product development roadmaps that prioritize shelf stability, logistical flexibility, and consistent texture performance across varying ambient conditions. This structural shift supports revenue visibility for manufacturers and helps foodservice operators manage ingredient procurement more predictably, particularly in regions where cold-chain constraints or volatile dairy pricing pressures exist.
Despite the favorable trajectory, three interconnected challenges are reshaping how participants position themselves. First, raw material volatility remains a persistent pressure point. Dairy derivatives such as skim milk powder and whole milk powder continue to experience price fluctuations tied to regional supply balances, export policy adjustments, and broader commodity cycles. When input costs move quickly, manufacturers must balance margin protection with competitive pricing for end users who are themselves facing consumer price sensitivity.
Second, formulation complexity is intensifying. Operators and end consumers increasingly expect cleaner labels, improved melting resistance, and reliable performance across different soft serve machines. Achieving these outcomes simultaneously places higher demands on emulsification systems, stabilizer blends, and processing consistency. Companies that can standardize premium sensory outcomes while maintaining operational compatibility across widely used equipment configurations are gaining an advantage, but this capability requires sustained technical investment and rigorous quality control.
Third, regulatory alignment and trade dynamics are adding a layer of geopolitical complexity. Regional agreements and domestic availability measures influence the flow of dairy-based inputs, export availability, and cost structures for premix suppliers. Businesses that rely on cross-border ingredient sourcing must monitor policy shifts that affect supply continuity, especially where export caps or domestic protection measures alter the availability of key powders. These dynamics do not necessarily constrain growth, but they demand more disciplined sourcing strategies and scenario planning.
Taken together, the market environment favors organizations that can marry formulation expertise with resilient supply planning. The revenue expansion expected over the coming years is not automatic; it will be captured by players who convert operational consistency, ingredient reliability, and sensory differentiation into commercial value.
Key Drivers Reshaping the Market
Technology, Formulation, and Sensory Performance
One of the most meaningful drivers in the soft ice cream powder market is the ongoing refinement of formulation technology. Modern premix systems are increasingly designed to deliver creamy mouthfeel and controlled melt-down without relying on overly complex ingredient lists. Manufacturers are investing in stabilizer and emulsifier architectures that maintain structure across temperature variations and improve texture consistency from the first serve to the last. This matters because soft serve operators face direct customer scrutiny on texture and visual appeal; even minor inconsistencies can affect repeat purchase behavior.
A second area of innovation lies in dairy-free and alternative-base development. Demand for plant-forward options is expanding beyond niche positioning, moving into mainstream commercial applications where operators want a single production format capable of serving mixed customer preferences. Powder formats are particularly well suited to this shift because they enable centralized formulation and simplify inventory management for businesses that must accommodate both traditional dairy and non-dairy orders without maintaining separate liquid supply chains.
These technical improvements are not merely product enhancements; they affect commercial economics. Better performance consistency reduces waste, improves machine compatibility, and enables operators to standardize offerings across multiple locations. For manufacturers, the ability to provide a reliable base that performs similarly across widely used dispensing equipment creates a competitive differentiator that is difficult for smaller or less technically organized competitors to replicate quickly.
Consumer and Operator Behavior Shifts
On the demand side, the market is being shaped by changes in how dessert and beverage programs are designed. Quick-service and value-oriented chains continue to seek dessert attach rates that are easy to store, easy to serve, and predictable in quality. At the same time, specialty parlors and catering environments are pursuing premium sensory differentiation through customized flavor profiles, regional preferences, and improved structure. This dual dynamic pushes manufacturers to serve both ends of the spectrum: high-volume reliability and premium customization.
Catering and event-driven usage also contributes to demand stability. In these settings, powdered formats are valued for their portability, extended shelf life, and ability to support scalable production without the logistical constraints associated with refrigerated liquid mixes. As event caterers and institutional foodservice providers look for ways to simplify menu planning and reduce spoilage risk, powder-based soft serve continues to gain relevance as a practical solution.
Supply-Side Dynamics and Input Availability
Dairy ingredient supply conditions remain central to the market’s operating environment. Spot activity and production data indicate that core inputs such as skim milk powder continue to move in volumes that reflect both domestic processing demand and export-oriented trade. At the same time, pricing for export-grade dairy powders has remained within a range that requires active cost management rather than passive purchasing. Whole milk powder used in frozen dessert bases often carries a related but distinct price profile, which influences how manufacturers construct formulations and where they seek substitution or efficiency.
In parallel, milk pricing signals tied to Grade A and Class III channels indirectly affect the broader dairy input environment relevant to ice cream mixes. Futures indications pointing toward higher interim pricing remind manufacturers that forward contracting, inventory timing, and formulation flexibility are essential tools for managing exposure. Companies that can adjust blending ratios or maintain a diversified ingredient base without sacrificing sensory quality are better positioned to preserve margin stability during periods of input fluctuation.
Cheese Powder Market
Trade and policy frameworks also influence supply availability in specific regions. Export caps and domestic availability provisions can alter the volume of powder moving across borders, particularly for skim milk powder and milk protein concentrates. These arrangements are often designed to support local supply, but they can also affect global pricing and logistics planning for premix producers with international distribution footprints. Businesses operating in multiple markets need to track these changes as part of their sourcing strategy, not merely as external news.
Regulatory and Standards-Driven Quality Expectations
Regulatory expectations and certification practices continue to shape product development and market access. In many commercial arenas, buyers look for documented compliance, consistent safety controls, and recognizable quality credentials. This is especially true for operators scaling across regions or serving institutional clients with strict procurement standards. Manufacturers that maintain strong documentation, standardized production protocols, and adaptable formulation pathways can reduce barriers to expansion and accelerate trust-building with new distribution partners.
Rather than treating compliance as a back-office function, leading companies increasingly view it as a commercial enabler. Clear specifications, repeatable processes, and the ability to provide both hot and cold process options where relevant help manufacturers serve a broader set of commercial applications with fewer friction points. This alignment between technical reliability and commercial usability is becoming a defining factor in winning larger, multi-site contracts.
Competitive Landscape and Strategic Positioning
The competitive field in soft ice cream powder spans established European manufacturers, Asia-based bulk suppliers, and regional specialty producers. The market is not dominated by a single formulation philosophy; instead, it reflects a patchwork of strengths, from premium sensory positioning to cost-efficient scalability and regional ingredient access. This diversity creates both opportunity and pressure, as buyers compare suppliers not only on price but also on texture performance, machine compatibility, and the breadth of flavor or dietary options available.
Several manufacturers stand out for differentiated positioning. Revala has built a profile around premium soft ice cream powders, including dairy-free variants, with an export footprint across more than 60 countries and a focus on creamy texture for HoReCa and industrial use. Its emphasis on unique recipes reflects a strategy rooted in sensory differentiation rather than pure commodity volume. ARO Global positions around reliable quality and global manufacturing and delivery for commercial soft serve and industrial applications, which appeals to buyers prioritizing consistency and supply continuity. Allwin Food Co., Ltd. targets commercial foodservice with a product designed for smooth, flavorful soft serve using water and machines, aligning with operators who need straightforward deployment.
In the premium artisanal segment, PreGel leverages its Italian manufacturing heritage and broad international certifications to serve gelato and soft serve applications with hot and cold process options. This positions the company as a solutions-oriented supplier for operators seeking both craftsmanship and operational flexibility. Rubicone adds scale and longevity to this profile, with a history stretching back to 1959 and exports to more than 75 countries, offering a complete range of ingredients for soft-serve machines. LYKKE complements the EU-focused landscape with worldwide shipping and flexible order sizes, supporting customers who need both smaller trial volumes and larger commercial supply.
PW Consulting
Regional specialists also play an important role. Shandong Bigtree Dreyfus Special Meals Food Co., Ltd. focuses on bulk soft ice cream powder for wholesale commercial use, while Lautan Natural Krimerindo serves dessert shops and foodservice in Indonesia with premix formulations built for rich texture and balanced flavor. PMF (BMF) offers Turkish-manufactured soft ice cream mix powders with dairy and vegan compatibility and alignment with major soft serve machines, which matters in markets where equipment interoperability is a priority. Alaskan Snow Manufacturing emphasizes cost efficiency, shelf stability, and creamy texture relative to liquid mixes, targeting HoReCa and industrial users who value operational predictability. Keliff’s adds export capability from India with multiple flavors and private label options, and AussieBlends serves frozen dessert businesses with powdered mixes tailored for soft serve applications. Luigi’s Gelato supplies a powder base engineered with emulsifiers, stabilizers, and fibers to improve structure and reduce melt-down, while Oleo-Fats focuses on premium soft serve mix quality for consistent commercial results.
The strategic pattern across these companies is not uniform, but it does suggest a market where differentiation is increasingly tied to three dimensions: texture and melt performance, dietary flexibility, and supply reliability. Companies that can combine these attributes with strong documentation and application support are better positioned to win multi-site and cross-border business. Newer entrants and regional suppliers can still compete effectively by serving specific flavor preferences, local ingredient economics, or machine-specific formulations, but broader international expansion usually requires a more comprehensive quality and logistics framework.
Recent commercial activity reinforces the importance of portfolio breadth and continuous catalog refresh. Itaberco’s 2025 catalog release showcased shelf-stable soft serve mixes spanning neutral, vanilla, chocolate, dairy-free, and dairy-alternative options, along with soft serve custard and customization for pastry chefs. This kind of portfolio expansion signals that manufacturers are responding to demand for both variety and application-specific support. ARO Global’s later update underlined its emphasis on global manufacturing and delivery with a message centered on reliable quality for commercial applications. These moves reflect a broader trend: suppliers are investing in making their offerings easier to evaluate, deploy, and scale across varied foodservice environments.
Looking at the structure of the market, concentration remains moderate, with leading players holding meaningful but not overwhelming share. That leaves room for consolidation among regional players, especially where scale, certification readiness, and export capability can be combined. At the same time, fragmentation persists in specialized niches where local taste preferences, machine compatibility, or private label demand create defensible positions. The likely evolution is a dual path: incremental consolidation among suppliers targeting international HoReCa and industrial channels, alongside continued specialization among regional manufacturers serving localized flavor and premix requirements.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, the soft ice cream powder market is likely to be shaped by a combination of formulation maturation, sourcing discipline, and channel expansion. One prominent trend is the continued convergence of sensory performance and dietary flexibility. As more operators seek to serve both dairy and non-dairy customers from a manageable inventory base, demand will grow for powders that deliver comparable texture and stability across different formulation paths. Suppliers that can standardize these outcomes while preserving distinct flavor profiles will have an advantage in multi-concept and multi-region deployments.
A second trend is the growing importance of cost-resilient sourcing strategies. Because dairy inputs remain sensitive to production cycles, export conditions, and domestic availability measures, manufacturers and large buyers will increasingly rely on structured sourcing plans, forward visibility, and formulation flexibility. This does not necessarily mean a move away from dairy-based formats; rather, it suggests that companies will need the ability to adjust blends, manage inventory timing, and respond to regional price divergence without compromising serving quality. In practice, this favors procurement teams and product developers who treat ingredient volatility as a design constraint rather than an occasional disruption.
A third trend is the expansion of powdered soft serve within convenience-oriented and scale-driven foodservice formats. Quick-service environments and catering operations value products that reduce waste, simplify storage, and support rapid service without refrigeration complications. Where flavor variety, machine compatibility, and consistent overrun or texture are achieved, powdered formats can become a preferred choice for growing dessert programs. The opportunity here is not just volume growth, but also product adjacency: operators may pair soft serve powders with complementary frozen dessert components, custard-style offerings, or localized flavor builds that increase menu relevance.
These trends carry both opportunity and risk. On the upside, companies that invest early in dairy-free and low-calorie performance, machine-agnostic reliability, and strong application support are well placed to capture broader usage across commercial channels. On the risk side, unpredictable input pricing, shifting trade provisions, and changing consumer expectations can erode margin assumptions or slow the adoption of premium-priced variants. Businesses that rely on narrow ingredient exposure or single-market sourcing may face more volatility than those with diversified supply and formulation redundancy.
Strategic Actions for Decision-Makers
For Manufacturers and Product Developers
Prioritize formulation versatility and application consistency as core commercial assets. The ability to deliver reliable texture, controlled melt-down, and machine compatibility across dairy, dairy-free, and reduced-sugar formats can expand market access and reduce customer switching risk. Equally important is sourcing architecture: build redundancy for key dairy inputs, maintain forward visibility on price signals, and test formulation flexibility without sacrificing sensory quality.
For Investors and Strategic Acquirers
Evaluate opportunities based on scalable quality systems, export readiness, and portfolio breadth rather than volume alone. Companies with strong documentation, international certifications, and the ability to support both premium and cost-efficient segments are more likely to sustain expansion across multiple foodservice channels. Integration potential is strongest where a supplier can combine regional cost advantages with the operational rigor needed for cross-border distribution.
A practical next step for any stakeholder is to deepen the view beyond headline market size and into the segments, regional cost dynamics, and company-level positioning that determine actual commercial outcomes. Detailed segmentation data, competitive profiling, and scenario-based insight can sharpen planning for sourcing, product roadmap decisions, and market entry. In that context, the full research report provides the granularity needed to move from directional confidence to specific execution planning.
Soft Ice Cream Machines Market
For detailed analysis of this topic, please visit the official page: Worldwide Soft Ice Cream Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Oxacillin Market at 3.55% CAGR: The Regional & Formulation Shifts Reshaping Strategy
By pmarketresearch, 2026-09-18
Worldwide Oxacillin Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The global oxacillin market has demonstrated steady growth over the past five years, expanding from approximately $378.12 million in 2020 to an estimated $450 million in 2025. Looking ahead, the market is projected to reach roughly $492.72 million by 2026 and continue its upward trajectory through 2032, with a compound annual growth rate of 3.55%. This growth trajectory reflects a mature but resilient pharmaceutical segment, driven by sustained demand for anti-infective therapies and the ongoing need for targeted treatment options against penicillinase-producing staphylococcal infections.
Despite the positive growth outlook, the oxacillin market faces several structural challenges that warrant careful strategic consideration. First, the market exhibits significant concentration, with the top three players capturing an estimated 52.4% of total revenue and the top five controlling approximately 78.1%. This concentration creates both competitive barriers and supply chain vulnerabilities, particularly when key manufacturers experience production disruptions. Second, the market is heavily weighted toward injectable formulations, which account for the substantial majority of revenue compared to oral capsules. This formulation imbalance creates specific regulatory, manufacturing, and distribution challenges that differ markedly from oral solid dosage markets. Third, the end-user landscape remains dominated by hospital settings, which concentrate procurement decisions and create dependency on institutional purchasing cycles and formulary management processes.
A critical inflection point has emerged around supply chain stability. Recent data indicates that oxacillin injection products have experienced notable supply disruptions, with manufacturing delays reported by several prominent suppliers. These disruptions are not isolated incidents but reflect broader vulnerabilities in the specialized API manufacturing ecosystem, where a limited number of qualified producers serve global demand. For market participants, this environment demands proactive supply chain risk management rather than reactive procurement strategies.
Additionally, the regulatory landscape continues to evolve. The absence of active originator patents for oxacillin creates an open generic market with multiple abbreviated new drug application approvals, which theoretically encourages competition but also intensifies price pressure on manufacturers. Simultaneously, regulatory bodies have introduced updated susceptibility testing interpretive criteria and labeling requirements that affect how oxacillin products are positioned, prescribed, and monitored. These regulatory dynamics create both compliance costs and opportunities for manufacturers who can navigate evolving standards efficiently.
Key Drivers Shaping Market Dynamics
Technological Innovation and Manufacturing Advances
The oxacillin market benefits from ongoing advancements in sterile manufacturing processes and quality control technologies. Injection formulations require stringent sterility assurance and specialized production capabilities, creating natural barriers to entry that favor established manufacturers with robust quality systems. Recent regulatory actions, including updated package inserts and prescribing information published in early 2026, reflect heightened attention to product quality documentation and labeling accuracy. Manufacturers that invest in modern sterile processing technologies and comprehensive quality management systems are better positioned to meet these standards while maintaining production efficiency.
The technology landscape also extends to formulation optimization. While injectable forms dominate current market revenue, developments in manufacturing precision and stability enhancement create opportunities for improved product consistency. Companies producing oxacillin sodium API and finished dosage forms increasingly leverage process analytical technologies and continuous manufacturing principles to reduce batch variability and improve supply reliability. These investments, while requiring upfront capital, contribute to long-term competitive differentiation through reduced deviation rates and more predictable production schedules.
Regulatory Environment and Standards Evolution
Regulatory dynamics fundamentally shape market participation strategies. The FDA has maintained active engagement with oxacillin product standards, with recent developments including the approval of previously withdrawn new drug applications for injectable formulations and the inclusion of oxacillin sodium in approved drug product listings for 2026. These regulatory milestones signal continued official recognition of oxacillin as an active therapeutic option while reinforcing compliance expectations for market participants.
A particularly important regulatory development involves susceptibility testing standards. Regulatory authorities have concurred with revised interpretive criteria for oxacillin testing against Staphylococcus species, with cefoxitin serving as a surrogate in certain testing contexts. This evolution affects how clinical laboratories assess antibiotic susceptibility and influences prescribing patterns. Manufacturers and supply chain participants who understand these testing framework changes can better anticipate demand shifts and align product positioning with clinical practice realities. The fact that oxacillin remains indicated specifically for infections caused by penicillinase-producing staphylococci demonstrated to be susceptible to the drug creates a well-defined clinical niche that distinguishes it from broader-spectrum alternatives.
Demand-Side Shifts and Clinical Practice Patterns
Hospital and clinic demand for oxacillin reflects broader trends in anti-infective utilization. Healthcare institutions increasingly focus on antimicrobial stewardship programs that emphasize appropriate antibiotic selection, dosing optimization, and resistance management. Within this framework, oxacillin occupies a specific therapeutic role for susceptible staphylococcal infections, differentiating it from broader-spectrum agents that may face greater stewardship scrutiny or contribute more substantially to resistance pressure. This clinical positioning supports sustained demand from institutional buyers who prioritize targeted therapy options within their formulary management strategies.
The end-user mix, with hospitals representing the dominant consumer segment, means that procurement decisions are influenced by institutional purchasing consortia, group purchasing organizations, and clinical guideline updates. This centralized purchasing environment rewards manufacturers who can demonstrate reliable supply, consistent quality, and competitive pricing structures. Clinics and retail pharmacy channels represent smaller but potentially growing segments, particularly as outpatient infusion services expand and community-based treatment options evolve.
Supply Chain Restructuring and Cost Dynamics
Supply chain considerations have become increasingly central to market strategy. Raw material availability and API production capacity represent critical constraints, with disruptions linked to supply issues affecting major producers. These challenges highlight the concentration risk inherent in specialized antibiotic manufacturing, where a limited number of qualified API producers and formulation facilities serve global demand pools. For manufacturers and distributors, this environment demands diversified sourcing strategies, strategic inventory management, and stronger supplier relationships to mitigate the impact of production interruptions.
Cephalosporin Market
Cost structures in the oxacillin market reflect the economics of generic antibiotic production, where price competition is intense and margin preservation depends on operational efficiency. Manufacturers based in India and China, alongside European and North American producers, compete across different value chain segments, from bulk API production to finished dosage form supply. Geographic diversification of manufacturing capabilities can provide competitive advantages through access to different cost structures, regulatory pathways, and customer bases. However, maintaining consistent quality across multiple production sites requires robust quality oversight and regulatory compliance infrastructure.
Worldwide Penicillin Market
Competitive Landscape and Leading Strategies
Market Structure and Key Participants
The global oxacillin market features a diverse set of participants spanning multiple geographies and business models. European manufacturers such as ACS Dobfar SPA contribute significant production capacity for oxacillin sodium API and sterile injectable forms, leveraging established partnerships to serve international markets including the United States. Centrient Pharmaceuticals maintains an active role in oxacillin sodium API production with an emphasis on high-quality penicillin-class antibiotics for worldwide distribution. These European participants bring established regulatory compliance records and quality manufacturing reputations that support their market positions.
Indian manufacturers represent a substantial presence in the market, with companies including Aurobindo Pharma Limited, Akums Lifesciences, SiNi Pharma, and Wellona Pharma offering oxacillin sodium API and finished dosage forms across various market channels. Aurobindo's extensive anti-infectives portfolio provides a broad commercial platform for oxacillin products, while specialized manufacturers like Akums focus on contract manufacturing arrangements that supply international markets. SiNi Pharma and Wellona Pharma concentrate on oxacillin injection finished dosage forms with export-oriented strategies, reflecting the importance of injectable formulations in global demand patterns. Bioquim in Spain and Reyoung Pharmaceutical Co., Ltd. in China add further geographic diversity, with Bioquim emphasizing GMP manufacturing for global pharmaceutical clients and Reyoung producing oxacillin in various forms including solid preparations and injectables with an export focus.
In North America, Baxter Healthcare Corporation and Sagent Pharmaceuticals serve the domestic market with oxacillin sodium for injection products. Baxter markets oxacillin sodium in plastic containers for intravenous use in treating susceptible staphylococcal infections, leveraging established healthcare distribution relationships and brand recognition in the US clinical environment. Sagent Pharmaceuticals supplies oxacillin injection products within the US market, contributing to domestic availability alongside other manufacturers.
Strategic Positioning and Differentiation Approaches
Leading market participants pursue distinct strategic positioning approaches. Some manufacturers emphasize vertical integration, controlling both API production and finished dosage form manufacturing to capture value across the supply chain and reduce dependency on external suppliers. This integration can improve margin structure and supply reliability but requires significant capital investment and regulatory compliance capability across multiple production stages. Other participants focus on specialized niches, such as contract manufacturing for international clients or specific formulation types, allowing them to serve particular market segments without the overhead of full product portfolios.
Quality reputation and regulatory compliance record represent important differentiators in a market where sterility assurance and product consistency are paramount. Manufacturers with demonstrated track records of regulatory adherence and quality system robustness can command preferential positioning with institutional buyers who prioritize supply reliability. The recent regulatory developments around labeling updates and approved drug product listings reinforce the importance of maintaining current compliance status, as products with outdated documentation or regulatory gaps face market access risks.
Price competitiveness remains a fundamental consideration given the generic nature of the market and multiple approved applications. However, in an environment marked by supply disruptions and manufacturing challenges, buyers increasingly value supply reliability alongside price. Manufacturers who can demonstrate consistent availability and proactive communication about supply status may earn stronger buyer relationships and more stable procurement commitments, even if their pricing is not always the lowest in the market.
PW Consulting
Evolving Competitive Dynamics
The competitive landscape shows indicators of both consolidation pressure and market fragmentation. High market concentration among the top participants suggests established players hold meaningful advantages in scale, customer relationships, and regulatory infrastructure. However, the presence of numerous manufacturers across multiple geographies, particularly in India and China, indicates opportunities for continued market entry and niche positioning. The lack of active originator patents removes traditional barriers to market entry, allowing new ANDA holders and contract manufacturers to participate in the market.
A trend toward supply chain regionalization may influence competitive dynamics going forward. As healthcare systems and procurement organizations seek to reduce dependency on single-source or distant suppliers, manufacturers with geographically diversified production capabilities or local market presence may gain competitive advantage. This dynamic could create opportunities for contract manufacturers who can provide flexible production capacity and responsive supply to meet shifting procurement preferences. Additionally, the evolving regulatory environment around susceptibility testing and product labeling may create opportunities for manufacturers who can proactively adapt their product information and clinical positioning to align with updated standards.
Future Trends and Outlook Through 2032
Trend 1: Supply Chain Resilience as a Competitive Imperative
Supply chain stability is poised to become an increasingly critical competitive factor over the next three to five years. The documented supply disruptions affecting major producers highlight vulnerabilities that procurement organizations and healthcare systems are likely to address more systematically. This trend creates opportunities for manufacturers who can invest in reliable production capacity, diversified sourcing, and transparent communication about supply status. Companies that build reputation for supply dependability may capture disproportionate share during periods of market tightness and establish stronger long-term buyer relationships. Conversely, participants who cannot address supply reliability concerns may face erosion of market position even if their cost structures remain competitive.
Strategic inventory management and multi-source procurement strategies will likely gain prominence among institutional buyers. This shift benefits manufacturers who can offer flexible supply arrangements, safety stock options, and contingency planning support. The trend also favors vertically integrated players who control more of their supply chain and can respond more nimbly to production challenges than those dependent on external API or component suppliers.
Trend 2: Regulatory Complexity and Quality Differentiation
The regulatory environment is expected to maintain its emphasis on product quality, labeling accuracy, and testing standard alignment. Recent regulatory actions suggest ongoing scrutiny of antibiotic product documentation and compliance status. Manufacturers who proactively maintain current regulatory filings, updated prescribing information, and alignment with susceptibility testing standards will be better positioned to navigate this environment. Quality differentiation may become more valued as healthcare institutions strengthen their vendor qualification processes and emphasize supply chain quality assurance in procurement decisions.
The indication specificity of oxacillin for penicillinase-producing staphylococci with demonstrated susceptibility creates a relatively stable clinical positioning that is less susceptible to displacement by broader-spectrum alternatives. However, evolving antimicrobial stewardship priorities and resistance patterns warrant ongoing monitoring, as shifts in clinical guidelines could affect demand patterns over the forecast period. Manufacturers who invest in understanding clinical practice trends and maintain alignment with stewardship program priorities may better anticipate demand shifts.
Trend 3: Geographic Expansion and Market Diversification
Geographic market dynamics are likely to evolve as healthcare access expands in emerging markets and existing markets mature. The current regional distribution of market revenue reflects established healthcare infrastructure in North America and Europe alongside growing demand in Asia Pacific and other regions. Over the forecast period, varying healthcare investment patterns, regulatory harmonization efforts, and local manufacturing development may create opportunities in specific geographies. Manufacturers with export capabilities and experience navigating diverse regulatory environments may find growing opportunities as demand expands in developing markets.
Portfolio diversification strategies also merit attention. While injectable formulations currently dominate market revenue, the oral capsule segment represents a smaller but potentially complementary product line. Understanding demand patterns across formulations and end-user channels can inform product development and commercialization strategies. Markets that balance multiple formulations and end-user segments may achieve greater revenue stability than those heavily dependent on a single formulation or channel.
Potential risks to the outlook include continued supply chain volatility, regulatory changes that could affect product positioning or compliance requirements, and broader market dynamics affecting generic antibiotic pricing pressure. Economic factors influencing healthcare budgets and procurement capacity could also impact market growth rates. Participants should maintain scenario awareness around these variables and develop contingency strategies accordingly.
Strategic Recommendations for Decision-Makers
For manufacturers operating in or considering entry to the oxacillin market, prioritizing supply chain resilience and quality documentation should feature prominently in strategic planning. Investments in production reliability, diversified sourcing, and robust quality management systems offer competitive advantages that extend beyond price considerations. Manufacturers should also maintain current regulatory compliance status across all product files and labeling, monitoring regulatory developments that affect susceptibility testing standards, prescribing information, and approved product listings. Building flexible manufacturing capacity that can respond to demand fluctuations and supply disruptions adds valuable optionality in a market with documented production challenges.
For investors evaluating opportunities in the anti-infective sector, the oxacillin market presents a mature but strategically interesting segment characterized by steady growth, established clinical positioning, and supply chain dynamics that create differentiation opportunities. Due diligence should examine participant quality systems, regulatory compliance records, supply chain dependencies, and geographic market exposure. Understanding the concentration of manufacturing capacity and the specific capabilities of key suppliers can inform assessments of market sustainability and competitive positioning. Investors should also monitor regulatory developments that could affect market access or product requirements.
For procurement organizations and healthcare systems sourcing oxacillin products, diversifying supply sources and developing contingency plans for product availability should be priorities given documented supply disruption patterns. Evaluating suppliers on criteria that include quality system robustness, regulatory compliance status, and supply reliability communication, alongside price, can support more resilient procurement strategies. Engaging with manufacturers who demonstrate proactive supply management and transparent communication about production status may reduce procurement risk during periods of market tightness. Staying informed about regulatory updates and susceptibility testing standards helps ensure procurement decisions align with current clinical practice requirements.
Timely access to detailed market intelligence, including granular segmentation data, competitive profiles, and regulatory tracking, supports more informed strategic decisions across these stakeholder groups. Comprehensive analysis that combines market sizing, competitive dynamics, regulatory developments, and demand-side trends provides a fuller picture than any single data source alone.
This analysis draws on market data and industry intelligence current through early 2026. For detailed segmentation data, competitive profiling, and customized strategic recommendations specific to your market position and objectives, PW Consulting offers comprehensive oxacillin market research services. Contact our team to discuss tailored intelligence solutions that address your specific strategic questions.
For detailed analysis of this topic, please visit the official page: Worldwide Oxacillin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
How Asia Pacific Dominates the Global MPP Films Market's 5.72% CAGR Path
By pmarketresearch, 2026-09-18
Navigating Strategic Shifts in the Global Metallised Polypropylene Films Market
Market Status and Core Challenges
The global metallised polypropylene films (MPP films) market has transitioned into a phase of steady expansion, underpinned by consistent demand across electrical, packaging, and industrial applications. Revenue grew from approximately $2.75 billion in 2020 to around $3.65 billion by 2025, with a compound annual growth rate of 5.72 percent projected through 2032. This trajectory reflects a market that has successfully navigated recent macroeconomic turbulence while maintaining structural momentum. The expansion is not uniform across all pathways, however, as growth is increasingly shaped by how different industrial sectors absorb cost pressures, adapt to regulatory expectations, and integrate newer manufacturing technologies.
Polypropylene Pp Synthetic Paper Market
Understanding the market today requires acknowledging that scale alone no longer guarantees advantage. The industry operates with a moderately concentrated structure, where a handful of established players command significant share, yet regional manufacturing footprints and application-specific expertise create meaningful differentiation. This concentration presents both stability and vulnerability: established supply relationships and brand recognition provide resilience, but they also raise the bar for new entrants seeking to compete on price or performance alone. At the same time, the market’s breadth spans highly technical capacitor-grade films and broader packaging-grade variants, meaning that competitive positioning depends heavily on which segment a manufacturer prioritizes and how well it aligns with downstream demand patterns.
MCPP Film for Packaging Market
Several converging challenges define the current inflection point. First, raw material volatility has become a persistent operational reality. Polypropylene feedstock pricing has exhibited sharp regional swings, with certain markets experiencing double-digit year-over-year increases driven by tighter supply conditions and fluctuating monomer costs. These movements compress margins for film producers who cannot easily pass costs downstream, particularly in price-sensitive packaging applications. Second, the gap between high-performance technical films and commodity packaging films is widening in terms of required investment. Manufacturers pursuing capacitor-grade or specialized industrial films face higher qualification standards, tighter tolerances, and longer customer validation cycles, while those focused on packaging must contend with intensifying competition from alternative barrier materials and converter-level integration. Third, regulatory and sustainability expectations are reshaping procurement criteria across end-use sectors. Electrical and automotive buyers increasingly prioritize components that support energy efficiency, thermal durability, and extended service life, while food and beverage packaging customers face mounting pressure to balance barrier performance with recyclability and reduced material complexity. These forces are not isolated; they interact to create a market where strategic clarity matters more than ever.
For executives and investors, the core question is no longer whether the market will grow, but where value will accrue as these challenges reshape cost structures, qualification pathways, and competitive dynamics. The companies that navigate this environment most effectively will be those that treat raw material exposure, application specialization, and regulatory alignment as integrated strategic variables rather than separate operational concerns.
Key Drivers of Market Change
The trajectory of the MPP films market is being shaped by a combination of technological advancement, regulatory pressure, demand-side evolution, and shifting supply chain economics. Each driver reinforces the others in ways that create both operational challenges and structural opportunities for well-positioned players.
Innovation in film architecture and metallisation techniques continues to raise the performance ceiling for both capacitor-grade and packaging-grade applications. Advances in vacuum deposition control, layer uniformity, and precision etching have improved dielectric consistency, insulation resistance, and breakdown voltage characteristics, enabling films to meet increasingly demanding specifications in power electronics, lighting, and motor control systems. In packaging, higher barrier uniformity and tighter thickness control support longer shelf life and reduce the need for multi-layer laminates, which appeals to brands seeking simpler material streams. These technical gains are not merely incremental; they expand the addressable use cases for MPP films into applications where alternatives previously held an advantage. The result is a market where performance differentiation is becoming a more reliable route to pricing power than volume alone.
Policy and regulatory environments are exerting a comparable influence, particularly in regions where energy efficiency standards, automotive qualification requirements, and packaging sustainability mandates are tightening in tandem. In the electrical and automotive sectors, stricter qualification frameworks and thermal durability expectations are filtering out lower-specification materials, favouring suppliers that can demonstrate consistent performance under elevated temperatures and prolonged electrical stress. At the same time, packaging regulations that encourage reduced waste, improved recyclability, and lower carbon intensity are pushing converters and brand owners to re-evaluate film choices. When MPP films can deliver required barrier properties with fewer composite layers or support closed-loop packaging design, they gain relevance in tenders and specification updates. Regulatory pressure therefore acts as a filter, rewarding manufacturers that can align product attributes with evolving compliance and procurement criteria.
Demand-side behaviour is shifting in ways that reinforce these technical and regulatory trends. In consumer electronics and automotive electrification, the push toward higher power density, smaller form factors, and more robust energy conversion systems is increasing reliance on reliable dielectric films that can operate reliably in challenging thermal and electrical environments. Renewable energy infrastructure and industrial power utilities are also expanding their requirement for capacitors and insulation materials that support grid stability and long-duration performance. On the packaging side, brand owners are balancing consumer expectations for convenience and shelf life with corporate sustainability commitments, creating demand for films that combine barrier functionality with material efficiency. These demand shifts are not uniform across regions or sectors, but they share a common direction: buyers are placing greater weight on reliability, efficiency, and material optimisation, and they are willing to qualify suppliers that can demonstrate those attributes credibly.
Supply chain and cost structure dynamics complete the picture. Feedstock pricing has become more regionally divergent, with some markets experiencing sharp upward movements while others see more moderate or even temporarily softening trends. These differences influence where production is competitive, how inventory is managed, and which customers face the greatest pressure to absorb cost increases. Manufacturers with integrated operations, flexible sourcing strategies, or the ability to pass through value-based pricing in high-specification applications are better positioned to manage this volatility. Conversely, companies dependent on single-region feedstock or heavily exposed to commodity packaging margins face a more difficult path. In this environment, cost management is increasingly tied to strategic decisions about product mix, geographic footprint, and customer segmentation rather than simple procurement optimization.
Taken together, these drivers suggest a market in which advantage is increasingly defined by the ability to combine technical credibility, regulatory alignment, and resilient cost positioning. Suppliers that treat these elements as interconnected are more likely to capture premium demand and sustain margins through cycles of raw material fluctuation and specification tightening.
Competitive Landscape and Leading Strategies
The competitive landscape in MPP films reflects a blend of regional manufacturing strength, application specialization, and varying degrees of vertical integration. Rather than competing on a single dimension, leading companies are building advantage through focused positioning, whether that means deep expertise in capacitor-grade dielectrics, scale in packaging-grade barrier films, or the ability to serve both high-performance and broader commercial applications with differentiated product lines.
In the capacitor and industrial electronics space, several manufacturers have established strong reputations by concentrating on metallised film quality, electrical consistency, and qualification support. Companies such as Cosmo Films, Anhui Saifu, Nantong Jiangsen Electronic Technology, Steiner Film GmbH, and Anhui Tongfeng Electronics illustrate different models within this segment. Some emphasise broad capacitor-grade portfolios that span lighting, motor run/start, and industrial power applications, while others focus on integrated production that links film manufacturing directly to capacitor assembly or specific bidirectional film outputs. This specialization allows them to respond to technical procurement requirements more effectively, offering variants such as aluminium-zinc, pure aluminium, and slope or RMF configurations that address insulation resistance and breakdown voltage needs. Their strategic value lies in reducing qualification friction for buyers who require predictable dielectric behaviour and documented performance under demanding conditions.
In packaging and broader industrial applications, a different set of players competes on barrier performance, capacity scale, and converter-oriented service. Jindal Films, Toray Plastics, Flex Films, Vibac, and Dunmore each bring distinct strengths, from vacuum-deposited aluminium barrier films designed for long-shelf-life food and beverage products to high-capacity BOPP portfolios and technical metallised substrates for diverse industrial uses. Their differentiation often centres on uniformity, coating and metallising control, and the ability to supply consistent material to downstream converters who require dependable runnability and barrier reliability. In this part of the market, scale and process reliability are critical, but so is the capacity to adapt film specifications to changing packaging architectures and brand-owner requirements.
The recent product activity from major component manufacturers further underscores how competitive advantage is increasingly tied to specification leadership. In 2025, Vishay Intertechnology introduced an AEC-Q200 qualified DC-link metallised polypropylene film capacitor rated for operation up to 125°C with enhanced robustness, targeting automotive, energy, and industrial use. Around the same period, TDK Corporation launched compact double-sided metallised polypropylene film capacitors suited for resonant topologies, and later updated technical specifications for additional series with detailed application and performance data. These moves highlight a broader dynamic: upstream film producers benefit when downstream component makers invest in higher-temperature, higher-voltage, and more tightly qualified solutions, because such products raise the performance baseline and expand demand for consistent, high-specification dielectric films.
Market concentration remains moderate, with the largest players holding meaningful but not dominant share. This structure leaves room for both consolidation and continued differentiation. Consolidation is likely where scale, feedstock access, or geographic reach can strengthen cost resilience, while fragmentation may persist where application-specific know-how, local qualification relationships, or specialised metallisation capabilities create defensible niches. New entrants face a challenging path unless they bring a clear technical or cost advantage, but regional expansion and targeted product launches remain viable strategies for established players seeking to deepen their footprint in high-growth demand areas. The overarching trend is toward a landscape where strategic positioning is defined less by total volume than by the ability to align product performance, qualification support, and supply reliability with the most valuable end-use segments.
Future Trends and Commercial Opportunities
Looking ahead three to five years, the MPP films market is likely to be defined by three interrelated trends. The first is the continued elevation of performance requirements in electrical and automotive applications. As power electronics become denser, operating temperatures rise, and qualification standards tighten, demand for capacitor-grade and DC-link films with proven thermal and electrical durability will expand. This creates opportunity for suppliers that can document high-temperature behaviour, long-term stability, and application-specific performance, particularly where downstream component makers are investing in qualified solutions for electrification and energy infrastructure.
The second trend is a gradual re-weighting of packaging demand toward material efficiency and simpler material streams. Brand owners and converters are under pressure to reduce multi-material complexity while preserving barrier performance and shelf life. Films that can deliver reliable moisture and gas barrier properties with fewer layers, or that integrate well into recycling-oriented design goals, are likely to gain preference in specification updates. This shift favours manufacturers that can balance metallised barrier consistency with flexible formatting and converter-friendly processing, especially in segments where shelf-life requirements remain stringent.
The third trend is regional cost divergence becoming a more persistent strategic variable. Because feedstock and monomer costs are moving differently across geographies, competitive positioning will increasingly depend on where capacity is located, how sourcing is managed, and which customer segments can absorb price movement through value-based differentiation. Manufacturers with diversified geographic exposure or the ability to shift product mix toward higher-specification, less price-elastic applications will be better insulated from regional volatility. At the same time, buyers in sensitive segments will continue to seek supply partners who offer predictable pricing frameworks and resilient availability.
These trends point to clear commercial opportunities, but they also carry risk. Overexposure to commodity packaging margins in a volatile cost environment can erode profitability, while over-concentration in a single application may leave a company vulnerable if qualification cycles lengthen or competing materials improve. There is also uncertainty around how quickly sustainability mandates translate into material substitution in packaging, and whether new capacitor technologies or alternative dielectrics eventually pressure certain MPP use cases. The most resilient strategies will be those that treat these uncertainties as inputs to portfolio design rather than as reasons to defer investment.
Strategic Recommendations for Decision-Makers
Manufacturers should use the current environment to sharpen product mix strategy. Prioritising segments where performance, qualification, and reliability command pricing power can reduce exposure to commodity margin pressure, while targeted investment in metallisation precision and high-temperature film consistency can strengthen position in electrical and automotive demand pools. Supply chain flexibility, including diversified feedstock sourcing and geographic balancing, remains essential to managing regional cost volatility without sacrificing service reliability.
PW Consulting
Investors should evaluate opportunities based on company positioning within application-specific value chains rather than headline scale alone. Assets and businesses that serve qualified capacitor, power electronics, or higher-barrier packaging applications are more likely to capture durable demand than undifferentiated commodity producers. It is equally important to assess whether a target’s cost structure and geographic footprint can withstand continued raw material divergence, and whether its product roadmap aligns with tightening qualification and sustainability expectations.
Procurement and supply chain leaders should treat film sourcing as a strategic specification decision, not just a cost exercise. Mapping suppliers by technical capability, qualification support, and regional cost resilience can improve both performance security and long-term pricing stability. Building multi-supplier strategies for critical applications, while consolidating volume where a single supplier offers clear technical or service advantage, can help balance risk and efficiency.
For organisations seeking a deeper view of segment-level demand patterns, regional dynamics, and company-specific positioning, the full PW Consulting market analysis provides a more granular foundation for planning. The complete report expands on the trends outlined here with detailed segmentation data, competitive profiles, and scenario-based insight designed to support investment, sourcing, and product strategy decisions across the MPP films value chain.
For detailed analysis of this topic, please visit the official page: Worldwide Metallised Polypropylene Films (MPP Films) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Flow Battery Factory solutions can support long duration energy storage by combining scalable system architecture, liquid electrolyte storage, modular power conversion, and project specific configuration. As renewable generation becomes more variable, energy storage needs to handle different operating periods rather than focusing only on short discharge cycles. The United States Department of Energy identifies flow based electrochemical systems as an important long duration storage pathway because their energy capacity and power capability can be configured with greater independence.
One important consideration is the relationship between energy capacity and power output. In a conventional design, increasing stored energy may require changes throughout the entire unit. In a redox based system, larger electrolyte tanks can increase available energy while the electrochemical stack is selected according to the required power level. This separation can give project developers more flexibility when planning installations for renewable generation, commercial facilities, microgrids, and other applications.
For a manufacturer, this flexibility creates several areas where engineering experience matters. Tank volume, electrolyte concentration, stack configuration, pump selection, piping, valves, sensors, control systems, and thermal conditions all influence the overall system. A suitable design needs to consider how these elements work together instead of treating each component as an independent part.
Long duration applications also place attention on operating stability. Energy storage may need to charge during periods of available renewable generation and discharge when electricity demand increases or generation decreases. A properly configured system can therefore support time shifting across several hours and may also be considered for extended backup requirements. DOE materials describe the ability to separate power and energy capacity as an important characteristic of this technology.
Another factor is scalability. Energy projects can vary considerably in required capacity, available installation space, operating environment, and expected usage pattern. A modular architecture allows engineers to consider these variables during project planning. For example, a commercial site may have different requirements from a renewable energy installation connected to a larger grid. The appropriate configuration should reflect actual load profiles, charging conditions, discharge periods, and space limitations.
Monitoring and control are also important parts of a complete energy storage solution. Sensors can help track parameters such as electrolyte condition, temperature, pressure, flow rate, state of charge, and system status. Control software can coordinate pumps, power conversion equipment, protection functions, and operating schedules. DOE research has also identified real time analysis and monitoring as areas that require continued development for these systems.
Material selection deserves careful attention as well. Electrolytes, membranes, seals, pipes, tanks, electrodes, and other components need to work together under the intended chemical and operating conditions. Manufacturing consistency can influence assembly quality and long term system operation. This is why buyers often look beyond a basic specification sheet and ask about production processes, inspection procedures, testing methods, and technical support.
ERG focuses on energy storage solutions designed around practical project requirements. From system configuration to component selection and production coordination, the goal is to help customers develop storage equipment that matches their application conditions. Different projects can require different energy capacities, power ratings, installation arrangements, and control strategies, so communication during the planning stage is an important part of the process.
Long duration storage is also closely connected with renewable energy integration. Solar and wind generation do not always match electricity demand, creating situations where available electricity needs to be stored for later use. A suitable storage system can help shift energy from one period to another and provide additional flexibility for grid connected or distributed applications. DOE categorizes long duration storage across several time ranges and identifies electrochemical technologies among the options being developed for extended duration applications.
For buyers evaluating a supplier, several questions can make the selection process clearer. What capacity range can the manufacturer support? How are system components tested? Can the configuration be adapted to project conditions? What monitoring functions are included? How is technical support handled during installation and operation? Asking these questions can help create a clearer understanding of whether a proposed solution matches the intended application.
The development of long duration energy storage continues to involve improvements in materials, manufacturing processes, system integration, and cost management. The Department of Energy has specifically identified manufacturing at scale and new electrolyte development among areas that can contribute to the future development of this technology.
For project developers looking for a practical starting point, ERG provides product and solution information covering energy storage applications and related equipment. You can review the available options and discuss project requirements through https://www.ergenergy.net/product/ to see which configuration may fit your intended application and operating conditions.
Worldwide Hot Tapping Machines Market: The Real Drivers Behind 4.7% CAGR Growth
By pmarketresearch, 2026-09-18
Hot Tapping Machines Market: Strategic Trends, Commercial Opportunities, and the Path Forward
The global hot tapping machines market has settled into a steady growth trajectory, anchored by recurring pipeline intervention needs across energy and industrial sectors. Valued at approximately USD 679.66 million in 2025, the market expanded from around USD 540.21 million in 2020 and is projected to reach roughly USD 937.39 million by 2032, translating to a compound annual growth rate of about 4.7%. This pace reflects a sector that is neither in a speculative boom nor in contraction, but rather in a mature, reliability-driven expansion where incremental gains are earned through operational resilience, compliance, and targeted innovation. The growth is broad-based, spanning multiple product types and application verticals, yet underlying segments show distinct velocity and margin profiles that shape where value is created. A glance at the revenue mix clarifies the competitive battlefield: hydraulic machines command the largest revenue pool, followed by pneumatic systems, with manual and electric variants occupying niche but strategically important positions. Application demand is similarly distributed, with oil and gas pipelines representing the most substantial revenue contributor, while water and wastewater treatment, chemical and industrial processing, and power generation plants collectively sustain a diversified demand base.
Framing the market solely by size, however, obscures the operational realities that determine winners and laggards. The sector is navigating a series of inflection points that test supply resilience, technical sophistication, and commercial agility. First, demand is increasingly defined by in-service continuity. Utilities, energy operators, and industrial plants are reluctant to accept full shutdowns for routine maintenance, branch connections, or emergency repairs, which elevates the strategic importance of equipment that can operate safely under pressure and varying flow conditions. Second, the cost of downtime has become a dominant economic variable. In tightly coupled supply chains and constrained labor markets, a single unplanned outage can cascade into production losses, contract penalties, and reputational damage. Third, regulatory and standards expectations continue to raise the technical bar. Operators and contractors must align procedures with widely referenced safety and design guidelines, which increases the importance of documented process control, material integrity, and operator training. Fourth, raw material specifications matter more than ever. Equipment constructed from pressure vessel–grade materials, with impact toughness at sub-zero temperatures and resistance to sulfide stress cracking, is increasingly favored in demanding service environments. These dynamics are reshaping procurement criteria, pricing power, and service expectations across the value chain.
For executives and investors, the practical implication is that market growth is not a simple function of new capital deployment. The most actionable opportunities lie in reducing total cost of intervention, improving uptime assurance, and aligning product capabilities with evolving compliance expectations. Companies that can demonstrate repeatable performance in live systems, shorten mobilization time, and support diverse pipe materials and pressure classes are better positioned to capture share in a fragmented but increasingly demanding market.
Key Drivers Reshaping the Hot Tapping Machines Market
Technical Capability as the New Differentiator
Innovation in hot tapping is moving beyond mechanical capacity toward integrated performance. The industry is seeing a push toward machines that handle a wider range of pipe diameters, wall thicknesses, and operating pressures without compromising alignment, seal integrity, or cut quality. Proprietary cutter and drive designs, double block and bleed sealing arrangements, and purpose-built accessories are increasingly central to competitive positioning. High-pressure capability is particularly significant in complex service environments, where operators require equipment that can tolerate sour gas conditions, subsea or offshore constraints, and challenging metallurgical profiles. In parallel, there is growing interest in systems that simplify setup and reduce operator dependence, enabling faster mobilization and more consistent outcomes in the field. These capabilities matter because they directly influence whether a contractor can accept a job, how long it takes to complete, and how much risk is transferred back to the asset owner.
Tamping Machine Market
The practical effect is a shift in purchasing logic. Buyers are less focused on unit price alone and more attentive to total intervention cost, including preparation time, tooling availability, spare parts access, and post-operation support. Manufacturers that can package equipment with clear operating envelopes, robust material specifications, and documented procedure support are gaining credibility in segments where failure tolerance is low. This is especially visible in applications where pipelines remain in service during branch connections or line stops, since even minor deviations can create operational or safety exposure.
Regulatory Expectations and Standards Alignment
Standards and guidance documents continue to shape both procurement and field practice. Widely referenced safety and design frameworks provide structured expectations for welding and hot tapping on equipment in service, while pressure equipment and pipeline design codes influence the technical envelope within which machines must operate. Compliance is not merely a procedural formality; it affects liability, insurability, and contractor qualification. As a result, suppliers that can demonstrate alignment with recognized engineering expectations and provide documentation that supports safe execution are better positioned to win work in regulated markets.
This regulatory backdrop also influences product design. Equipment intended for demanding service environments increasingly requires materials and fabrication practices that address sub-zero impact toughness, corrosion resistance, and resistance to sulfide stress cracking. These requirements elevate the importance of supply chain control, quality assurance, and traceability. For operators, the implication is that machine selection is increasingly a risk management decision. For manufacturers, it creates a premium on consistency, certification readiness, and transparent documentation.
Demand-Side Shifts Toward Continuity and Resilience
A structural change in operator behavior is reinforcing demand for in-service connection and repair solutions. Many organizations are prioritizing continuity over the simplicity of a shutdown, particularly where interruptions would disrupt downstream operations, customer commitments, or critical infrastructure services. This shift is visible across multiple verticals, including water distribution, industrial processing, and energy transport. In water systems, for example, there is sustained interest in under-pressure connection methods that allow branch installation without service interruption. In industrial and energy contexts, the emphasis is on minimizing exposure to process upsets while maintaining throughput.
This demand pattern changes the commercial equation. It rewards equipment that is versatile across pipe materials such as steel, copper, brass, and aluminum, and across pressure classes. It also favors suppliers who can support both planned maintenance and urgent response scenarios. From a market perspective, this broadens the addressable opportunity beyond large-scale energy projects into municipal, industrial, and distributed infrastructure work, where frequency of intervention may be higher even if individual project sizes are smaller.
Supply Chain, Cost Structure, and Manufacturing Concentration
Cost dynamics in the hot tapping market are being reshaped by material input requirements, fabrication complexity, and the concentration of manufacturing capability. The top three competitors account for a meaningful share of revenue, and the top five collectively represent more than half of market output. This level of concentration suggests that scale, engineering depth, and established service relationships confer real advantages, particularly in high-stakes applications. At the same time, the presence of specialized manufacturers and regional suppliers ensures that niche requirements, faster turnaround, and application-specific configurations remain viable competitive positions.
Investment in in-house manufacturing capacity is one sign of how companies are responding to these pressures. Strengthening machine shop capability allows suppliers to reduce dependency on external fabrication, improve lead-time predictability, and maintain tighter control over critical components. In an environment where equipment specifications are demanding and downtime costs are high, predictability in production and support can be as valuable as the machine itself. Cost structures are therefore not only about material prices; they are about the ability to deliver repeatable quality, maintain inventory of key parts, and respond to customized requests without excessive premium pricing.
PW Consulting
Competitive Landscape and Leading Strategies
The competitive field in hot tapping machines is diverse, spanning established global specialists, regional manufacturers, and equipment providers that serve narrower application sets. Leadership is not uniformly defined by portfolio breadth; it is increasingly defined by the ability to match machine capability with service requirements, demonstrate reliability in live systems, and support customers through installation, operation, and maintenance. Several firms have built recognizable positions by emphasizing either high-pressure performance, application specialization, or broad coverage across pipe sizes and materials.
One cluster of competitors has focused on comprehensive hot tapping capability for live pipeline connections across a wide diameter and pressure range, including onshore and offshore use. This type of positioning appeals to operators who need a single supplier relationship for multiple project conditions. The strategic advantage here is versatility, supported by a portfolio that spans smaller branch connections and much larger interventions. Another group has built its differentiation around proprietary high-pressure machines with sealing architectures designed for demanding service environments, including sour service and subsea-related applications. In this segment, credibility is tied to documented performance envelopes and the ability to manage risk in challenging conditions. A third group serves water and municipal applications with equipment optimized for under-pressure connections and live service insertion. These companies often compete on long experience, ease of use, and familiarity with local utility practices. A fourth group addresses smaller diameter or lower-pressure needs, including hand-operated or specialized systems for active lines. These offerings may not dominate headline revenue, but they can be strategically important where speed, simplicity, and accessibility matter more than maximum operating pressure.
Differentiation Paths and Commercial Logic
Across these positions, several common success factors emerge. The first is technical clarity. Suppliers that define operating envelopes precisely, specify compatible pipe materials and pressure ranges, and provide accessories that reduce field complexity tend to earn stronger customer confidence. The second is service integration. Hot tapping is not purely an equipment sale; it often involves procedure support, training, spare parts availability, and rapid response when field conditions change. Companies that treat support as part of the core offering can command better retention and more predictable demand. The third is manufacturing discipline. Recent investments in advanced machine tools by established players reflect an intent to control critical production steps internally, which can improve consistency and reduce dependence on external sources for key components. Such moves are especially meaningful when equipment must meet stringent material and performance expectations.
How the Landscape Is Evolving
The market structure appears likely to remain moderately fragmented while rewarding scale in the upper end of the pressure and diameter spectrum. Consolidation may continue where companies seek broader application coverage, stronger service networks, or deeper manufacturing capability. At the same time, the presence of specialized and regional players is likely to persist because many projects have localized requirements, specific material constraints, or limited scope that favors agile suppliers over large portfolios. New entrants face a meaningful barrier in credibility, documentation, and field validation, but they can still gain traction by targeting underserved size ranges, particular materials, or specific application workflows. In parallel, industry events and technical exchanges continue to accelerate the spread of best practices, especially around repair methods, in-service welding considerations, and safe intervention procedures. These forums matter because they influence operator expectations and elevate the importance of demonstrable competence over generic capability claims.
Forward Outlook: Trends and Opportunity Windows for 2026–2032
The next several years are likely to be shaped by a combination of steady demand growth and selective performance upgrades. One clear direction is the continued emphasis on in-service operations. As operators weigh the cost of shutdowns against the complexity of live interventions, equipment that enables safe branch connections and line stops without service interruption will remain central. This favors designs that improve alignment control, sealing reliability, and adaptability across pipe types. A second direction is the expansion of application coverage in water, wastewater, and industrial processing. While energy pipelines remain a major revenue pillar, diversified infrastructure spending and the need to maintain existing systems create repeated intervention opportunities in other verticals. A third direction is increasing attention to material integrity and compliance documentation. As expectations around pressure equipment, pipeline design, and safe field practice remain elevated, suppliers will be rewarded for transparent specifications and repeatable quality.
These trends create several commercial opportunity windows. For manufacturers, there is room to strengthen high-pressure and specialty portfolios while also improving accessibility for smaller-diameter or lower-pressure applications where demand frequency can be high. For equipment distributors and service providers, the value lies in combining suitable machines with procedure support, training, and rapid parts availability, since field outcomes depend on more than hardware alone. For investors, the more attractive exposure is likely to be in companies that can demonstrate consistent execution, controlled manufacturing, and the ability to serve regulated or high-risk applications where failure is costly. At the same time, uncertainty remains. Demand can shift with project cycles, maintenance budgets, and macroeconomic conditions. Raw material and fabrication costs may compress margins if not managed carefully. And competitive pressure can intensify where products become more comparable, especially in commoditized size and pressure ranges. The net effect is that growth will likely continue, but profitability and market share will be determined by execution quality rather than market tailwinds alone.
Actionable Implications for Decision-Makers
For manufacturers and equipment suppliers, the strategic priority is to align product capability with the economics of uptime. That means sharpening the definition of operating envelopes, investing in manufacturing control for critical components, and treating documentation and support as core commercial assets. Companies that can reduce setup complexity, improve reliability across materials, and shorten mobilization timelines will be better positioned to compete in both planned and urgent intervention scenarios. It also pays to evaluate where portfolio breadth genuinely adds value and where focused specialization can protect margin.
For investors and strategic planners, the key is to look beyond headline market size and assess where value is being retained. Attention should be given to suppliers with credible high-pressure or specialty positions, disciplined production capabilities, and service models that reduce customer risk. Portfolio exposure should be evaluated against demand diversification across oil and gas, water and wastewater, chemical and industrial processing, and power generation, since segment mix influences both growth resilience and sensitivity to project cycles. In a market where the top five competitors hold a majority share, scale advantages are real, but differentiated application expertise can still create durable niches.
For procurement teams and end users, machine selection should be evaluated through a total-intervention lens. The relevant questions include how well the equipment matches pipe material and pressure class, how quickly it can be deployed, how restrictive its documentation and compliance support are, and whether spare parts and field support are available when conditions change. Buying on unit price alone can understate operational risk and long-cycle cost. Selecting equipment that aligns with service conditions and support expectations typically reduces exposure to delays, rework, and downtime-related losses.
For decision-makers who need precise segmentation, regional demand patterns, product-type breakdowns, application-level revenue detail, and competitive benchmarking, a comprehensive market study can provide the granularity required for planning and investment judgment. A full research report can also support scenario analysis around pricing, capacity investments, and entry strategy across different application verticals and geographic markets.
Worldwide Single Axis Automatic Tapping Machine Market
For detailed analysis of this topic, please visit the official page: Worldwide Hot Tapping Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Diethyl Chlorophosphate Market: Why 5.03% CAGR and Asia Pacific’s 94M Shift Redefine Growth
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Diethyl Chlorophosphate Market
The global diethyl chlorophosphate market has evolved into a specialized yet strategically vital segment within the broader organophosphorus chemicals landscape. Valued at approximately USD 205.0 million in 2025, the market reflects a compound annual growth rate of 5.03 percent from 2020 through 2032, translating into a projected valuation of nearly USD 289.0 million by the end of the forecast period. This trajectory indicates steady expansion rather than speculative volatility, underpinned by sustained demand across chemical synthesis, flame retardant manufacturing, and agrochemical production. The market has demonstrated resilience through recent macroeconomic fluctuations, with 2024 recording a notable recovery to USD 196.6 million following a temporary contraction in 2023. Such patterns underscore an industry that is structurally anchored yet sensitive to input cost dynamics, regulatory shifts, and regional demand reallocation.
Despite this steady upward course, the sector confronts several structural friction points that will shape competitive positioning and investment priorities. First, the classification of diethyl chlorophosphate as a hazardous material under international transport frameworks introduces compliance complexity that disproportionately affects smaller manufacturers and cross-border traders. Logistics constraints, labeling requirements, and carrier restrictions elevate operational overhead and can delay time-sensitive deliveries to downstream formulators. Second, the market remains moderately concentrated, with the top three players capturing roughly 35 percent of global revenue and the top five accounting for just over half. This distribution leaves substantial headroom for fragmentation, yet it also means that scale advantages in procurement, purification, and regulatory documentation are increasingly decisive. Third, the industry is navigating a transitional phase in feedstock economics, where volatility in primary intermediary pricing has compelled producers to recalibrate margin structures and explore cost-pass-through mechanisms without alienating price-sensitive buyers.
Key Challenges at an Inflection Point
The intersection of regulatory scrutiny and supply chain recalibration has created an inflection point for market participants. Companies that once relied on incremental capacity additions and standardized distribution models are now compelled to rethink how they manage hazard compliance, quality consistency, and customer segmentation. The pressure is particularly acute in regions where transportation infrastructure is undergoing upgrades or where environmental enforcement is becoming more stringent. At the same time, downstream buyers are demanding greater transparency regarding material sourcing, batch consistency, and safety documentation. These expectations are reshaping procurement criteria and elevating the importance of supplier reliability over pure price competition. For executives evaluating exposure to this segment, the immediate question is not whether growth will continue, but which operational and strategic capabilities will determine who captures the most profitable share of that growth.
Key Drivers Shaping Market Trajectory
The expansion of the diethyl chlorophosphate market is being pulled forward by a convergence of technological, regulatory, and demand-side forces. Understanding these drivers requires looking beyond headline growth figures and examining the operational and commercial mechanisms that convert industry momentum into tangible value creation.
Technological Innovation and Process Refinement
Advancements in synthesis pathways and purification techniques are steadily improving the cost-efficiency and quality consistency of diethyl chlorophosphate production. Manufacturers are investing in optimized chlorination and esterification processes that reduce impurity profiles, particularly for applications requiring high-purity grades. In research and specialty chemical contexts, tighter control over moisture content and byproduct formation has become a differentiator, enabling suppliers to serve demanding applications in pharmaceutical intermediate synthesis and fine chemical production with greater reliability. These process improvements are not merely incremental; they are reshaping the value proposition of the high-purity segment by lowering rejection rates, reducing batch-to-batch variability, and expanding the range of downstream reactions that can be supported with confidence. As a result, suppliers that can demonstrate reproducible purity levels and robust analytical documentation are gaining preference in procurement decisions where performance consistency outweighs marginal price differences.
PW Consulting
Regulatory and Compliance Evolution
The regulatory environment continues to act as both a constraint and a competitive filter. Diethyl chlorophosphate is classified as a hazardous substance under international transport codes, requiring specific labeling, packaging, and carrier coordination in line with Department of Transportation and IATA standards. This classification is not merely a logistical footnote; it influences sourcing decisions, inventory positioning, and the economics of cross-border distribution. In parallel, European Union registration requirements under REACH impose additional obligations for volumes exceeding one tonne per year, with ongoing safety assessments evaluating reprotoxic classification potential. These requirements elevate the compliance burden for manufacturers and distributors operating in or supplying into Europe, but they also create a barrier that favors organizations with established regulatory expertise and document management capabilities. The practical effect is a market where compliance readiness increasingly functions as a strategic asset, enabling better-positioned players to secure long-term supply agreements and expand into regulated end markets with fewer friction points.
Demand-Side Shifts and Application Breadth
On the demand side, end-use industries are driving sustained consumption through both volume growth and application diversification. Agrochemical synthesis remains the largest application channel, reflecting the ongoing need for organophosphorus building blocks in crop protection and specialty pesticide formulations. This segment benefits from structural agricultural demand and the continued modernization of pest management portfolios in multiple regions. Flame retardant manufacturing represents another significant demand pillar, as materials used in electronics, construction, and transportation increasingly require halogen-free or lower-hazard fire resistance solutions. Diethyl chlorophosphate serves as a functional intermediate in certain formulations, linking its consumption to broader materials innovation cycles. Pharmaceutical and fine chemical intermediates, while smaller in aggregate volume, contribute disproportionately to margin profiles because these applications typically require higher purity, stricter documentation, and more responsive technical support. The cumulative effect is a demand base that is broad enough to buffer sector-specific downturns while offering multiple pathways for value creation.
Tris (Clorisopropyl) Phosphate Market
Supply Chain and Cost Structure Dynamics
Supply chain conditions have emerged as a decisive factor in shaping market economics. Feedstock availability and pricing, particularly for phosphorus oxychloride, directly influence production costs and margin resilience. Early 2024 saw a notable increase in intermediary pricing driven by supply chain disruptions in China, a shift that rippled through procurement cycles and prompted manufacturers to reassess inventory strategies. Some producers responded by securing longer-term supply agreements, diversifying source origins, or adjusting product mix toward grades with stronger margin characteristics. The broader lesson is that cost structure flexibility is becoming a competitive requirement rather than an optional optimization. Companies that can dynamically manage input exposure, maintain buffer inventory where justified, and communicate transparent cost drivers to customers are better positioned to preserve profitability during periods of input volatility. Conversely, rigid cost models and single-source dependencies increase vulnerability to regional disruptions and price shocks.
Competitive Landscape and Leading Strategies
The competitive structure of the diethyl chlorophosphate market reflects a blend of established specialty chemical suppliers and regional manufacturers with focused application expertise. Rather than a race to the bottom on price, the leading players are competing on reliability, technical support, purity assurance, and the ability to navigate evolving compliance requirements.
Differentiation Among Key Participants
Several companies have carved out recognizable strategic positions based on their product orientation and end-market focus. Major reagent and research chemical suppliers emphasize high-purity offerings for organic synthesis, phosphorylation reactions, and laboratory-scale applications. Their value proposition centers on consistent batch quality, comprehensive safety documentation, and accessibility for research and development teams. These players often benefit from broad catalog reach, global distribution networks, and strong brand recognition in scientific procurement channels. In contrast, manufacturers oriented toward industrial and agrochemical applications prioritize scale, export capability, and the ability to supply intermediates in volumes that support sustained downstream production. Their differentiation often lies in manufacturing flexibility, the capacity to serve organophosphorus compound supply chains, and responsiveness to bulk procurement requirements. A third group of specialty chemical producers focuses on fine chemical synthesis and pharmaceutical intermediate pathways, where technical service, purification consistency, and regulatory alignment with research-grade expectations matter more than sheer throughput.
Dicalcium Phosphate Market
Strategic Positioning and Competitive Advantages
The most effective competitive strategies in this market combine product-grade focus with operational discipline. High-purity suppliers gain advantage by reducing customer risk in sensitive applications, backing their products with analytical data, and maintaining inventory availability for time-sensitive research and pilot-scale demand. Industrial-focused producers compete by stabilizing supply, managing feedstock exposure, and offering dependable logistics even under hazardous-material transport constraints. Across both models, an increasingly important advantage is regulatory fluency. Suppliers that can anticipate compliance obligations, prepare necessary registration and safety documentation, and communicate transport requirements clearly reduce friction for buyers and strengthen long-term supply relationships. Another differentiating factor is customer segmentation discipline. Companies that align grade offerings, documentation depth, and service levels with specific application needs tend to protect margins more effectively than those pursuing undifferentiated volume growth.
Market Structure Evolution
The market structure appears poised for selective consolidation and parallel specialization. Moderate concentration leaves room for new entrants and regional expansion, particularly where demand growth outpaces local supply or where import dependence creates opportunities for domestic production. At the same time, the compliance, logistics, and quality assurance demands of the sector favor players with established infrastructure and process maturity. Over time, this dynamic is likely to encourage partnership models, capacity alignment with key downstream users, and gradual consolidation among smaller suppliers that lack the scale or capability to keep pace with regulatory and cost pressures. New entrants will need a clearly defined angle, whether through niche purity standards, regional supply reliability, or application-specific technical support, rather than competing purely on availability. The broader trend is toward a more segmented market in which competitive success depends on matching the right grade, the right compliance posture, and the right service model to the right end-use segment.
Future Trends and Commercial Implications
Looking ahead across the next three to five years, several trends are likely to shape how value is created and captured in the diethyl chlorophosphate market. These trends are not isolated developments; they interact with one another and will influence both opportunity selection and risk management.
Continued Growth with Graded Maturity
Market expansion is expected to remain positive, but the pace and composition of growth will likely diverge by segment and region. High-purity applications may continue to command stronger margins as research, fine chemical, and specialized intermediate demand grows more exacting. Industrial and agrochemical channels will still contribute substantial volume, but their profitability will depend more heavily on cost management, feedstock stability, and logistics efficiency. For commercial leaders, this implies that strategy should be calibrated by grade and application rather than treating the market as a single growth pool. The most resilient portfolios will likely combine reliable volume sources with higher-value specialty positions that benefit from stricter quality and documentation requirements.
Regulatory and Transport Compliance as a Strategic Lever
Compliance expectations are likely to intensify rather than plateau. Transport classification, labeling discipline, and regional registration processes are already shaping purchasing behavior, and this influence should deepen as enforcement becomes more consistent and documentation expectations rise. Organizations that proactively invest in compliance infrastructure, standardize safety and transport documentation, and monitor regulatory signals will be better equipped to expand into regulated channels and maintain supply continuity. The commercial opportunity here lies in reducing buyer friction: when a supplier can streamline compliance-related overhead for customers, it becomes a preferred partner in procurement decisions where reliability and risk management matter. The risk is equally clear. Operators that treat compliance as a reactive administrative task may face increasing delays, restricted market access, and customer attrition as buyers shift toward partners with stronger readiness.
Feedstock Volatility and Supply Chain Resilience
Input cost dynamics will remain a central theme. Intermediary pricing sensitivity, regional supply disruptions, and logistics constraints can quickly alter margin outlooks. The trend is pushing the market toward greater supply chain resilience through diversified sourcing, inventory planning that balances carrying costs against disruption risk, and closer coordination with downstream users to anticipate demand swings. Companies that build flexibility into procurement and production planning will be more capable of protecting margins while maintaining service levels. At the same time, the market may see increased interest in regional supply hubs and localized distribution strategies to reduce exposure to long-haul hazardous transport constraints and cross-border regulatory variation. The uncertainty lies in how quickly feedstock markets rebalance after disruptions and whether regional production capacity expands fast enough to absorb demand shifts without creating new bottlenecks.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to align grade strategies with the realities of cost structure and compliance readiness. High-purity lines should be supported by robust analytical control and documentation that justifies premium positioning, while industrial-grade operations should focus on feedstock diversification, logistics reliability, and disciplined inventory management. Companies that define their target applications clearly and avoid overextending into segments where they lack technical or regulatory capability are more likely to protect margins and build durable customer relationships.
For investors, the most attractive exposure may not come from undifferentiated volume plays but from operators that combine application focus with compliance strength and supply chain flexibility. Due diligence should assess feedstock exposure, hazardous-material logistics capability, regional regulatory readiness, and the extent to which a company’s product mix aligns with stable or growing end-use channels. Capabilities that reduce customer friction in regulated environments often translate into stronger retention and pricing power over time.
For procurement and sourcing leaders, supplier selection should extend beyond unit price to include batch consistency, documentation quality, transport compliance, and responsiveness under disruption. Long-term agreements can be valuable when paired with suppliers that demonstrate process maturity and regulatory alignment, particularly where production continuity and safety assurance are critical to downstream operations. Ongoing visibility into regional demand shifts, feedstock movements, and regulatory developments will help sourcing teams adjust specifications and inventory posture before disruptions cascade into operational risk. Detailed market intelligence that tracks these signals at a segment and regional level can materially improve planning accuracy and partnership decisions.
For decision-makers seeking a deeper view of segment-level demand structure, regional dynamics, and company-specific positioning, the full PW Consulting market research report provides the supporting detail needed to translate these strategic themes into actionable plans. The complete analysis offers a more granular breakdown of market size trajectories, segmentation intensity, and competitive moves that can inform capacity allocation, sourcing strategy, and investment prioritization with greater precision.
For detailed analysis of this topic, please visit the official page: Worldwide Diethyl Chlorophosphate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com