

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
DTH Hammer Market: Why the 4.65% CAGR and Asia Pacific's Dominance Change Everything

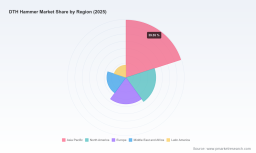
Global DTH Hammer Market: Strategic Trends and Commercial Opportunities (2025–2032)
The Worldwide DTH Hammer Market demonstrates steady structural growth, transitioning from a mature equipment segment to a dynamic ecosystem shaped by technological upgrades, shifting mining economics, and evolving end-use requirements. Measured at approximately $822.0 million in 2025, the market expands from $665.4 million in 2020, reflecting consistent value creation across the equipment lifecycle. Over the historical period, annual revenue progression has been influenced by project cycles, capital expenditure pacing, and operator preferences for higher reliability and uptime. Forecasts indicate growth accelerating through the late 2020s, with the market reaching $944.32 million by 2029 and crossing the $1 billion threshold by 2030 at $1022.16 million, before reaching $1129.96 million in 2032. The CAGR of 4.65% over the 2026–2032 forecast window indicates a market that is not merely expanding in nominal terms, but recalibrating around performance, serviceability, and application-specific engineering.
Hydraulic Hammer Market
This trajectory is not uniformly distributed. Revenue concentration remains moderate, with the top three players accounting for 38.5% of the market and the top five reaching 52.1%, indicating a competitive middle tier where regional specialists, application-focused manufacturers, and emerging cost-optimized suppliers continue to compete alongside established global brands. The balance of share across segments reveals where operators allocate spend: large-diameter and high-pressure configurations command a larger portion of revenue, while lower- and medium-pressure variants sustain significant utilization in shallower drilling, water infrastructure, and construction. Application-wise, mining remains the dominant revenue driver, followed by water well drilling and construction, with oil and gas contributing a smaller but strategically important portion tied to well development and geothermal activity.
Several inflection points define the current market environment. First, the shift from equipment replacement to performance-maximizing upgrades is changing purchasing logic. Operators increasingly view down-the-hole hammers as part of an integrated drilling system, weighing air consumption, penetration consistency, and service intervals alongside purchase price. Second, raw material volatility is pressuring cost structures across the supply chain. Tungsten carbide, a critical material in DTH hammer bits and internal components, experienced an average unit price increase of 9% in 2024 due to supply constraints in tungsten mining, and combined fluctuations in carbide and high-grade steel pushed manufacturing expenses for mining drill bits and related DTH tools up by 5–7% annually. These cost dynamics are forcing manufacturers to reevaluate material sourcing, standardize component families, and communicate total cost of ownership more effectively. Third, the operational context for DTH drilling is changing. High metal prices in 2025 sustained elevated activity levels in global mining markets, benefiting demand for DTH drilling equipment, while the ability of DTH hammers to perform effectively in hard rock and relatively populated areas with reduced risk to existing structures expands their role beyond traditional remote operations.
The practical implication for decision-makers is that the market is growing, but competitiveness is increasingly determined by engineering precision, aftermarket strength, and the ability to manage input cost pressure without eroding margins. Companies that treat DTH hammers as commoditized consumables risk losing share to competitors that frame product value around uptime, air efficiency, and configuration flexibility. At the same time, buyers face a widening range of solutions, requiring clearer evaluation criteria to distinguish genuine performance differences from positioning language.
Key Drivers Reshaping the DTH Hammer Market
Technology innovation is moving the market beyond incremental improvements toward measurable drilling efficiency and system-level integration. Recent product and exhibition activity underscores this direction. In early 2026, Sandvik introduced the Leopard DI610i high-performance down-the-hole surface drill rig for open-pit mines, signaling continued investment in rigs optimized for DTH performance in surface operations. Around the same period, Epiroc showcased the Smart Roc T40 rig with DTH hammer and a new integrated OilQuick bracket at CONEXPO-CON/AGG 2026, reinforcing a trend toward smarter rig linkage, quicker tool change methods, and configuration flexibility across surface applications. These launches reflect a broader shift: DTH hammers are no longer evaluated in isolation, but as part of a drilling ecosystem where rig compatibility, bit mechanics, and operator ergonomics jointly determine productivity. The commercial consequence is that manufacturers are competing on integrated performance rather than standalone tool attributes, and buyers are prioritizing solutions that reduce cycle time and simplify field adjustments.
Policy and regulatory dynamics are also shaping demand patterns. Environmental and community considerations increasingly influence site selection and drilling method choice, especially where operations intersect with inhabited or infrastructure-sensitive areas. In this context, DTH hammers are valued for their suitability in hard rock formations and their ability to support drilling in populated areas with reduced risk to existing structures compared to alternative methods. This characteristic expands the pool of viable projects, particularly in water well development, urban construction, and certain mining expansions where vibration, noise, and structural impact are scrutinized. Regulatory expectations do not merely constrain operations; they redirect demand toward equipment that can meet performance requirements under tighter site conditions. As a result, manufacturers that can demonstrate controlled operation, reliable casing compatibility, and predictable penetration behavior are positioned to capture project approvals more readily.
Demand-side behavior reflects both cyclical commodity economics and structural changes in how drilling services are procured. Supportive metal prices in 2025 helped sustain elevated activity in global mining markets, which in turn lifted demand for DTH drilling equipment and related tooling. Beyond the cyclical support, end-users are increasingly focused on operational continuity. Aftermarket solutions remain an important part of the value proposition; Epiroc’s 2025 reporting highlighted sustained demand for tools and attachments, with DTH-related equipment and aftermarket solutions remaining strong. This pattern indicates that buyers are willing to invest in equipment that supports longer service life, easier maintenance, and predictable replacement cycles. The shift is especially meaningful for contractors and producers who manage fleets across multiple sites, where downtime directly affects project economics. Demand is therefore becoming more discerning: price remains relevant, but reliability, parts availability, and configuration adaptability increasingly determine repeat purchasing.
Supply chain and cost structure changes put additional pressure on both producers and buyers. The 5–7% annual increases in manufacturing expenses for mining drill bits and related DTH tools, driven by tungsten carbide and high-grade steel price fluctuations, illustrate how raw material exposure affects product economics. This environment rewards companies that can redesign hammer families with modularity, standardize high-wear components, and negotiate more resilient material supply arrangements. It also matters for buyers, who must weigh whether lower upfront prices translate into higher total cost when wear rates, air consumption, and replacement frequency are considered. The broader trend is a market in which cost discipline and engineering efficiency must be pursued together rather than in isolation. Companies that can balance material cost management with performance retention are better positioned to defend margins while maintaining competitiveness.
Taken together, these drivers suggest a market where growth is supported by application expansion, performance-led procurement, and systemic integration rather than raw volume alone. The most meaningful opportunities are likely to accrue to organizations that can align product development with site constraints, fleet economics, and material cost realities.
Competitive Landscape and Leadership Strategies
The competitive field combines global incumbents with strong aftermarket capabilities and regional specialists offering cost-competitive or application-focused solutions. Sandvik, Epiroc, and Atlas Copco each compete from a position of broad portfolios and established channel networks. Sandvik’s offering centers on high-performance DTH hammers engineered for efficiency, durability, and precise drilling performance across mining and construction applications. Epiroc provides advanced DTH hammers, including COP M-series and DTH 5 hammers with multiple configurations for surface and underground operations in mining, quarrying, and construction. Atlas Copco delivers high-performance DTH hammers designed for demanding operating environments in mining, construction, and water well drilling. Collectively, these companies benefit from the ability to supply integrated rig-tool-support pathways, which reduces integration friction for large operators and supports repeat business through service and parts ecosystems.
Specialist and regional players pursue differentiation through focused engineering or value positioning. Mincon emphasizes precision-engineered DTH hammers that optimize air usage for outstanding drilling performance in mining, waterwell, geothermal, and construction applications, an angle that directly addresses operating cost and efficiency. Halco Rock Tools manufactures DTH hammers, drill bits, and casing systems for mining, quarrying, construction, water wells, and formation sampling, positioning itself around complete hole-making solutions rather than hammer-only offerings. Drill King International produces a comprehensive range of DTH air hammers, water hammers, and reverse circulation hammers for various drilling challenges, broadening its addressable use cases beyond conventional DTH air systems. Mindrill focuses on DTH hammers optimized for hard rock with high penetration rates and low maintenance, a proposition aligned with difficult formation drilling where throughput and service frequency matter. Numa designs and supplies large-diameter DTH hammers for holes from 3.5 to 48 inches in mining and construction, targeting a specialized size segment where capacity and hole diameter justify distinct engineering choices. Ingersoll Rand provides DTH hammers as part of its broader industrial equipment portfolio for drilling operations. Guizhou Sinodrills Equipment (Sinodrills) supplies cost-effective and reliable DTH hammers and drilling tools, including the GSE DHD series, for global rock drilling applications, appealing to buyers seeking dependable performance with a sharper price profile.
Recent company activity illustrates how strategy is evolving in practice. Sandvik’s Leopard DI610i introduction for surface open-pit mining reflects continued emphasis on high-performance surface rigs paired with DTH tooling. Epiroc’s Smart Roc T40 display with DTH hammer and integrated OilQuick bracket demonstrates attention to rig-tool integration and field flexibility. Epiroc’s 2025 reporting on sustained demand for tools and attachments, with aftermarket solutions remaining strong, reinforces the importance of service and replacement cycles in maintaining revenue resilience. Robit’s streamlining of its H-series Down the Hole hammer family into a modular offering, aimed at improving efficiency in the DTH product line, points to a broader industry movement toward modularization as a way to manage complexity, standardize service, and respond faster to configuration demand. These developments indicate that differentiation is increasingly achieved through system compatibility, modularity, and service strength rather than through hammer geometry alone.
Market structure is evolving along multiple lines. Consolidation pressure exists at the top, where established players leverage scale, global distribution, and aftermarket depth. At the same time, the moderate concentration levels leave meaningful room for differentiation in the middle and lower tiers. New entry and expansion are most viable where companies can address a specific size class, formation type, or application requirement more effectively than generalist suppliers. Cost-competitive suppliers continue to expand their reach, especially where buyers prioritize reliable function and favorable pricing over premium brand attachment. However, the rising cost of materials and the growing importance of uptime create a ceiling for pure price competition; sustainable positioning increasingly requires demonstrable efficiency advantages, predictable service intervals, or configuration flexibility that reduces total operating cost. The strategic implication is that incumbents must continue to invest in integration and service ecosystems, while challengers need credible performance claims and a clear application niche to avoid competing solely on price.
Forward Outlook: Trends Defining the Next Three to Five Years
One clear trend is the continued emphasis on system-level performance over component-only specifications. As rigs, hammers, bits, and service practices become more tightly linked in operator evaluations, the market will likely reward solutions that reduce setup time, improve air efficiency, and maintain penetration consistency across varied formations. This favors manufacturers that can demonstrate measurable operating benefits and provide configurations suited to distinct site conditions. Companies that treat the hammer as a standalone consumable will face growing pressure from integrated offerings that tie tooling performance to rig capability and service availability.
PW Consulting
A second trend is the expanding relevance of DTH drilling in applications beyond traditional hard-rock mining. Water well infrastructure, construction-related foundation and blast-hole work, and geothermal-related development can all benefit from DTH’s characteristics in hard formations and its comparatively controlled impact in sensitive settings. If project activity in these segments continues to grow, demand will become more diversified, reducing reliance on any single end-use cycle and creating opportunities for manufacturers with application-specific variants and casing-compatible tooling strategies. The diversification also encourages broader aftermarket demand, since multiple application segments generate ongoing service and replacement needs.
A third trend is cost and supply chain resilience becoming a permanent competitive variable rather than a temporary disruption. With raw material exposure continuing to influence manufacturing expenses, modular product design, standardized high-wear components, and disciplined sourcing will likely remain central to margin protection. Buyers will increasingly scrutinize total cost economics, which could compress margins for suppliers that cannot justify performance premiums and could advantage suppliers that can demonstrate lower operating cost despite higher initial price. This dynamic introduces uncertainty: commodity-driven project pacing can shift demand quickly, and material price swings can alter both supply and purchasing behavior. Still, the direction of travel points toward a market where efficiency, modularity, and service reliability are integral to growth rather than optional enhancements.
Strategic Implications for Decision-Makers
For manufacturers, the priority is to align product strategy with how buyers now evaluate drilling systems. Modular hammer families, air-efficient designs, and clear service intervals can support both cost management and performance claims. Companies should also prepare for a more demanding aftermarket environment by ensuring parts availability, compatibility information, and configuration guidance are easy to access and apply in the field. Differentiation should be anchored in measurable operating benefits rather than broad positioning language, especially as material costs continue to pressure margins.
For investors, the most relevant signals are aftermarket resilience, application diversification, and the ability to manage input cost volatility without eroding value. Businesses that combine credible performance with service depth and a defensible niche in size, formation, or end-use are better positioned to sustain growth through market cycles. Attention should also be paid to integration moves and modularization strategies, since these can reveal where competitive advantage is being built over the next planning horizon.
For procurement and operations leaders, the key is to evaluate DTH solutions against total operating economics rather than first cost alone. Air consumption, penetration stability, service frequency, and compatibility with existing rig setups can materially affect project economics. A disciplined comparison framework that reflects formation requirements, hole diameter needs, and site constraints will help avoid false savings from lower-spec options that increase downtime or wear. Detailed segment-level comparisons of configuration families, application use patterns, and regional pricing dynamics can sharpen procurement decisions and reduce operational risk. For a closer look at the full segmentation, company positioning, and tailored scenarios across regions and applications, the complete PW Consulting report provides structured detail and custom analysis paths to support planning.
DTH Drill Market
For detailed analysis of this topic, please visit the official page: Worldwide DTH Hammer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com