

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Lactation Massager Market: Why Home Care Subsidizes Growth in 2025-2032

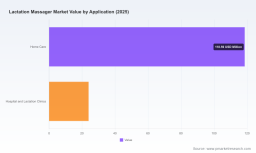
Strategic Trends and Commercial Opportunities in the Worldwide Lactation Massager Market
Market Landscape and Core Challenges
The global lactation massager market has entered a period of sustained expansion, driven by heightened awareness of breastfeeding support and the growing acceptance of at-home therapeutic devices. From 2020 to 2025, the market revenue climbed from approximately $92.2 million to $142.6 million, reflecting a compound annual growth rate of nearly 9.15 percent. Projections extending through 2032 indicate the market will surpass $263 million, with the most pronounced acceleration expected in the mid-to-late forecast window. This trajectory is supported by a convergence of clinical validation, consumer preference for non-invasive comfort solutions, and the broader integration of lactation support into maternal health ecosystems.
Despite the favorable momentum, the industry faces several structural headwinds that will shape competitive outcomes over the next decade. The first challenge revolves around regulatory classification and the resulting compliance burden. Products in this category are typically regulated as Class II therapeutic massagers or vibrators under the FDA’s framework for physical medicine devices. Manufacturers must navigate special controls that specify vibration frequency limits, leakage current thresholds, and skin-surface temperature ranges when heat is applied. These requirements create a non-trivial barrier to rapid product iteration, particularly for startups that lack established regulatory infrastructure. At the same time, the absence of dedicated reimbursement codes means the end-user or healthcare system usually absorbs the full cost, which constrains volume-based adoption in institutional settings.
The second challenge is the tension between feature differentiation and consumer accessibility. As manufacturers introduce warming, vibration, and kneading combinations, the risk of feature creep increases. Overly complex devices can undermine the core value proposition—simple, reliable relief—and complicate usability for new parents who need intuitive, low-learning-curve tools. Manufacturers must balance clinical-grade performance with ergonomic simplicity, a tension that is visible in the growing split between single-function tools and multi-mode integrated devices.
The third challenge lies in market concentration and channel dynamics. The top three players collectively capture a meaningful share of revenue, while the top five expand that footprint further, indicating that brand trust, distribution relationships, and clinical endorsement remain potent moats. New entrants must therefore compete not only on product design but also on evidence generation, retail or direct-to-consumer visibility, and partnerships with lactation professionals. The market is large enough to accommodate multiple players, yet selective enough that undifferentiated offerings struggle to gain traction.
Key Drivers of Market Change
Technological Innovation and Clinical Validation
The most durable driver in this market is the shift from anecdotal comfort products to devices backed by functional design and, increasingly, clinical evidence. Recent developments illustrate this transition. In mid-2025, independent trial results from Amsterdam University Medical Centre quantified breast inflammation outcomes and positioned a clinically validated aid as a breakthrough option for common breastfeeding challenges. This publication builds on earlier hospital pilot data and signals a broader industry move toward measurable efficacy. For manufacturers, the implication is clear: clinical signals are becoming a competitive asset rather than a niche differentiator. Devices that demonstrate reproducible benefits in relieving engorgement, improving milk flow, or reducing pumping discomfort are better positioned to earn trust from lactation consultants, healthcare providers, and discerning consumers.
Technologically, product innovation is progressing along two parallel paths. One path emphasizes integrated multimodal relief, combining heat with vibration or kneading in a single form factor. The other path focuses on ergonomic refinement, compact geometry, and ease of cleaning, which matter deeply for daily use. Some entrants have even introduced smaller warming massagers designed for comfort and convenience, reflecting a consumer demand for discreet, travel-friendly support. The competitive frontier is no longer just about whether a device provides relief, but how precisely it delivers it, how intuitively it is operated, and whether it fits into the routines of nursing and pumping parents.
Policy, Regulatory, and Reimbursement Context
Regulatory dynamics are shaping both entry timing and product architecture. Under current FDA expectations for therapeutic vibrators and massagers, manufacturers must adhere to special controls covering vibration parameters, electrical safety, and temperature limits where heat is applied. These controls do not automatically block market entry, but they do require disciplined design verification and documentation. In practice, this favors companies with established quality systems and the ability to manage 510(k) pathways or exemption qualifications without compromising speed to market.
On the reimbursement side, the landscape remains constrained. There are no dedicated CPT or HCPCS codes for lactation massager devices, and related breastfeeding support services often rely on general evaluation and management codes or breast pump codes. Because massagers themselves are generally not separately reimbursable under standard durable medical equipment policies, commercial adoption depends on out-of-pocket purchasing, bundled offerings, or institutional procurement where clinical value can be justified internally. This reimbursement gap is both a limitation and an opportunity: companies that frame their products as high-value self-care tools, or that integrate them into broader lactation support programs, can still drive adoption without relying on traditional reimbursement channels.
Consumer Behavior and Demand-Side Shifts
Demand-side change is being powered by a cultural and clinical re-framing of breastfeeding support. Parents increasingly view lactation comfort tools as practical, non-invasive aids rather than optional accessories, and they are more willing to invest in devices that reduce pain, shorten pumping sessions, or support regular milk flow. The growth of remote lactation counseling and digital maternal health services is also expanding the addressable audience, because recommendations from professionals can accelerate product awareness and reduce purchase hesitation. In addition, the rise of direct-to-consumer education has made it easier for consumers to compare features, read peer experiences, and seek devices with warming, vibration, and waterproofing attributes that fit lifestyle needs.
From a commercial standpoint, this demand evolution rewards brands that can articulate a clear benefit story and provide consistent quality. Emotional resonance matters, but it must be supported by reliable performance. Products designed by people with direct breastfeeding experience and marketed around practical outcomes such as clogged duct relief, engorgement reduction, and improved lymphatic drainage are gaining attention because they align product claims with real user priorities.
Supply Chain and Cost Structure Evolution
Supply chain considerations are becoming a more prominent part of the strategic conversation. As device portfolios expand from manual tools to electric and heat-integrated models, component selection, battery safety, heating element reliability, and waterproofing requirements influence both unit economics and time-to-market. Manufacturers are increasingly balancing the cost of feature richness against the need to maintain accessible price points. At the same time, channel diversification is reshaping cost structures: direct-to-consumer sales can improve margin control and brand ownership, while retail and professional channel partnerships can accelerate awareness but require trade-offs in discounting and inventory management. Companies that stabilize their supply chains and align product complexity with target price tiers are better positioned to scale without eroding profitability.
Competitive Landscape and Leading Strategies
The competitive set in the lactation massager market blends established consumer health brands with specialized maternal care entrants. Several companies have built their positioning around product architecture, clinical narrative, and ecosystem fit, creating a landscape where differentiation is increasingly multidimensional.
One recurring strategy is multimodal functionality paired with targeted clinical claims. Some leading consumer direct brands have introduced warming and vibrating models, including versions that combine both modalities in a single device, explicitly designed to relieve clogged ducts, engorgement, and mastitis-related discomfort while improving milk flow and reducing pumping time. This approach reflects a move toward comprehensive relief rather than single-mechanism tools. Alongside this, major lactation support brands are offering dedicated massagers to loosen and comfort breast areas, improving both breastfeeding and milk expressing experiences. These portfolios show that the category is no longer about a single product type but a spectrum of solutions adapted to different user preferences.
A second strategy is evidence-led positioning. One Australian company has advanced a clinically validated aid combining temperature, movement, and compression for common breastfeeding challenges, with independent trial results published in a recognized breastfeeding journal. This kind of evidence building strengthens credibility with clinicians and informed consumers, and it can support premium positioning or institutional adoption where internal stakeholders demand substantiation. The April-to-July 2025 trial activity at Amsterdam University Medical Centre, which quantified breast inflammation outcomes and highlighted the device as a breakthrough aid, reinforces this trajectory and suggests that academic collaboration can be a meaningful lever for market trust.
A third strategy is ecosystem integration and bundling. Some manufacturers offer multiple lactation massagers with warming, vibrating, and kneading options, and frequently bundle them with breast pumps. This bundling strategy can increase average order value, simplify consumer choice, and position the massager as part of a holistic expression routine rather than a standalone accessory. Complementary features such as adjustable heat and vibration settings, along with waterproofing, are being used to address practical pain points like cleaning convenience and customizable comfort.
A fourth strategy is specialization by material and usage philosophy. A New Zealand-origin brand known for silicone-based manual breastfeeding products offers massagers and support tools compatible with its broader ecosystem, emphasizing natural, non-toxic relief. Meanwhile, several U.S.-based consumer brands focus on patented or purpose-built designs for nursing and pumping parents, targeting engorgement relief, duct unblocking, milk flow improvement, and lymphatic drainage. This diversity shows that differentiation is not limited to electronics or heat; material choice, form factor, and brand mission all contribute to positioning.
PW Consulting
The market structure is evolving along both consolidating and fragmenting axes. On one hand, the presence of a meaningful concentration among leading players indicates that scale, distribution, and brand recognition matter, and that larger consumer health portfolios can leverage cross-selling and retail relationships. On the other hand, the number of specialized entrants is growing, and innovation is coming from both small focused brands and larger players adding lactation support to their catalogs. New entrants are likely to continue arriving, especially where they can bring a compelling clinical story, a distinctive ergonomic concept, or a channel advantage such as strong professional recommendation networks. Over time, the market may see selective consolidation among smaller brands that struggle to fund regulatory compliance or clinical validation, while successful niche players may be acquired for their product credibility or consumer loyalty.
Future Trends and Commercial Implications
Over the next three to five years, the market is likely to move along three interconnected paths. First, clinical substantiation will become a more standard expectation rather than a rare advantage. As more trial data becomes available and as lactation professionals increasingly reference evidence in recommendations, brands that can demonstrate measurable benefit will be better placed to command trust and, in some contexts, premium pricing. Second, product complexity will keep rising, but winners are likely to emphasize calibrated simplicity: multimodal relief that is easy to operate, easy to clean, and safe for repeated use. Devices that balance heat, vibration, and compression with intuitive controls and clear safety boundaries should outperform overly complicated alternatives. Third, channel and partnership models will diversify. Expect stronger links between device manufacturers, lactation consultants, hospital programs, and digital maternal health platforms, even if reimbursement codes remain limited. Bundling, professional recommendation, and embedded education can all drive adoption without depending solely on direct payback from insurance.
These trends create concrete opportunities. Manufacturers can invest in design-for-compliance, robust thermal and vibration controls, and clinical collaboration to build defensible positions. Investors can look for brands with credible evidence pipelines, stable supply chains, and clear channel strategies rather than feature novelty alone. Procurement and channel partners can evaluate products on usability, safety documentation, and professional endorsement, since these attributes will increasingly influence repeat purchase and recommendation rates.
The main uncertainties relate to regulatory interpretation, reimbursement policy, and consumer price sensitivity. Should expectations around special controls or labeling tighten further, development cycles could lengthen. If reimbursement pathways remain constrained, broader institutional volume may depend on internal procurement logic rather than external coding. And if inflation or category saturation pressures price thresholds, brands will need to justify premium features with demonstrable value.
Actionable Guidance for Decision-Makers
-
For manufacturers, prioritize design that aligns multimodal features with clear regulatory and safety documentation. Invest early in clinical validation or independent testing where feasible, because evidence is becoming a differentiator that supports both consumer trust and professional recommendation. Calibrate product complexity to the target user’s daily routine, and choose channel strategies that balance margin control with visibility among lactation professionals.
Worldwide Breastfeeding Accessories Market -
For investors, evaluate opportunities against three filters: credible differentiation, defensible compliance readiness, and a realistic route to awareness. Favor companies that can articulate measurable user benefits, maintain stable cost structures as they scale multimodal devices, and build relationships with lactation consultants or institutional buyers. Be cautious about plays that rely only on feature announcements without evidence or channel traction.
-
For procurement teams and channel partners, assess products on usability, safety documentation, cleaning practicality, and the strength of professional endorsement. Because reimbursement is generally limited, total value should be judged through the lens of user satisfaction, repeat purchase potential, and compatibility with broader lactation support programs. Device selection should favor options that make daily use easier and that reduce friction for parents and clinicians alike.
For decision-makers seeking detailed segmentation data, company-level profiles, and tailored scenario planning, the full PW Consulting research report provides a deeper breakdown of regional and application dynamics, competitive moves, and forward-looking market scenarios. The complete study is available for teams that need granular inputs to support product planning, investment screening, or procurement decisions.
Breast Pump Market
For detailed analysis of this topic, please visit the official page: Worldwide Lactation Massager Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com