

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Soft Ice Cream Powder Market: Why the 5.25% CAGR Story Hides Bigger Shifts Through 2032

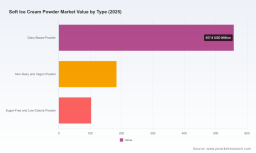
Navigating Momentum and Complexity in the Worldwide Soft Ice Cream Powder Market
Market Status and Critical Inflection Points
The global market for soft ice cream powder has entered a phase of structured expansion, characterized by consistent demand growth and evolving formulation standards across commercial foodservice channels. Between 2020 and 2025, the industry navigated a period of post-pandemic operational normalization, with revenue trajectories reflecting steady adoption in quick-service environments and specialty dessert outlets. Forecasts extending through 2032 point to a compound annual growth rate of approximately 5.25 percent, suggesting that the sector will continue to benefit from institutional menu innovation, increased reliance on powdered formats for operational consistency, and growing appetite for customizable dessert components.
At the macro level, the market has crossed a threshold where powdered soft serve formats are no longer viewed solely as cost-efficient alternatives to liquid mixes. Instead, they are increasingly integrated into product development roadmaps that prioritize shelf stability, logistical flexibility, and consistent texture performance across varying ambient conditions. This structural shift supports revenue visibility for manufacturers and helps foodservice operators manage ingredient procurement more predictably, particularly in regions where cold-chain constraints or volatile dairy pricing pressures exist.
Despite the favorable trajectory, three interconnected challenges are reshaping how participants position themselves. First, raw material volatility remains a persistent pressure point. Dairy derivatives such as skim milk powder and whole milk powder continue to experience price fluctuations tied to regional supply balances, export policy adjustments, and broader commodity cycles. When input costs move quickly, manufacturers must balance margin protection with competitive pricing for end users who are themselves facing consumer price sensitivity.
Second, formulation complexity is intensifying. Operators and end consumers increasingly expect cleaner labels, improved melting resistance, and reliable performance across different soft serve machines. Achieving these outcomes simultaneously places higher demands on emulsification systems, stabilizer blends, and processing consistency. Companies that can standardize premium sensory outcomes while maintaining operational compatibility across widely used equipment configurations are gaining an advantage, but this capability requires sustained technical investment and rigorous quality control.
Third, regulatory alignment and trade dynamics are adding a layer of geopolitical complexity. Regional agreements and domestic availability measures influence the flow of dairy-based inputs, export availability, and cost structures for premix suppliers. Businesses that rely on cross-border ingredient sourcing must monitor policy shifts that affect supply continuity, especially where export caps or domestic protection measures alter the availability of key powders. These dynamics do not necessarily constrain growth, but they demand more disciplined sourcing strategies and scenario planning.
Taken together, the market environment favors organizations that can marry formulation expertise with resilient supply planning. The revenue expansion expected over the coming years is not automatic; it will be captured by players who convert operational consistency, ingredient reliability, and sensory differentiation into commercial value.
Key Drivers Reshaping the Market
Technology, Formulation, and Sensory Performance
One of the most meaningful drivers in the soft ice cream powder market is the ongoing refinement of formulation technology. Modern premix systems are increasingly designed to deliver creamy mouthfeel and controlled melt-down without relying on overly complex ingredient lists. Manufacturers are investing in stabilizer and emulsifier architectures that maintain structure across temperature variations and improve texture consistency from the first serve to the last. This matters because soft serve operators face direct customer scrutiny on texture and visual appeal; even minor inconsistencies can affect repeat purchase behavior.
A second area of innovation lies in dairy-free and alternative-base development. Demand for plant-forward options is expanding beyond niche positioning, moving into mainstream commercial applications where operators want a single production format capable of serving mixed customer preferences. Powder formats are particularly well suited to this shift because they enable centralized formulation and simplify inventory management for businesses that must accommodate both traditional dairy and non-dairy orders without maintaining separate liquid supply chains.
These technical improvements are not merely product enhancements; they affect commercial economics. Better performance consistency reduces waste, improves machine compatibility, and enables operators to standardize offerings across multiple locations. For manufacturers, the ability to provide a reliable base that performs similarly across widely used dispensing equipment creates a competitive differentiator that is difficult for smaller or less technically organized competitors to replicate quickly.
Consumer and Operator Behavior Shifts
On the demand side, the market is being shaped by changes in how dessert and beverage programs are designed. Quick-service and value-oriented chains continue to seek dessert attach rates that are easy to store, easy to serve, and predictable in quality. At the same time, specialty parlors and catering environments are pursuing premium sensory differentiation through customized flavor profiles, regional preferences, and improved structure. This dual dynamic pushes manufacturers to serve both ends of the spectrum: high-volume reliability and premium customization.
Catering and event-driven usage also contributes to demand stability. In these settings, powdered formats are valued for their portability, extended shelf life, and ability to support scalable production without the logistical constraints associated with refrigerated liquid mixes. As event caterers and institutional foodservice providers look for ways to simplify menu planning and reduce spoilage risk, powder-based soft serve continues to gain relevance as a practical solution.
Supply-Side Dynamics and Input Availability
Dairy ingredient supply conditions remain central to the market’s operating environment. Spot activity and production data indicate that core inputs such as skim milk powder continue to move in volumes that reflect both domestic processing demand and export-oriented trade. At the same time, pricing for export-grade dairy powders has remained within a range that requires active cost management rather than passive purchasing. Whole milk powder used in frozen dessert bases often carries a related but distinct price profile, which influences how manufacturers construct formulations and where they seek substitution or efficiency.
In parallel, milk pricing signals tied to Grade A and Class III channels indirectly affect the broader dairy input environment relevant to ice cream mixes. Futures indications pointing toward higher interim pricing remind manufacturers that forward contracting, inventory timing, and formulation flexibility are essential tools for managing exposure. Companies that can adjust blending ratios or maintain a diversified ingredient base without sacrificing sensory quality are better positioned to preserve margin stability during periods of input fluctuation.
Cheese Powder Market
Trade and policy frameworks also influence supply availability in specific regions. Export caps and domestic availability provisions can alter the volume of powder moving across borders, particularly for skim milk powder and milk protein concentrates. These arrangements are often designed to support local supply, but they can also affect global pricing and logistics planning for premix producers with international distribution footprints. Businesses operating in multiple markets need to track these changes as part of their sourcing strategy, not merely as external news.
Regulatory and Standards-Driven Quality Expectations
Regulatory expectations and certification practices continue to shape product development and market access. In many commercial arenas, buyers look for documented compliance, consistent safety controls, and recognizable quality credentials. This is especially true for operators scaling across regions or serving institutional clients with strict procurement standards. Manufacturers that maintain strong documentation, standardized production protocols, and adaptable formulation pathways can reduce barriers to expansion and accelerate trust-building with new distribution partners.
Rather than treating compliance as a back-office function, leading companies increasingly view it as a commercial enabler. Clear specifications, repeatable processes, and the ability to provide both hot and cold process options where relevant help manufacturers serve a broader set of commercial applications with fewer friction points. This alignment between technical reliability and commercial usability is becoming a defining factor in winning larger, multi-site contracts.
Competitive Landscape and Strategic Positioning
The competitive field in soft ice cream powder spans established European manufacturers, Asia-based bulk suppliers, and regional specialty producers. The market is not dominated by a single formulation philosophy; instead, it reflects a patchwork of strengths, from premium sensory positioning to cost-efficient scalability and regional ingredient access. This diversity creates both opportunity and pressure, as buyers compare suppliers not only on price but also on texture performance, machine compatibility, and the breadth of flavor or dietary options available.
Several manufacturers stand out for differentiated positioning. Revala has built a profile around premium soft ice cream powders, including dairy-free variants, with an export footprint across more than 60 countries and a focus on creamy texture for HoReCa and industrial use. Its emphasis on unique recipes reflects a strategy rooted in sensory differentiation rather than pure commodity volume. ARO Global positions around reliable quality and global manufacturing and delivery for commercial soft serve and industrial applications, which appeals to buyers prioritizing consistency and supply continuity. Allwin Food Co., Ltd. targets commercial foodservice with a product designed for smooth, flavorful soft serve using water and machines, aligning with operators who need straightforward deployment.
In the premium artisanal segment, PreGel leverages its Italian manufacturing heritage and broad international certifications to serve gelato and soft serve applications with hot and cold process options. This positions the company as a solutions-oriented supplier for operators seeking both craftsmanship and operational flexibility. Rubicone adds scale and longevity to this profile, with a history stretching back to 1959 and exports to more than 75 countries, offering a complete range of ingredients for soft-serve machines. LYKKE complements the EU-focused landscape with worldwide shipping and flexible order sizes, supporting customers who need both smaller trial volumes and larger commercial supply.
PW Consulting
Regional specialists also play an important role. Shandong Bigtree Dreyfus Special Meals Food Co., Ltd. focuses on bulk soft ice cream powder for wholesale commercial use, while Lautan Natural Krimerindo serves dessert shops and foodservice in Indonesia with premix formulations built for rich texture and balanced flavor. PMF (BMF) offers Turkish-manufactured soft ice cream mix powders with dairy and vegan compatibility and alignment with major soft serve machines, which matters in markets where equipment interoperability is a priority. Alaskan Snow Manufacturing emphasizes cost efficiency, shelf stability, and creamy texture relative to liquid mixes, targeting HoReCa and industrial users who value operational predictability. Keliff’s adds export capability from India with multiple flavors and private label options, and AussieBlends serves frozen dessert businesses with powdered mixes tailored for soft serve applications. Luigi’s Gelato supplies a powder base engineered with emulsifiers, stabilizers, and fibers to improve structure and reduce melt-down, while Oleo-Fats focuses on premium soft serve mix quality for consistent commercial results.
The strategic pattern across these companies is not uniform, but it does suggest a market where differentiation is increasingly tied to three dimensions: texture and melt performance, dietary flexibility, and supply reliability. Companies that can combine these attributes with strong documentation and application support are better positioned to win multi-site and cross-border business. Newer entrants and regional suppliers can still compete effectively by serving specific flavor preferences, local ingredient economics, or machine-specific formulations, but broader international expansion usually requires a more comprehensive quality and logistics framework.
Recent commercial activity reinforces the importance of portfolio breadth and continuous catalog refresh. Itaberco’s 2025 catalog release showcased shelf-stable soft serve mixes spanning neutral, vanilla, chocolate, dairy-free, and dairy-alternative options, along with soft serve custard and customization for pastry chefs. This kind of portfolio expansion signals that manufacturers are responding to demand for both variety and application-specific support. ARO Global’s later update underlined its emphasis on global manufacturing and delivery with a message centered on reliable quality for commercial applications. These moves reflect a broader trend: suppliers are investing in making their offerings easier to evaluate, deploy, and scale across varied foodservice environments.
Looking at the structure of the market, concentration remains moderate, with leading players holding meaningful but not overwhelming share. That leaves room for consolidation among regional players, especially where scale, certification readiness, and export capability can be combined. At the same time, fragmentation persists in specialized niches where local taste preferences, machine compatibility, or private label demand create defensible positions. The likely evolution is a dual path: incremental consolidation among suppliers targeting international HoReCa and industrial channels, alongside continued specialization among regional manufacturers serving localized flavor and premix requirements.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, the soft ice cream powder market is likely to be shaped by a combination of formulation maturation, sourcing discipline, and channel expansion. One prominent trend is the continued convergence of sensory performance and dietary flexibility. As more operators seek to serve both dairy and non-dairy customers from a manageable inventory base, demand will grow for powders that deliver comparable texture and stability across different formulation paths. Suppliers that can standardize these outcomes while preserving distinct flavor profiles will have an advantage in multi-concept and multi-region deployments.
A second trend is the growing importance of cost-resilient sourcing strategies. Because dairy inputs remain sensitive to production cycles, export conditions, and domestic availability measures, manufacturers and large buyers will increasingly rely on structured sourcing plans, forward visibility, and formulation flexibility. This does not necessarily mean a move away from dairy-based formats; rather, it suggests that companies will need the ability to adjust blends, manage inventory timing, and respond to regional price divergence without compromising serving quality. In practice, this favors procurement teams and product developers who treat ingredient volatility as a design constraint rather than an occasional disruption.
A third trend is the expansion of powdered soft serve within convenience-oriented and scale-driven foodservice formats. Quick-service environments and catering operations value products that reduce waste, simplify storage, and support rapid service without refrigeration complications. Where flavor variety, machine compatibility, and consistent overrun or texture are achieved, powdered formats can become a preferred choice for growing dessert programs. The opportunity here is not just volume growth, but also product adjacency: operators may pair soft serve powders with complementary frozen dessert components, custard-style offerings, or localized flavor builds that increase menu relevance.
These trends carry both opportunity and risk. On the upside, companies that invest early in dairy-free and low-calorie performance, machine-agnostic reliability, and strong application support are well placed to capture broader usage across commercial channels. On the risk side, unpredictable input pricing, shifting trade provisions, and changing consumer expectations can erode margin assumptions or slow the adoption of premium-priced variants. Businesses that rely on narrow ingredient exposure or single-market sourcing may face more volatility than those with diversified supply and formulation redundancy.
Strategic Actions for Decision-Makers
For Manufacturers and Product Developers
Prioritize formulation versatility and application consistency as core commercial assets. The ability to deliver reliable texture, controlled melt-down, and machine compatibility across dairy, dairy-free, and reduced-sugar formats can expand market access and reduce customer switching risk. Equally important is sourcing architecture: build redundancy for key dairy inputs, maintain forward visibility on price signals, and test formulation flexibility without sacrificing sensory quality.
For Investors and Strategic Acquirers
Evaluate opportunities based on scalable quality systems, export readiness, and portfolio breadth rather than volume alone. Companies with strong documentation, international certifications, and the ability to support both premium and cost-efficient segments are more likely to sustain expansion across multiple foodservice channels. Integration potential is strongest where a supplier can combine regional cost advantages with the operational rigor needed for cross-border distribution.
A practical next step for any stakeholder is to deepen the view beyond headline market size and into the segments, regional cost dynamics, and company-level positioning that determine actual commercial outcomes. Detailed segmentation data, competitive profiling, and scenario-based insight can sharpen planning for sourcing, product roadmap decisions, and market entry. In that context, the full research report provides the granularity needed to move from directional confidence to specific execution planning.
Soft Ice Cream Machines Market
For detailed analysis of this topic, please visit the official page: Worldwide Soft Ice Cream Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com