

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Oxacillin Market at 3.55% CAGR: The Regional & Formulation Shifts Reshaping Strategy

Worldwide Oxacillin Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The global oxacillin market has demonstrated steady growth over the past five years, expanding from approximately $378.12 million in 2020 to an estimated $450 million in 2025. Looking ahead, the market is projected to reach roughly $492.72 million by 2026 and continue its upward trajectory through 2032, with a compound annual growth rate of 3.55%. This growth trajectory reflects a mature but resilient pharmaceutical segment, driven by sustained demand for anti-infective therapies and the ongoing need for targeted treatment options against penicillinase-producing staphylococcal infections.
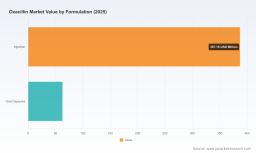
Despite the positive growth outlook, the oxacillin market faces several structural challenges that warrant careful strategic consideration. First, the market exhibits significant concentration, with the top three players capturing an estimated 52.4% of total revenue and the top five controlling approximately 78.1%. This concentration creates both competitive barriers and supply chain vulnerabilities, particularly when key manufacturers experience production disruptions. Second, the market is heavily weighted toward injectable formulations, which account for the substantial majority of revenue compared to oral capsules. This formulation imbalance creates specific regulatory, manufacturing, and distribution challenges that differ markedly from oral solid dosage markets. Third, the end-user landscape remains dominated by hospital settings, which concentrate procurement decisions and create dependency on institutional purchasing cycles and formulary management processes.
A critical inflection point has emerged around supply chain stability. Recent data indicates that oxacillin injection products have experienced notable supply disruptions, with manufacturing delays reported by several prominent suppliers. These disruptions are not isolated incidents but reflect broader vulnerabilities in the specialized API manufacturing ecosystem, where a limited number of qualified producers serve global demand. For market participants, this environment demands proactive supply chain risk management rather than reactive procurement strategies.
Additionally, the regulatory landscape continues to evolve. The absence of active originator patents for oxacillin creates an open generic market with multiple abbreviated new drug application approvals, which theoretically encourages competition but also intensifies price pressure on manufacturers. Simultaneously, regulatory bodies have introduced updated susceptibility testing interpretive criteria and labeling requirements that affect how oxacillin products are positioned, prescribed, and monitored. These regulatory dynamics create both compliance costs and opportunities for manufacturers who can navigate evolving standards efficiently.
Key Drivers Shaping Market Dynamics
Technological Innovation and Manufacturing Advances
The oxacillin market benefits from ongoing advancements in sterile manufacturing processes and quality control technologies. Injection formulations require stringent sterility assurance and specialized production capabilities, creating natural barriers to entry that favor established manufacturers with robust quality systems. Recent regulatory actions, including updated package inserts and prescribing information published in early 2026, reflect heightened attention to product quality documentation and labeling accuracy. Manufacturers that invest in modern sterile processing technologies and comprehensive quality management systems are better positioned to meet these standards while maintaining production efficiency.
The technology landscape also extends to formulation optimization. While injectable forms dominate current market revenue, developments in manufacturing precision and stability enhancement create opportunities for improved product consistency. Companies producing oxacillin sodium API and finished dosage forms increasingly leverage process analytical technologies and continuous manufacturing principles to reduce batch variability and improve supply reliability. These investments, while requiring upfront capital, contribute to long-term competitive differentiation through reduced deviation rates and more predictable production schedules.
Regulatory Environment and Standards Evolution
Regulatory dynamics fundamentally shape market participation strategies. The FDA has maintained active engagement with oxacillin product standards, with recent developments including the approval of previously withdrawn new drug applications for injectable formulations and the inclusion of oxacillin sodium in approved drug product listings for 2026. These regulatory milestones signal continued official recognition of oxacillin as an active therapeutic option while reinforcing compliance expectations for market participants.
A particularly important regulatory development involves susceptibility testing standards. Regulatory authorities have concurred with revised interpretive criteria for oxacillin testing against Staphylococcus species, with cefoxitin serving as a surrogate in certain testing contexts. This evolution affects how clinical laboratories assess antibiotic susceptibility and influences prescribing patterns. Manufacturers and supply chain participants who understand these testing framework changes can better anticipate demand shifts and align product positioning with clinical practice realities. The fact that oxacillin remains indicated specifically for infections caused by penicillinase-producing staphylococci demonstrated to be susceptible to the drug creates a well-defined clinical niche that distinguishes it from broader-spectrum alternatives.
Demand-Side Shifts and Clinical Practice Patterns
Hospital and clinic demand for oxacillin reflects broader trends in anti-infective utilization. Healthcare institutions increasingly focus on antimicrobial stewardship programs that emphasize appropriate antibiotic selection, dosing optimization, and resistance management. Within this framework, oxacillin occupies a specific therapeutic role for susceptible staphylococcal infections, differentiating it from broader-spectrum agents that may face greater stewardship scrutiny or contribute more substantially to resistance pressure. This clinical positioning supports sustained demand from institutional buyers who prioritize targeted therapy options within their formulary management strategies.
The end-user mix, with hospitals representing the dominant consumer segment, means that procurement decisions are influenced by institutional purchasing consortia, group purchasing organizations, and clinical guideline updates. This centralized purchasing environment rewards manufacturers who can demonstrate reliable supply, consistent quality, and competitive pricing structures. Clinics and retail pharmacy channels represent smaller but potentially growing segments, particularly as outpatient infusion services expand and community-based treatment options evolve.
Supply Chain Restructuring and Cost Dynamics
Supply chain considerations have become increasingly central to market strategy. Raw material availability and API production capacity represent critical constraints, with disruptions linked to supply issues affecting major producers. These challenges highlight the concentration risk inherent in specialized antibiotic manufacturing, where a limited number of qualified API producers and formulation facilities serve global demand pools. For manufacturers and distributors, this environment demands diversified sourcing strategies, strategic inventory management, and stronger supplier relationships to mitigate the impact of production interruptions.
Cephalosporin Market
Cost structures in the oxacillin market reflect the economics of generic antibiotic production, where price competition is intense and margin preservation depends on operational efficiency. Manufacturers based in India and China, alongside European and North American producers, compete across different value chain segments, from bulk API production to finished dosage form supply. Geographic diversification of manufacturing capabilities can provide competitive advantages through access to different cost structures, regulatory pathways, and customer bases. However, maintaining consistent quality across multiple production sites requires robust quality oversight and regulatory compliance infrastructure.
Worldwide Penicillin Market
Competitive Landscape and Leading Strategies
Market Structure and Key Participants
The global oxacillin market features a diverse set of participants spanning multiple geographies and business models. European manufacturers such as ACS Dobfar SPA contribute significant production capacity for oxacillin sodium API and sterile injectable forms, leveraging established partnerships to serve international markets including the United States. Centrient Pharmaceuticals maintains an active role in oxacillin sodium API production with an emphasis on high-quality penicillin-class antibiotics for worldwide distribution. These European participants bring established regulatory compliance records and quality manufacturing reputations that support their market positions.
Indian manufacturers represent a substantial presence in the market, with companies including Aurobindo Pharma Limited, Akums Lifesciences, SiNi Pharma, and Wellona Pharma offering oxacillin sodium API and finished dosage forms across various market channels. Aurobindo's extensive anti-infectives portfolio provides a broad commercial platform for oxacillin products, while specialized manufacturers like Akums focus on contract manufacturing arrangements that supply international markets. SiNi Pharma and Wellona Pharma concentrate on oxacillin injection finished dosage forms with export-oriented strategies, reflecting the importance of injectable formulations in global demand patterns. Bioquim in Spain and Reyoung Pharmaceutical Co., Ltd. in China add further geographic diversity, with Bioquim emphasizing GMP manufacturing for global pharmaceutical clients and Reyoung producing oxacillin in various forms including solid preparations and injectables with an export focus.
In North America, Baxter Healthcare Corporation and Sagent Pharmaceuticals serve the domestic market with oxacillin sodium for injection products. Baxter markets oxacillin sodium in plastic containers for intravenous use in treating susceptible staphylococcal infections, leveraging established healthcare distribution relationships and brand recognition in the US clinical environment. Sagent Pharmaceuticals supplies oxacillin injection products within the US market, contributing to domestic availability alongside other manufacturers.
Strategic Positioning and Differentiation Approaches
Leading market participants pursue distinct strategic positioning approaches. Some manufacturers emphasize vertical integration, controlling both API production and finished dosage form manufacturing to capture value across the supply chain and reduce dependency on external suppliers. This integration can improve margin structure and supply reliability but requires significant capital investment and regulatory compliance capability across multiple production stages. Other participants focus on specialized niches, such as contract manufacturing for international clients or specific formulation types, allowing them to serve particular market segments without the overhead of full product portfolios.
Quality reputation and regulatory compliance record represent important differentiators in a market where sterility assurance and product consistency are paramount. Manufacturers with demonstrated track records of regulatory adherence and quality system robustness can command preferential positioning with institutional buyers who prioritize supply reliability. The recent regulatory developments around labeling updates and approved drug product listings reinforce the importance of maintaining current compliance status, as products with outdated documentation or regulatory gaps face market access risks.
Price competitiveness remains a fundamental consideration given the generic nature of the market and multiple approved applications. However, in an environment marked by supply disruptions and manufacturing challenges, buyers increasingly value supply reliability alongside price. Manufacturers who can demonstrate consistent availability and proactive communication about supply status may earn stronger buyer relationships and more stable procurement commitments, even if their pricing is not always the lowest in the market.
PW Consulting
Evolving Competitive Dynamics
The competitive landscape shows indicators of both consolidation pressure and market fragmentation. High market concentration among the top participants suggests established players hold meaningful advantages in scale, customer relationships, and regulatory infrastructure. However, the presence of numerous manufacturers across multiple geographies, particularly in India and China, indicates opportunities for continued market entry and niche positioning. The lack of active originator patents removes traditional barriers to market entry, allowing new ANDA holders and contract manufacturers to participate in the market.
A trend toward supply chain regionalization may influence competitive dynamics going forward. As healthcare systems and procurement organizations seek to reduce dependency on single-source or distant suppliers, manufacturers with geographically diversified production capabilities or local market presence may gain competitive advantage. This dynamic could create opportunities for contract manufacturers who can provide flexible production capacity and responsive supply to meet shifting procurement preferences. Additionally, the evolving regulatory environment around susceptibility testing and product labeling may create opportunities for manufacturers who can proactively adapt their product information and clinical positioning to align with updated standards.
Future Trends and Outlook Through 2032
Trend 1: Supply Chain Resilience as a Competitive Imperative
Supply chain stability is poised to become an increasingly critical competitive factor over the next three to five years. The documented supply disruptions affecting major producers highlight vulnerabilities that procurement organizations and healthcare systems are likely to address more systematically. This trend creates opportunities for manufacturers who can invest in reliable production capacity, diversified sourcing, and transparent communication about supply status. Companies that build reputation for supply dependability may capture disproportionate share during periods of market tightness and establish stronger long-term buyer relationships. Conversely, participants who cannot address supply reliability concerns may face erosion of market position even if their cost structures remain competitive.
Strategic inventory management and multi-source procurement strategies will likely gain prominence among institutional buyers. This shift benefits manufacturers who can offer flexible supply arrangements, safety stock options, and contingency planning support. The trend also favors vertically integrated players who control more of their supply chain and can respond more nimbly to production challenges than those dependent on external API or component suppliers.
Trend 2: Regulatory Complexity and Quality Differentiation
The regulatory environment is expected to maintain its emphasis on product quality, labeling accuracy, and testing standard alignment. Recent regulatory actions suggest ongoing scrutiny of antibiotic product documentation and compliance status. Manufacturers who proactively maintain current regulatory filings, updated prescribing information, and alignment with susceptibility testing standards will be better positioned to navigate this environment. Quality differentiation may become more valued as healthcare institutions strengthen their vendor qualification processes and emphasize supply chain quality assurance in procurement decisions.
The indication specificity of oxacillin for penicillinase-producing staphylococci with demonstrated susceptibility creates a relatively stable clinical positioning that is less susceptible to displacement by broader-spectrum alternatives. However, evolving antimicrobial stewardship priorities and resistance patterns warrant ongoing monitoring, as shifts in clinical guidelines could affect demand patterns over the forecast period. Manufacturers who invest in understanding clinical practice trends and maintain alignment with stewardship program priorities may better anticipate demand shifts.
Trend 3: Geographic Expansion and Market Diversification
Geographic market dynamics are likely to evolve as healthcare access expands in emerging markets and existing markets mature. The current regional distribution of market revenue reflects established healthcare infrastructure in North America and Europe alongside growing demand in Asia Pacific and other regions. Over the forecast period, varying healthcare investment patterns, regulatory harmonization efforts, and local manufacturing development may create opportunities in specific geographies. Manufacturers with export capabilities and experience navigating diverse regulatory environments may find growing opportunities as demand expands in developing markets.
Portfolio diversification strategies also merit attention. While injectable formulations currently dominate market revenue, the oral capsule segment represents a smaller but potentially complementary product line. Understanding demand patterns across formulations and end-user channels can inform product development and commercialization strategies. Markets that balance multiple formulations and end-user segments may achieve greater revenue stability than those heavily dependent on a single formulation or channel.
Potential risks to the outlook include continued supply chain volatility, regulatory changes that could affect product positioning or compliance requirements, and broader market dynamics affecting generic antibiotic pricing pressure. Economic factors influencing healthcare budgets and procurement capacity could also impact market growth rates. Participants should maintain scenario awareness around these variables and develop contingency strategies accordingly.
Strategic Recommendations for Decision-Makers
For manufacturers operating in or considering entry to the oxacillin market, prioritizing supply chain resilience and quality documentation should feature prominently in strategic planning. Investments in production reliability, diversified sourcing, and robust quality management systems offer competitive advantages that extend beyond price considerations. Manufacturers should also maintain current regulatory compliance status across all product files and labeling, monitoring regulatory developments that affect susceptibility testing standards, prescribing information, and approved product listings. Building flexible manufacturing capacity that can respond to demand fluctuations and supply disruptions adds valuable optionality in a market with documented production challenges.
For investors evaluating opportunities in the anti-infective sector, the oxacillin market presents a mature but strategically interesting segment characterized by steady growth, established clinical positioning, and supply chain dynamics that create differentiation opportunities. Due diligence should examine participant quality systems, regulatory compliance records, supply chain dependencies, and geographic market exposure. Understanding the concentration of manufacturing capacity and the specific capabilities of key suppliers can inform assessments of market sustainability and competitive positioning. Investors should also monitor regulatory developments that could affect market access or product requirements.
For procurement organizations and healthcare systems sourcing oxacillin products, diversifying supply sources and developing contingency plans for product availability should be priorities given documented supply disruption patterns. Evaluating suppliers on criteria that include quality system robustness, regulatory compliance status, and supply reliability communication, alongside price, can support more resilient procurement strategies. Engaging with manufacturers who demonstrate proactive supply management and transparent communication about production status may reduce procurement risk during periods of market tightness. Staying informed about regulatory updates and susceptibility testing standards helps ensure procurement decisions align with current clinical practice requirements.
Timely access to detailed market intelligence, including granular segmentation data, competitive profiles, and regulatory tracking, supports more informed strategic decisions across these stakeholder groups. Comprehensive analysis that combines market sizing, competitive dynamics, regulatory developments, and demand-side trends provides a fuller picture than any single data source alone.
This analysis draws on market data and industry intelligence current through early 2026. For detailed segmentation data, competitive profiling, and customized strategic recommendations specific to your market position and objectives, PW Consulting offers comprehensive oxacillin market research services. Contact our team to discuss tailored intelligence solutions that address your specific strategic questions.
For detailed analysis of this topic, please visit the official page: Worldwide Oxacillin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com