

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Report: Low‑ and Medium‑Voltage Inverter Market Poised to Expand at 7.16% CAGR Through 2032
By pmarketresearch, 2026-06-30
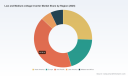
Low and Medium‑Voltage Inverter Market: Strategic Imperatives for 2026 — PW Consulting Insights
Executive summary
PW Consulting's latest market research on the Low and Medium‑Voltage Inverter Market (base year 2025; historical window 2020–2025; forecast 2026–2032) delivers a pragmatic, decision‑grade playbook for senior executives preparing strategy in 2026. The market has more than doubled in size since 2020 — rising from a mid‑single digit billion USD base to an estimated 8.21 Billion USD in 2025 — and is modeled to continue expanding at a compound annual growth rate (CAGR) of approximately 7.16% through the 2026–2032 forecast window, reaching an addressable market in excess of 13 Billion USD by 2032. These headline figures mask a complex set of technological, regulatory and supply‑chain inflection points: our report translates those inflections into concrete choices for product roadmaps, procurement, M&A and go‑to‑market priorities.
Low and Medium-voltage Inverter Market
Why 2026 is a pivotal planning year
-
Regulatory compression: 2024–2026 has seen an unprecedented flurry of grid‑code and interconnection updates that materially affect inverter functional requirements. Examples include tightened ride‑through and post‑fault active power recovery obligations for sizable demand connections, mandatory reactive power capability ceilings for inverter‑based resources, and updated low‑voltage interconnection standards. For product leaders and system specifiers, these are not hypothetical compliance items — they are hardware and control software specifications that will shape purchase cycles and retrofit windows in 2026 and beyond.
Low and Medium-voltage Inverter Market -
Technology gating: The commercialisation of higher‑blocking SiC devices and 3kV string inverter architectures, combined with new medium‑voltage inverter topologies for utility‑scale deployments, is accelerating a step‑change in plant simplicity and levelised cost dynamics. Pilots commissioned in early 2026 demonstrate that these technologies can materially reduce balance‑of‑plant complexity, but they also shift BOM composition and supplier exposure.
Low and Medium-voltage Inverter Market -
Supply‑side stress: Critical raw‑material tensions — most notably a global copper supply shortfall that has been observable since 2025 — are driving both input price volatility and procurement lead‑times. For manufacturers and large project developers, 2026 will be the first full planning cycle where raw‑material constraints materially affect production planning, hedging strategies and supplier selection.
-
Market structure dynamics: Although a set of established multinational players continue to anchor technology and brand leadership, concentration metrics reflect a market that remains comparatively fragmented versus adjacent power‑electronics domains. That fragmentation creates space for targeted entrants, regional champions and consolidation plays that we expect to accelerate in 2026–2027.
What the report delivers — practical, executable content
-
Market sizing and scenario modelling: multi‑horizon topline and downside scenarios (sensitivity to commodity price, grid‑code adoption and technology substitution) designed to feed financial planning models.
-
Technology roadmaps and product specification matrices: comparison of LV and MV inverter architectures, key semiconductor and passive component choices, and minimum viable control‑function sets to meet evolving grid codes.
-
Go‑to‑market playbooks: demand segmentation approaches, channel strategies for EPCs vs. utilities, and deployment sequencing for hybrid storage + inverter propositions.
-
Procurement and supply‑chain playbooks: risk heatmaps, dual‑sourcing templates, hedging and long‑lead component strategies tailored to 2026 procurement cycles.
-
Competitive and M&A evaluation frameworks: capability and gap analyses for leading corporations and fast‑growing challengers, plus trigger events that typically catalyse consolidation.
-
Regulatory compliance and revenue‑path mapping: regionally contextualised compliance checklists and a monetisation matrix for grid services enabled by inverter control (frequency response, voltage support, demand‑side markets).
-
Executable pilots and CAPEX/OPEX templates: step‑by‑step pilot design guides (including performance metrics and test protocols) and financial templates to quantify payback and lifetime cost of ownership.
Competitive landscape — patterns, not just names
The competitive field is a mix of long‑standing global incumbents, diversified power‑systems vendors and agile regional specialists. The market’s three‑player and five‑player concentration metrics indicate meaningful room for challenger strategies: global leaders anchor solutions across equipment, services and software, while disciplined regional players exploit price, local standards familiarity and speed to market.
-
ABB (Zurich, Switzerland) — Re‑entering segments via targeted acquisitions and leveraging wind converter expertise to recombine medium‑ and low‑voltage solar offers. Strategic concern for incumbents: ABB’s acquisition pattern hints at rapid capability stacking across renewable grid interconnection technologies.
-
Siemens (Munich, Germany) — Focusing on medium‑voltage drives and integrated power conversion for industrial and renewable applications; Siemens competes on system integration and utility‑grade controls.
-
Schneider Electric (Rueil‑Malmaison, France) — Emphasises power management and inverter solutions for LV and MV, playing to strengths in building automation and distributed energy resource orchestration.
-
Danfoss (Nordborg, Denmark) — Industrial frequency converters and AC drives, positioning to capture industrial retrofit opportunities driven by energy‑efficiency programs.
-
Yaskawa, Fuji Electric, Nidec, Hitachi — Japanese incumbents with deep industrial drive portfolios and strong OEM links; their differentiated value is reliability, engineering services and heavy‑duty industrial product lines.
-
GE Vernova — Targeting utility‑scale renewables with integrated solar power station offerings; new product launches in early 2026 illustrate an intent to simplify utility procurement by delivering transformer plus inverter stations.
-
Chinese and Taiwanese challengers (e.g., INVT, Inovance, Hiconics, STEP Electric, Delta) — Compete aggressively on cost and rapid product cycles; increasingly visible in large‑volume industrial and distributed renewable projects.
Recent competitive events — such as ABB’s acquisition move to re‑enter the solar inverter market, Fraunhofer’s commissioning of medium‑voltage PV pilots using high‑blocking SiC semiconductors, and GE Vernova’s mid‑2026 product launches — are signals that incumbents are both defending installed bases and racing to secure superior technology nodes.
Market dynamics: drivers, risks and near‑term inflection points
-
Demand drivers: accelerating renewable capacity additions, electrification of industrial processes, and the opening of new grid‑service revenue streams to smaller, inverter‑based assets.
-
Technology drivers: SiC adoption, higher DC‑link voltages in string inverters, digital twins for inverter fleet management, and tighter power‑electronics + controls integration to meet grid‑code demands.
-
Supply risks: copper shortages and volatile commodity markets, extended lead times for certain passive components, and single‑sourcing risks for power semiconductors.
-
Regulatory uncertainties: staggered and regionally divergent grid codes create retrofit risk for early deployments; conversely, they also create first‑mover revenue opportunities for products engineered to the new standards.
Strategic recommendations for 2026 decision‑makers
-
Prioritise standards‑compliant functionality in next‑generation SKU planning. Products that can demonstrably meet new ride‑through, active‑power recovery and reactive‑power obligations gain an outsized procurement preference.
-
Hedge input‑commodity exposure now. Adopt multi‑tier supplier contracts, strategic component inventory buffers for 2026 delivery windows, and explore material substitution validation where feasible.
-
Accelerate SiC and higher‑voltage string inverter pilots. Technology readiness will determine market access in medium‑voltage PV deployments; pilots will also clarify BOS and O&M cost implications.
-
Pursue targeted M&A or alliance plays to close capability gaps (controls, grid services software, or medium‑voltage transformer integration) rather than broadscale horizontal consolidation.
-
Design commercial offers that monetise grid services. With markets opening to smaller resources and in several jurisdictions now compensating reactive and dynamic services, inverters with market‑grade telemetry and controls command pricing premiums.
-
Revisit warranty and service‑model economics. Longer, performance‑linked service agreements can differentiate product offers while enabling predictable revenue streams amid hardware commoditisation.
-
Localise manufacturing and aftermarket capabilities where regulatory or grid‑code enforcement is most active; this reduces retrofit friction and speeds compliance updates.
How to use this report in your 2026 planning cycle
-
Board briefings: distil scenario analyses into three investment envelopes (protect, optimise, grow) with clear trigger criteria tied to commodity prices, pilot outcomes and regulatory adoption timelines.
-
Product roadmap alignment: map feature development to mandatory compliance milestones first, then to revenue‑enabling functions (grid services). Prioritise modular architectures that allow field upgrades.
-
Procurement reset: deploy the report’s supplier risk matrix to re‑evaluate global sourcing — particularly for copper and power‑semiconductor supply chains — and implement dual‑sourcing where economically warranted.
-
M&A and partnership screening: use the competitive matrices to identify bolt‑on targets that close gaps in control software, MV transformer integration or service networks.
Concluding note and call to action
2026 will be the year many strategic choices crystallise for companies competing in the Low and Medium‑Voltage Inverter Market. With a market on a sustained growth trajectory — demonstrated by the acceleration from an early‑decade base to an estimated 8.21 Billion USD in 2025 and modeled forward at a 7.16% CAGR to 2032 — leaders must balance engineering investments, supply‑chain resilience and commercial creativity. PW Consulting’s full report provides the granular segment intelligence, supplier scorecards and deployable templates that boards and executive teams will need to convert the high‑level signals outlined here into winning action plans. For the detailed segment breakouts, supplier scorecards and downloadable modelling assets, visit our report page to access the complete dossier and companion toolset.
For detailed analysis of this topic, please visit the official page: Low and Medium-voltage Inverter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Helicopter Simulator Market to Climb from USD 215.0 Million in 2025 to USD 344.8 Million by 2032 at 6.98% CAGR
By pmarketresearch, 2026-06-30
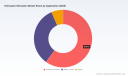
Helicopter Simulator Market 2026: Strategic Imperatives from PW Consulting’s New Industry Report
Executive snapshot
PW Consulting’s latest Helicopter Simulator Market report (base year 2025) synthesizes five years of historic performance (2020–2025) with a detailed outlook through 2032. The market has expanded materially since 2020 and is projected to continue growing at a compounded annual growth rate (CAGR) of 6.98% across the 2026–2032 forecast window. From a strategic planning perspective, this trajectory transforms simulator programs from niche cost centers into scalable training and sustainment platforms that materially affect fleet readiness, instructor staffing models, and supplier selection across civil and defense operators.
Helicopter Simulator Market
Why this report matters for 2026 decision-makers
-
Timing: 2026 is an inflection year. Regulatory shifts, rapid adoption of mixed-reality technologies, and supplier consolidation are converging to create first-mover advantages for operators and vendors who align procurement, certification, and commercial models now.
Helicopter Simulator Market -
Risk-to-opportunity translation: The market’s steady growth trajectory—built on a resilient base established during the previous five years—means decisions made in 2026 about simulator type, certification pathways, and support contracts will influence total cost of ownership and training throughput for the next decade.
Helicopter Simulator Market -
Strategic clarity: For C-suite and operational leaders, the report converts macro growth and competitive dynamics into actionable priorities—procurement timing, technology partnerships, and aftermarket strategies—that preserve optionality while capturing upside from digitalization.
What the report contains (practical, actionable deliverables)
-
Market sizing and forecast: A validated topline series covering 2020–2032, with scenario-based forecasts to stress-test growth assumptions under differing regulatory and technology adoption paths.
-
Demand modelling toolkit: Customizable templates for operators to estimate training demand, simulator seat-hours, instructor staffing and break-even timelines under multiple fleet and utilization scenarios.
-
Certification and regulatory playbooks: Step-by-step guidance on contemporary FAA/EASA pathways, risk mitigations for cancelled or evolving advisory circulars, and a checklist for mixed-reality pre-qualification.
-
Supplier evaluation matrix: Rigorous comparative assessment criteria—technical fidelity, maintainability, upgradeability, IP and software openness, delivery lead times, and aftermarket economics—that buyers can deploy immediately.
-
M&A and partnership maps: Target profiles and diligence checklists for strategic acquisitions, minority investments, and OEM-operator JV structures to accelerate capability acquisition.
-
Commercial templates: Negotiable contract language, service-level benchmarks, and TCO calculators designed for procurement teams to secure predictable lifecycle costs and performance guarantees.
Market dynamics and what’s driving growth
The overall simulator market has shown robust expansion from its 2020 base, with an accelerated pace through 2024–2025 and sustained momentum into the forecast period. The drivers are multifold:
-
Technology substitution: Mixed-reality and high-fidelity visual systems are reducing the marginal cost of scenario complexity and enabling faster certification pathways for certain training objectives.
-
Operator economics: Rising real-flight costs and crew availability pressures are increasing the share of training conducted in simulators, while operators seek scalable, on-site training solutions.
-
Defense and security demand: Modern doctrines emphasizing realistic mission rehearsal have increased investments in mission-specific simulation capabilities.
-
Aftermarket service growth: With higher installed bases and longer lifecycle expectations, service revenues—updates, motion platform maintenance, and scenario libraries—are an expanding value pool for suppliers.
Regulatory & standards landscape — implications for 2026
-
Regulatory flux brings both risk and opportunity. The cancellation of FAA AC 120-63 in April 2026 alters the certification environment for some helicopter simulators, introducing uncertainty for certain device qualification routes but also opening space for manufacturers to propose alternate compliance regimes. Our report provides a navigation map for operators and vendors to re-scope certification programs, reduce rework risk, and accelerate deployment.
-
EASA’s Special Conditions framework and national pre-qualifications are emerging as practical accelerators for mixed-reality solutions; recent pre-qualifications and device pre-approvals demonstrate viable templates to follow.
Competitive landscape — players to watch and strategic moves
The market displays a concentrated supplier structure: the top three companies control a meaningful share of industry revenues, and the top five capture an even larger portion. This concentration creates differentiated routes to scale—either by partnering with established integrators or by targeting underserved niches with modular, lower-cost offerings.
-
CAE Inc. (Montreal): A dominant provider of full-flight devices and Level D-capable platforms, CAE’s portfolio and global service network make it a primary partner for large airlines, OEMs and defense customers. Strategic implication: CAE remains the go-to for turnkey, high-fidelity programs but can be expensive for mid-market operators seeking rapid deployment.
-
Frasca International (Urbana, IL): With a broad line of FTDs, AATDs and CPTS, Frasca is positioned to capture training center and flight school demand that prioritizes cost-effectiveness and reliability. Strategic implication: Frasca is a logical partner for scale-focused operators and regional training networks.
-
ELITE Simulation Solutions (Zurich): Known for FAA- and EASA-certified TH-125 and AS355 models, ELITE’s recent delivery and commissioning of an FAA-certified TH-125 for a law-enforcement unit underscores its operational focus and credibility in public safety markets.
-
Reiser Simulation and Training GmbH (Germany): A leader in mixed-reality integration, Reiser’s pre-qualification of the H145 D3 demonstrates the viability of high-fidelity XR solutions under EASA frameworks.
-
Ryan Aerospace (Gold Coast): By launching an affordable Robinson mixed-reality simulator, Ryan targets the professional training segment with a disruptive price-performance proposition.
-
TRU Simulation + Training (South Carolina) and Helisim GmbH (Germany): TRU’s close alignment with specific OEM platforms, and Helisim’s pre-qualification work for large twin-engine models, make both key partners for OEM-endorsed training ecosystems.
Recent market moves—product launches, certification milestones and localized deliveries—signal that suppliers are diversifying go-to-market approaches: OEM-aligned high-end devices, lower-cost XR-based solutions, and dedicated public-safety and regional operator offerings. The report decodes these tactics into playbooks for both buyers and investors.
Strategic imperatives for 2026
-
Prioritize certification-aligned procurement: Map procurement timelines to certification windows rather than catalog lead times. The cancellation of certain advisory guidance means certification strategy must be an early input to RFPs.
-
Adopt hybrid deployment models: Combine fixed-base simulators for core type-rating activities with mixed-reality units for recurrent and mission-specific training to optimize capital intensity and utilization.
-
Lock in service agreements with clear upgrade paths: Given the value of scenario libraries and software updates, negotiate multiyear, outcome-based SLAs that include upgrade credits and predictable refresh cycles.
-
Invest in instructor competence and digital curriculum: Simulation ROI compounds when paired with optimized curriculum and instructor training—investing in both reduces seat-hour inflation and shortens qualification timelines.
-
Explore consortium approaches for distributed training: Regional operators can pool demand to justify higher-fidelity devices while keeping per-operator costs manageable.
-
Embed simulation strategy into fleet acquisition and sustainment planning: Decisions about aircraft variants, avionics suites, and mission modules should consider simulator compatibility and lifecycle support.
How PW Consulting’s report accelerates execution
Beyond market maps and competitive profiles, our report equips executives with operational tools: customizable demand models, procurement templates, certification roadmaps, and a prioritized list of vendor diligence questions. For private equity and corporate development teams, we provide an M&A playbook that identifies thinly served niches and value-creation levers—service expansion, software monetization, and geographic channel development—that have the highest projected IRR given market growth and concentration dynamics.
Conclusion — decision-ready intelligence for 2026
As the helicopter simulator market transitions from tactical displacement to strategic capability, 2026 will be a decisive year for those who align procurement, certification and commercial models with emergent technology and regulatory realities. With an industry CAGR of 6.98% underpinning continued expansion through 2032 and a market structure where the top vendors hold meaningful share, the winners will be those who convert macro growth into repeatable, service-driven revenue streams while de-risking certification and delivery timelines.
To access the full dataset, regional and application-level segmentation, proprietary vendor scoring, and the suite of decision-support tools described here, visit our official report page. The report intentionally preserves certain granular segment outputs for subscribers—ensuring you receive the depth required to execute with confidence in 2026.
For detailed analysis of this topic, please visit the official page: Helicopter Simulator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Steel Hollow Section Market Set to Grow at 5.2% CAGR, New Insight Report Reveals
By pmarketresearch, 2026-06-30
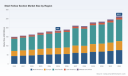
PW Consulting Releases Strategic Brief: Steel Hollow Section Market Outlook — A Practical Playbook for 2026 Decision-Making
PW Consulting today publishes a targeted industry brief built from our full Steel Hollow Section (HSS) Market study (base year 2025, historical 2020–2025, forecast 2026–2032). The brief synthesizes the market’s macro trajectory — a steady expansion from USD 150.0 Million in 2020 to USD 185.0 Million in 2025, with a forecast rise to USD 263.1 Million by 2032 at a 5.2% CAGR across the forecast window — and translates that trend into concrete choices procurement, operations, and corporate development teams should make in 2026. This release is a strategic “trailer”: we reveal frameworks, scenarios, and actionable guidance while preserving the granular segment-level tables and proprietary models for report subscribers.
Steel Hollow Section Market
Why this brief matters for 2026
-
Timing: The market is at an operational inflection point. Price movements and raw-material swings that began in late 2025 have carried into 2026, creating near-term cost pressure and supplier re-prioritization opportunities.
Steel Hollow Section Market -
Decision focus: Capital allocation, contract architecture, and decarbonization investments made in 2026 will determine competitiveness through the remainder of the decade as the market grows at a mid-single-digit CAGR.
Steel Hollow Section Market -
Risk management: The interplay between raw-material cost volatility, regulatory carbon benchmarks, and producer pricing behavior makes scenario-based procurement and hedging essential.
What’s inside the full report (practical deliverables)
We designed the report as an execution toolkit for commercial, supply chain, and corporate strategy teams. Highlights include:
-
Integrated demand-supply models with adjustable inputs for raw-material costs, HRC prices, and tariff scenarios to quantify margin pass-through under alternative market conditions.
-
Price-sensitivity dashboards and supplier scorecards that assess lead times, jumbo-size capability, quality certification coverage, and responsiveness — formatted for direct inclusion in RFPs and SRM platforms.
-
Operational playbooks: templates for indexed contract clauses, contingency inventory policies, and dual-sourcing decision trees calibrated to mid-cycle and stress scenarios.
-
M&A and partnership due-diligence packs: cash-flow stress tests, plant-level cost benchmarking, and integration checklists targeted at bolt-on acquisitions and capacity rationalization.
-
Carbon and compliance module: mapping of production emissions footprints, gap analysis vs. major procurement standards (including Buy Clean-type benchmarks), and practical decarbonization roadmaps.
-
Scenario annex: three forward-looking scenarios (Base, High-Price Shock, Low-Growth) with trigger thresholds, impact matrices, and recommended tactical responses for 0–12 month, 12–36 month, and 36+ month horizons.
Market dynamics shaping 2026 strategies
The HSS market entered 2026 under the influence of multiple forces:
-
Price momentum and supplier actions: Leading North American producers announced sequential price adjustments in late 2025 and early 2026. These moves have the practical effect of compressing buyer margins unless pass-through mechanisms or material substitutions are deployed.
-
Raw-material volatility: Recent market intelligence shows Heavy Melting Steel scrap prices in parts of the U.S. averaged USD 379 per ton in May 2026. Given the reliance of electric-arc furnace (EAF) HSS production on recycled scrap (approximately half of material input on average), this volatility translates directly into plant-level cost swings.
-
Upstream coil and trade dynamics: Hot-rolled coil price increases and import restrictions remain key drivers of late-2025/early-2026 price volatility. Tariff and trade-policy shifts continue to alter regional competitiveness and sourcing corridors.
-
Regulatory pressure on embodied carbon: Emerging procurement requirements — exemplified by a California benchmark of roughly 1.71 metric tons CO2e per metric ton for HSS — are creating a new supplier selection axis. Buyers will increasingly apply carbon performance as a commercial gate.
Competitive landscape: strategic read on key producers
The market is neither monopolistic nor atomized. Our concentration metrics show a top-three share that signals meaningful scale-based advantages for leading producers, while leaving room for regional specialists and niche-capability players to thrive. The report’s company profiles synthesize publicly available data, plant footprints, product breadth, and recent commercial signals; below we summarize strategic positions.
-
Nucor Corporation — A scale leader with diversified structural steel capabilities and multiple HSS manufacturing sites. Nucor’s ability to move large volumes, its product certification breadth, and its recent pricing activity underscore strong commercial discipline. For buyers, Nucor represents supply security and scale-driven negotiating pressure; for investors, the firm’s margin resilience is a bellwether for industry pricing.
-
Atlas Tube / Zekelman umbrella — Offers the broadest size range and jumbo HSS capacities. Their product breadth and recent price actions highlight tactical pricing leverage in projects requiring large-section or thick-wall offerings. Competitors face challenges on jumbo-size lead times; buyers requiring large sizes should prioritize early engagement.
-
Canadian HSS specialists (several regional producers) — Multiple Canada-based producers focus on ASTM/CSA-compliant products and regional service. These players are positioned to capture local infrastructure and construction demand where logistics and certification matter more than scale.
-
Regional welded-tube and boutique providers — Smaller facilities offering specific grades, welded construction, or niche tolerances provide important tactical options for OEMs and regional fabricators seeking customization or shorter lead times.
Strategically, the competitive landscape implies three near-term imperatives: secure trusted primary suppliers from large-scale producers for volume and resilience; maintain relationships with regional specialists for flexibility and niche sizing requirements; and monitor producer pricing announcements as leading indicators of market tightness.
Actionable 2026 playbook (what to do this quarter)
-
Implement indexed contracts with escalation triggers tied to a composite of scrap and HRC prices — not flat annual increases — to reduce basestock margin erosion when raw-materials spike.
-
Prioritize dual-sourcing for critical sizes and jumbo sections; assign minimum-viable stocking for long-lead SKUs where substitution is infeasible.
-
Run a 90-day rapid supplier audit for carbon intensity disclosure: require primary suppliers to report production CO2e and steelmaking route (EAF vs. BOF) to prepare for procurement standards and public-sector projects.
-
Adopt a tranche-based hedging approach: layer fixed-price contracts for near-term needs while retaining spot optionality for opportunistic buys as price volatility abates.
-
For M&A teams: prioritize tuck-ins that add geographic fill or unique technical capabilities (e.g., jumbo HSS, specialty wall thicknesses) rather than broad market share grabs which may dilute synergies.
-
Institute a quarterly “market-triggers” review: scrap price thresholds, tariff announcements, and major producer pricing actions that would shift capital-intensity or procurement posture.
How PW Consulting supports your 2026 agenda
PW Consulting pairs the published study’s empirical forecasting with hands-on implementation support. Our advisory services include rapid scenario workshops, supplier scorecard deployment, transaction due diligence, plant-level cost modeling, and carbon compliance strategies tailored to Buy Clean-style procurement. For organizations prioritizing resilience, margin protection, and sustainability in 2026, we offer focused engagements that translate the report’s models into executable plans within 4–8 weeks.
Note on data access: this brief highlights the study’s macro trajectory and strategic implications while withholding proprietary segment-level breakdowns, plant-level cost models, and full supplier scoring matrices. These granular elements are available exclusively in the full report and supporting data packages.
Next steps
-
Download the executive summary and request a scoped advisory session to receive the full dataset and a tailored scenario run for your supply chain.
-
Schedule a workshop with our sector team to convert the 2026 playbook into an operational plan aligned with your procurement cycles and capital calendar.
In a market growing at a steady mid-single-digit pace and facing concurrent cost, regulatory, and trade shocks, 2026 will reward firms that convert insight into disciplined contracts, carbon-aware sourcing, and targeted capacity investments. PW Consulting’s Steel Hollow Section Market study is designed to make those decisions faster, less risky, and more profitable. For access to the full report, appendices, and bespoke engagements, visit our website or contact our advisory desk.
For detailed analysis of this topic, please visit the official page: Steel Hollow Section Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Lithium Carbonate Market Poised to Expand Rapidly, Projected 14.3% CAGR Through 2032
By pmarketresearch, 2026-06-30
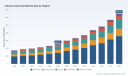
Lithium Carbonate Market: Strategic Imperatives for 2026 — PW Consulting Insights
Executive snapshot
PW Consulting’s latest Lithium Carbonate Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) is calibrated for executives making capital, procurement, and M&A decisions in 2026. The global market has expanded rapidly—rising from approximately USD 175.5 Million in 2020 to USD 255.75 Million in 2025—and is projected to continue on a steep trajectory to roughly USD 647.0 Million by 2032, reflecting a compound annual growth rate (CAGR) of 14.3% across the forecast horizon. All revenue references in this note are in USD Million.
Lithium Carbonate Market
Why this matters for 2026 decision-makers
- Market scale and growth velocity are now strategic determinants: procurement rhythm, offtake tenor, and capital allocation must reflect a market growing at mid-double-digit CAGR.
- Concentration dynamics are material to strategy: the top three and five participants account for a meaningful share of supply, creating both counterparty risk and strategic opportunity for new entrants and downstream consumers.
- Regulation and traceability are shifting the shape of competitiveness: compliance timelines tied to EU and regional rules are compressing implementation windows for suppliers and processors.
What PW Consulting’s report delivers
- Transparent, auditable supply-demand modelling calibrated to 2020–2025 history and 2026–2032 scenarios (upside, base, downside) with configurable inputs for price, feedstock yields, and processing lead times.
- Practical playbooks for offtake structuring, tolling agreements and hedging strategies that optimize working capital without surrendering optionality.
- Capital and operating cost benchmarks for spodumene-based and brine/DLE conversion routes, plus sensitivity analysis for reagent and energy cost volatility.
- Regulatory impact matrix translating EU Battery Regulation, Critical Raw Materials Act benchmarks, and regional permitting trajectories into decision triggers for project sanctioning.
- Competitive and counterparty risk heatmaps—profiles of incumbent producers, emerging entrants, and technology providers with scenario-driven strategic options (partner, buy, or out-licence).
- ESG and traceability due-diligence checklists that map to procurement requirements entering force in 2026–2028.
Supply-side dynamics and strategic implications
The market’s growth is a supply-and-demand story played out across multiple project archetypes: brine operations with long lead times but low variable costs, hard-rock spodumene conversions with modular expansion profiles, and new direct lithium extraction (DLE) entrants offering faster ramp but execution and scalability risk. Recent project developments underscore the heterogeneity of supply pathways: established lithium chemicals producers have brought incremental chloride and carbonate conversion capacity online; greenfield hard-rock projects are targeting late-2027 mechanical completions; and DLE pilot-to-commercial transitions have started generating first shipments.
Lithium Carbonate Market
Strategically, buyers and financiers must adopt a differentiated sourcing approach: secure staggered offtakes across technology types, prioritize counterparties with proven traceability and regulatory conformance, and structure contracts that allow optionality as new, lower-cost volumes come online. For suppliers, the priority is managing ramp risk, ensuring product spec consistency for battery-grade applications, and advancing downstream integration to capture margin.
Lithium Carbonate Market
Demand drivers and resilience of growth
EV adoption curves, grid-scale energy storage deployments, and the industrial demand for high-purity carbonate underpin the base-case CAGR. Beyond headline demand, regulatory push—particularly traceability and human-rights-related supply chain standards—will reshape procurement, favouring vertically integrated or well-certified suppliers. Demand elasticity to price is non-linear: short-term spikes induce substitution and recycling acceleration, while sustained price levels spur incremental investment into new feedstock conversion and recycling facilities.
Competitive landscape: Signals and strategic takeaways
The market exhibits moderate concentration—our analysis shows the top three firms supply a majority position in the market, while the top five extend that dominance. This creates several tactical positions for investors and downstream players:
- Incumbent integrated producers retain strategic advantages through scale, downstream conversion, and established customer relationships. Their ongoing capacity projects and joint ventures are designed to secure long-tenor contracts with OEMs and energy utilities.
- New large-scale greenfield projects are strategically important but timing- and capital-sensitive; public financing and government loan guarantees are shaping which projects reach first production.
- DLE and other processing innovations are a double-edged sword: they can lower cost and environmental footprint quickly if proven at scale, but they also introduce technical execution risk that can impact timelines and product specs.
Key corporate movements we track (illustrative, non-exhaustive):
- Large integrated manufacturers have expanded chloride and carbonate capacity while forging JVs to secure brine feedstocks and accelerate conversion capacity.
- Primary brine operators continue to scale, with some achieving key industry certifications and moving toward broader market participation for battery-grade products.
- North American projects have attracted public financing support focused on onshore processing to meet domestic content and critical minerals objectives.
Regulatory, certification and geopolitical headwinds
Regulatory drivers are increasingly binding. The European Battery Regulation and Critical Raw Materials Act introduce concrete thresholds for extraction, processing and recycling that buyers must meet—effective compliance dates are shaping capex and sourcing decisions now. Certification programs and on-site audits (already achieved by several operations) materially affect market access with tier-one OEMs. Additionally, public-sector financing and tariff policy are reshaping project economics for onshore processing capacity in major consuming regions.
Actionable plays for 2026 — prioritized
- Secure multi-year, flexible offtake contracts that combine fixed-volume anchors with options and index-linked tranches to balance price protection and upside participation.
- Diversify feedstock and geography across brine, spodumene conversion, and recycling sources to mitigate single-sourcing and geopolitical concentration risks.
- Invest in traceability and ESG reporting capabilities now—meeting imminent regulatory and OEM procurement thresholds will be a de facto market access requirement.
- Partner with validated DLE and electrolytic process providers on proof-of-concept pilots to shorten time-to-market for lower-footprint supply.
- Use staged, milestone-linked funding structures for greenfield projects to de-risk execution and align vendor incentives with throughput and product-spec performance.
Report methodology and what you’ll find inside
Our modelling combines bottom-up plant-level capacity build schedules and top-down demand forecasts by end-application, cross-checked against trade flows and inventory cycles. Scenario outputs allow users to re-run sensitivities against price, feedstock yield and ramp profiles. The report includes a negotiable contract template library, an ESG due-diligence pack mapped to major buyer requirements, and an interactive executive dashboard designed for Board and investment committees.
The trailer principle — what’s intentionally withheld here
This release is a strategic trailer: it conveys the core directional findings, the operational frameworks, and the strategic implications executives need to know in 2026. To preserve the utility of the report for clients and to avoid substituting for bespoke advisory work, we have intentionally omitted granular segmented tables, detailed regional and application share breakdowns, and our full unit-cost curves. Those proprietary datasets—essential for pricing negotiations, project sanction, or acquisition diligence—are available in the full report and advisory deliverables.
Next steps for leaders
- Procurement heads: request a tailored sensitivity run from PW Consulting to stress-test your offtake portfolio against our three scenarios.
- Investors: use our supply-side execution scorecard to triage target projects—prioritize nodes with proven permitting and commercialization pathways.
- OEMs and battery manufacturers: accelerate supplier certification pilots with vertically integrated producers and DLE providers to lock in compliant supply.
PW Consulting’s Lithium Carbonate Market report is designed to move organizations from inference to action: equipping Boards, strategy teams, and transaction desks with the models, playbooks, and regulatory mapping needed to make high-stakes decisions in 2026. For access to the full dataset, scenario models, and customized advisory options, consult the report landing page or contact our industry practice.
For detailed analysis of this topic, please visit the official page: Lithium Carbonate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Report: PW Consulting Forecasts Content Moderation Market to Reach USD 28.45 Billion by 2032, Growing at a 13.42% CAGR
By pmarketresearch, 2026-06-30
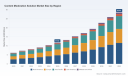
PW Consulting Releases 2026 Content Moderation Solution Market Report — Strategic Imperatives for Enterprise Leaders
PW Consulting today publishes its Content Moderation Solution Market report (base year: 2025), a deep-dive industry study designed to inform C-suite and product leaders as they set trust & safety, platform compliance, and risk mitigation priorities for 2026. The market we track has more than doubled in scale since 2020 and is forecast to continue expanding at a compound annual growth rate of 13.42% through 2032, reflecting the convergence of high-volume user-generated content, regulatory pressure, and rapid adoption of multimodal AI tooling. Our study combines rigorous market sizing, scenario-based forecasts for 2026–2032, and operational guidance intended to be put into practice within the next 12–18 months.
Content Moderation Solution Market
Why 2026 Is a Turning Point
-
Regulatory inflection: Global policy initiatives — from the EU’s Digital Services Act and the UK’s Online Safety framework to recent statutes and proposals in major markets — are elevating platform obligations and accelerating procurement of auditable moderation solutions. These mandates make 2026 a practical deadline for many enterprises to upgrade governance and reporting capabilities.
Content Moderation Solution Market -
Technology inflection: Advances in generative and multimodal AI have materially increased both the scale and complexity of moderation workloads. Real-time video, immersive environments, and synthesized audio introduce latency, provenance, and intent-analysis challenges that were rare in previous waves of UGC growth.
Content Moderation Solution Market -
Commercial inflection: Buyers are shifting from point-product purchases to integrated Trust & Safety programs that combine automated triage, human-in-the-loop review, and post-moderation remediation workflows. This shift is creating new service models and supplier specialization.
Key Findings and Strategic Signals
-
Market trajectory: From a mid-single-digit billion-dollar industry in 2020, the content moderation market expanded significantly through 2025 and is expected to accelerate further as platforms scale cross-border services and immersive content formats multiply.
-
Consolidation with room for specialists: The market exhibits meaningful concentration at the top (our concentration metrics show a dominant share among the leading firms alongside a healthy long tail of specialized providers), creating procurement trade-offs between scale, language coverage, and vertical expertise.
-
Hybrid models prevail: The most resilient programs combine machine-led filtering and fast triage with geographically distributed, linguistically capable human review teams—particularly where policy nuance or legal risk is high.
-
Compliance as a differentiator: Vendors and buyers that can demonstrate auditable, provenance-aware workflows (data residency, explainability, retention policies) are gaining a premium in enterprise procurement conversations.
-
Operational risk: Labor sourcing, platform outages, adversarial content manipulation, and policy disputes are rising operating costs; capacity planning and supplier diversification are now central to enterprise resilience planning.
Competitive Landscape: How Leading Players Are Positioning
Our competitive analysis synthesizes corporate strategy, product roadmaps, recent deal activity, and public announcements. Below are concise profiles and implications for buyers and partners.
-
iMerit (San Jose, CA) — iMerit continues to emphasize AI data workflows and domain-focused moderation, with deep operational capabilities for gaming and platform safety. Their positioning is attractive for enterprises requiring customized annotation and moderation pipelines for complex interactive content.
-
WebPurify (San Francisco, CA) — Now part of a larger customer-experience and moderation group following acquisition activity, WebPurify’s hybrid AI + human approach remains well-suited to multimedia UGC moderation where modular deployments and rapid time-to-value matter.
-
Teleperformance (Paris, France) — Teleperformance has expanded its Trust & Safety portfolio with AI-driven triage and multilanguage operations. For global platforms seeking scale and multi-regional coverage, large BPOs like Teleperformance offer integrated program management and regulatory-compliance services.
-
Accenture (Dublin, Ireland) — Accenture packages human-in-the-loop moderation into broader digital transformation and risk advisory services, positioning itself for enterprise deals that require technical integration, governance frameworks, and transformation roadmaps.
-
ModSquad (USA) — A pioneer in outsourced moderation and community management, ModSquad leverages on-demand multilingual talent and flexible engagement models, which appeals to platforms with variable surge requirements and nuanced community standards.
-
Concentrix (Bellevue, WA) — Concentrix’s trust & safety offerings emphasize compliance and validation workflows across immersive environments and multiple languages; they are a contender where regulatory controls and audit trails are procurement priorities.
-
Enshored (Pasig City, Philippines) — Enshored focuses on scalable moderation teams for e-commerce and SaaS platforms, highlighting operational scalability and language coverage that are important for customer-facing marketplaces.
-
Gcore (Luxembourg) — Gcore is advancing real-time, AI-enabled moderation capabilities and spotlighting sovereign infrastructure themes; recent events they hosted emphasized the role of sovereign AI and infrastructure in meeting regulatory and reliability requirements.
Recent Industry Moves That Matter
-
Product launches and community events have spotlighted sovereign AI infrastructure and real-time moderation as differentiators for vendors targeting regulated markets.
-
Acquisitions and service integrations are consolidating capability stacks—buyers should expect fewer standalone point solutions and more bundled offerings that combine consulting, platform integration, and managed services.
-
Regulatory updates across the EU, UK, India, China, and the United States are raising baseline compliance requirements and increasing the need for auditable workflows and cross-border operational models.
What the Report Contains — Operational Tools, Not Just Theory
PW Consulting’s report is structured to be directly operational for procurement, security, product, and legal teams. Key deliverables include:
-
Transparent market sizing and scenario-based forecasts (2026–2032) with methodology notes and sensitivity testing so executives can stress-test budget and headcount plans.
-
Decision-ready buyer’s playbook: RFP templates, vendor scorecards, procurement evaluation matrices, and pilot design checklists tuned for multimodal content and regulated jurisdictions.
-
Vendor landscape and capability mapping: qualitative profiles, go-to-market vectors, and strategic fit assessments (note: fine-grained segmentation tables and per-vendor financial splits are available in the full report).
-
Implementation blueprints: recommended architectures for hybrid AI + human moderation, data flows that support audit and explainability, and staffing models for surge and escalation handling.
-
Regulatory compliance matrix and data-residency playbook: recommended controls, logging and retention patterns, and workflows to support transparency reporting obligations.
-
Risk register and mitigation plan: adversarial content scenarios, supply-chain resilience options, and cost-of-failure estimates to inform executive-level risk tolerance discussions.
Five Strategic Moves for Executive Teams in 2026
-
Commit to a hybrid architecture — Invest in automated triage for scale, but retain adjudicative human capacity for edge cases and policy nuance. Prioritize explainability and logging in every automation purchase.
-
Operationalize compliance — Map obligations by jurisdiction, bake reporting requirements into moderation workflows, and codify escalation paths to legal and public policy teams.
-
Modularize your stack — Adopt a composable approach that separates detection, classification, human review, and appeals so you can swap best-of-breed components without wholesale replatforming.
-
Design for surge and adversary behavior — Build capacity buffers, supplier diversification plans, and automated throttling to cope with episodic content storms and coordinated manipulation campaigns.
-
Make procurement strategic — Use comprehensive vendor scorecards and staged pilots to validate performance on latency, accuracy, language coverage, and compliance before scaling commitments.
Methodology and Report Integrity
The study combines bottom-up supplier intelligence, primary interviews with buyers and providers, regulatory text analysis, and a scenario-driven forecasting model calibrated against historical data through 2025 (base year). We disclose concentration metrics and market-wide trajectories while preserving vendor-level commercial confidentiality; full datasets and interactive dashboards are included in the paid report package.
Next Steps: Accessing the Full Intelligence
PW Consulting’s Content Moderation Solution Market report is intentionally structured as a decision support tool. This news release surfaces critical strategic signals and operational recommendations while withholding granular segmentation tables and vendor-level financial splits that are included in the full deliverable. For procurement teams, product leaders, and policy strategists who must translate foresight into budgets and programs in 2026, that full dataset and the included templates will materially shorten time-to-action.
To obtain the complete report, interactive datasets, and buyer toolkits, please visit PW Consulting's publications page or contact our research sales team to arrange an enterprise briefing. Our analysts are available for briefings and tailored advisory engagements to convert the report’s findings into a concrete 12–18 month implementation roadmap.
For detailed analysis of this topic, please visit the official page: Content Moderation Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Shot Peening Machine Market to Reach USD 1,125.83 Million by 2032, Growing at a 5.7% CAGR from 2025's USD 755.2 Million
By pmarketresearch, 2026-06-30
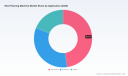
Shot Peening Machine Market: Strategic Imperatives for 2026 — A PW Consulting Report Preview
As manufacturers confront an inflection point in surface-treatment technology, PW Consulting’s latest market study on Shot Peening Machines distills the strategic intelligence executives need to make high‑stakes 2026 decisions. Anchored on a 2025 base year and projecting the industry through 2032, our analysis shows a resilient market expanding at a 5.7% compound annual growth rate (CAGR). From a market size of approximately USD 755 million in 2025, the sector is forecast to progress toward the billion‑dollar threshold by the end of the decade — a trajectory driven by automation, stricter aerospace and automotive quality regimes, and the evolution of peening techniques tied to electrification and lightweighting.
Shot Peening Machine Market
Why this report matters for 2026 planning
-
Operational investment decisions are time sensitive. Capital allocations made in 2026 will determine manufacturing posture for the rest of the decade; our base‑year benchmarking and forecast runway provide the forward‑looking economics to justify or defer those investments.
Shot Peening Machine Market -
Regulatory and standards dynamics are evolving. Technical committees and OEM stakeholders are actively updating shot‑peening specifications and traceability requirements — changes that will materially affect line qualification, audit readiness, and supplier selection starting in 2026.
Shot Peening Machine Market -
Technology is reframing total cost of ownership. Intelligent automation (robotic vision, multi‑axis controls, real‑time monitoring) is shifting the economics from labor to software and services; our study quantifies the adoption implications across purchase price, throughput, and compliance risk.
-
Market concentration is meaningful for strategy. With the top industry players accounting for a material share of supply, tactical partnerships, aftermarket service capabilities, and certification credentials are differentiators for both buyers and sellers.
Core trends shaping the market in 2026
-
Automation and intelligent control: The industry is accelerating the integration of robotic systems, programmable tool changers, and machine‑vision feedback loops. These upgrades reduce operator dependency, improve repeatability, and enable traceable process logs required by tier‑1 aerospace and automotive customers.
-
Traceability and compliance: Recent standardization discussions and committee activity indicate a tightening of process traceability expectations. Equipment that supports real‑time monitoring and audit‑grade data capture is now a procurement priority for regulated segments.
-
Service and consumables as revenue drivers: As hardware commoditizes in some subsegments, suppliers are increasingly monetizing maintenance, certification services, and consumable supply chains (including steel shot), creating attractive recurring revenue streams.
-
Geographic and vertical demand shifts: Demand continues to be anchored by aerospace and automotive markets, but electrification, transmission design changes, and industrial maintenance cycles are creating new peening use cases and volume pockets.
-
Supply chain pressure points: Raw material dynamics — notably the continued dominance of steel shot for high‑hardness applications — and logistics complexity are influencing lead times and working capital considerations for buyers and OEMs alike.
What’s inside the report (practical, operational deliverables)
-
Proprietary market model: A consolidated historical series (2020–2025) and a seven‑year forecast (2026–2032) with scenario sensitivity for demand shocks, regulatory acceleration, and technology substitution. The model is delivered with editable inputs so teams can re‑run scenarios aligned to their strategic assumptions.
-
Decision frameworks: Capital budgeting templates that map purchase options (manual vs. semi‑automated vs. fully automated) to expected throughput, lifecycle maintenance, and compliance costs — enabling a quick, defensible CapEx approval package.
-
Vendor scorecards and procurement playbooks: A repeatable supplier evaluation matrix covering technical fit, service footprint, certification status, total cost of ownership, and aftermarket performance. Includes negotiation levers and sample RFP language tailored for different risk profiles.
-
Technology due diligence checklist: A practical diagnostics toolkit for validation of new systems — from multi‑axis kinematics to real‑time monitoring integrity — and a blueprint for on‑site acceptance testing and capability proofs.
-
Implementation roadmaps and KPIs: Phase‑based rollouts for retrofits or greenfield lines, with target metrics for throughput gains, quality yield, touch‑time reduction, and payback timelines under conservative, base, and aggressive adoption scenarios.
-
Primary research and case studies: Plant‑level case studies and buyer interviews with major OEMs and tier suppliers, providing on‑the‑ground context for adoption barriers, training needs, and service expectations.
Competitive landscape — who matters and why
The Shot Peening Machine market combines niche specialists, long‑standing OEMs, and cost‑focused manufacturers. Our competitive analysis profiles the leading vendors and distills their strategic postures, differentiators, and likely plays through 2026:
-
Wheelabrator Group (UK): A leader in automated systems with deep aerospace and heavy‑industry credentials. Their strength lies in integrated turnkey solutions and aftermarket service networks tailored to demanding, certified processes.
-
Empire Abrasive Equipment Company (Buffalo, NY): Known for precision, conventional and CNC peening systems. Recent corporate emphasis on certification and engineering depth positions Empire for partnerships with quality‑conscious OEMs.
-
Rösler Oberflächentechnik GmbH (Germany): High‑performance systems for complex components; demonstrated traction in EV drivetrain applications through targeted system implementations.
-
Guyson Corporation and Sinto America: Strong in aerospace‑grade cabinets and systems, with reputational strength in process documentation and compliance support.
-
Pangborn Group and other established OEMs: Offer custom equipment and integration services for forming, peening, and finishing — attractive to customers requiring hybrid process lines.
-
Progressive Surface and Engineered Abrasives (United States): Innovators in intelligent automation and robotic integration, delivering integrated vision and tool‑changer capabilities that reduce labor intensity and improve traceability.
-
Chinese OEMs (multiple): Competitive on price and volume for industrial applications; increasingly active in export markets for heavy industrial peening where cost is the primary procurement criterion.
Market concentration metrics in our analysis underscore that a relatively small set of providers controls a sizeable share of supply — a structural feature that shapes bargaining power, aftermarket economics, and M&A interest. Equipment certification, field support density, and data‑capability are the three axes on which suppliers are being evaluated more than ever.
Recent developments and their strategic implications
-
Product innovation: The introduction of next‑generation multi‑axis peening machines with built‑in real‑time monitoring has immediate implications for aerospace and high‑value automotive parts, shortening qualification cycles and enabling tighter process control.
-
System deployments at academia and labs: Strategic installations at research institutions create cross‑pollination opportunities — suppliers gain validation and visibility, while OEMs get access to early adoption learnings.
-
Certification milestones: Suppliers investing in shot‑peening certification and staff training are increasingly preferred partners for OEMs with stringent audit requirements, reducing supplier switching costs and accelerating purchase cycles.
Actionable strategic recommendations for 2026
-
Prioritize traceable automation investments: For regulated segments, select platforms with embedded data capture and audit‑grade monitoring as a minimum requirement. The incremental CapEx is often recouped through reduced audit failures and higher first‑pass yields.
-
Use pilots to derisk rollout: Implement a modular pilot (single cell) that replicates production complexity and ties into enterprise data systems; baseline KPIs for a one‑quarter proof of value before multi‑cell rollouts.
-
Reassess supplier scorecards to include certification and service SLAs: Wherever uptime and documented process control matter, service footprint and certification trumps headline price.
-
Hedge raw‑material and consumable exposure: Locking multi‑year agreements on consumables supply and considering vendor‑managed inventory can smooth production risk and reduce working capital volatility.
-
Explore partnerships and bolt‑ons for digital services: For OEMs, capturing aftermarket service revenue from monitoring, predictive maintenance, and consumables supply will be a critical margin lever.
-
Build a talent and certification roadmap: Invest in operator certification and engineering training aligned to updated standards to shorten qualification time and reduce quality risk.
How PW Consulting supports your 2026 decisions
-
Custom quantification — we adapt our forecast model to your production footprint, capital plan, and compliance timelines so you can model the exact ROI of equipment choices.
-
Supplier due diligence — deep technical audits, reference checks, and on‑site acceptance test scripts to minimize procurement risk and accelerate installation timelines.
-
Implementation acceleration — program management and change‑management playbooks to translate pilot successes into plantwide performance improvements while protecting ongoing production.
PW Consulting’s Shot Peening Machine Market report blends market‑grade forecasting with the operational playbooks procurement, operations, and engineering teams need to act in 2026. The analysis demonstrates where to deploy capital, how to mitigate regulatory and supply risks, and which supplier capabilities to prioritize — while preserving the granular datasets and segment breakdowns required for transaction‑level decisions. To access the full quantitative datasets, supplier scorecards, and editable forecast model, please visit our report page and download the complete study.
For detailed analysis of this topic, please visit the official page: Shot Peening Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tailgating Detection Market Set to Reach USD 92.58 Million by 2032, Growing at a 7.4% CAGR — PW Consulting
By pmarketresearch, 2026-06-30
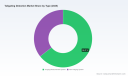
Tailgating Detection Market 2026: Strategic Signals for Secure Entry Investment
Executive Snapshot
As enterprises recalibrate physical and cyber security postures for a hybrid world, tailgating detection has moved from a niche add-on to a core component of modern access control. PW Consulting’s latest market study (base year 2025) shows how a focused convergence of AI-driven video analytics, multi-sensor fusion, and cloud-native access platforms is reshaping how organizations prevent unauthorized entry. The market expanded significantly across 2020–2025 and, propelled by ongoing digitalization and regulatory momentum, is forecast to continue expanding through the 2026–2032 window at a compound annual growth rate of 7.4%.
Tailgating Detection Market
Why 2026 Is a Decisive Year for Enterprise Decision-Makers
-
Procurement cycles are shortening; organizations want deployable solutions that demonstrate measurable reductions in unauthorized entries and clear integration paths into broader building management systems.
Tailgating Detection Market -
Regulatory and standards activity is converging on tailgating detection as a recognized security control in biometric and access-control frameworks, increasing mandatory requirements in public tenders and critical infrastructure projects.
Tailgating Detection Market -
Vendors are moving rapidly from proof-of-concept to operationalized offerings—integrated appliances, edge AI, and cloud orchestration are now table stakes for sustainable deployments.
Market Trajectory: What the Numbers Tell Us
PW Consulting’s analysis highlights a clear maturation curve. The market has scaled materially since 2020 and reached a meaningful base by 2025, reflecting both new deployments and retrofit activity. Our forecast to 2032 shows continued expansion, underscoring persistent buyer demand and steady technology refresh cycles. Importantly, market concentration is non-trivial: the top three vendors account for a majority share, and the top five command a pronounced share of industry revenue—an indicator of vendor leadership and consolidation trends that buyers must factor into strategic sourcing decisions.
Practical Value of the Report for 2026 Decision Cycles
-
Investment Prioritization: Our report maps where tailgating detection delivers the fastest risk-adjusted returns across enterprise classes—supporting capital allocation decisions for 2026 budgets without overcommitting to one technology strand.
-
Vendor Selection Playbook: We distill vendor strengths and fit-for-purpose evaluations, enabling procurement teams to shortlist solutions based on operational constraints (throughput, environmental conditions, integration points) rather than marketing claims.
-
Deployment Risk Matrix: The report provides an execution-oriented checklist—covering site surveys, sensor placement, network and bandwidth planning, and staged pilot designs—to reduce implementation surprises.
-
Compliance and RFP Language: We supply templated language and requirement constructs that align with current standards activity and federal procurement expectations, helping procurement teams embed tailgating detection requirements into RFPs that pass legal and accessibility reviews.
-
ROI & TCO Models: Built-in financial models reflect acquisition, integration, maintenance, and staffing impacts—critical for 2026 business cases that must compete with competing digital transformation projects.
Competitive Landscape: Who Matters and Why
The field encompasses global systems integrators, camera vendors, access-control platform providers, and niche analytics specialists. Leading companies combine hardware innovation with deep analytics and access-control integration. Key vendor profiles in the report highlight practical differentiation vectors such as sensor modality (ceiling-mounted 3D, infrared, microwave), edge AI capabilities, and integration maturity with access management suites.
-
Optex Co., Ltd. – Known for ceiling-mounted 3D virtual modeling and human-tracking sensors that emphasize real-time detection accuracy at busy entry points.
-
Detex Corporation – Offers interlock-centric systems with one-person-rule enforcement tailored to high-security installations requiring deterministic control behavior.
-
ACTi Corporation – Positions AI-powered people counting tightly with access control platforms to enable automated incident identification and alerting.
-
Integrated Design Limited (IDL) and FASTCOM Technology – Deliver sensor-fusion and analytics stacks for perimeter and entry-point protection across commercial and secured facilities.
-
Alcatraz AI, Openpath, Kisi, and others – Focus on cloud-native or embedded-AI solutions that simplify deployment and reduce incremental hardware needs.
-
Major systems players (Honeywell, Johnson Controls, Axis, Panasonic, Genetec) – Provide tailgating detection as a capability within broader building and security platforms, appealing to enterprises seeking single-vendor operational simplicity.
Each vendor cluster brings trade-offs: specialized analytics vendors often deliver superior detection performance in constrained scenarios, while platform vendors offer stronger lifecycle management and integration economies. The report includes a practical vendor-fit framework to help decision-makers choose the right approach for their risk profile.
Recent Technology and Market Developments
-
Product feature cadence is accelerating: Several vendors released or enhanced tailgating features in 2025–2026, including AI-based multi-object line-crossing detection and simplified troubleshooting tools that lower operational friction during rollout.
-
Sensor fusion is mainstreaming: Integrations across video analytics, infrared, microwave, and ceiling-mounted 3D sensors are increasingly used to reduce false positives in high-traffic and cluttered environments.
-
Procurement expectations have shifted: Federal and municipal RFP language now often requires explicit tailgating detection capabilities and ADA-compliant implementations, raising the bar for vendor solutions.
Regulatory and Operational Dynamics to Watch
Standards work and regulatory guidance are converging to make tailgating detection a recognized component of access security architectures. Developments in international standards and national guidance now reference tailgating detection within biometric fusion and network-system frameworks—implications that extend to procurement, acceptance testing, and auditability. In parallel, implementation cost remains a visible constraint: hardware, software, and professional services can create material first-cost hurdles. The report provides mitigations and phased procurement approaches for 2026 that balance security gains against financial and operational constraints.
Strategic Recommendations for 2026 Planning
-
Adopt a staged procurement strategy: Begin with targeted pilots in representative sites (peak ingress, mixed lighting, and staffing variance) and use telemetry from pilots to refine spec and scale-up plans.
-
Prioritize integration over feature-chasing: Ensure that chosen solutions integrate with existing access-control, building automation, and incident-response workflows. Integration risk drives most lifetime costs.
-
Insist on measurable acceptance criteria: Define objective KPIs for tailgating reduction, false alarm rates, and mean time to detect/alert to quantify vendor performance.
-
Evaluate vendor ecosystems: Favor vendors with proven partnerships across camera manufacturers, access-control platforms, and systems integrators to reduce single-source dependency.
-
Budget for operational change: Training, policy changes, and SOC playbook updates are necessary to extract value from new detection capabilities—allocate resources accordingly in 2026 budgets.
-
Embed privacy and AI governance: Ensure solutions provide explainability, audit logs, and data minimization controls appropriate to local privacy rules and procurement requirements.
What the Full Report Contains (Practical Components)
PW Consulting’s full Tailgating Detection Market report is built to be actionable. Highlights include our market-sizing methodology, vendor scorecards and technology profiles, scenario-based ROI and TCO models, a procurement-ready RFP annex, pilot design templates, integration and network planning guides, and regulatory alignment maps. The report also includes an incident-playbook template aligned with SOC operations and audit-ready acceptance testing checklists to shorten time-to-value post-purchase.
Final Thought: Positioning for 2026 and Beyond
Tailgating detection is no longer a point-solution novelty; it is evolving into a required capability within security architectures where controlled entry is a risk vector. For organizations making 2026 investment choices, the decision calculus is clear: favor solutions that demonstrably reduce unauthorized entries, integrate cleanly with operational systems, and provide a transparent path to measurement and governance. PW Consulting’s report equips decision-makers with the analytical backbone and practical tools needed to make those choices with confidence.
Next Steps
For security leaders preparing 2026 budgets and technology roadmaps, PW Consulting’s full report provides the detailed segment-level data, vendor benchmarking, and procurement templates that underpin defensible investment decisions. Visit our website to access the full report and supporting tools, or contact our advisory team for a tailored briefing aligned to your facilities and risk profile.
For detailed analysis of this topic, please visit the official page: Tailgating Detection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cloth Diapers Market Set to Expand at 11.85% CAGR Through 2032
By pmarketresearch, 2026-06-30
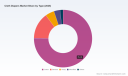
Cloth Diapers Market 2026: Strategic Intelligence for Decision-Makers — Preview of PW Consulting’s Comprehensive Report
As global retailers, manufacturers, and investors prepare their 2026 playbooks, the cloth diapers market is emerging as a high-conviction opportunity defined by durable consumption trends, material-driven differentiation, and accelerating consolidation. PW Consulting’s latest market study — based on a 2025 base year, five years of historical trend analysis (2020–2025), and a forward-looking forecast horizon to 2032 — synthesizes quantitative projection and practical guidance to convert macro signals into executable strategy. At the top line, the global market was valued at USD 215.0 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 11.85% through the 2026–2032 forecast window, reaching roughly USD 345 Million by 2032. This preview outlines the high-level implications for 2026 decision cycles while preserving the report’s proprietary segment-level intelligence for readers who access the full study.
Cloth Diapers Market
Why 2026 Is a Strategic Inflection Point
Multiple forces converge in 2026 to reframe competitive dynamics. First, regulatory clarity is arriving: new guidance from the Consumer Product Safety Commission requires permanent tracking labels and prescriptive testing standards for cloth diapers. Compliance timelines will drive near-term product re-engineering, lab testing budgets, and supply chain audits. Second, premium natural materials — notably organic cotton, hemp, and bamboo blends — have moved from niche to mainstream in developed markets. These materials underpin higher ASPs and new positioning opportunities but increase exposure to raw-material sourcing constraints and freight volatility. Third, consumer behavior continues to tilt toward reusable solutions for environmental and lifetime-cost reasons; adoption momentum is particularly strong among multi-child households and eco-conscious cohorts. Finally, industry structure is shifting: a fragmented supplier base is encountering a wave of pragmatic consolidation and product innovation, forcing incumbents and challengers to re-evaluate scale, vertical integration, and channel strategies.
Cloth Diapers Market
What the PW Consulting Report Delivers (Practical, Executable Content)
-
Integrated market sizing and outlook — top-line annual estimates and scenario modeling across the forecast window (2026–2032) with sensitivity to supply-side and policy shocks.
Cloth Diapers Market -
Actionable growth playbooks — go-to-market templates for premium, value, and private-label strategies, with customer acquisition cost benchmarks and early ROI timelines.
-
Product and material intelligence — comparative analysis of cotton, bamboo, hemp, and engineered microfiber systems, highlighting cost structures, expected margins, and consumer willingness-to-pay differentiators.
-
Supply chain risk matrix — end-to-end mapping of raw-material sources, freight exposure, and contingency levers that preserve margin under import disruptions.
-
Regulatory compliance roadmap — prioritized investments and testing sequences to meet new safety and traceability mandates while minimizing market disruption.
-
Competitive playbook — profiles of the industry’s active players, recent M&A and product moves, and defensive/offensive options for market entrants and incumbents.
-
Financial and KPI toolkit — pricing tests, unit-economics templates, and channel-level contribution analysis that executives can deploy within 90 days.
To preserve the report’s value as an actionable subscription product, granular regional and application-level breakdowns — including per-region volumes and product-type shares — are summarized in the full report and online data annex. This release intentionally foregrounds strategic implications while directing practitioners to the full dataset for operational planning.
Competitive Landscape: Read Acrosss and Strategic Implications
The cloth diapers market remains structurally fragmented; our concentration metrics indicate a market where top firms collectively control a modest share of global revenues, leaving substantial room for regional specialists and private-label players. Recent corporate actions underscore two clear trends: consolidation to capture scale and product breadth, and targeted product innovation aimed at leak protection and consumer convenience.
-
Kanga Care (USA) — With its acquisition of GroVia in July 2025, Kanga Care has accelerated a consolidation pathway that combines proprietary pocket systems with all-in-one solutions. For competitors, the strategic implication is that scale enables broader SKU portfolios and cross-selling across retail and subscription channels; smaller brands must increasingly choose between specialization or partnering with consolidators.
-
GroVia (USA) — Historically focused on modern AIO systems, GroVia’s integration signals prioritization of lifecycle customer value and subscription-friendly designs. Retail buyers should expect bundled offerings that bridge full-price and demo-friendly sampling.
-
Charlie Banana, Thirsties, BumGenius, Blueberry, Flip, Rumparooz — These recognized innovation leaders continue to defend market niches through product differentiation (eco-friendly, stay-dry systems, hemp/bamboo blends, and hybrid models). Their playbooks emphasize performance claims, channel diversification, and community-driven marketing.
-
Ecoable and Alvababy — Regional specialists and wholesale-oriented players that represent alternative routes to scale: private label and wholesale distribution into discount and value channels. Their models demonstrate how volume-focused supply chains and cost-driven sourcing can coexist with premium product narratives.
For strategic buyers and partners, the competitive map suggests three prudent approaches: (1) pursue tuck-in acquisitions to rapidly augment product breadth and quality credentials, (2) invest in proprietary material science or testing capabilities to meet regulatory standards ahead of competitors, or (3) commit to channel specialization where vertical relationships and logistics efficiencies produce durable margin advantages.
Industry Dynamics to Monitor for 2026 Planning
-
Regulatory compliance costs: The CPSC’s new labeling and testing requirements will introduce fixed compliance costs — prioritization and early certification will be competitive differentiators in 2026.
-
Raw-material price pressure: Premium organic fibers command pricing power that supports margin expansion but raises procurement volatility; firms should hedge exposure and qualify alternate suppliers.
-
Freight and logistics: Continued supply-chain sensitivity for components imported from Asia impacts distributors in North America and Europe; near-shoring and consolidated shipping lanes will become common tactical responses.
-
Consumer adoption patterns: Adoption is increasingly driven by sustainability messaging and lifecycle-cost narratives; conversion funnels should measure both ecological intent and cost-per-child economics.
Practical Strategic Moves for 2026
-
Product roadmap: Accelerate certification-ready versions of flagship SKUs; focus R&D on leak protection and fabric performance that align with mandated testing protocols.
-
Sourcing and margin protection: Secure multi-supplier agreements for organic fibers, incorporate freight pass-through language in channel contracts, and evaluate buffer inventory for critical components.
-
M&A and partnerships: Screen acquisition targets for complementary product technologies or scale in priority channels (direct-to-consumer subscription, mass retail, specialty stores).
-
Channel and pricing strategy: Use tiered SKUs (premium, core, entry) to defend margins while enabling private-label partnerships for high-volume channels.
-
Brand and consumer engagement: Invest in education-led marketing around sustainability and total-cost-of-ownership to convert eco-aware, cost-conscious parents.
How Executive Teams Should Use This Report
PW Consulting’s report is designed as an operational playbook as much as a market forecast. Executive teams should use the study to: (1) validate strategic priorities through scenario stress tests that incorporate regulatory and freight shocks; (2) quantify payback on product certification and re-engineering projects; (3) build an M&A scorecard that ranks targets by customer overlap, SKU fit, and cost synergies; and (4) deploy the provided financial templates for channel-specific unit economics and inventory run-rate modeling. Our clients typically operationalize the study through a 4–6 week implementation sprints encompassing procurement, product, and commercial teams.
Conclusion — Why This Report Matters for 2026
The next 12–18 months will determine whether firms capture the shift from disposable to reusable diapering at scale. With a clear top-line trajectory — the market expanding from USD 215.0 Million in 2025 at a projected 11.85% CAGR to approximately USD 345 Million by 2032 — the opportunity is material for players who can marry compliant product engineering with resilient sourcing and targeted channel execution. PW Consulting’s full report delivers the segment-level detail, regional analytics, and model-ready tools necessary to translate these macro dynamics into profitable action. For procurement leads, product heads, and corporate strategists planning 2026 initiatives, the study functions as an immediate decision-support resource and a blueprint for near-term execution.
To access the full dataset, scenario matrices, and company-level appendices that underpin these insights, please consult the PW Consulting report and online data annex. The preview above outlines the strategic imperatives; the full study contains the granular inputs required to operationalize them.
For detailed analysis of this topic, please visit the official page: Cloth Diapers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com