

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Lithium Carbonate Market Poised to Expand Rapidly, Projected 14.3% CAGR Through 2032

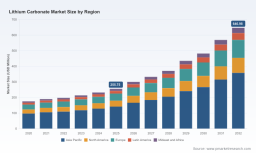
Lithium Carbonate Market: Strategic Imperatives for 2026 — PW Consulting Insights
Executive snapshot
PW Consulting’s latest Lithium Carbonate Market study (base year 2025; historical window 2020–2025; forecast 2026–2032) is calibrated for executives making capital, procurement, and M&A decisions in 2026. The global market has expanded rapidly—rising from approximately USD 175.5 Million in 2020 to USD 255.75 Million in 2025—and is projected to continue on a steep trajectory to roughly USD 647.0 Million by 2032, reflecting a compound annual growth rate (CAGR) of 14.3% across the forecast horizon. All revenue references in this note are in USD Million.
Lithium Carbonate Market
Why this matters for 2026 decision-makers
- Market scale and growth velocity are now strategic determinants: procurement rhythm, offtake tenor, and capital allocation must reflect a market growing at mid-double-digit CAGR.
- Concentration dynamics are material to strategy: the top three and five participants account for a meaningful share of supply, creating both counterparty risk and strategic opportunity for new entrants and downstream consumers.
- Regulation and traceability are shifting the shape of competitiveness: compliance timelines tied to EU and regional rules are compressing implementation windows for suppliers and processors.
What PW Consulting’s report delivers
- Transparent, auditable supply-demand modelling calibrated to 2020–2025 history and 2026–2032 scenarios (upside, base, downside) with configurable inputs for price, feedstock yields, and processing lead times.
- Practical playbooks for offtake structuring, tolling agreements and hedging strategies that optimize working capital without surrendering optionality.
- Capital and operating cost benchmarks for spodumene-based and brine/DLE conversion routes, plus sensitivity analysis for reagent and energy cost volatility.
- Regulatory impact matrix translating EU Battery Regulation, Critical Raw Materials Act benchmarks, and regional permitting trajectories into decision triggers for project sanctioning.
- Competitive and counterparty risk heatmaps—profiles of incumbent producers, emerging entrants, and technology providers with scenario-driven strategic options (partner, buy, or out-licence).
- ESG and traceability due-diligence checklists that map to procurement requirements entering force in 2026–2028.
Supply-side dynamics and strategic implications
The market’s growth is a supply-and-demand story played out across multiple project archetypes: brine operations with long lead times but low variable costs, hard-rock spodumene conversions with modular expansion profiles, and new direct lithium extraction (DLE) entrants offering faster ramp but execution and scalability risk. Recent project developments underscore the heterogeneity of supply pathways: established lithium chemicals producers have brought incremental chloride and carbonate conversion capacity online; greenfield hard-rock projects are targeting late-2027 mechanical completions; and DLE pilot-to-commercial transitions have started generating first shipments.
Lithium Carbonate Market
Strategically, buyers and financiers must adopt a differentiated sourcing approach: secure staggered offtakes across technology types, prioritize counterparties with proven traceability and regulatory conformance, and structure contracts that allow optionality as new, lower-cost volumes come online. For suppliers, the priority is managing ramp risk, ensuring product spec consistency for battery-grade applications, and advancing downstream integration to capture margin.
Lithium Carbonate Market
Demand drivers and resilience of growth
EV adoption curves, grid-scale energy storage deployments, and the industrial demand for high-purity carbonate underpin the base-case CAGR. Beyond headline demand, regulatory push—particularly traceability and human-rights-related supply chain standards—will reshape procurement, favouring vertically integrated or well-certified suppliers. Demand elasticity to price is non-linear: short-term spikes induce substitution and recycling acceleration, while sustained price levels spur incremental investment into new feedstock conversion and recycling facilities.
Competitive landscape: Signals and strategic takeaways
The market exhibits moderate concentration—our analysis shows the top three firms supply a majority position in the market, while the top five extend that dominance. This creates several tactical positions for investors and downstream players:
- Incumbent integrated producers retain strategic advantages through scale, downstream conversion, and established customer relationships. Their ongoing capacity projects and joint ventures are designed to secure long-tenor contracts with OEMs and energy utilities.
- New large-scale greenfield projects are strategically important but timing- and capital-sensitive; public financing and government loan guarantees are shaping which projects reach first production.
- DLE and other processing innovations are a double-edged sword: they can lower cost and environmental footprint quickly if proven at scale, but they also introduce technical execution risk that can impact timelines and product specs.
Key corporate movements we track (illustrative, non-exhaustive):
- Large integrated manufacturers have expanded chloride and carbonate capacity while forging JVs to secure brine feedstocks and accelerate conversion capacity.
- Primary brine operators continue to scale, with some achieving key industry certifications and moving toward broader market participation for battery-grade products.
- North American projects have attracted public financing support focused on onshore processing to meet domestic content and critical minerals objectives.
Regulatory, certification and geopolitical headwinds
Regulatory drivers are increasingly binding. The European Battery Regulation and Critical Raw Materials Act introduce concrete thresholds for extraction, processing and recycling that buyers must meet—effective compliance dates are shaping capex and sourcing decisions now. Certification programs and on-site audits (already achieved by several operations) materially affect market access with tier-one OEMs. Additionally, public-sector financing and tariff policy are reshaping project economics for onshore processing capacity in major consuming regions.
Actionable plays for 2026 — prioritized
- Secure multi-year, flexible offtake contracts that combine fixed-volume anchors with options and index-linked tranches to balance price protection and upside participation.
- Diversify feedstock and geography across brine, spodumene conversion, and recycling sources to mitigate single-sourcing and geopolitical concentration risks.
- Invest in traceability and ESG reporting capabilities now—meeting imminent regulatory and OEM procurement thresholds will be a de facto market access requirement.
- Partner with validated DLE and electrolytic process providers on proof-of-concept pilots to shorten time-to-market for lower-footprint supply.
- Use staged, milestone-linked funding structures for greenfield projects to de-risk execution and align vendor incentives with throughput and product-spec performance.
Report methodology and what you’ll find inside
Our modelling combines bottom-up plant-level capacity build schedules and top-down demand forecasts by end-application, cross-checked against trade flows and inventory cycles. Scenario outputs allow users to re-run sensitivities against price, feedstock yield and ramp profiles. The report includes a negotiable contract template library, an ESG due-diligence pack mapped to major buyer requirements, and an interactive executive dashboard designed for Board and investment committees.
The trailer principle — what’s intentionally withheld here
This release is a strategic trailer: it conveys the core directional findings, the operational frameworks, and the strategic implications executives need to know in 2026. To preserve the utility of the report for clients and to avoid substituting for bespoke advisory work, we have intentionally omitted granular segmented tables, detailed regional and application share breakdowns, and our full unit-cost curves. Those proprietary datasets—essential for pricing negotiations, project sanction, or acquisition diligence—are available in the full report and advisory deliverables.
Next steps for leaders
- Procurement heads: request a tailored sensitivity run from PW Consulting to stress-test your offtake portfolio against our three scenarios.
- Investors: use our supply-side execution scorecard to triage target projects—prioritize nodes with proven permitting and commercialization pathways.
- OEMs and battery manufacturers: accelerate supplier certification pilots with vertically integrated producers and DLE providers to lock in compliant supply.
PW Consulting’s Lithium Carbonate Market report is designed to move organizations from inference to action: equipping Boards, strategy teams, and transaction desks with the models, playbooks, and regulatory mapping needed to make high-stakes decisions in 2026. For access to the full dataset, scenario models, and customized advisory options, consult the report landing page or contact our industry practice.
For detailed analysis of this topic, please visit the official page: Lithium Carbonate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com