

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Low‑ and Medium‑Voltage Inverter Market Poised to Expand at 7.16% CAGR Through 2032

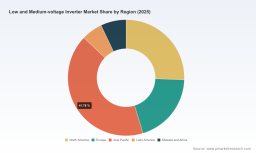
Low and Medium‑Voltage Inverter Market: Strategic Imperatives for 2026 — PW Consulting Insights
Executive summary
PW Consulting's latest market research on the Low and Medium‑Voltage Inverter Market (base year 2025; historical window 2020–2025; forecast 2026–2032) delivers a pragmatic, decision‑grade playbook for senior executives preparing strategy in 2026. The market has more than doubled in size since 2020 — rising from a mid‑single digit billion USD base to an estimated 8.21 Billion USD in 2025 — and is modeled to continue expanding at a compound annual growth rate (CAGR) of approximately 7.16% through the 2026–2032 forecast window, reaching an addressable market in excess of 13 Billion USD by 2032. These headline figures mask a complex set of technological, regulatory and supply‑chain inflection points: our report translates those inflections into concrete choices for product roadmaps, procurement, M&A and go‑to‑market priorities.
Low and Medium-voltage Inverter Market
Why 2026 is a pivotal planning year
-
Regulatory compression: 2024–2026 has seen an unprecedented flurry of grid‑code and interconnection updates that materially affect inverter functional requirements. Examples include tightened ride‑through and post‑fault active power recovery obligations for sizable demand connections, mandatory reactive power capability ceilings for inverter‑based resources, and updated low‑voltage interconnection standards. For product leaders and system specifiers, these are not hypothetical compliance items — they are hardware and control software specifications that will shape purchase cycles and retrofit windows in 2026 and beyond.
Low and Medium-voltage Inverter Market -
Technology gating: The commercialisation of higher‑blocking SiC devices and 3kV string inverter architectures, combined with new medium‑voltage inverter topologies for utility‑scale deployments, is accelerating a step‑change in plant simplicity and levelised cost dynamics. Pilots commissioned in early 2026 demonstrate that these technologies can materially reduce balance‑of‑plant complexity, but they also shift BOM composition and supplier exposure.
Low and Medium-voltage Inverter Market -
Supply‑side stress: Critical raw‑material tensions — most notably a global copper supply shortfall that has been observable since 2025 — are driving both input price volatility and procurement lead‑times. For manufacturers and large project developers, 2026 will be the first full planning cycle where raw‑material constraints materially affect production planning, hedging strategies and supplier selection.
-
Market structure dynamics: Although a set of established multinational players continue to anchor technology and brand leadership, concentration metrics reflect a market that remains comparatively fragmented versus adjacent power‑electronics domains. That fragmentation creates space for targeted entrants, regional champions and consolidation plays that we expect to accelerate in 2026–2027.
What the report delivers — practical, executable content
-
Market sizing and scenario modelling: multi‑horizon topline and downside scenarios (sensitivity to commodity price, grid‑code adoption and technology substitution) designed to feed financial planning models.
-
Technology roadmaps and product specification matrices: comparison of LV and MV inverter architectures, key semiconductor and passive component choices, and minimum viable control‑function sets to meet evolving grid codes.
-
Go‑to‑market playbooks: demand segmentation approaches, channel strategies for EPCs vs. utilities, and deployment sequencing for hybrid storage + inverter propositions.
-
Procurement and supply‑chain playbooks: risk heatmaps, dual‑sourcing templates, hedging and long‑lead component strategies tailored to 2026 procurement cycles.
-
Competitive and M&A evaluation frameworks: capability and gap analyses for leading corporations and fast‑growing challengers, plus trigger events that typically catalyse consolidation.
-
Regulatory compliance and revenue‑path mapping: regionally contextualised compliance checklists and a monetisation matrix for grid services enabled by inverter control (frequency response, voltage support, demand‑side markets).
-
Executable pilots and CAPEX/OPEX templates: step‑by‑step pilot design guides (including performance metrics and test protocols) and financial templates to quantify payback and lifetime cost of ownership.
Competitive landscape — patterns, not just names
The competitive field is a mix of long‑standing global incumbents, diversified power‑systems vendors and agile regional specialists. The market’s three‑player and five‑player concentration metrics indicate meaningful room for challenger strategies: global leaders anchor solutions across equipment, services and software, while disciplined regional players exploit price, local standards familiarity and speed to market.
-
ABB (Zurich, Switzerland) — Re‑entering segments via targeted acquisitions and leveraging wind converter expertise to recombine medium‑ and low‑voltage solar offers. Strategic concern for incumbents: ABB’s acquisition pattern hints at rapid capability stacking across renewable grid interconnection technologies.
-
Siemens (Munich, Germany) — Focusing on medium‑voltage drives and integrated power conversion for industrial and renewable applications; Siemens competes on system integration and utility‑grade controls.
-
Schneider Electric (Rueil‑Malmaison, France) — Emphasises power management and inverter solutions for LV and MV, playing to strengths in building automation and distributed energy resource orchestration.
-
Danfoss (Nordborg, Denmark) — Industrial frequency converters and AC drives, positioning to capture industrial retrofit opportunities driven by energy‑efficiency programs.
-
Yaskawa, Fuji Electric, Nidec, Hitachi — Japanese incumbents with deep industrial drive portfolios and strong OEM links; their differentiated value is reliability, engineering services and heavy‑duty industrial product lines.
-
GE Vernova — Targeting utility‑scale renewables with integrated solar power station offerings; new product launches in early 2026 illustrate an intent to simplify utility procurement by delivering transformer plus inverter stations.
-
Chinese and Taiwanese challengers (e.g., INVT, Inovance, Hiconics, STEP Electric, Delta) — Compete aggressively on cost and rapid product cycles; increasingly visible in large‑volume industrial and distributed renewable projects.
Recent competitive events — such as ABB’s acquisition move to re‑enter the solar inverter market, Fraunhofer’s commissioning of medium‑voltage PV pilots using high‑blocking SiC semiconductors, and GE Vernova’s mid‑2026 product launches — are signals that incumbents are both defending installed bases and racing to secure superior technology nodes.
Market dynamics: drivers, risks and near‑term inflection points
-
Demand drivers: accelerating renewable capacity additions, electrification of industrial processes, and the opening of new grid‑service revenue streams to smaller, inverter‑based assets.
-
Technology drivers: SiC adoption, higher DC‑link voltages in string inverters, digital twins for inverter fleet management, and tighter power‑electronics + controls integration to meet grid‑code demands.
-
Supply risks: copper shortages and volatile commodity markets, extended lead times for certain passive components, and single‑sourcing risks for power semiconductors.
-
Regulatory uncertainties: staggered and regionally divergent grid codes create retrofit risk for early deployments; conversely, they also create first‑mover revenue opportunities for products engineered to the new standards.
Strategic recommendations for 2026 decision‑makers
-
Prioritise standards‑compliant functionality in next‑generation SKU planning. Products that can demonstrably meet new ride‑through, active‑power recovery and reactive‑power obligations gain an outsized procurement preference.
-
Hedge input‑commodity exposure now. Adopt multi‑tier supplier contracts, strategic component inventory buffers for 2026 delivery windows, and explore material substitution validation where feasible.
-
Accelerate SiC and higher‑voltage string inverter pilots. Technology readiness will determine market access in medium‑voltage PV deployments; pilots will also clarify BOS and O&M cost implications.
-
Pursue targeted M&A or alliance plays to close capability gaps (controls, grid services software, or medium‑voltage transformer integration) rather than broadscale horizontal consolidation.
-
Design commercial offers that monetise grid services. With markets opening to smaller resources and in several jurisdictions now compensating reactive and dynamic services, inverters with market‑grade telemetry and controls command pricing premiums.
-
Revisit warranty and service‑model economics. Longer, performance‑linked service agreements can differentiate product offers while enabling predictable revenue streams amid hardware commoditisation.
-
Localise manufacturing and aftermarket capabilities where regulatory or grid‑code enforcement is most active; this reduces retrofit friction and speeds compliance updates.
How to use this report in your 2026 planning cycle
-
Board briefings: distil scenario analyses into three investment envelopes (protect, optimise, grow) with clear trigger criteria tied to commodity prices, pilot outcomes and regulatory adoption timelines.
-
Product roadmap alignment: map feature development to mandatory compliance milestones first, then to revenue‑enabling functions (grid services). Prioritise modular architectures that allow field upgrades.
-
Procurement reset: deploy the report’s supplier risk matrix to re‑evaluate global sourcing — particularly for copper and power‑semiconductor supply chains — and implement dual‑sourcing where economically warranted.
-
M&A and partnership screening: use the competitive matrices to identify bolt‑on targets that close gaps in control software, MV transformer integration or service networks.
Concluding note and call to action
2026 will be the year many strategic choices crystallise for companies competing in the Low and Medium‑Voltage Inverter Market. With a market on a sustained growth trajectory — demonstrated by the acceleration from an early‑decade base to an estimated 8.21 Billion USD in 2025 and modeled forward at a 7.16% CAGR to 2032 — leaders must balance engineering investments, supply‑chain resilience and commercial creativity. PW Consulting’s full report provides the granular segment intelligence, supplier scorecards and deployable templates that boards and executive teams will need to convert the high‑level signals outlined here into winning action plans. For the detailed segment breakouts, supplier scorecards and downloadable modelling assets, visit our report page to access the complete dossier and companion toolset.
For detailed analysis of this topic, please visit the official page: Low and Medium-voltage Inverter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com