

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Steel Hollow Section Market Set to Grow at 5.2% CAGR, New Insight Report Reveals

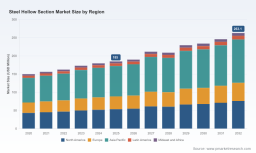
PW Consulting Releases Strategic Brief: Steel Hollow Section Market Outlook — A Practical Playbook for 2026 Decision-Making
PW Consulting today publishes a targeted industry brief built from our full Steel Hollow Section (HSS) Market study (base year 2025, historical 2020–2025, forecast 2026–2032). The brief synthesizes the market’s macro trajectory — a steady expansion from USD 150.0 Million in 2020 to USD 185.0 Million in 2025, with a forecast rise to USD 263.1 Million by 2032 at a 5.2% CAGR across the forecast window — and translates that trend into concrete choices procurement, operations, and corporate development teams should make in 2026. This release is a strategic “trailer”: we reveal frameworks, scenarios, and actionable guidance while preserving the granular segment-level tables and proprietary models for report subscribers.
Steel Hollow Section Market
Why this brief matters for 2026
-
Timing: The market is at an operational inflection point. Price movements and raw-material swings that began in late 2025 have carried into 2026, creating near-term cost pressure and supplier re-prioritization opportunities.
Steel Hollow Section Market -
Decision focus: Capital allocation, contract architecture, and decarbonization investments made in 2026 will determine competitiveness through the remainder of the decade as the market grows at a mid-single-digit CAGR.
Steel Hollow Section Market -
Risk management: The interplay between raw-material cost volatility, regulatory carbon benchmarks, and producer pricing behavior makes scenario-based procurement and hedging essential.
What’s inside the full report (practical deliverables)
We designed the report as an execution toolkit for commercial, supply chain, and corporate strategy teams. Highlights include:
-
Integrated demand-supply models with adjustable inputs for raw-material costs, HRC prices, and tariff scenarios to quantify margin pass-through under alternative market conditions.
-
Price-sensitivity dashboards and supplier scorecards that assess lead times, jumbo-size capability, quality certification coverage, and responsiveness — formatted for direct inclusion in RFPs and SRM platforms.
-
Operational playbooks: templates for indexed contract clauses, contingency inventory policies, and dual-sourcing decision trees calibrated to mid-cycle and stress scenarios.
-
M&A and partnership due-diligence packs: cash-flow stress tests, plant-level cost benchmarking, and integration checklists targeted at bolt-on acquisitions and capacity rationalization.
-
Carbon and compliance module: mapping of production emissions footprints, gap analysis vs. major procurement standards (including Buy Clean-type benchmarks), and practical decarbonization roadmaps.
-
Scenario annex: three forward-looking scenarios (Base, High-Price Shock, Low-Growth) with trigger thresholds, impact matrices, and recommended tactical responses for 0–12 month, 12–36 month, and 36+ month horizons.
Market dynamics shaping 2026 strategies
The HSS market entered 2026 under the influence of multiple forces:
-
Price momentum and supplier actions: Leading North American producers announced sequential price adjustments in late 2025 and early 2026. These moves have the practical effect of compressing buyer margins unless pass-through mechanisms or material substitutions are deployed.
-
Raw-material volatility: Recent market intelligence shows Heavy Melting Steel scrap prices in parts of the U.S. averaged USD 379 per ton in May 2026. Given the reliance of electric-arc furnace (EAF) HSS production on recycled scrap (approximately half of material input on average), this volatility translates directly into plant-level cost swings.
-
Upstream coil and trade dynamics: Hot-rolled coil price increases and import restrictions remain key drivers of late-2025/early-2026 price volatility. Tariff and trade-policy shifts continue to alter regional competitiveness and sourcing corridors.
-
Regulatory pressure on embodied carbon: Emerging procurement requirements — exemplified by a California benchmark of roughly 1.71 metric tons CO2e per metric ton for HSS — are creating a new supplier selection axis. Buyers will increasingly apply carbon performance as a commercial gate.
Competitive landscape: strategic read on key producers
The market is neither monopolistic nor atomized. Our concentration metrics show a top-three share that signals meaningful scale-based advantages for leading producers, while leaving room for regional specialists and niche-capability players to thrive. The report’s company profiles synthesize publicly available data, plant footprints, product breadth, and recent commercial signals; below we summarize strategic positions.
-
Nucor Corporation — A scale leader with diversified structural steel capabilities and multiple HSS manufacturing sites. Nucor’s ability to move large volumes, its product certification breadth, and its recent pricing activity underscore strong commercial discipline. For buyers, Nucor represents supply security and scale-driven negotiating pressure; for investors, the firm’s margin resilience is a bellwether for industry pricing.
-
Atlas Tube / Zekelman umbrella — Offers the broadest size range and jumbo HSS capacities. Their product breadth and recent price actions highlight tactical pricing leverage in projects requiring large-section or thick-wall offerings. Competitors face challenges on jumbo-size lead times; buyers requiring large sizes should prioritize early engagement.
-
Canadian HSS specialists (several regional producers) — Multiple Canada-based producers focus on ASTM/CSA-compliant products and regional service. These players are positioned to capture local infrastructure and construction demand where logistics and certification matter more than scale.
-
Regional welded-tube and boutique providers — Smaller facilities offering specific grades, welded construction, or niche tolerances provide important tactical options for OEMs and regional fabricators seeking customization or shorter lead times.
Strategically, the competitive landscape implies three near-term imperatives: secure trusted primary suppliers from large-scale producers for volume and resilience; maintain relationships with regional specialists for flexibility and niche sizing requirements; and monitor producer pricing announcements as leading indicators of market tightness.
Actionable 2026 playbook (what to do this quarter)
-
Implement indexed contracts with escalation triggers tied to a composite of scrap and HRC prices — not flat annual increases — to reduce basestock margin erosion when raw-materials spike.
-
Prioritize dual-sourcing for critical sizes and jumbo sections; assign minimum-viable stocking for long-lead SKUs where substitution is infeasible.
-
Run a 90-day rapid supplier audit for carbon intensity disclosure: require primary suppliers to report production CO2e and steelmaking route (EAF vs. BOF) to prepare for procurement standards and public-sector projects.
-
Adopt a tranche-based hedging approach: layer fixed-price contracts for near-term needs while retaining spot optionality for opportunistic buys as price volatility abates.
-
For M&A teams: prioritize tuck-ins that add geographic fill or unique technical capabilities (e.g., jumbo HSS, specialty wall thicknesses) rather than broad market share grabs which may dilute synergies.
-
Institute a quarterly “market-triggers” review: scrap price thresholds, tariff announcements, and major producer pricing actions that would shift capital-intensity or procurement posture.
How PW Consulting supports your 2026 agenda
PW Consulting pairs the published study’s empirical forecasting with hands-on implementation support. Our advisory services include rapid scenario workshops, supplier scorecard deployment, transaction due diligence, plant-level cost modeling, and carbon compliance strategies tailored to Buy Clean-style procurement. For organizations prioritizing resilience, margin protection, and sustainability in 2026, we offer focused engagements that translate the report’s models into executable plans within 4–8 weeks.
Note on data access: this brief highlights the study’s macro trajectory and strategic implications while withholding proprietary segment-level breakdowns, plant-level cost models, and full supplier scoring matrices. These granular elements are available exclusively in the full report and supporting data packages.
Next steps
-
Download the executive summary and request a scoped advisory session to receive the full dataset and a tailored scenario run for your supply chain.
-
Schedule a workshop with our sector team to convert the 2026 playbook into an operational plan aligned with your procurement cycles and capital calendar.
In a market growing at a steady mid-single-digit pace and facing concurrent cost, regulatory, and trade shocks, 2026 will reward firms that convert insight into disciplined contracts, carbon-aware sourcing, and targeted capacity investments. PW Consulting’s Steel Hollow Section Market study is designed to make those decisions faster, less risky, and more profitable. For access to the full report, appendices, and bespoke engagements, visit our website or contact our advisory desk.
For detailed analysis of this topic, please visit the official page: Steel Hollow Section Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com