

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Shot Peening Machine Market to Reach USD 1,125.83 Million by 2032, Growing at a 5.7% CAGR from 2025's USD 755.2 Million

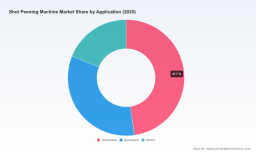
Shot Peening Machine Market: Strategic Imperatives for 2026 — A PW Consulting Report Preview
As manufacturers confront an inflection point in surface-treatment technology, PW Consulting’s latest market study on Shot Peening Machines distills the strategic intelligence executives need to make high‑stakes 2026 decisions. Anchored on a 2025 base year and projecting the industry through 2032, our analysis shows a resilient market expanding at a 5.7% compound annual growth rate (CAGR). From a market size of approximately USD 755 million in 2025, the sector is forecast to progress toward the billion‑dollar threshold by the end of the decade — a trajectory driven by automation, stricter aerospace and automotive quality regimes, and the evolution of peening techniques tied to electrification and lightweighting.
Shot Peening Machine Market
Why this report matters for 2026 planning
-
Operational investment decisions are time sensitive. Capital allocations made in 2026 will determine manufacturing posture for the rest of the decade; our base‑year benchmarking and forecast runway provide the forward‑looking economics to justify or defer those investments.
Shot Peening Machine Market -
Regulatory and standards dynamics are evolving. Technical committees and OEM stakeholders are actively updating shot‑peening specifications and traceability requirements — changes that will materially affect line qualification, audit readiness, and supplier selection starting in 2026.
Shot Peening Machine Market -
Technology is reframing total cost of ownership. Intelligent automation (robotic vision, multi‑axis controls, real‑time monitoring) is shifting the economics from labor to software and services; our study quantifies the adoption implications across purchase price, throughput, and compliance risk.
-
Market concentration is meaningful for strategy. With the top industry players accounting for a material share of supply, tactical partnerships, aftermarket service capabilities, and certification credentials are differentiators for both buyers and sellers.
Core trends shaping the market in 2026
-
Automation and intelligent control: The industry is accelerating the integration of robotic systems, programmable tool changers, and machine‑vision feedback loops. These upgrades reduce operator dependency, improve repeatability, and enable traceable process logs required by tier‑1 aerospace and automotive customers.
-
Traceability and compliance: Recent standardization discussions and committee activity indicate a tightening of process traceability expectations. Equipment that supports real‑time monitoring and audit‑grade data capture is now a procurement priority for regulated segments.
-
Service and consumables as revenue drivers: As hardware commoditizes in some subsegments, suppliers are increasingly monetizing maintenance, certification services, and consumable supply chains (including steel shot), creating attractive recurring revenue streams.
-
Geographic and vertical demand shifts: Demand continues to be anchored by aerospace and automotive markets, but electrification, transmission design changes, and industrial maintenance cycles are creating new peening use cases and volume pockets.
-
Supply chain pressure points: Raw material dynamics — notably the continued dominance of steel shot for high‑hardness applications — and logistics complexity are influencing lead times and working capital considerations for buyers and OEMs alike.
What’s inside the report (practical, operational deliverables)
-
Proprietary market model: A consolidated historical series (2020–2025) and a seven‑year forecast (2026–2032) with scenario sensitivity for demand shocks, regulatory acceleration, and technology substitution. The model is delivered with editable inputs so teams can re‑run scenarios aligned to their strategic assumptions.
-
Decision frameworks: Capital budgeting templates that map purchase options (manual vs. semi‑automated vs. fully automated) to expected throughput, lifecycle maintenance, and compliance costs — enabling a quick, defensible CapEx approval package.
-
Vendor scorecards and procurement playbooks: A repeatable supplier evaluation matrix covering technical fit, service footprint, certification status, total cost of ownership, and aftermarket performance. Includes negotiation levers and sample RFP language tailored for different risk profiles.
-
Technology due diligence checklist: A practical diagnostics toolkit for validation of new systems — from multi‑axis kinematics to real‑time monitoring integrity — and a blueprint for on‑site acceptance testing and capability proofs.
-
Implementation roadmaps and KPIs: Phase‑based rollouts for retrofits or greenfield lines, with target metrics for throughput gains, quality yield, touch‑time reduction, and payback timelines under conservative, base, and aggressive adoption scenarios.
-
Primary research and case studies: Plant‑level case studies and buyer interviews with major OEMs and tier suppliers, providing on‑the‑ground context for adoption barriers, training needs, and service expectations.
Competitive landscape — who matters and why
The Shot Peening Machine market combines niche specialists, long‑standing OEMs, and cost‑focused manufacturers. Our competitive analysis profiles the leading vendors and distills their strategic postures, differentiators, and likely plays through 2026:
-
Wheelabrator Group (UK): A leader in automated systems with deep aerospace and heavy‑industry credentials. Their strength lies in integrated turnkey solutions and aftermarket service networks tailored to demanding, certified processes.
-
Empire Abrasive Equipment Company (Buffalo, NY): Known for precision, conventional and CNC peening systems. Recent corporate emphasis on certification and engineering depth positions Empire for partnerships with quality‑conscious OEMs.
-
Rösler Oberflächentechnik GmbH (Germany): High‑performance systems for complex components; demonstrated traction in EV drivetrain applications through targeted system implementations.
-
Guyson Corporation and Sinto America: Strong in aerospace‑grade cabinets and systems, with reputational strength in process documentation and compliance support.
-
Pangborn Group and other established OEMs: Offer custom equipment and integration services for forming, peening, and finishing — attractive to customers requiring hybrid process lines.
-
Progressive Surface and Engineered Abrasives (United States): Innovators in intelligent automation and robotic integration, delivering integrated vision and tool‑changer capabilities that reduce labor intensity and improve traceability.
-
Chinese OEMs (multiple): Competitive on price and volume for industrial applications; increasingly active in export markets for heavy industrial peening where cost is the primary procurement criterion.
Market concentration metrics in our analysis underscore that a relatively small set of providers controls a sizeable share of supply — a structural feature that shapes bargaining power, aftermarket economics, and M&A interest. Equipment certification, field support density, and data‑capability are the three axes on which suppliers are being evaluated more than ever.
Recent developments and their strategic implications
-
Product innovation: The introduction of next‑generation multi‑axis peening machines with built‑in real‑time monitoring has immediate implications for aerospace and high‑value automotive parts, shortening qualification cycles and enabling tighter process control.
-
System deployments at academia and labs: Strategic installations at research institutions create cross‑pollination opportunities — suppliers gain validation and visibility, while OEMs get access to early adoption learnings.
-
Certification milestones: Suppliers investing in shot‑peening certification and staff training are increasingly preferred partners for OEMs with stringent audit requirements, reducing supplier switching costs and accelerating purchase cycles.
Actionable strategic recommendations for 2026
-
Prioritize traceable automation investments: For regulated segments, select platforms with embedded data capture and audit‑grade monitoring as a minimum requirement. The incremental CapEx is often recouped through reduced audit failures and higher first‑pass yields.
-
Use pilots to derisk rollout: Implement a modular pilot (single cell) that replicates production complexity and ties into enterprise data systems; baseline KPIs for a one‑quarter proof of value before multi‑cell rollouts.
-
Reassess supplier scorecards to include certification and service SLAs: Wherever uptime and documented process control matter, service footprint and certification trumps headline price.
-
Hedge raw‑material and consumable exposure: Locking multi‑year agreements on consumables supply and considering vendor‑managed inventory can smooth production risk and reduce working capital volatility.
-
Explore partnerships and bolt‑ons for digital services: For OEMs, capturing aftermarket service revenue from monitoring, predictive maintenance, and consumables supply will be a critical margin lever.
-
Build a talent and certification roadmap: Invest in operator certification and engineering training aligned to updated standards to shorten qualification time and reduce quality risk.
How PW Consulting supports your 2026 decisions
-
Custom quantification — we adapt our forecast model to your production footprint, capital plan, and compliance timelines so you can model the exact ROI of equipment choices.
-
Supplier due diligence — deep technical audits, reference checks, and on‑site acceptance test scripts to minimize procurement risk and accelerate installation timelines.
-
Implementation acceleration — program management and change‑management playbooks to translate pilot successes into plantwide performance improvements while protecting ongoing production.
PW Consulting’s Shot Peening Machine Market report blends market‑grade forecasting with the operational playbooks procurement, operations, and engineering teams need to act in 2026. The analysis demonstrates where to deploy capital, how to mitigate regulatory and supply risks, and which supplier capabilities to prioritize — while preserving the granular datasets and segment breakdowns required for transaction‑level decisions. To access the full quantitative datasets, supplier scorecards, and editable forecast model, please visit our report page and download the complete study.
For detailed analysis of this topic, please visit the official page: Shot Peening Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com