

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Eddy Current NDT Equipment Market to Reach USD 846.7 Million by 2032, Growing at a 7.12% CAGR
By pmarketresearch, 2026-06-30
Eddy Current NDT Equipment Market: Strategic Preview for 2026 Decision-Making
PW Consulting’s latest market research briefing on the Eddy Current Non-Destructive Testing (NDT) Equipment market synthesizes proprietary data, field interviews, and advanced scenario modeling to provide a decision-grade vantage point as corporate leaders set budgets, partnerships, and technology roadmaps for 2026. This preview highlights the report’s strategic value without disclosing the granular segment allocations—crafted intentionally to demonstrate analytical depth while directing executives and investment teams to the full report for transaction-ready detail.
Eddy Current NDT Equipment Market
Market Snapshot — Growth Trajectory and What It Means
The eddy current NDT equipment market has demonstrated steady expansion through the early 2020s and PW Consulting’s base-year assessment (2025) places the global market at USD 521.4 Million. Our forecast horizon (2026–2032) anticipates continued acceleration, with the market projected to reach approximately USD 846.7 Million by 2032, reflecting a compound annual growth rate (CAGR) of 7.12% over the forecast period. The 2026 projection sits notably ahead of 2025, signaling an inflection point for procurement cycles, capex allocation, and product development prioritization.
Eddy Current NDT Equipment Market
For corporate strategists, this macro trajectory matters for three reasons: (1) predictable scale allows larger OEMs and service firms to underwrite multi-year R&D and platform investments, (2) the rate of growth supports new business models—rental-as-a-service, condition-based inspection contracts, and integrated digital services—and (3) market momentum reduces exit risk for strategic M&A but raises the bar for transformational acquisitions.
Eddy Current NDT Equipment Market
Report Contents — Practical, Transaction-Ready Intelligence
- Robust Market Sizing & Methodology: Transparent bottom-up and top-down reconciliations with our base year anchored in 2025. Readers will find reproducible assumptions and sensitivity levers for adapting the model to bespoke use cases.
- Scenario & Stress Testing: Three forward-looking market scenarios (base, accelerated adoption, and constrained investment) that quantify revenue, margin, and CAPEX implications across short and long horizons.
- Technology Roadmaps: Comparative analysis of probe architectures, array and pulsed techniques, and software-enabled analytics—aligned to time-to-market and R&D investment profiles.
- Commercial Playbooks: Go-to-market segmentation, pricing elasticity matrices, channel strategies for rental vs. capital sales, and service contract templates for extended warranty and data services.
- Supplier & Buyer Intelligence: Verified supplier profiles, buyer persona mapping across aerospace, energy, and heavy industry, and procurement checklists to accelerate RFQ responses and vendor selection.
- M&A & Partnership Dossiers: Investment filters, synergy estimators, and target shortlists informed by our competitive and capability gap analyses.
- Regulatory & Standards Tracker: Compliance impact checklists—particularly for aerospace and nuclear applications—updated to reflect the latest validations and enforcement trends through 2025.
Each module is designed to be operational: slide-ready charts, downloadable data tables, and a compact executive decision memo template that executives can adapt directly for board and investment committee use.
Competitive Landscape — Leaders, Challengers and Where Value Hides
The vendor environment is characterized by a mix of established OEMs, focused specialty players, and service-oriented providers. Market concentration metrics indicate a moderately consolidated sector: the top three players command roughly 45% of market revenue and the top five capture close to 59%. This structure creates both defensive moats for incumbents and identifiable windows for niche entrants.
- Olympus Corporation (Tokyo, Japan): Strong in portable high-frequency systems for aerospace; incumbency in handheld units and a broad service footprint make Olympus a reference customer for airlines and MROs. Their continued product evolution keeps them central in aerospace inspection cycles.
- Zetec, Inc. (Snoqualmie, WA, USA): Deeply positioned in nuclear and power generation markets with integrated robotics and array systems—Zetec’s strength is in high-value service contracts and deployment of automated inspection solutions.
- Eddyfi Technologies (Quebec City, Canada): Known for advanced array and electromagnetic testing platforms, Eddyfi leads in high-resolution analytics and is often first-to-market for niche industrial use-cases requiring sophisticated defect characterization.
- Mid-sized specialists (Magnetic Analysis Corporation, ETher NDE, Rohmann, Institut Dr. Foerster, UniWest, Criterion, ibg NDT, Ashtead Technology, IMG ULTRASUONI): These firms collectively provide depth—probe design, inline solutions, rental and service models, and regionally dominant channel relationships. Their agility often makes them attractive targets for bolt-on acquisition by larger OEMs or private-equity platforms seeking volume or technology augmentation.
Recent strategic moves underscore the dynamic competitive environment: product launches across portable and array platforms in 2025, an acquisition expanding global footprints, and strong event activity leading into ECNDT 2026. These developments validate that incumbents continue to invest in product refreshes while also pursuing inorganic routes to shore up capabilities.
Technology & Adoption Dynamics — Signals to Monitor in 2026
- Digital Array Probe Adoption: Installations surged in 2025, reflecting a broader shift toward data-rich inspections and automated analysis. This adoption accelerates demand for integrated software and storage services, creating recurring revenue opportunities.
- Wireless & Connected Inspections: Wireless eddy current solutions recorded markedly higher adoption in 2025. Connectivity opens pathway to remote diagnostics, federated data models, and condition-based maintenance (CBM) offerings.
- Product Refreshes & Modular Platforms: Multiple vendors launched next-gen instruments in 2025—emphasizing portability, frequency range, and AI-assisted defect detection. Buyers should expect a compressing product lifecycle and a growing aftermarket for software updates and probe upgrades.
For R&D planning, these signals mean prioritizing software-enabled differentiation, cloud/edge data integration, and modular product architectures that support upgrades rather than full replacements—improving customer retention and lifetime value.
Regulatory & Standards Environment — Operational Risk and Opportunity
Standards bodies and industry validations continue to shape adoption. Notable developments include certification validations of eddy current techniques for aged nuclear assets (2025) and ongoing enforcement by bodies such as ASNT for aerospace and nuclear inspections. ECNDT 2026 remains a focal point for protocol updates and cross-industry harmonization. For compliance-driven buyers and suppliers, staying ahead of standards is not a cost-center but a market-access enabler.
Strategic Imperatives for 2026 Decision-Making
- For OEMs: Accelerate investment in digital analytics and probe modularity. Prioritize SaaS-enabled service tiers and subscription models for higher-margin recurring revenue.
- For Service Providers & Rentals: Expand asset-light rental fleets with remote monitoring capabilities; bundle inspections with analytics and trend reporting to capture downstream service economics.
- For Buyers (Aerospace, Energy, Manufacturing): Redesign procurement frameworks to favor total cost of ownership (TCO) evaluations that include software, upgrades, and data services—not just initial CAPEX.
- For Investors & Dealmakers: Target bolt-on acquisition candidates that fill capability gaps in array technologies, software analytics, or regional service coverage; use concentration dynamics to assess consolidation upside.
- For R&D Leaders: De-risk roadmaps by investing in adaptable platforms that address both pulsed and array use-cases and by building partnerships for AI-driven defect characterization.
Why PW Consulting’s Report Matters for 2026
Decision-makers told us they need three deliverables going into 2026: credible market sizing, scenario-planning with clear financial implications, and a tactical playbook for execution. Our report delivers each. It integrates the 2025 base-year reality with a forward model (2026–2032) that incorporates a 7.12% CAGR and multiple adoption pathways—allowing executives to stress-test budgets, prioritize capital allocation, and quantify strategic options such as entering new verticals, launching subscription services, or executing roll-up strategies.
The report packages actionable outputs—supplier heat maps, prioritized R&D roadmaps, M&A scorecards, and a regulatory impact matrix—so that teams can move from insight to investment in weeks, not months.
Next Steps
This preview outlines the strategic contours but intentionally omits the segment-level splits and targetable figures that trading, procurement, and M&A teams require to act. For access to the full data tables, scenario models, and vendor-level financial analytics that are essential for transaction execution and 2026 planning, consult the complete PW Consulting Eddy Current NDT Equipment Market report.
Contact PW Consulting to license the full report, request a briefing with our lead analyst, or commission a bespoke deep-dive tailored to your organization’s strategic questions.
For detailed analysis of this topic, please visit the official page: Eddy Current NDT Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Enterprise Search Market Set to Reach USD 7.61 Billion by 2032 at 8.99% CAGR — Cloud Leads with USD 2.39 Billion (2025)
By pmarketresearch, 2026-06-30
Enterprise Search Market 2026: A Strategic Briefing for CIOs, CPOs and Procurement Leaders
PW Consulting’s latest market study on the Enterprise Search Market (base year 2025) is designed as a decision-grade playbook for leaders planning investments and vendor strategies in 2026. Our analysis shows the market reaching USD 4.09 Billion in 2025 and continuing to expand to an estimated USD 7.61 Billion by 2032, reflecting a compound annual growth rate (CAGR) of 8.99% over the forecast window. These headline numbers capture a clear truth: the enterprise search layer is moving from a productivity enabler to a strategic platform that underpins knowledge work, compliance, and AI-driven automation.
Enterprise Search Market
Why this report matters for enterprise decision-makers in 2026
-
Timing: 2026 is a hinge year. Regulatory enforcement, cloud sovereignty moves, and a new wave of agentic and semantic search capabilities are converging — forcing procurement and architecture decisions that will have multi-year cost and compliance consequences.
Enterprise Search Market -
Clarity for investment: With near-term budgets tightening, IT and business leaders need a concise framework that prioritizes use cases where search drives measurable ROI (e.g., time-to-insight, case resolution, developer productivity) rather than vendor feature lists.
Enterprise Search Market -
Vendor selection risk mitigation: The market is commercially vibrant but remains moderately fragmented; choosing a partner without a clear governance model or compliance posture will create hidden costs and integration friction.
Market trajectory — what’s driving the next wave of growth
Enterprise search is expanding along three intersecting vectors. First, the semantic and agentic wave: mature embeddings, retrieval-augmented generation (RAG) patterns, and agent layers are turning search from document retrieval into task orchestration and decision support. Second, the unstructured-data imperative: enterprises still have massive volumes of documents, chat, and siloed systems that only search and knowledge graphs can knit together efficiently. Third, commercial model evolution: the shift to consumption-based cloud pricing and global points of presence has made search platforms easier to adopt at scale, accelerating deployments in customer service, knowledge management, and internal productivity applications.
Historically, the market has grown steadily from its early 2020s baseline and, as our forecasts show, continues to compound at roughly 9% per year through 2032. This pace reflects both organic adoption and expansion of addressable use cases as search platforms embed AI-native capabilities and cross-application workflows.
Regulatory and infrastructure dynamics — negotiation points for 2026
Regulation and data-residency requirements are no longer hypothetical risks — they are forcing architectural choices. The upcoming enforcement of new AI legislation in the EU introduces explainability, transparency, and accountability obligations for high-impact applications, which directly affects search and AI systems used in recruitment, credit, insurance, and healthcare. At the same time, European cloud initiatives and sovereign cloud mandates are raising the bar for data locality, compliance certifications, and interoperability. Our analysis finds that compliance-driven architectures materially increase vendor integration and operational costs, and these delta costs must be modeled explicitly in procurement decisions.
Other practical dynamics to factor into 2026 planning:
-
Sovereign cloud mandates are accelerating hybrid and multi-cloud deployments: sensitive datasets are increasingly retained on-premises or in sovereign clouds while index and inference layers may sit in public cloud. That hybrid split creates new operational and integration complexity that few organizations are operationally prepared for.
-
Enterprise sustainability and infrastructure requirements — such as supplier PUE and renewable energy commitments — are being written into cloud provider eligibility criteria, increasing the procurement checklist beyond purely technical or commercial metrics.
-
Vendors and customers face higher compliance execution costs post-2026; PW Consulting’s scenario analysis shows a significant uplift to compliance-related TCO that must be stress-tested in vendor RFPs.
Competitive landscape — practical read on the vendor field
The enterprise search ecosystem is populated by a mix of specialist platform vendors and hyperscale cloud incumbents. The market is best thought of as an architecture ecosystem rather than a winner-takes-all product contest — different vendors lead on integration, AI capabilities, or deployment models, and enterprises should match vendor strengths to specific use cases.
-
Glean — Rapid product innovation focused on workplace search with deep app connectors, permissions-aware knowledge graphs and emerging agentic features. Recent product milestones indicate a push toward automated model selection and agent-assisted multi-application workflows, and the vendor has accelerated go-to-market moves into on-prem and partner-delivered deployments.
-
Coveo — Positioned as a platform that blends enterprise search with personalization and recommendations; attractive for organizations that need unified customer-facing and employee-facing search experiences backed by behavioral signals.
-
Lucidworks — Focuses on relevance tuning, content intelligence and operationalization at scale. Their signaling and automation tooling is a strong fit for data-rich search implementations that require continuous optimization.
-
Microsoft — Tight integration with Microsoft 365 and Graph, plus Copilot Search, makes Microsoft the pragmatic choice for organizations deeply invested in M365 productivity suites and seeking native semantics across Outlook, Teams, SharePoint and OneDrive.
-
Google — Developer-centric search capabilities and cloud search products that appeal to firms building RAG-native experiences and needing advanced model tooling from Vertex AI.
-
IBM and AWS — Enterprise-grade offerings (watsonx, Kendra) designed for regulated industries and large-scale knowledge discovery, with strong integration into respective cloud and software ecosystems.
-
Elastic — The open-source stack play, viable for teams that prioritize customization, self-hosting and open architecture for scalable semantic search deployments.
Across this vendor landscape, the competitive dynamic is shaped less by single-feature differentials and more by four procurement criteria: integration breadth (connectors and permissions-awareness), AI governance (explainability and safety), compliance posture (sovereign-cloud and audit readiness), and operational economics (TCO under compliance scenarios). PW Consulting’s scoring models in the full report quantify these trade-offs for multiple buyer archetypes.
Actionable playbook — five pragmatic moves for 2026
-
Start with outcome-driven use cases. Prioritize three near-term, high-value uses (e.g., legal e-discovery acceleration, frontline support resolution, R&D knowledge synthesis) and design pilots that map directly to measurable KPIs.
-
Design an explicit data strategy for hybrid environments. Create a data residency map, classify sensitivity, and specify which assets must remain on-prem or in sovereign clouds versus what can be indexed in public clouds.
-
Require AI governance artifacts in RFPs. Ask for model provenance, explainability reports, red-teaming results, and operational monitoring plans as contract deliverables — not optional features.
-
Include compliance uplift in TCO models. Stress-test vendor economics under regulatory compliance and sovereign-cloud scenarios; include transition costs, certification timelines and energy/sustainability commitments.
-
Adopt a modular procurement stance. Favor platforms that provide well-documented APIs, connector ecosystems, and the ability to replace inference components or models without rearchitecting the index layer.
What PW Consulting’s full report contains
This briefing intentionally surfaces strategic insights while withholding granular segmentation and vendor scorecards reserved for the full report. The complete study includes:
-
Detailed historical and forecast market sizing at multiple aggregation levels with scenario runs and sensitivity analysis;
-
Vendor benchmarking across integration, AI capabilities, compliance posture and TCO under multiple deployment scenarios;
-
Procurement and implementation checklists, RFP templates, and a practical 90-day pilot playbook;
-
Regulatory impact models that quantify incremental compliance cost and operational timelines for EU AI Act and sovereign cloud mandates;
-
Case studies showing measurable business outcomes from enterprise search implementations across regulated industries.
Next steps
For enterprise leaders who must align budget cycles, negotiate vendor contracts, or define 2026 roadmaps, this PW Consulting study is intended to be the single-vendor-neutral reference that translates market momentum into pragmatic procurement and architecture decisions. To access the full dataset, vendor scorecards and implementation toolkits, please download the complete report from PW Consulting’s website or contact our Enterprise Search advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Enterprise Search Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Troponin Market Poised to Reach USD 5.52 Billion by 2032, Growing at a 9.35% CAGR
By pmarketresearch, 2026-06-30
Troponin Market 2026 Outlook: Why PW Consulting’s New Report Is Strategic Intelligence, Not Just Data
Executive snapshot
PW Consulting’s Troponin Market study—anchored on a 2025 base year and projecting through 2032—translates the troponin testing opportunity into decision-grade guidance for 2026. The market is on a sustained growth trajectory: global revenues grew from USD 2.11 Billion in 2020 to USD 2.96 Billion in 2025, and our forecast sees the market expanding to USD 5.52 Billion by 2032 at a compound annual growth rate of 9.35%. Those headline metrics matter because they frame capital allocation, R&D prioritization, and commercial entry planning for the coming 12–18 months.
Troponin Market
Why this report matters for 2026 decision cycles
-
Timing of bets: 2026 is the inflection year for many organizations—regulatory approvals, point-of-care (POC) launches, and hospital reimbursement pressures converge to reshape adoption curves. Our forecast provides scenario-based revenue and volume paths that let executives model near-term ROI under conservative, base, and aggressive assumptions.
Troponin Market -
Resource prioritization: with a multi-year doubling potential visible in the top-line trajectory, deciding whether to accelerate POC investments, scale lab-based assay capacity, or redirect R&D to next-generation sensitivity becomes a capital-allocation question. The report quantifies trade-offs in operating margin, payback period, and required investment thresholds.
Troponin Market -
Market concentration and competitive leverage: the troponin market is highly consolidated—our concentration analysis shows a triopoly capturing the majority of commercial volumes and the top five vendors controlling an even larger slice. For incumbents and challengers this has direct implications for channel strategy, OEM partnerships, and price elasticity in bidding situations.
What’s inside: practical, executable content
This report is built for operators and boards, not just academics. It contains:
-
A transparent market-sizing model with historical reconciliation (2020–2025) and a 2026–2032 forecasting engine that supports scenario toggles for sensitivity to reimbursement, adoption delays, and technological substitution.
-
Commercial playbooks: go-to-market templates for lab diagnostics vendors, POC suppliers, and clinical partnerships—covering channel economics, pricing levers, tender strategies, and hospital value propositions.
-
Regulatory & reimbursement mapping that links likely approval timelines to adoption inflection points and payer engagement playbooks tailored to national systems.
-
Supply chain de-risking and cost-sensitivity analyses, including stress tests for raw material and labor inflation scenarios and tariff impacts on API and reagent procurement.
-
Investment cases and M&A scenaria with valuation sensitivities, break-even horizons, and integration checklists for acquiring assay platforms, reagent manufacturing, or POC distribution networks.
-
Board-ready slide decks and an interactive dataset for senior leaders to run bespoke what-if analyses without exposing raw subsegment disclosures externally.
Competitive landscape: what top players are doing and why it matters
PW Consulting’s vendor assessment focuses on capability, distribution reach, clinical evidence, and regulatory momentum. Leading incumbents have been executing predictable strategies: validating high-sensitivity assays, broadening platform footprints across laboratory and bedside testing, and leveraging clinical outcomes data to support guideline adoption.
-
Abbott Laboratories (Chicago, IL). Strength: integrated lab and true bedside POC capabilities with market-ready high-sensitivity troponin I solutions. Strategic implication: Abbott’s expanded POC footprint compresses time-to-diagnosis value propositions, increasing pressure on lab-only competitors to demonstrate incremental clinical or economic benefits.
-
F. Hoffmann‑La Roche Ltd (Basel, Switzerland). Strength: deep laboratory franchise and recent regulatory traction for the latest-generation troponin T assay. Strategic implication: Roche’s diagnostic scale lets it pair assay launches with systems-level adoption programs—winning in guideline-influenced hospital pathways.
-
Siemens Healthineers (Munich, Germany). Strength: strong platform integration and recent U.S. clearance for an Atellica high-sensitivity troponin I test. Strategic implication: platform-enabled assays create switching costs and enable bundled contracting strategies with health systems.
-
QuidelOrtho Corporation (San Diego, CA). Strength: rapid regulatory progress on high-sensitivity assays for VITROS systems and expanded U.S. clearance. Strategic implication: QuidelOrtho is well-positioned to convert lab customers that value integrated chemistry and immunoassay ecosystems.
-
Danaher Corporation / Beckman Coulter (Washington, D.C.). Strength: broad analyzer installed base and high-sensitivity troponin assay portfolio. Strategic implication: the combination of reagent margins and analyzer lifecycle services underpins a defensible commercial model but requires ongoing investment in assay differentiation.
Recent regulatory and commercial milestones—CE Mark approvals, multiple U.S. clearances, and the first bedside lab-quality POC rollouts—are reshaping where and how troponin testing is delivered. PW Consulting’s timeline synthesis aligns those events with adoption milestones so executives can plan launches, manufacturing scale-up, and market access campaigns to capture short windows of competitive advantage.
Market dynamics and headwinds to plan around in 2026
-
Reimbursement pressure: hospital reimbursement dynamics continue to strain adoption economics for more expensive assays. Our analysis incorporates the latest payer arithmetic and models the impact of underpayments on hospital procurement strategies and capital approval timelines.
-
Input-cost inflation and tariffs: elevated R&D intensity and precision manufacturing already make high-sensitivity assays cost-heavy; new tariffs enacted on certain raw materials and APIs amplify procurement risk. The report includes cost pass-through scenarios and mitigation playbooks.
-
Supply chain and labor constraints: precision immunoassay manufacturing requires skilled labor and controlled raw material inputs. We model capacity bottlenecks and propose short- and medium-term hedges, from dual-sourcing to contract manufacturing partnerships.
-
Clinical evidence and guideline inertia: gaining preferred status within clinical pathways still hinges on large-scale evidence and workflow integrations—our clinical adoption model quantifies the lift required to move from early adopter to mainstream care pathways.
Actionable strategic recommendations for 2026
PW Consulting distills the analysis into a ten-point operating agenda for C-suite and boards preparing 2026 budgets and roadmaps. Highlights include:
-
Prioritize platform-compatible POC investments that demonstrably reduce door-to-treatment time—use our scenario model to determine break-even volumes by hospital size and payer mix.
-
Accelerate clinical-evidence programs focused on real-world outcomes and cost-of-care reductions; regulatory clearances alone are insufficient to secure preferred placement in clinical pathways.
-
Engage payers proactively with localized economic models; small changes in reimbursement assumptions materially alter adoption curves embedded in our forecast engine.
-
Design supply-chain hedges for at least two full production cycles and assess tariff exposures—our stress tests identify the inventory and sourcing policies that preserve margin at scale.
-
Use targeted M&A and partnerships to close capability gaps—bolt-on reagent manufacturing or a regional distribution partner can compress time to market and lower working capital needs.
Risk scenarios and what to watch in Q1–Q3 2026
We provide three near-term scenarios—Constrained Adoption, Baseline Adoption, and Accelerated Adoption—each driven by combinations of regulatory timing, hospital capital flows, and payer engagement success. Key monitoring triggers include regulatory approvals in primary markets, hospital procurement cycles, changes in Medicare payment policy, and the resolution or escalation of tariff regimes affecting key inputs.
How to use this report
Leaders should treat this study as both a strategic playbook and a modeling toolkit. The published summary establishes the macro runway and competitive topology; the full report contains the proprietary forecast model, downloadable datasets, and executable playbooks for commercial, regulatory, and supply-chain teams. To preserve competitive leverage for clients, our public brief deliberately omits granular subsegment tables and the underlying revenue-by-channel matrices—these withheld files are included with the full report purchase or available to enterprise subscribers.
Final perspective
For organizations allocating capital and attention in 2026, the troponin market is not a single binary bet but a portfolio of interdependent choices: platform vs. POC, speed-to-evidence vs. scale, and margin protection vs. share capture. With the market set to grow from a USD 2.96 Billion base in 2025 toward more than USD 5.5 Billion by 2032 at a 9.35% CAGR, the question is no longer whether the opportunity exists—it is how quickly and efficiently your organization can translate technical and regulatory wins into sustainable commercial advantage.
PW Consulting’s Troponin Market report equips decision-makers with the numbers, the scenarios, and the operational playbooks necessary to make those choices with confidence. For access to the full dataset, subsegment tables, and the interactive forecasting model, please consult the full report on the PW Consulting website.
For detailed analysis of this topic, please visit the official page: Troponin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Influenza Diagnostics Market to Rise from USD 137.4 Million in 2025 to USD 228.5 Million by 2032 at a 7.45% CAGR
By pmarketresearch, 2026-06-30
Influenza Diagnostics Market 2026: Strategic Imperatives from PW Consulting’s New Industry Report
As healthcare systems around the world enter a post-pandemic equilibrium, influenza diagnostics has re-emerged as a focal category for clinical operations, public-health preparedness, and commercial innovation. PW Consulting’s new market research, anchored on a 2025 base year and covering historical trends from 2020–2025 with forecasts to 2032, equips executives with actionable intelligence for decisive moves in 2026. Our analysis combines rigorous top-down market sizing with bottom-up capability assessments and regulatory-reimbursement mapping to translate epidemiology and technology trends into commercial advantage.
Influenza Diagnostics Market
Market trajectory and what it means for 2026 planning
The global influenza diagnostics market has demonstrated steady expansion through the 2020–2025 period and is forecast to accelerate into the early 2030s. PW Consulting’s base-year estimate places the market at USD 137.4 Million in 2025; under our core scenario, the market grows at a compound annual growth rate (CAGR) of 7.45% to reach USD 228.5 Million by 2032. This trajectory reflects the combined impact of sustained demand for rapid and multiplex testing, renewed investment in respiratory surveillance, and broadened adoption of molecular platforms in point-of-care and decentralized settings.
Influenza Diagnostics Market
For corporate strategists and health system procurement leads, this forecast translates into three immediate imperatives for 2026:
Influenza Diagnostics Market
- Prioritize platform flexibility: Invest in or partner with providers that can support multiplexing and rapid molecular workflows to capture cross-seasonal respiratory testing demand.
- Prepare for reimbursement shifts: Align pricing and coding strategies with evolving payer guidelines to secure coverage and maintain volume momentum.
- Differentiate on data and service: Add value through analytics, digital result reporting, and integrated sample-to-answer solutions that reduce clinician burden and support surveillance.
What the PW Consulting report delivers — practical, execution-ready insights
Beyond headline forecasts, our report is structured to support calendar-year 2026 decision cycles. Key deliverables include:
- Market-sizing methodology and scenario analysis: Transparent assumptions, sensitivity tests, and upside/downside scenarios that help finance teams stress-test investment cases.
- Technology landscape and product roadmaps: Comparative assessments of rapid antigen, nucleic acid amplification, and molecular point-of-care technologies, with time-to-market and upgrade paths.
- Regulatory and reimbursement playbooks: Action-oriented guidance on navigating FDA clearance requirements, coding updates, and payer coverage, including practical timelines and submission risk factors.
- Competitive intelligence and supplier benchmarking: SWOT-style profiles, capability scoring, and go-to-market positioning for incumbents and challengers—designed to accelerate partner selection and M&A screening.
- Commercial playbooks: Market-entry templates, tender and procurement strategies, pricing levers, and customer segmentation frameworks tailored for diagnostics manufacturers and distributors.
- Surveillance and public-health integration briefings: Pathways to partner with public health agencies and health systems for sentinel surveillance and outbreak response contracts.
Each deliverable is paired with an annex of primary-source references, regulatory timelines, and reproducible financial models so that corporate teams can move from insight to implementation within established budget cycles.
Competitive landscape: positioning for 2026
The influenza diagnostics ecosystem remains moderately fragmented, with the three largest suppliers accounting for approximately 28.5% of the market and the top five about 36.2%. That concentration profile creates opportunities both for scale players to consolidate further and for focused innovators to capture niche, high-value segments.
PW Consulting’s vendor analysis synthesizes product portfolios, channel reach, and R&D breadth across established manufacturers and public-health players. Highlights of competitive behaviors relevant to 2026 planning:
- Diagnostic platform leaders emphasize integrated molecular solutions and multiplex assays that address influenza alongside SARS-CoV-2 and RSV—positioning for use in both clinical labs and near-patient settings.
- Rapid-test specialists continue to compete on speed-to-result, low-cost workflows, and CLIA-waived performance, with growing emphasis on sensitivity thresholds aligned to regulatory expectations.
- Companies with existing public-health supply relationships are leveraging that footprint to win surveillance contracts and bundled procurement agreements.
- Smaller specialists and instrument-agnostic kit makers are exploiting flexibility and lower fixed-cost models to serve decentralized testing demand, particularly in outpatient and point-of-care venues.
Our company briefs synthesize these dynamics into recommended strategic responses—ranging from targeted partnerships and licensing to portfolio rebalancing and selective bolt-on acquisitions. For example, manufacturers focused on antigen lateral-flow products may find disproportionate margin and access benefits by adding a molecular reflex solution or by pursuing CLIA-waived molecular platforms for point-of-care use.
Regulation and reimbursement: immediate constraints and levers
Two policy developments are particularly salient for 2026 strategies:
- Reimbursement clarity: As of January 1, 2025, Medicare Local Coverage Article A59055 revised CPT code usage and coverage parameters for influenza molecular and antigen tests. Providers and vendors must align test claims, unitization and documentation to capture allowable reimbursement for dual detection units under relevant codes.
- Performance thresholds: Since 2024, FDA guidance requires rapid influenza diagnostic tests to meet minimum sensitivity thresholds relative to RT‑PCR for regulatory clearance. This higher bar requires vendors to invest in validation and post‑market performance monitoring to sustain clinical confidence and payer coverage.
PW Consulting maps these regulatory and payer shifts to product development and commercialization milestones. Our recommendations help R&D and regulatory teams prioritize evidence generation, select comparative-performance endpoints, and time submissions to minimize market access delays.
Noteworthy industry moves and implications
Recent product introductions underscore how quickly the competitive picture can change. In September 2025, a major vendor launched a CLIA-waived rapid immunoassay for simultaneous detection of influenza A, B and SARS‑CoV‑2 from a single sample with approximately ten-minute turnaround—illustrating the push toward rapid multiplex convenience. For 2026, companies must decide whether to meet this capability through internal development, OEM arrangements, or distribution agreements.
PW Consulting’s strategic playbooks evaluate these options against time-to-market, regulatory risk, and margin implications. We quantify break-even horizons for internal development versus partnering and provide negotiation points to manage IP and exclusivity within OEM deals.
How PW Consulting’s analyses translate into boardroom actions
Executives tell us they need two things from market intelligence in 2026: confidence in the market outlook and a short list of executable moves. Our report is designed to deliver both.
- For corporate development teams: Target lists for M&A and partnerships, with financial triangulation and integration risk profiles to support investment committees.
- For product and R&D heads: Prioritized feature roadmaps and validation plans mapped to payer and regulatory requirements to reduce time-to-revenue and rework risk.
- For commercial teams: Segmented go-to-market plays with tender-entry strategies and channel incentives to accelerate uptake across hospitals, laboratories and point-of-care channels.
- For public-health and procurement leaders: Contracting templates, surveillance-integration models and scenario planning to manage seasonal and outbreak demand swings.
Why the full report matters (and what is intentionally withheld here)
This announcement highlights the strategic conclusions and the macro trajectory of the influenza diagnostics market to guide 2026 decision-making. In keeping with our “trailer” approach, we have deliberately withheld the detailed segment-level breakdowns, regional allocations, and proprietary supplier scoring metrics from this summary. Those granular data points—critical for building business cases and procurement bids—are included in the full PW Consulting report along with downloadable financial models and supplier shortlists.
Next steps for executives
To translate these insights into 2026 action plans, firms should prioritize three near-term steps:
- Commission a rapid gap analysis against the PW Consulting supplier scorecard to identify capability shortfalls that can be closed within 6–12 months.
- Immediately map product pipelines to the updated reimbursement coding environment and to FDA performance expectations to de-risk launch timelines.
- Engage in selective commercial partnerships to secure multiplex capability or point-of-care platforms where internal development would outlast market opportunity windows.
PW Consulting’s full Influenza Diagnostics Market Report provides the detailed segment data, supplier benchmarking, and execution templates necessary to operationalize these steps. For access to the complete dataset, models, and client-only strategy workshops, please visit PW Consulting’s report page.
For detailed analysis of this topic, please visit the official page: Influenza Diagnostics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: DC Circuit Breaker Market Poised to Expand at 7.54% CAGR Through 2032 on Renewables and T&D Demand
By pmarketresearch, 2026-06-30
DC Circuit Breaker Market — 2026 Strategic Brief (PW Consulting)
PW Consulting today publishes a strategic briefing accompanying our in-depth DC Circuit Breaker Market report, designed to be a practical decision tool for corporate leaders, procurement teams, R&D heads, utilities and investors planning for 2026 and beyond. Built on a base year of 2025 and a 2026–2032 forecasting horizon, the study maps a clear growth trajectory for the sector: a compound annual growth rate (CAGR) of 7.54% and a market expansion from the mid‑2020s into a multi‑billion dollar market by the end of the forecast window. This briefing highlights the report’s operational value, key dynamics that will shape 2026 decisions, and the competitive posture of core vendors — intentionally omitting detailed segment tables to invite deeper engagement with the source report.
DC Circuit Breaker Market
Why this report matters for 2026 decision‑makers
- Procurement prioritization: Utilities and system integrators face a narrowing window to replace SF6‑dependent assets and to specify DC‑native protection for PV, storage and EV charging projects. Our market sizing and supplier readiness scores help prioritize spend across retrofit vs greenfield projects.
- CapEx and product roadmap alignment: With the market on a sustained growth path to 2032, OEMs must reconcile silicon‑carbide and solid‑state investments with modular hybrid approaches. The report quantifies technology adoption curves and delivers a phased R&D playbook aligned to realistic payback horizons.
- M&A and partnership screening: Moderate market concentration presents acquisition opportunities in manufacturing scale, IP consolidation and regional channel access. We provide a pragmatic M&A checklist tailored to DC protection assets and balance‑sheet considerations for 2026.
- Regulatory compliance and risk mitigation: Fast‑moving legislation in Europe and national rule changes are reshaping allowable insulation and switching technologies. The report’s regulatory matrix converts compliance timelines into procurement and retrofit milestones, reducing regulatory execution risk.
- Supply‑chain resilience: Component bottlenecks and test‑lab capacity constraints are the most cited near‑term risks. We translate market demand forecasts into component lead‑time scenarios and inventory hedge strategies.
What the full report delivers — operational contents
Our methodology combines primary interviews, proprietary supply‑chain models and scenario forecasting. For practitioners, the report provides:
DC Circuit Breaker Market
- Executive summary and investment thesis with three actionable scenarios (conservative, base, upside) for 2026 board deliberations.
- Transparent market sizing and growth model (base year 2025) with downloadable model templates for sensitivity testing.
- Technology roadmap juxtaposing vacuum, solid‑state, hybrid and emerging insulation media, with break‑even and TCO calculators for each technology pathway.
- Regulatory impact matrix that maps rules, effective dates, certification implications and retrofit triggers relevant to procurement cycles.
- Vendor scorecards and capability heatmaps assessing manufacturing footprint, certification readiness, modularity options and after‑sales networks.
- Buyer’s toolkit: specification checklists, test protocols, contract clauses to enforce delivery and performance milestones, and a procurement timeline for 2026 implementation.
- Operational case studies illustrating retrofit approaches, combiner‑box strategies for PV farms and protection architectures for BESS and EV charging hubs.
- Risk register and mitigation playbooks covering supply chain, test capacity, regulatory shifts and interoperability challenges.
These practical deliverables are purposefully granular in the full report. In this briefing we highlight strategic implications while preserving the detailed segment tables for the full report experience.
DC Circuit Breaker Market
Key market dynamics shaping 2026 strategy
- Regulatory acceleration: Recent and upcoming regulatory actions — notably the European Union’s staged restrictions on SF6 and national bans in major markets — are creating non‑negotiable timelines for asset replacement and new‑build specifications. Organizations that treat these rules as strategic constraints rather than compliance checkboxes will capture first‑mover benefits in retrofit contracts and specification leadership.
- Certification cycle compression: Proposed international standard amendments are set to shorten certification timelines. Faster certification favors modular, standardized product architectures and benefits vendors with established test partnerships and pre‑certified subassemblies.
- Hybridization and modularity: Product launches by several global players are validating a shift to hybrid DC breakers that blend mechanical interruption with solid‑state mitigation. Modular cartridge approaches enable staged capital deployment — a decisive commercial lever for large asset owners seeking phased upgrades.
- Technology diversification: The market is witnessing parallel adoption of vacuum interruption at certain voltage classes and solid‑state switching for high reliability/high‑cycling applications (e.g., EV fast‑charging islands). Differential adoption by end‑use (grid, renewables, industrial) requires nuanced spec’ing to avoid over‑ or under‑engineering systems.
- Consolidation pressure: As demand scales, the sector’s middling concentration metrics point to a near‑term wave of supplier consolidation, strategic partnerships and private equity interest — particularly among suppliers that can demonstrate scalable manufacturing and international certification footprints.
Competitive landscape — what we observed
Our vendor analysis covers established global incumbents as well as a sizable cohort of regional specialists. Key vendor archetypes emerging from our research include: low‑voltage specialists focusing on photovoltaic and storage integration; modular hybrid innovators positioning for deferred capital models; and manufacturers optimizing for IP protection and ingress‑rated field units.
- Sinobreaker (China) — Focuses on low‑voltage DC MCB and MCCB for PV, storage and EV charging applications, with high‑voltage ratings and IEC‑compliant offerings. Strength: rapid product customization for system integrators and export certification strategy.
- LETOP (China) — Offers both standard and custom DC MCB/MCCB solutions and leverages long product cycle experience for PV and battery systems. Strength: mature manufacturing processes and design flexibility for specific system topologies.
- ZJBENY (China) — Manufactures products targeted at battery systems and PV installations including field‑rated miniatures. Strength: niche depth in IP65 and high‑current models for harsh‑environment deployments.
- BENY (China) — Provides PV‑focused DC breakers and molded‑case solutions for energy storage and combiner boxes. Strength: product breadth for balance‑of‑system vendors.
- CNC Electric (China) — Develops DC product lines explicitly positioned for new‑energy applications. Strength: alignment with renewables integrator requirements.
- Geya (China) — Known for DC miniature breakers and custom solutions, with CE certification for export markets. Strength: certification and small‑form‑factor innovation.
- Kuangya Electric (China) — Emphasizes DC MCBs for solar systems and publishes comparative guidance on DC vs AC approaches. Strength: educational positioning that supports channel uptake.
- People Electrical Appliance Group (China) — Produces advanced DC breaker models with a stated focus on energy efficiency and sustainability in commercial and industrial settings. Strength: product positioning for energy‑sensitive customers.
Beyond this supplier set, we have tracked several strategic product moves among global engineering groups that materially affect competitive dynamics. Recent product launches that matter to 2026 strategies include medium‑voltage switchgear designed for DC with alternative insulation platforms, and modular hybrid concepts that enable capacity additions without full unit replacement. These innovations are shifting buyer requirements and accelerating conversations on interoperability and retrofit design.
Strategic recommendations for 2026
- Utilities & asset owners: Translate regulatory timelines into irreversible procurement milestones. Use staged procurements with modular acceptance criteria to reduce obsolescence risk.
- OEMs & component suppliers: Prioritize modular, pre‑certified subassemblies and invest in accelerated test capacities to exploit compressed certification cycles.
- System integrators: Package retrofit offerings that combine breaker swaps with diagnostic and lifecycle services — these deliver higher margin and lock‑in for ensuing O&M contracts.
- Investors & M&A teams: Screen targets for manufacturing scale, certification breadth and product modularity; prioritize assets that reduce time‑to‑field for large utility contracts.
How to use the full PW Consulting report
The briefing above is a curated preview of the strategic takeaways. The full report contains the quantitative tables, segmented forecasts, supplier scorecards, and downloadable financial models that underpin these conclusions. Organizations that need bespoke scenario runs, vendor due‑diligence packs or a tailored procurement playbook for 2026 should contact PW Consulting to license the report or engage our advisory services.
PW Consulting’s DC Circuit Breaker Market report is intended as a decision accelerator — a commercially focused, practitioner‑grade resource that converts regulatory signals and technology inflections into concrete procurement, R&D and M&A roadmaps for 2026. For access to the full dataset, segment breakdowns and supplier profiles, please visit the report landing page referenced in our release materials.
For detailed analysis of this topic, please visit the official page: DC Circuit Breaker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Men's Underwear Market Tops USD 39.0 Billion in 2025, Set for 5.5% CAGR to USD 57.4 Billion by 2032 as Asia‑Pacific Leads at USD 16.17 Billion
By pmarketresearch, 2026-06-30
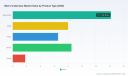
Men’s Underwear Market 2026: Strategic Preview — Why This Report Will Shape Your Decisions This Year
PW Consulting’s latest market research on the global Men’s Underwear market is designed as a practical strategic tool for executive teams preparing for the competitive inflection points of 2026. Built on a robust historical series (2020–2025) and an explicit forecast window (2026–2032), the study combines rigorous market sizing, competitive mapping, cost-pressure diagnostics, and implementation-ready playbooks to translate signal into action. This briefing highlights the most consequential insights and the specific ways our report empowers better decisions — while reserving the granular segment-level tables and proprietary model outputs for subscribers and the source web page.
Men's Underwear Market
Market Trajectory: The Numbers that Matter
The men’s underwear market has demonstrated steady expansion through the early 2020s, growing from USD 26.5 Billion in 2020 to USD 39.0 Billion in 2025. Looking forward, our central forecast projects the market to continue expanding at a 5.5% CAGR over the 2026–2032 period, reaching approximately USD 57.4 Billion by 2032. In short, the category remains a reliable growth portfolio in apparel — large enough to attract strategic investment, consolidated enough to reward scale, and dynamic enough to create new white-space opportunities for incumbents and challengers alike.
Men's Underwear Market
Why 2026 Is a Strategic Inflection Point
-
Transitioning cost structures: Input and tariff dynamics that crystallized in 2024–2025 mean 2026 will be the first full planning year in which firms can operationalize new sourcing and pricing strategies adopted late last year.
Men's Underwear Market -
Consolidation aftershocks: The M&A activity of late 2025 materially alters competitive bargaining power and supply footprints, creating short- to medium-term advantages for acquirers but also raising the bar for nimble independents.
-
Consumer premiumization and sustainability: Shifts in consumer willingness-to-pay for performance fabrics and responsible sourcing are redefining assortment strategies across channels, placing innovation and traceability at the center of near-term growth plays.
Competitive Landscape — Structure and Strategic Postures
The men’s underwear sector shows clear concentration: our CR3 sits at roughly 72% while CR5 approaches 80%, signaling a market where a few large groups define scale economics and distribution pull. For strategy teams, this concentration implies two concurrent realities: large players control wholesale and global retail access, and smaller brands must differentiate on product, channel agility, or brand narrative to sustain margin.
-
PVH Corp (Calvin Klein, etc.) — headquartered in New York, PVH leverages global brand equity and fashion-led product rhythms to command a premium intersection of style and distribution. Their recent collection refresh in Fall 2025 underscores a continued focus on design-led, higher-margin assortments.
-
Hanesbrands / Gildan (post-acquisition) — historically a scale-focused supplier emphasizing value and broad retail penetration, the December 2025 Gildan acquisition reconfigures the competitive map by combining sizable manufacturing and private-label capabilities into a single operating platform.
-
Jockey International — known for fit and heritage positioning, Jockey’s strength is in product reliability and retailer relationships, allowing it to defend share in core channels even as fashion-driven brands press higher.
-
Saxx, Pico Manufacturing, Argus Apparel, Sigma Apparel — these players represent the innovation and private-label vectors: performance-led niche brands, specialized contract manufacturers, and regional apparel houses that are sources of product differentiation and supply resilience for larger retailers.
Collectively, this topology creates strategic windows for: (a) scale consolidation plays, (b) premiumization and DTC-led brand extensions, and (c) contract manufacturing partnerships optimized for speed and margin.
Cost & Regulatory Dynamics: Inputs That Will Rewrite Margins
-
Tariffs and import costs: US apparel imports registered modest unit price increases in 2025, with men’s underwear reflecting elevated cost pressure amid prevailing tariff structures. Planning teams must treat trade policy as a recurring operating cost — not a one-off shock.
-
Raw material movement: World cotton prices declined in 2025, which translated into nearly flat unit prices for cotton apparel imports in the US. However, rising sustainability mandates increased costs for organic and recycled cotton sourcing, creating a two-speed cost environment between conventional cotton and sustainable inputs.
-
Regulatory asymmetry: Average tariffs for men’s underwear remain materially different from adjacent categories, contributing to sourcing arbitrage and near-term reshoring conversations in procurement committees.
Together, these forces are increasing complexity in procurement modeling: procurement leaders must now pair traditional cost-per-unit calculations with carbon-costing, tariff scenario planning, and validated supplier resilience assessments.
What the Report Contains — Practical Chapters for 2026 Execution
Our full study goes beyond market sizing to provide tools and frameworks you can operationalize this year. Key deliverables include:
-
Dynamic market model (2020–2032) with scenario toggles for price inflation, tariff shifts, and sustainability cost premiums.
-
Competitive playbooks for incumbents and challengers: positioning maps, channel matrices, and recommended KPI stacks for DTC, wholesale, and private-label strategies.
-
Sourcing decision toolkit: supplier scorecards, nearshoring vs. offshore TCO templates, and a fabric-cost sensitivity model that integrates raw material volatility and sustainability premiums.
-
M&A and partnership playbook: valuation checklists grounded in category multiples, integration risk heatmaps, and a short-list of strategic targets tailored by capability gaps.
-
Retail and assortment optimization matrices: SKU rationalization guidelines, promotional elasticity estimates, and play-tested approaches to balancing basics vs. fashion in omnichannel assortments.
-
Commercial growth modules: digital acquisition cohorts, LTV/CAC thresholds for DTC expansion, and conversion levers for subscription and replenishment models.
Each module is accompanied by reproducible Excel models and an executive presentation designed for Board-level deliberations in 2026.
Strategic Recommendations for 2026 Planning Cycles
-
Prioritize supply-flex playbooks: lock-in diversified suppliers, secure contingency capacity, and run tariff-impact scenarios weekly during procurement cycles. The combined effect of tariff asymmetry and the Gildan–Hanesbrands realignment means capacity and cost advantages will be transient if not actively managed.
-
Differentiate on product and occasion: allocate R&D and assortment investments based on margin-to-growth gradients. Basics will remain volume drivers; performance and sustainability premium SKUs will deliver margin expansion if supported by authentic supply chains and validated certifications.
-
Operationalize sustainability costs into pricing codes: with sustainability requirements raising input costs, accounting and pricing teams must adopt cost-plus and value-based pricing in parallel to preserve margin.
-
Reassess channel economics: DTC remains attractive for brand capture and data, but wholesale and big-box relationships are still indispensable for scale. Use the report’s channel matrices to define the right mix for 2026 growth targets.
-
Scan M&A opportunistically: the late-2025 consolidation wave has created both acquisition targets and potential buyer fatigue. Use our M&A playbook to determine optimal timing and integration priorities.
Use Cases — How Different Teams Should Leverage This Report
-
CEOs & Strategy Officers: scenario-tested growth roadmaps and M&A checklists crafted to support Board debate ahead of 2026 budgeting cycles.
-
COOs & Supply Chain Leaders: sourcing scorecards and tariff-scenario models to reduce margin leakage and improve resilience.
-
CMOs & Merchants: channel-specific assortment guidance and consumer segment primers that align product roadmaps with conversion economics.
-
Private Equity & Corporate Development: concise acquisition-opportunity briefs and integration playbooks for target diligence and post-deal value capture.
Why PW Consulting’s Approach Matters
Many market studies recount the past; few convert that knowledge into executable plans with quantifiable trade-offs. Our research ties historical market movement (USD 26.5 Billion in 2020 → USD 39.0 Billion in 2025) to explicit forecasts (5.5% CAGR across 2026–2032 to USD ~57.4 Billion) and then maps the operational levers that materially change outcomes for players at different scale and capability levels. We surface the competitive implications of recent events — such as the Gildan acquisition of Hanesbrands and PVH’s collection cadence — and translate regulatory and input price noise into procurement actions and pricing strategy adjustments.
Next Steps — Where to Find the Full Intelligence
This preview highlights the strategic salience of the men’s underwear market in 2026; our full report contains the segment-level breakdowns, channel share matrices, and downloadable models that informed the recommendations above. For teams that need to convert these insights into 2026 plans — from P&L re-forecasting to sourcing RFPs and M&A diligence — the full dataset, scenario models, and playbooks are available on the PW Consulting report page.
To ensure your 2026 planning cycle is grounded in the latest market reality and actionable rigor, consult the full Men’s Underwear Market report — it’s engineered to move decisions from debate to delivery.
For detailed analysis of this topic, please visit the official page: Men's Underwear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Alignment Systems Market to Soar from USD 1,345.0 Million in 2025 to USD 3,468.6 Million by 2032 at a 14.6% CAGR, Led by an USD 814.9M Laser Alignment Segment
By pmarketresearch, 2026-06-30
Alignment Systems Market — Strategic Imperatives for 2026: A PW Consulting Insight
PW Consulting’s new Alignment Systems Market report (base year 2025, forecast period 2026–2032) arrives at a pivotal moment for industrial automation, semiconductor packaging, and integrated photonics. Our analysis shows a robust long-term expansion driven by the convergence of high-precision optics, automation-enabled manufacturing, and system-level integration across multiple end markets. The alignment systems market nearly doubled in size over the 2020–2025 historical window and is forecast to continue expanding at a compound annual growth rate (CAGR) of 14.6% through 2032. This growth trajectory underscores why alignment technology choices made in 2026 will materially influence competitiveness and cost structures for manufacturers and integrators alike.
Alignment Systems Market
Why this report matters to 2026 decision-makers
-
Timing matters: With the market accelerating into a steeper growth phase from 2026, procurement cycles that previously prioritized lowest upfront cost will now be re-weighted toward throughput, repeatability, and ecosystem compatibility. Our report quantifies the trade-offs between capital intensity and lifetime cost for active vs. passive alignment approaches and provides timelines for when those trade-offs change in favor of automation.
Alignment Systems Market -
Risk management: Geopolitical and regulatory dynamics instituted in 2025 are shifting supply chain footprints and require near-term contingency planning. The report maps regulatory thresholds (certifications, export controls) and supply shock scenarios against vendor capabilities to prioritize immediate mitigations.
Alignment Systems Market -
Technology roadmaps: Integration of sub‑nanometer overlay requirements (notably for EUV-class lithography and next‑generation photonics) is changing sensor and actuator requirements. Our analysis links technology choices—sensor types, motion engines, and control architectures—to achievable yield curves in production environments.
What the report contains — practical deliverables for executives and practitioners
-
Executive summary with concise strategic recommendations tailored for procurement, R&D, and M&A teams.
-
Market sizing and validated forecast model (historical 2020–2025, base year 2025, forecast 2026–2032) including sensitivity analysis around key adoption drivers and downside shock scenarios.
-
Methodology appendix detailing data sources, primary interviews, and our bottom-up modeling approach—enabling clients to reproduce or adapt findings to bespoke internal assumptions.
-
Vendor benchmarking and a supplier capability matrix covering system architecture, throughput, modularity, software ecosystems, and service economics.
-
Regulatory, certification, and supply‑chain compliance playbook (ISO, ITAR, tariff implications) with practical checklists for supplier due diligence and contracting clauses.
-
Technology matrix and product roadmap comparison—showing where high-throughput automated alignment, active photonics alignment, and specialized wafer‑level systems are mature versus where further R&D is required.
-
Capex/Opex models and lifecycle TCO calculators to support leasing vs. purchase decisions and service-model design.
-
Scenario planning and strategic triggers that translate market projections into concrete decision points for scaling, partnering, or pausing investments.
Competitive landscape — who is shaping the next wave
The market displays meaningful concentration among leading system integrators and precision motion specialists (our CR3 and CR5 metrics indicate a high-but-not-absolute concentration in the leading tier). This structure creates a dual dynamic: established firms can set technical and commercial standards, but gaps in modularity and cost-efficiency leave space for targeted entrants and specialist carve-outs.
Two vendors exemplify contrasting strategic positions:
-
Physik Instrumente (PI) SE & Co. KG (Karlsruhe, Germany): A hardware and motion-systems leader with a clear focus on high-speed active photonics alignment. PI has doubled down on modular, multi-axis engines and piezo-based fine motion systems that address silicon photonics assembly and high-volume photonic integrated circuit (PIC) testing. Their 2026 demonstrations reinforced a product strategy aimed at industrial scale-up—cost-optimized modular six-axis solutions and piezo modules that prioritize deterministic throughput.
-
EV Group (EVG) (St. Florian am Inn, Austria): EVG’s strengths lie in wafer-to-wafer, mask, and bond alignment systems targeted at semiconductor packaging and MEMS production. Their systems are positioned where overlay precision, repeatable bond alignment, and lithography compatibility are table stakes—areas that will grow in importance as packaging complexity increases.
In addition to incumbents, specialized innovators are emerging. Notable recent activity includes a breakthrough in high‑accuracy multi‑channel fibre array alignment from a specialist within the quantum photonics ecosystem—an example of how niche advances can alter cost/performance envelopes for broader markets.
Key dynamics to account for in 2026 strategy
-
Tariff and trade policy effects: New tariffs enacted in 2025 have already shifted sourcing economics for precision components. Our scenarios model the pass-through impact to OEM pricing and identify mitigation via strategic nearshoring or bonded-manufacturing strategies.
-
Upfront capital vs. lifecycle performance: Active alignment systems require more sophisticated sensors and actuators, increasing initial capex relative to passive approaches. The report quantifies how initial capital premiums can be offset by improved yields, faster throughput, and lower rework rates over three-to-five year horizons.
-
Precision thresholds (EUV and advanced packaging): Sub-nanometer overlay and stability demands are driving investment into specialized sensor technologies and higher-performance motion platforms. Vendors that can demonstrate integrated metrology and closed-loop process control will command premium positions in high-end segments.
-
Localized photonics ecosystems: Regional initiatives accelerating integrated photonics pilot lines are changing adoption curves. Pilot-to-production transitions create windows for suppliers to lock in long-term manufacturing partnerships if they can meet scale and qualification timelines.
-
Standards and certifications: Compliance requirements (e.g., ISO certification and export control registrations) are an operating prerequisite for participation in international semiconductor supply chains. Our risk matrix highlights how non-compliance can preclude access to critical customers.
Strategic playbook for 2026 — prioritized actions
-
Immediate (0–6 months): Map your exposure to tariff-impacted components and initiate dual-sourcing pilots for critical sensors and actuators. Require supplier roadmaps and force‑rank their certification readiness (ISO/ITAR).
-
Near-term (6–18 months): Pilot active alignment modules in high-value production lines where yield sensitivity justifies higher capex. Use PW Consulting’s TCO model to decide between retrofit vs. greenfield deployments. Negotiate service-level agreements that convert part of capex into predictable Opex where feasible.
-
Medium-term (18–36 months): Invest in strategic partnerships or minority equity stakes with niche innovators that provide enabling subsystems (multi-channel fiber aligners, piezo actuators, advanced metrology). Consider bolt-on M&A to secure IP that materially shortens time-to-market for production-grade systems.
-
Organizational & talent: Build cross-functional teams that marry process engineering, systems integration, and controls software skills. Prioritize hiring control-systems engineers and metrology specialists; establish rotational programs with supplier partners to accelerate knowledge transfer.
-
Commercial & go-to-market: Shift from unit sales to outcome-based service contracts in high-volume lines (guaranteed throughput/yield). Develop ‘qualification as a service’ offerings to lower adoption friction for customers moving from pilot to production.
Scenario planning — decision triggers
-
Base case (aligned with our central forecast): Market continues to grow at ~14.6% CAGR; incremental investments in active alignment deliver positive ROI within 24–36 months in high-volume photonics and packaging lines. Trigger: sustained customer demand growth and validated yield improvements in pilot lines.
-
Upside: Faster-than-expected adoption of integrated photonics and packaging complexity accelerates demand; lead vendors scale rapidly. Trigger: announcement of major foundry/IDM capacity additions adopting automated alignment as a standard.
-
Downside: Prolonged trade restrictions or component shortages materially raise costs and slow adoption. Trigger: extended tariff escalations or export control expansions that block key sensor/actuator sources for more than two quarters.
How to use this report in board-level and operational planning
-
Link capital allocation decisions to scenario thresholds laid out in the report so investment committees can defer, accelerate, or structure staged funding based on observable market signals.
-
Use the supplier capability matrix during vendor selection to ensure alignment between technical roadmaps and procurement contracts—tactical clauses we recommend include performance milestones and qualification timelines tied to payment and warranty terms.
-
Adopt the regulatory and compliance checklist to accelerate cross-border qualification and reduce the risk of disqualification from critical supply chains.
PW Consulting’s Alignment Systems Market report is intentionally configured as a decision-ready tool: it combines rigorous market modelling, vendor benchmarking, regulatory mapping, and executable playbooks. This news release has highlighted strategic takeaways and the decision-use value of our research while withholding the detailed subsegment worksheets and proprietary vendor scoring that we reserve for the full report. Those core breakdowns—critical for vendor selection, regional capacity planning, and capex approval packs—are accessible in the full publication.
For procurement leaders, R&D heads, and corporate strategists preparing 2026 roadmaps, this report provides the evidence base and operational templates to move from analysis to action. To download the full report or arrange a tailored briefing, visit PW Consulting’s market reports page or contact our industry leads for a private walkthrough and scenario clinic.
For detailed analysis of this topic, please visit the official page: Alignment Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: CAFM Market Poised to Rise from USD 1,210 Million in 2025 to USD 2,101.5 Million by 2032, Driven by an 8.2% CAGR
By pmarketresearch, 2026-06-30
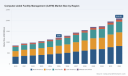
CAFM Market 2026 Strategic Brief: Why Facility Leaders Must Recalibrate Plans Now
Executive snapshot
As organizations prepare capital and operational budgets for 2026, Computer-aided Facility Management (CAFM) is no longer a back-office efficiency play — it is a strategic lever for resilience, regulatory compliance, and ESG delivery. PW Consulting’s latest CAFM Market report (base year 2025) synthesizes five years of historical performance and a seven-year forward view to 2032, delivering an evidence-based narrative that links technology choices to measurable enterprise outcomes. The market that expanded robustly through 2020–2025 continues to accelerate, with a compound annual growth rate of 8.2% underpinning the forecast horizon.
Computer-aided Facility Management (CAFM) Market
Why this report matters for 2026 decision cycles
- Timing: Procurement and vendor consolidation cycles in facility services and real estate typically span 12–24 months. Decisions made in 2026 will lock in platforms and integrations that determine capabilities through 2030 and beyond.
- Complexity: CAFM now intersects with asset lifecycle, workplace experience, compliance reporting, and sustainability metrics. Executives require a single, trusted source that maps vendor functionality to regulatory and operational obligations.
- Risk mitigation: A growing regulatory and data-privacy burden elevates the cost of non-compliance. Facility leaders need quantitative scenarios — not just feature checklists — to justify cloud/on-premises trade-offs, outsourcing, and security investments.
Market trajectory — the macro view
PW Consulting’s topline sizing places the CAFM market at a clear inflection point by the 2025 base year. After consistent expansion through the historical window, our forecast to 2032 models continued double-digit-equivalent growth in many adoption pockets, driven primarily by digital transformation initiatives across commercial, institutional, and industrial portfolios. The modeled growth path reflects an 8.2% CAGR across the forecast period, with total market value projected to materially increase from the 2025 base. This trajectory embeds scenarios for accelerated cloud migration, AI-enabled predictive maintenance, and integrations with enterprise IWMS/ERP stacks.
Computer-aided Facility Management (CAFM) Market
Key market dynamics shaping vendor and buyer strategies
- Regulatory and safety monitoring: CAFM platforms are being pressed into service as continuous monitoring systems. Machine learning models now support automated checks that can flag compliance deviations and equipment safety risks in real time, turning CAFM into a compliance-first technology.
- Data privacy and cybersecurity: The cost and complexity of meeting GDPR, CCPA, and region-specific privacy regimes are material. Buyers must assess vendor capabilities across encryption, tenancy, auditability, and breach response as first-order procurement criteria.
- Sustainability and ESG reporting: Facility managers are increasingly the custodians of ESG data — from energy consumption to space-utilization emissions. CAFM solutions that embed automated data capture and standardized reporting frameworks will command premium attention from corporate sustainability teams.
- Labor and skill shifts: Automation reduces routine task load but increases demand for analytics, vendor management, and digital process design skills. Workforce planning must therefore anticipate reskilling requirements tied to CAFM rollouts.
Competitive landscape — what the leading vendors are doing
The CAFM vendor field remains moderately fragmented and competitive, with established enterprise vendors and specialist providers co-existing. PW Consulting’s competitive analysis focuses on product strategy, integration posture, route-to-market, and recent strategic moves.
Computer-aided Facility Management (CAFM) Market
- IBM Corporation — IBM leverages its Maximo and Tririga heritage to position CAFM capabilities within broader enterprise asset and operations management suites. Their strength is in deep integration with large-scale enterprise estates and advanced analytics; clients seeking enterprise-grade lifecycle management value IBM’s platform for its extensibility and governance capabilities.
- Planon Corporation — Planon continues to pursue an IWMS-first strategy, emphasizing built-in modules for space management and sustainability. Their appeal is strongest where clients prioritize end-to-end real estate and operations workflows within a single platform.
- FM:Systems (Johnson Controls) — FM:Systems has been active on certification and integration fronts. Notably, recent secure-authority accomplishments and tighter integrations with building automation ecosystems (e.g., Johnson Controls Metasys integrations) enhance their suitability for regulated and government-adjacent portfolios.
- Accruent — Accruent’s CAFM strategy centers on unified operations, maintenance, and compliance tracking. Their platform is frequently chosen where clients need rapid deployment and strong downstream vendor management capabilities.
- MRI Software — MRI bridges real estate management and facilities operations. Organizations focused on the intersection of lease/accounting processes and facilities workflows find MRI’s approach pragmatic for minimizing data friction between finance and operations.
- Eptura — Eptura, with its Archibus lineage, is positioning new worktech innovations to address urgent workspace and asset problems, particularly in complex public-sector and large-enterprise environments.
- ServiceChannel — ServiceChannel retains a distinct foothold on maintenance workflows and vendor performance management, which makes them a frequent choice where CMMS integration and field-service orchestration are mission-critical.
PW Consulting’s vendor benchmarking synthesizes these strategic postures into actionable vendor-selection matrices, but the full matrices and scoring weightings are reserved for the report to preserve our clients’ competitive intelligence advantage.
Recent vendor moves to watch
- Product refreshes and worktech launches are accelerating the convergence of workplace experience and facilities operations.
- Security and compliance certifications (including government-oriented accreditations) are becoming determinative in public-sector procurement.
- Cross-vendor integrations between CAFM and building automation suppliers are shortening time-to-value for predictive maintenance use cases.
What PW Consulting’s CAFM Market report delivers (practical, board-ready outputs)
Our report is structured for immediate use by C-suite sponsors, procurement teams, and technical leaders who must link CAFM vendor choices to capital planning and regulatory obligations. Highlights include:
- Topline market sizing and a year-by-year forecast through 2032, with modeled scenarios for cloud adoption, AI-enabled services, and regulatory tailwinds.
- A dynamics chapter that quantifies the impact of data-privacy regulation, compliance automation, and labor cost shifts on total cost of ownership and time-to-value.
- Vendor profiles and a competitive landscape that map capability differentials (integration depth, analytics maturity, deployment flexibility, security posture) without disclosing client-sensitive benchmarks.
- Decision frameworks for CIOs and facility heads to evaluate cloud vs. on-premises trade-offs, contract structures, and managed-services models.
- Implementation playbooks and risk-mitigation checklists — from phased rollouts to data governance templates — designed to reduce migration risk and accelerate realization of operational KPIs.
- M&A and partnership opportunity scan for private equity and strategic buyers seeking inorganic routes to capability or geographic expansion.
Strategic recommendations for 2026 planning
- Adopt a capability-first procurement approach: Prioritize use-case outcomes (predictive maintenance, compliance automation, ESG measurement) rather than feature parity. This forces vendors to price outcomes, making ROI transparent.
- Design for data portability and auditability: Insist on open APIs, exportable audit trails, and standardized telemetry schemas to mitigate vendor lock-in and simplify compliance reporting.
- Stagger modernization into three tranches: stabilize core maintenance and compliance workflows, deploy analytics for predictive insights, and then optimize workplace experience and tenant services.
- Budget for governance and skills: Allocate 10–15% of implementation budgets to change management, data governance, and cybersecurity hardening—short-term investments that materially reduce operational risk.
- Use certification and integration as gating criteria for high-risk estates: Government, healthcare, and critical infrastructure portfolios should elevate security and certification requirements in RFPs.
How PW Consulting supports executive decision-making
Beyond delivering the report, PW Consulting offers tailored advisory packages including vendor selection facilitation, RFP design, implementation oversight, and post-go-live benefits tracking. Our approach translates market-level insights into procurement and transformation actions — with deliverables such as vendor shortlists aligned to specific risk appetites, contractual guardrails, and a KPI roadmap tied to finance and sustainability goals.
Conclusion — the call to action for 2026
For organizations that treat facilities as strategic infrastructure rather than cost centers, the next 18 months represent a window to lock in capabilities that materially reduce risk and unlock operational alpha. PW Consulting’s CAFM Market report provides the macro context, vendor intelligence, and implementation rigor needed to make those decisions with confidence. To preserve the actionable edge and access our full datasets, segmentation tables, and vendor scoring details, please consult the full report on our website. The executive summary available here is a strategic primer — the complete analysis is the operational playbook you’ll want at the negotiating table.
For detailed analysis of this topic, please visit the official page: Computer-aided Facility Management (CAFM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com