

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Alignment Systems Market to Soar from USD 1,345.0 Million in 2025 to USD 3,468.6 Million by 2032 at a 14.6% CAGR, Led by an USD 814.9M Laser Alignment Segment

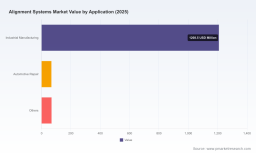
Alignment Systems Market — Strategic Imperatives for 2026: A PW Consulting Insight
PW Consulting’s new Alignment Systems Market report (base year 2025, forecast period 2026–2032) arrives at a pivotal moment for industrial automation, semiconductor packaging, and integrated photonics. Our analysis shows a robust long-term expansion driven by the convergence of high-precision optics, automation-enabled manufacturing, and system-level integration across multiple end markets. The alignment systems market nearly doubled in size over the 2020–2025 historical window and is forecast to continue expanding at a compound annual growth rate (CAGR) of 14.6% through 2032. This growth trajectory underscores why alignment technology choices made in 2026 will materially influence competitiveness and cost structures for manufacturers and integrators alike.
Alignment Systems Market
Why this report matters to 2026 decision-makers
-
Timing matters: With the market accelerating into a steeper growth phase from 2026, procurement cycles that previously prioritized lowest upfront cost will now be re-weighted toward throughput, repeatability, and ecosystem compatibility. Our report quantifies the trade-offs between capital intensity and lifetime cost for active vs. passive alignment approaches and provides timelines for when those trade-offs change in favor of automation.
Alignment Systems Market -
Risk management: Geopolitical and regulatory dynamics instituted in 2025 are shifting supply chain footprints and require near-term contingency planning. The report maps regulatory thresholds (certifications, export controls) and supply shock scenarios against vendor capabilities to prioritize immediate mitigations.
Alignment Systems Market -
Technology roadmaps: Integration of sub‑nanometer overlay requirements (notably for EUV-class lithography and next‑generation photonics) is changing sensor and actuator requirements. Our analysis links technology choices—sensor types, motion engines, and control architectures—to achievable yield curves in production environments.
What the report contains — practical deliverables for executives and practitioners
-
Executive summary with concise strategic recommendations tailored for procurement, R&D, and M&A teams.
-
Market sizing and validated forecast model (historical 2020–2025, base year 2025, forecast 2026–2032) including sensitivity analysis around key adoption drivers and downside shock scenarios.
-
Methodology appendix detailing data sources, primary interviews, and our bottom-up modeling approach—enabling clients to reproduce or adapt findings to bespoke internal assumptions.
-
Vendor benchmarking and a supplier capability matrix covering system architecture, throughput, modularity, software ecosystems, and service economics.
-
Regulatory, certification, and supply‑chain compliance playbook (ISO, ITAR, tariff implications) with practical checklists for supplier due diligence and contracting clauses.
-
Technology matrix and product roadmap comparison—showing where high-throughput automated alignment, active photonics alignment, and specialized wafer‑level systems are mature versus where further R&D is required.
-
Capex/Opex models and lifecycle TCO calculators to support leasing vs. purchase decisions and service-model design.
-
Scenario planning and strategic triggers that translate market projections into concrete decision points for scaling, partnering, or pausing investments.
Competitive landscape — who is shaping the next wave
The market displays meaningful concentration among leading system integrators and precision motion specialists (our CR3 and CR5 metrics indicate a high-but-not-absolute concentration in the leading tier). This structure creates a dual dynamic: established firms can set technical and commercial standards, but gaps in modularity and cost-efficiency leave space for targeted entrants and specialist carve-outs.
Two vendors exemplify contrasting strategic positions:
-
Physik Instrumente (PI) SE & Co. KG (Karlsruhe, Germany): A hardware and motion-systems leader with a clear focus on high-speed active photonics alignment. PI has doubled down on modular, multi-axis engines and piezo-based fine motion systems that address silicon photonics assembly and high-volume photonic integrated circuit (PIC) testing. Their 2026 demonstrations reinforced a product strategy aimed at industrial scale-up—cost-optimized modular six-axis solutions and piezo modules that prioritize deterministic throughput.
-
EV Group (EVG) (St. Florian am Inn, Austria): EVG’s strengths lie in wafer-to-wafer, mask, and bond alignment systems targeted at semiconductor packaging and MEMS production. Their systems are positioned where overlay precision, repeatable bond alignment, and lithography compatibility are table stakes—areas that will grow in importance as packaging complexity increases.
In addition to incumbents, specialized innovators are emerging. Notable recent activity includes a breakthrough in high‑accuracy multi‑channel fibre array alignment from a specialist within the quantum photonics ecosystem—an example of how niche advances can alter cost/performance envelopes for broader markets.
Key dynamics to account for in 2026 strategy
-
Tariff and trade policy effects: New tariffs enacted in 2025 have already shifted sourcing economics for precision components. Our scenarios model the pass-through impact to OEM pricing and identify mitigation via strategic nearshoring or bonded-manufacturing strategies.
-
Upfront capital vs. lifecycle performance: Active alignment systems require more sophisticated sensors and actuators, increasing initial capex relative to passive approaches. The report quantifies how initial capital premiums can be offset by improved yields, faster throughput, and lower rework rates over three-to-five year horizons.
-
Precision thresholds (EUV and advanced packaging): Sub-nanometer overlay and stability demands are driving investment into specialized sensor technologies and higher-performance motion platforms. Vendors that can demonstrate integrated metrology and closed-loop process control will command premium positions in high-end segments.
-
Localized photonics ecosystems: Regional initiatives accelerating integrated photonics pilot lines are changing adoption curves. Pilot-to-production transitions create windows for suppliers to lock in long-term manufacturing partnerships if they can meet scale and qualification timelines.
-
Standards and certifications: Compliance requirements (e.g., ISO certification and export control registrations) are an operating prerequisite for participation in international semiconductor supply chains. Our risk matrix highlights how non-compliance can preclude access to critical customers.
Strategic playbook for 2026 — prioritized actions
-
Immediate (0–6 months): Map your exposure to tariff-impacted components and initiate dual-sourcing pilots for critical sensors and actuators. Require supplier roadmaps and force‑rank their certification readiness (ISO/ITAR).
-
Near-term (6–18 months): Pilot active alignment modules in high-value production lines where yield sensitivity justifies higher capex. Use PW Consulting’s TCO model to decide between retrofit vs. greenfield deployments. Negotiate service-level agreements that convert part of capex into predictable Opex where feasible.
-
Medium-term (18–36 months): Invest in strategic partnerships or minority equity stakes with niche innovators that provide enabling subsystems (multi-channel fiber aligners, piezo actuators, advanced metrology). Consider bolt-on M&A to secure IP that materially shortens time-to-market for production-grade systems.
-
Organizational & talent: Build cross-functional teams that marry process engineering, systems integration, and controls software skills. Prioritize hiring control-systems engineers and metrology specialists; establish rotational programs with supplier partners to accelerate knowledge transfer.
-
Commercial & go-to-market: Shift from unit sales to outcome-based service contracts in high-volume lines (guaranteed throughput/yield). Develop ‘qualification as a service’ offerings to lower adoption friction for customers moving from pilot to production.
Scenario planning — decision triggers
-
Base case (aligned with our central forecast): Market continues to grow at ~14.6% CAGR; incremental investments in active alignment deliver positive ROI within 24–36 months in high-volume photonics and packaging lines. Trigger: sustained customer demand growth and validated yield improvements in pilot lines.
-
Upside: Faster-than-expected adoption of integrated photonics and packaging complexity accelerates demand; lead vendors scale rapidly. Trigger: announcement of major foundry/IDM capacity additions adopting automated alignment as a standard.
-
Downside: Prolonged trade restrictions or component shortages materially raise costs and slow adoption. Trigger: extended tariff escalations or export control expansions that block key sensor/actuator sources for more than two quarters.
How to use this report in board-level and operational planning
-
Link capital allocation decisions to scenario thresholds laid out in the report so investment committees can defer, accelerate, or structure staged funding based on observable market signals.
-
Use the supplier capability matrix during vendor selection to ensure alignment between technical roadmaps and procurement contracts—tactical clauses we recommend include performance milestones and qualification timelines tied to payment and warranty terms.
-
Adopt the regulatory and compliance checklist to accelerate cross-border qualification and reduce the risk of disqualification from critical supply chains.
PW Consulting’s Alignment Systems Market report is intentionally configured as a decision-ready tool: it combines rigorous market modelling, vendor benchmarking, regulatory mapping, and executable playbooks. This news release has highlighted strategic takeaways and the decision-use value of our research while withholding the detailed subsegment worksheets and proprietary vendor scoring that we reserve for the full report. Those core breakdowns—critical for vendor selection, regional capacity planning, and capex approval packs—are accessible in the full publication.
For procurement leaders, R&D heads, and corporate strategists preparing 2026 roadmaps, this report provides the evidence base and operational templates to move from analysis to action. To download the full report or arrange a tailored briefing, visit PW Consulting’s market reports page or contact our industry leads for a private walkthrough and scenario clinic.
For detailed analysis of this topic, please visit the official page: Alignment Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com