

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Enterprise Search Market Set to Reach USD 7.61 Billion by 2032 at 8.99% CAGR — Cloud Leads with USD 2.39 Billion (2025)

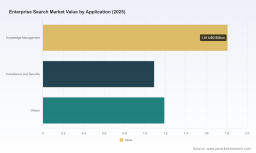
Enterprise Search Market 2026: A Strategic Briefing for CIOs, CPOs and Procurement Leaders
PW Consulting’s latest market study on the Enterprise Search Market (base year 2025) is designed as a decision-grade playbook for leaders planning investments and vendor strategies in 2026. Our analysis shows the market reaching USD 4.09 Billion in 2025 and continuing to expand to an estimated USD 7.61 Billion by 2032, reflecting a compound annual growth rate (CAGR) of 8.99% over the forecast window. These headline numbers capture a clear truth: the enterprise search layer is moving from a productivity enabler to a strategic platform that underpins knowledge work, compliance, and AI-driven automation.
Enterprise Search Market
Why this report matters for enterprise decision-makers in 2026
-
Timing: 2026 is a hinge year. Regulatory enforcement, cloud sovereignty moves, and a new wave of agentic and semantic search capabilities are converging — forcing procurement and architecture decisions that will have multi-year cost and compliance consequences.
Enterprise Search Market -
Clarity for investment: With near-term budgets tightening, IT and business leaders need a concise framework that prioritizes use cases where search drives measurable ROI (e.g., time-to-insight, case resolution, developer productivity) rather than vendor feature lists.
Enterprise Search Market -
Vendor selection risk mitigation: The market is commercially vibrant but remains moderately fragmented; choosing a partner without a clear governance model or compliance posture will create hidden costs and integration friction.
Market trajectory — what’s driving the next wave of growth
Enterprise search is expanding along three intersecting vectors. First, the semantic and agentic wave: mature embeddings, retrieval-augmented generation (RAG) patterns, and agent layers are turning search from document retrieval into task orchestration and decision support. Second, the unstructured-data imperative: enterprises still have massive volumes of documents, chat, and siloed systems that only search and knowledge graphs can knit together efficiently. Third, commercial model evolution: the shift to consumption-based cloud pricing and global points of presence has made search platforms easier to adopt at scale, accelerating deployments in customer service, knowledge management, and internal productivity applications.
Historically, the market has grown steadily from its early 2020s baseline and, as our forecasts show, continues to compound at roughly 9% per year through 2032. This pace reflects both organic adoption and expansion of addressable use cases as search platforms embed AI-native capabilities and cross-application workflows.
Regulatory and infrastructure dynamics — negotiation points for 2026
Regulation and data-residency requirements are no longer hypothetical risks — they are forcing architectural choices. The upcoming enforcement of new AI legislation in the EU introduces explainability, transparency, and accountability obligations for high-impact applications, which directly affects search and AI systems used in recruitment, credit, insurance, and healthcare. At the same time, European cloud initiatives and sovereign cloud mandates are raising the bar for data locality, compliance certifications, and interoperability. Our analysis finds that compliance-driven architectures materially increase vendor integration and operational costs, and these delta costs must be modeled explicitly in procurement decisions.
Other practical dynamics to factor into 2026 planning:
-
Sovereign cloud mandates are accelerating hybrid and multi-cloud deployments: sensitive datasets are increasingly retained on-premises or in sovereign clouds while index and inference layers may sit in public cloud. That hybrid split creates new operational and integration complexity that few organizations are operationally prepared for.
-
Enterprise sustainability and infrastructure requirements — such as supplier PUE and renewable energy commitments — are being written into cloud provider eligibility criteria, increasing the procurement checklist beyond purely technical or commercial metrics.
-
Vendors and customers face higher compliance execution costs post-2026; PW Consulting’s scenario analysis shows a significant uplift to compliance-related TCO that must be stress-tested in vendor RFPs.
Competitive landscape — practical read on the vendor field
The enterprise search ecosystem is populated by a mix of specialist platform vendors and hyperscale cloud incumbents. The market is best thought of as an architecture ecosystem rather than a winner-takes-all product contest — different vendors lead on integration, AI capabilities, or deployment models, and enterprises should match vendor strengths to specific use cases.
-
Glean — Rapid product innovation focused on workplace search with deep app connectors, permissions-aware knowledge graphs and emerging agentic features. Recent product milestones indicate a push toward automated model selection and agent-assisted multi-application workflows, and the vendor has accelerated go-to-market moves into on-prem and partner-delivered deployments.
-
Coveo — Positioned as a platform that blends enterprise search with personalization and recommendations; attractive for organizations that need unified customer-facing and employee-facing search experiences backed by behavioral signals.
-
Lucidworks — Focuses on relevance tuning, content intelligence and operationalization at scale. Their signaling and automation tooling is a strong fit for data-rich search implementations that require continuous optimization.
-
Microsoft — Tight integration with Microsoft 365 and Graph, plus Copilot Search, makes Microsoft the pragmatic choice for organizations deeply invested in M365 productivity suites and seeking native semantics across Outlook, Teams, SharePoint and OneDrive.
-
Google — Developer-centric search capabilities and cloud search products that appeal to firms building RAG-native experiences and needing advanced model tooling from Vertex AI.
-
IBM and AWS — Enterprise-grade offerings (watsonx, Kendra) designed for regulated industries and large-scale knowledge discovery, with strong integration into respective cloud and software ecosystems.
-
Elastic — The open-source stack play, viable for teams that prioritize customization, self-hosting and open architecture for scalable semantic search deployments.
Across this vendor landscape, the competitive dynamic is shaped less by single-feature differentials and more by four procurement criteria: integration breadth (connectors and permissions-awareness), AI governance (explainability and safety), compliance posture (sovereign-cloud and audit readiness), and operational economics (TCO under compliance scenarios). PW Consulting’s scoring models in the full report quantify these trade-offs for multiple buyer archetypes.
Actionable playbook — five pragmatic moves for 2026
-
Start with outcome-driven use cases. Prioritize three near-term, high-value uses (e.g., legal e-discovery acceleration, frontline support resolution, R&D knowledge synthesis) and design pilots that map directly to measurable KPIs.
-
Design an explicit data strategy for hybrid environments. Create a data residency map, classify sensitivity, and specify which assets must remain on-prem or in sovereign clouds versus what can be indexed in public clouds.
-
Require AI governance artifacts in RFPs. Ask for model provenance, explainability reports, red-teaming results, and operational monitoring plans as contract deliverables — not optional features.
-
Include compliance uplift in TCO models. Stress-test vendor economics under regulatory compliance and sovereign-cloud scenarios; include transition costs, certification timelines and energy/sustainability commitments.
-
Adopt a modular procurement stance. Favor platforms that provide well-documented APIs, connector ecosystems, and the ability to replace inference components or models without rearchitecting the index layer.
What PW Consulting’s full report contains
This briefing intentionally surfaces strategic insights while withholding granular segmentation and vendor scorecards reserved for the full report. The complete study includes:
-
Detailed historical and forecast market sizing at multiple aggregation levels with scenario runs and sensitivity analysis;
-
Vendor benchmarking across integration, AI capabilities, compliance posture and TCO under multiple deployment scenarios;
-
Procurement and implementation checklists, RFP templates, and a practical 90-day pilot playbook;
-
Regulatory impact models that quantify incremental compliance cost and operational timelines for EU AI Act and sovereign cloud mandates;
-
Case studies showing measurable business outcomes from enterprise search implementations across regulated industries.
Next steps
For enterprise leaders who must align budget cycles, negotiate vendor contracts, or define 2026 roadmaps, this PW Consulting study is intended to be the single-vendor-neutral reference that translates market momentum into pragmatic procurement and architecture decisions. To access the full dataset, vendor scorecards and implementation toolkits, please download the complete report from PW Consulting’s website or contact our Enterprise Search advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Enterprise Search Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com