

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Men's Underwear Market Tops USD 39.0 Billion in 2025, Set for 5.5% CAGR to USD 57.4 Billion by 2032 as Asia‑Pacific Leads at USD 16.17 Billion

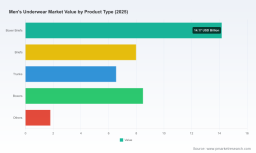
Men’s Underwear Market 2026: Strategic Preview — Why This Report Will Shape Your Decisions This Year
PW Consulting’s latest market research on the global Men’s Underwear market is designed as a practical strategic tool for executive teams preparing for the competitive inflection points of 2026. Built on a robust historical series (2020–2025) and an explicit forecast window (2026–2032), the study combines rigorous market sizing, competitive mapping, cost-pressure diagnostics, and implementation-ready playbooks to translate signal into action. This briefing highlights the most consequential insights and the specific ways our report empowers better decisions — while reserving the granular segment-level tables and proprietary model outputs for subscribers and the source web page.
Men's Underwear Market
Market Trajectory: The Numbers that Matter
The men’s underwear market has demonstrated steady expansion through the early 2020s, growing from USD 26.5 Billion in 2020 to USD 39.0 Billion in 2025. Looking forward, our central forecast projects the market to continue expanding at a 5.5% CAGR over the 2026–2032 period, reaching approximately USD 57.4 Billion by 2032. In short, the category remains a reliable growth portfolio in apparel — large enough to attract strategic investment, consolidated enough to reward scale, and dynamic enough to create new white-space opportunities for incumbents and challengers alike.
Men's Underwear Market
Why 2026 Is a Strategic Inflection Point
-
Transitioning cost structures: Input and tariff dynamics that crystallized in 2024–2025 mean 2026 will be the first full planning year in which firms can operationalize new sourcing and pricing strategies adopted late last year.
Men's Underwear Market -
Consolidation aftershocks: The M&A activity of late 2025 materially alters competitive bargaining power and supply footprints, creating short- to medium-term advantages for acquirers but also raising the bar for nimble independents.
-
Consumer premiumization and sustainability: Shifts in consumer willingness-to-pay for performance fabrics and responsible sourcing are redefining assortment strategies across channels, placing innovation and traceability at the center of near-term growth plays.
Competitive Landscape — Structure and Strategic Postures
The men’s underwear sector shows clear concentration: our CR3 sits at roughly 72% while CR5 approaches 80%, signaling a market where a few large groups define scale economics and distribution pull. For strategy teams, this concentration implies two concurrent realities: large players control wholesale and global retail access, and smaller brands must differentiate on product, channel agility, or brand narrative to sustain margin.
-
PVH Corp (Calvin Klein, etc.) — headquartered in New York, PVH leverages global brand equity and fashion-led product rhythms to command a premium intersection of style and distribution. Their recent collection refresh in Fall 2025 underscores a continued focus on design-led, higher-margin assortments.
-
Hanesbrands / Gildan (post-acquisition) — historically a scale-focused supplier emphasizing value and broad retail penetration, the December 2025 Gildan acquisition reconfigures the competitive map by combining sizable manufacturing and private-label capabilities into a single operating platform.
-
Jockey International — known for fit and heritage positioning, Jockey’s strength is in product reliability and retailer relationships, allowing it to defend share in core channels even as fashion-driven brands press higher.
-
Saxx, Pico Manufacturing, Argus Apparel, Sigma Apparel — these players represent the innovation and private-label vectors: performance-led niche brands, specialized contract manufacturers, and regional apparel houses that are sources of product differentiation and supply resilience for larger retailers.
Collectively, this topology creates strategic windows for: (a) scale consolidation plays, (b) premiumization and DTC-led brand extensions, and (c) contract manufacturing partnerships optimized for speed and margin.
Cost & Regulatory Dynamics: Inputs That Will Rewrite Margins
-
Tariffs and import costs: US apparel imports registered modest unit price increases in 2025, with men’s underwear reflecting elevated cost pressure amid prevailing tariff structures. Planning teams must treat trade policy as a recurring operating cost — not a one-off shock.
-
Raw material movement: World cotton prices declined in 2025, which translated into nearly flat unit prices for cotton apparel imports in the US. However, rising sustainability mandates increased costs for organic and recycled cotton sourcing, creating a two-speed cost environment between conventional cotton and sustainable inputs.
-
Regulatory asymmetry: Average tariffs for men’s underwear remain materially different from adjacent categories, contributing to sourcing arbitrage and near-term reshoring conversations in procurement committees.
Together, these forces are increasing complexity in procurement modeling: procurement leaders must now pair traditional cost-per-unit calculations with carbon-costing, tariff scenario planning, and validated supplier resilience assessments.
What the Report Contains — Practical Chapters for 2026 Execution
Our full study goes beyond market sizing to provide tools and frameworks you can operationalize this year. Key deliverables include:
-
Dynamic market model (2020–2032) with scenario toggles for price inflation, tariff shifts, and sustainability cost premiums.
-
Competitive playbooks for incumbents and challengers: positioning maps, channel matrices, and recommended KPI stacks for DTC, wholesale, and private-label strategies.
-
Sourcing decision toolkit: supplier scorecards, nearshoring vs. offshore TCO templates, and a fabric-cost sensitivity model that integrates raw material volatility and sustainability premiums.
-
M&A and partnership playbook: valuation checklists grounded in category multiples, integration risk heatmaps, and a short-list of strategic targets tailored by capability gaps.
-
Retail and assortment optimization matrices: SKU rationalization guidelines, promotional elasticity estimates, and play-tested approaches to balancing basics vs. fashion in omnichannel assortments.
-
Commercial growth modules: digital acquisition cohorts, LTV/CAC thresholds for DTC expansion, and conversion levers for subscription and replenishment models.
Each module is accompanied by reproducible Excel models and an executive presentation designed for Board-level deliberations in 2026.
Strategic Recommendations for 2026 Planning Cycles
-
Prioritize supply-flex playbooks: lock-in diversified suppliers, secure contingency capacity, and run tariff-impact scenarios weekly during procurement cycles. The combined effect of tariff asymmetry and the Gildan–Hanesbrands realignment means capacity and cost advantages will be transient if not actively managed.
-
Differentiate on product and occasion: allocate R&D and assortment investments based on margin-to-growth gradients. Basics will remain volume drivers; performance and sustainability premium SKUs will deliver margin expansion if supported by authentic supply chains and validated certifications.
-
Operationalize sustainability costs into pricing codes: with sustainability requirements raising input costs, accounting and pricing teams must adopt cost-plus and value-based pricing in parallel to preserve margin.
-
Reassess channel economics: DTC remains attractive for brand capture and data, but wholesale and big-box relationships are still indispensable for scale. Use the report’s channel matrices to define the right mix for 2026 growth targets.
-
Scan M&A opportunistically: the late-2025 consolidation wave has created both acquisition targets and potential buyer fatigue. Use our M&A playbook to determine optimal timing and integration priorities.
Use Cases — How Different Teams Should Leverage This Report
-
CEOs & Strategy Officers: scenario-tested growth roadmaps and M&A checklists crafted to support Board debate ahead of 2026 budgeting cycles.
-
COOs & Supply Chain Leaders: sourcing scorecards and tariff-scenario models to reduce margin leakage and improve resilience.
-
CMOs & Merchants: channel-specific assortment guidance and consumer segment primers that align product roadmaps with conversion economics.
-
Private Equity & Corporate Development: concise acquisition-opportunity briefs and integration playbooks for target diligence and post-deal value capture.
Why PW Consulting’s Approach Matters
Many market studies recount the past; few convert that knowledge into executable plans with quantifiable trade-offs. Our research ties historical market movement (USD 26.5 Billion in 2020 → USD 39.0 Billion in 2025) to explicit forecasts (5.5% CAGR across 2026–2032 to USD ~57.4 Billion) and then maps the operational levers that materially change outcomes for players at different scale and capability levels. We surface the competitive implications of recent events — such as the Gildan acquisition of Hanesbrands and PVH’s collection cadence — and translate regulatory and input price noise into procurement actions and pricing strategy adjustments.
Next Steps — Where to Find the Full Intelligence
This preview highlights the strategic salience of the men’s underwear market in 2026; our full report contains the segment-level breakdowns, channel share matrices, and downloadable models that informed the recommendations above. For teams that need to convert these insights into 2026 plans — from P&L re-forecasting to sourcing RFPs and M&A diligence — the full dataset, scenario models, and playbooks are available on the PW Consulting report page.
To ensure your 2026 planning cycle is grounded in the latest market reality and actionable rigor, consult the full Men’s Underwear Market report — it’s engineered to move decisions from debate to delivery.
For detailed analysis of this topic, please visit the official page: Men's Underwear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com