

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Tailgating Detection Market Set to Reach USD 92.58 Million by 2032, Growing at a 7.4% CAGR — PW Consulting

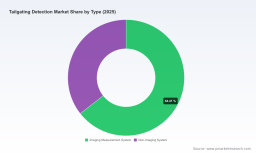
Tailgating Detection Market 2026: Strategic Signals for Secure Entry Investment
Executive Snapshot
As enterprises recalibrate physical and cyber security postures for a hybrid world, tailgating detection has moved from a niche add-on to a core component of modern access control. PW Consulting’s latest market study (base year 2025) shows how a focused convergence of AI-driven video analytics, multi-sensor fusion, and cloud-native access platforms is reshaping how organizations prevent unauthorized entry. The market expanded significantly across 2020–2025 and, propelled by ongoing digitalization and regulatory momentum, is forecast to continue expanding through the 2026–2032 window at a compound annual growth rate of 7.4%.
Tailgating Detection Market
Why 2026 Is a Decisive Year for Enterprise Decision-Makers
-
Procurement cycles are shortening; organizations want deployable solutions that demonstrate measurable reductions in unauthorized entries and clear integration paths into broader building management systems.
Tailgating Detection Market -
Regulatory and standards activity is converging on tailgating detection as a recognized security control in biometric and access-control frameworks, increasing mandatory requirements in public tenders and critical infrastructure projects.
Tailgating Detection Market -
Vendors are moving rapidly from proof-of-concept to operationalized offerings—integrated appliances, edge AI, and cloud orchestration are now table stakes for sustainable deployments.
Market Trajectory: What the Numbers Tell Us
PW Consulting’s analysis highlights a clear maturation curve. The market has scaled materially since 2020 and reached a meaningful base by 2025, reflecting both new deployments and retrofit activity. Our forecast to 2032 shows continued expansion, underscoring persistent buyer demand and steady technology refresh cycles. Importantly, market concentration is non-trivial: the top three vendors account for a majority share, and the top five command a pronounced share of industry revenue—an indicator of vendor leadership and consolidation trends that buyers must factor into strategic sourcing decisions.
Practical Value of the Report for 2026 Decision Cycles
-
Investment Prioritization: Our report maps where tailgating detection delivers the fastest risk-adjusted returns across enterprise classes—supporting capital allocation decisions for 2026 budgets without overcommitting to one technology strand.
-
Vendor Selection Playbook: We distill vendor strengths and fit-for-purpose evaluations, enabling procurement teams to shortlist solutions based on operational constraints (throughput, environmental conditions, integration points) rather than marketing claims.
-
Deployment Risk Matrix: The report provides an execution-oriented checklist—covering site surveys, sensor placement, network and bandwidth planning, and staged pilot designs—to reduce implementation surprises.
-
Compliance and RFP Language: We supply templated language and requirement constructs that align with current standards activity and federal procurement expectations, helping procurement teams embed tailgating detection requirements into RFPs that pass legal and accessibility reviews.
-
ROI & TCO Models: Built-in financial models reflect acquisition, integration, maintenance, and staffing impacts—critical for 2026 business cases that must compete with competing digital transformation projects.
Competitive Landscape: Who Matters and Why
The field encompasses global systems integrators, camera vendors, access-control platform providers, and niche analytics specialists. Leading companies combine hardware innovation with deep analytics and access-control integration. Key vendor profiles in the report highlight practical differentiation vectors such as sensor modality (ceiling-mounted 3D, infrared, microwave), edge AI capabilities, and integration maturity with access management suites.
-
Optex Co., Ltd. – Known for ceiling-mounted 3D virtual modeling and human-tracking sensors that emphasize real-time detection accuracy at busy entry points.
-
Detex Corporation – Offers interlock-centric systems with one-person-rule enforcement tailored to high-security installations requiring deterministic control behavior.
-
ACTi Corporation – Positions AI-powered people counting tightly with access control platforms to enable automated incident identification and alerting.
-
Integrated Design Limited (IDL) and FASTCOM Technology – Deliver sensor-fusion and analytics stacks for perimeter and entry-point protection across commercial and secured facilities.
-
Alcatraz AI, Openpath, Kisi, and others – Focus on cloud-native or embedded-AI solutions that simplify deployment and reduce incremental hardware needs.
-
Major systems players (Honeywell, Johnson Controls, Axis, Panasonic, Genetec) – Provide tailgating detection as a capability within broader building and security platforms, appealing to enterprises seeking single-vendor operational simplicity.
Each vendor cluster brings trade-offs: specialized analytics vendors often deliver superior detection performance in constrained scenarios, while platform vendors offer stronger lifecycle management and integration economies. The report includes a practical vendor-fit framework to help decision-makers choose the right approach for their risk profile.
Recent Technology and Market Developments
-
Product feature cadence is accelerating: Several vendors released or enhanced tailgating features in 2025–2026, including AI-based multi-object line-crossing detection and simplified troubleshooting tools that lower operational friction during rollout.
-
Sensor fusion is mainstreaming: Integrations across video analytics, infrared, microwave, and ceiling-mounted 3D sensors are increasingly used to reduce false positives in high-traffic and cluttered environments.
-
Procurement expectations have shifted: Federal and municipal RFP language now often requires explicit tailgating detection capabilities and ADA-compliant implementations, raising the bar for vendor solutions.
Regulatory and Operational Dynamics to Watch
Standards work and regulatory guidance are converging to make tailgating detection a recognized component of access security architectures. Developments in international standards and national guidance now reference tailgating detection within biometric fusion and network-system frameworks—implications that extend to procurement, acceptance testing, and auditability. In parallel, implementation cost remains a visible constraint: hardware, software, and professional services can create material first-cost hurdles. The report provides mitigations and phased procurement approaches for 2026 that balance security gains against financial and operational constraints.
Strategic Recommendations for 2026 Planning
-
Adopt a staged procurement strategy: Begin with targeted pilots in representative sites (peak ingress, mixed lighting, and staffing variance) and use telemetry from pilots to refine spec and scale-up plans.
-
Prioritize integration over feature-chasing: Ensure that chosen solutions integrate with existing access-control, building automation, and incident-response workflows. Integration risk drives most lifetime costs.
-
Insist on measurable acceptance criteria: Define objective KPIs for tailgating reduction, false alarm rates, and mean time to detect/alert to quantify vendor performance.
-
Evaluate vendor ecosystems: Favor vendors with proven partnerships across camera manufacturers, access-control platforms, and systems integrators to reduce single-source dependency.
-
Budget for operational change: Training, policy changes, and SOC playbook updates are necessary to extract value from new detection capabilities—allocate resources accordingly in 2026 budgets.
-
Embed privacy and AI governance: Ensure solutions provide explainability, audit logs, and data minimization controls appropriate to local privacy rules and procurement requirements.
What the Full Report Contains (Practical Components)
PW Consulting’s full Tailgating Detection Market report is built to be actionable. Highlights include our market-sizing methodology, vendor scorecards and technology profiles, scenario-based ROI and TCO models, a procurement-ready RFP annex, pilot design templates, integration and network planning guides, and regulatory alignment maps. The report also includes an incident-playbook template aligned with SOC operations and audit-ready acceptance testing checklists to shorten time-to-value post-purchase.
Final Thought: Positioning for 2026 and Beyond
Tailgating detection is no longer a point-solution novelty; it is evolving into a required capability within security architectures where controlled entry is a risk vector. For organizations making 2026 investment choices, the decision calculus is clear: favor solutions that demonstrably reduce unauthorized entries, integrate cleanly with operational systems, and provide a transparent path to measurement and governance. PW Consulting’s report equips decision-makers with the analytical backbone and practical tools needed to make those choices with confidence.
Next Steps
For security leaders preparing 2026 budgets and technology roadmaps, PW Consulting’s full report provides the detailed segment-level data, vendor benchmarking, and procurement templates that underpin defensible investment decisions. Visit our website to access the full report and supporting tools, or contact our advisory team for a tailored briefing aligned to your facilities and risk profile.
For detailed analysis of this topic, please visit the official page: Tailgating Detection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com