

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Forecast: Vertical Rotary Surface Grinders Market to Expand at 5.59% CAGR, Unlocking New Opportunities Through 2032
By pmarketresearch, 2026-07-01
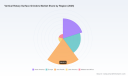
Vertical Rotary Surface Grinders Market — Strategic Preview for 2026 Decision‑Makers
PW Consulting’s new market study on Vertical Rotary Surface Grinders offers a focused, decision‑grade intelligence package designed to steer capital, sourcing and product strategies in 2026. Grounded in five years of historical observation (2020–2025) and a seven‑year forecast horizon (2026–2032), the report synthesizes macro growth trajectories, competitive positioning and actionable playbooks for OEMs, end‑users and investors. This preview outlines why the report is strategically material for choices you will make this year, while intentionally withholding detailed subsegment tables to encourage direct access to the full dataset.
Vertical Rotary Surface Grinders Market
Market Snapshot: Macro Trajectory and Competitive Structure
The vertical rotary surface grinders market reached an estimated USD 2,580 Million in the base year (2025). Our modeling indicates steady expansion through the forecast window, with a compound annual growth rate of 5.59% from 2026 to 2032 and a projected market size approaching USD 3.78 Billion by 2032. These headline metrics reflect a combination of demand drivers: sustained investment in automotive, aerospace and toolmaking; ongoing replacement cycles in heavy industry; and selectively rising requirements for precision flatness in advanced manufacturing.
Vertical Rotary Surface Grinders Market
Concentration metrics show a market that is neither atomized nor fully consolidated: the top three players account for roughly 38.5% of market sales while the top five approach 52.7%. That mid‑fragmented structure creates both scale advantages for established OEMs and fertile ground for niche specialists, particularly in remanufacturing, aftermarket service and application‑specific turnkey solutions.
Vertical Rotary Surface Grinders Market
Why This Matters for 2026 Decisions
- Capital Allocation: With predictable mid‑single‑digit growth, major capital expenditures should be gated by clear payback expectations. The report supplies modeled ROI scenarios under differing utilization, pricing and material‑cost assumptions to assist board‑level approvals.
- Sourcing & Supply Chain: Volatility in steel and specialty material pricing, along with ongoing trade investigations, materially affect BOM costs and lead times. The study provides scenario stress‑tests for sourcing strategies (near‑shoring, dual‑sourcing, contractual hedging) to be executed in 2026.
- Product Roadmaps: Technology choices (e.g., hydrostatic turntables, high‑powered vertical spindles, remanufactured Blanchard lines) should be prioritized against end‑market demand elasticity. We map technology adoption sequences to price bands and buyer personas to help product and engineering teams set 18–36 month development cadences.
- M&A and Partnership Screening: The mid‑concentrated nature of the market makes strategic acquisitions or capacity partnerships attractive for both OEMs seeking share and private equity looking for consolidation plays. The report includes a shortlist framework for target screening and valuation levers.
Actionable Contents of the Full Report
The published report is structured for operational use. Highlights include:
- Executive dashboards with topline growth scenarios and sensitivity to steel price and tariff shocks.
- Buyer personas and procurement playbooks—how to evaluate TCO for one‑head vs multi‑head machines, retrofit vs new purchase, and when remanufactured assets make sense.
- Technology horizon maps detailing adoption curves for hydrostatic tables, high‑HP spindle platforms and control/automation upgrades.
- Profitability models for aftermarket services (spares, rebuilds, field servicing) and a build‑out playbook for service organizations.
- Regulatory and trade risk matrix with mitigation options—procurement clauses, inventory buffers, and tariff pass‑through modeling.
- M&A playbooks and a prioritized target list based on strategic fit, manufacturing footprint and aftermarket overlap.
- Benchmarked supplier scorecards and negotiation checklists to shorten vendor qualification cycles.
To preserve the report’s commercial integrity, granular regional and application breakdowns are not reproduced in this preview. The full downloadable dataset contains the complete segmented tables and time‑series that underpin our recommendations.
Competitive Landscape — Who Matters and Why
We examined a cross‑section of OEMs and regional specialists to form a layered view of competition, capability and go‑to‑market approaches.
- Bourn & Koch, Inc. (Rockford, Illinois, USA) — Known as the OEM for Blanchard vertical rotary grinders, Bourn & Koch’s portfolio emphasizes both new and remanufactured models with very large chuck capacities and high‑horsepower spindles. Their strength lies in heavy‑stock removal and purpose‑built installations for large workpieces.
- DCM Tech (Winona, Minnesota, USA) — Offers the IG series of American‑made rotary grinders with a range of capacities. DCM targets precision grinding for industrial and aerospace applications, balancing compact footprints with serviceability emphasis.
- Chevalier Machinery (Taiwan / USA) — The FRG series highlights hydrostatic turntable designs and high rigidity. Chevalier is notable for product refreshes that push precision at competitive price points and for expanding aftermarket capabilities.
- Okamoto Corporation (Japan) — The VRG‑DX line focuses on high‑power spindles and accuracy in rotary table models, positioning Okamoto against premium accuracy demands in aerospace and optical component manufacturing.
- Tong Yi Machinery / Dowell (Taiwan) — Markets VR series machines that stress reliability across metalworking segments, often chosen where predictable uptime and ease of maintenance are procurement priorities.
- Alex Machine Tools, Synergy Machine Tools, ABL Machine Tools, Kent USA — These regional manufacturers offer a spectrum of vertical rotary platforms, from high‑volume die & mold machines to specialty units for valves, bearings and hard/brittle material work.
Competitive dynamics are evolving: premium accuracy and aftercare are moving from differentiators to table stakes, while remanufacturing and service models (where margins are typically higher than OEM equipment sales) are becoming profit centers for firms that can execute nationwide field networks.
Recent Industry Signals and Their Strategic Implications
- Trade show activity and product launches (for example, Alex Machine Tools’ participation at Die Mould India 2026 and Chevalier’s recent FRG series introduction) signal renewed OEM emphasis on capturing die & mold and custom applications—opportunities for localized manufacturing partnerships.
- Notable installations and product upgrades (illustrated by Bourn & Koch’s placements in 2025) show that existing demand is still driven by replacement and capacity expansion in regional metalworking hubs.
- Input‑cost noise—steel coil prices rose meaningfully in 2025—along with ongoing national trade investigations and tariff proposals on machine tools and specialty materials, create risk for global sourcing models and warrant explicit procurement hedging strategies in 2026.
Strategic Recommendations for 2026 Execution
- Lock in modular sourcing: Pursue dual‑source agreements for key castings and spindle components, and qualify regional sub‑assemblies to reduce tariff exposure and lead time volatility.
- Prioritize the aftermarket: Build spare parts inventory strategies, subscription‑style maintenance, and remote diagnostics offerings to increase recurring revenue and reduce price sensitivity.
- Invest selectively in high‑value tech: Target hydrostatic turntables and high‑HP spindle platforms for customers where productivity gains justify price premiums; standardize controls for easier service and upgrades.
- Hedge material cost exposure: Use indexed contracts or multi‑year supply agreements where possible; model scenarios for up to 50% tariff shocks in procurement planning exercises.
- Consider bolt‑on consolidation: For mid‑sized OEMs and financial sponsors, pursue tuck‑ins that strengthen service footprints or add remanufacturing capabilities—those assets accelerate margin expansion.
- Engage on policy: Coordinate with industry associations to influence trade policy implementation timelines and secure carve‑outs for critical capital equipment components.
Methodology, Confidence and Next Steps
Our analysis synthesizes primary interviews, vendor and end‑user surveys, company disclosures and price‑sensitive input‑cost models. Base year is 2025; forecasts run 2026–2032. We assign medium‑high confidence to headline growth and concentration metrics, with scenario banding around material price and tariff trajectories to reflect elevated policy risk.
This preview is intentionally selective—core segmented tables, regional/application splits, and detailed company financials are only available in the full report package and accompanying data workbook. For procurement teams, strategy committees, or investors preparing decisions in 2026, those granular datasets are the difference between directional understanding and executable strategy.
Access the Full Intelligence
PW Consulting’s full Vertical Rotary Surface Grinders Market report provides the datasets, slide decks and implementation tools required to convert insight into action. Contact our market research desk or visit the report page to download the executive summary, review the methodology appendix and access the client portal for custom queries and model extracts.
For detailed analysis of this topic, please visit the official page: Vertical Rotary Surface Grinders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Biomass Power Equipment Market Poised to Grow at a 6.99% CAGR Through 2032
By pmarketresearch, 2026-07-01
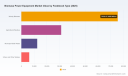
Biomass Power Equipment Market — Strategic Outlook for 2026: A PW Consulting Brief
As global energy systems accelerate the transition away from unabated fossil fuels, biomass power equipment has re-emerged as a pragmatic bridge technology for utilities, industrial off-takers, and municipal energy planners. PW Consulting’s latest market study examines the commercial dynamics and technology vectors shaping the biomass power equipment market through 2032, delivering a decision-grade framework that corporate strategists and capital allocators must engage with before making 2026 commitments.
Biomass Power Equipment Market
Why this study matters for 2026 decisions
Investment windows that open in 2026 will be defined by three converging forces: sustained market expansion, policy-driven incentives, and tightening carbon economics. Our analysis shows the global biomass power equipment market expanded from approximately USD 89.5 billion in 2020 to about USD 125.5 billion in 2025, and is forecast to exceed USD 201.5 billion by 2032 — a compound annual growth rate of roughly 7% across the 2026–2032 forecast horizon. That trajectory translates into high-visibility opportunities for equipment suppliers, plant developers, and engineering partners, but it also intensifies competitive pressures and supply-chain risk for late movers.
Biomass Power Equipment Market
Report scope and actionable deliverables
-
Forward-looking market sizing: verified historical base (2020–2025), and detailed forecasts to 2032 — useful for financial planning and capital budgeting.
Biomass Power Equipment Market -
Technology and procurement playbooks: comparative assessment of combustion, gasification, and anaerobic digestion pathways with pragmatic procurement checklists and LCoE-sensitive decision trees tailored to common utility and industrial use cases.
-
CapEx/Opex benchmarks and component cost indices: vendor-neutral tables and sensitivity matrices for boilers, turbines, flue-gas cleaning, and common balance-of-plant items that underpin credible project bids.
-
Supply chain and localization roadmap: supplier tier-mapping, critical-component lead-time scenarios, and contract structuring options to reduce schedule and price exposure.
-
Regulatory and carbon scenario planning: three stress-tested policy scenarios (accelerated decarbonization, status quo, and protectionist retrenchment) with implications for subsidy capture, eligibility, and carbon risk hedging.
-
Competitive intelligence and vendor scorecards: qualitative strengths, recent program wins, and execution risk profiles for the major equipment providers and regional challengers.
Market dynamics shaping supplier and investor choices
Several dynamics will determine winners and losers in 2026 and beyond:
-
Policy acceleration: Renewable energy mandates and investment tax credits materially alter project IRRs. For example, recent policy frameworks in major markets have increased subsidy availability and investment certainty for qualified biomass projects — altering financing structures and shortening payback periods for first-movers who can validate eligibility early in project development.
-
Carbon pricing squeeze: Elevated carbon allowance prices in mature emissions trading systems are already making biomass-fired generation relatively more attractive than fossil baseload in dispatch economics. Developers and OEMs should model carbon scenarios into long-lead procurement decisions to avoid stranded-asset risk.
-
Feedstock and logistics volatility: Feedstock costs and availability — from wood pellets to agricultural residues — remain the single largest operational unknown for many projects. Price spikes and logistical bottlenecks can erode margins quickly; our recommended mitigation tactics include diversified feedstock contracts and staged fuel sourcing strategies linked to indexed pricing.
-
Component and EPC cost pressure: Mechanical systems such as grate stoker assemblies and fluidized bed components carry concentrated cost exposure. Established cost bands for such components mean procurement timing and bundle strategies (equipment + installation) materially affect total installed cost.
-
Project execution complexity: Integration of flue gas cleaning, ash handling and CHP interfaces remains a proven source of schedule slippage. Vendors with turnkey delivery experience command a premium; however, modularization approaches and standardized plant packages are emerging as viable de-risking mechanisms for repeatable deployments.
Competitive landscape — what to watch in 2026
The market exhibits clear leadership in large-scale, turnkey solutions while also hosting regional specialists that capture niche demand. PW Consulting’s vendor analysis highlights several archetypes:
-
Global turnkey integrators: Established European and Japanese OEMs continue to win large-scale CHP and utility projects by offering end-to-end solutions — boilers, steam turbines, and emissions controls — bundled with project execution capability. These firms benefit from deep engineering benches and an installed-base advantage.
-
Specialist component suppliers: Firms with focused product portfolios (e.g., gasifiers, grate technology) can be attractive partners in hybrid contracting models where IP and manufacturing cost control are prioritized.
-
Regional system builders: Local manufacturers and operators that can tailor designs to feedstock realities and regulatory requirements provide a nimble alternative to larger OEMs, particularly in small- to mid-scale projects.
Recent vendor developments emphasize execution readiness: notable 2024–2025 milestones include new plant commissions, secured orders for medium-scale projects, and efficiency breakthroughs that directly influence project economics. These operational signals should form a critical input to supplier selection and commercial negotiations in 2026.
Strategic implications and recommended actions for C-suite and project teams
For executives making capital and procurement decisions in 2026, the study suggests a five-point strategic playbook:
-
Lock-in policy and subsidy eligibility early: Engage with legal and policy advisors during FEED to secure tax credits or renewable premium access; assumptions about subsidy capture should be conservative in base-case financial models.
-
Prioritize vendor execution track records over headline efficiency claims: Efficiency gains are valuable, but schedule and commissioning risk more often determine NPV outcomes for first-of-a-kind projects.
-
Adopt staged capital deployment: Use modular plant designs and phased capacity increases to align capital expenditure with confirmed offtake and feedstock contracts, reducing exposure to volatile input prices.
-
Diversify feedstock contracts and incorporate indexed pricing: Negotiate contracts that permit fuel-switching or co-firing and include price collars or stepped escalators tied to transparent indices.
-
Build carbon-market hedges into commercial bids: Where applicable, price carbon allowance exposure into offtake contracts or secure forward emissions allowances to stabilize dispatch economics.
How PW Consulting’s report adds unique decision advantage
Beyond headline forecasts, the report combines proprietary cost-benchmarks, vendor execution scoring, and scenario-based financial models to convert market signals into executable strategies. Practically, this means:
-
Procurement teams receive a prioritized vendor shortlist and negotiation playbook tailored to plant scale and feedstock mix.
-
Investment committees get stress-tested project cash flows under multiple policy and fuel-price scenarios to inform approval thresholds and financing structures.
-
Business development teams obtain go-to-market blueprints, including high-probability corridors for retrofit and greenfield opportunities over the next 18–30 months.
Where this leaves decision-makers entering 2026
Market momentum is unmistakable: growth since 2020 has been strong and structural drivers indicate sustained demand through 2032. But the path to value is selective. The most compelling opportunities favor organizations that combine early policy-compliance verification, disciplined feedstock strategies, and procurement models that prioritize execution resilience. For OEMs and EPCs, differentiating through proven modular solutions and guaranteed commissioning timelines will be decisive.
We designed this briefing to be a strategic preview — it demonstrates the depth of analysis you should expect, while reserving the granular regional, technology and feedstock splits that underpin procurement and M&A decisions for the full report. That detailed segmentation, our proprietary vendor scorecards, and the complete set of financial model assumptions are available in the full PW Consulting Biomass Power Equipment Market report and its interactive data annex.
Next steps
-
Request the full report to access the granular breakdowns and interactive scenario models required for bid preparation, CAPEX approval, or strategic partnerships.
-
Engage our advisory team for a tailored workshop: we translate report findings into a 90-day action plan for procurement, contracting and capital allocation aligned to your risk tolerance.
PW Consulting’s analysis equips leaders with the market context and practical tools needed to make high-confidence biomass equipment decisions in 2026. For executives preparing bids, arranging financing, or evaluating vendor partnerships, timely access to the full data set and our consulting support will be the difference between seizing advantage and reacting to it.
For detailed analysis of this topic, please visit the official page: Biomass Power Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Market Insights: Walk‑In Humidity Chambers Poised to Expand at a 6.3% CAGR Through 2026–2032
By pmarketresearch, 2026-07-01
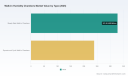
Walk In Humidity Chambers Market: Strategic Intelligence for 2026 Decision-Makers
As organizations across pharmaceuticals, electronics, automotive, aerospace, and industrial testing recalibrate capital plans for 2026, the Walk In Humidity Chambers market presents a clear, actionable growth narrative that we quantify and contextualize in PW Consulting’s latest study. The global market—anchored on a rigorous base-year analysis through 2025—has demonstrated steady expansion and is modeled to continue at a compound annual growth rate (CAGR) of 6.3% through our 2026–2032 forecast window. In plain terms, this is a market moving from mid‑single‑hundreds of USD millions toward a near‑billion dollar arena by the end of the decade, creating decisive strategic choices for buyers, suppliers, and investors.
Walk In Humidity Chambers Market
Why this study matters for 2026 strategy
-
Timing: 2026 is the inflection year for many capex programs initiated in 2022–2024; procurement teams must decide between immediate replacement, scaled retrofits, or staged procurement to match evolving testing profiles.
Walk In Humidity Chambers Market -
Risk management: Supply chain fragilities—particularly for stainless steel interiors, specialized insulation, high‑performance compressors and precision humidity sensors—require preemptive sourcing and inventory strategies.
Walk In Humidity Chambers Market -
Regulatory alignment: Stricter compliance requirements (ICH guidelines for stability testing, FDA/GMP, ISO 17025 and CE standards) are raising minimum performance and validation expectations for walk‑in solutions, changing the economics of procurement and lifecycle management.
-
Service economics: As energy efficiency and uptime become as important as footprint, total cost of ownership (TCO) and availability of local service networks will increasingly determine supplier selection and aftermarket revenues.
Key market dynamics shaping 2026 decisions
-
Moderate fragmentation with consolidation potential: Market concentration metrics show a competitive landscape where the top three players do not dominate the sector entirely (CR3 ~31.4%), and the top five control under half of market revenues (CR5 ~42.8%). This creates fertile ground for bolt‑on acquisitions, differentiated service models, and regional scale plays.
-
Sector-driven demand diversity: Pharmaceutical stability programs, electronics and semiconductor qualification, automotive and EV environmental testing, and aerospace/defense qualification are driving different performance requirements—forcing vendors to balance standardized product lines against bespoke, regulated solutions.
-
Energy and efficiency premium: New designs that reduce life‑cycle energy consumption and improve humidity control precision command pricing and shorten payback periods—an increasingly common procurement criterion in capital approval committees.
-
Supply chain sensitivities: Component-level concentration (compressors, sensors) introduces procurement risk and creates strategic options for vertical integration, supplier redundancy, and inventory hedging.
What the PW Consulting report delivers (practical, executable content)
-
Actionable market sizing and forward scenarios: Our model quantifies baseline demand and stresses it under three adoption and regulatory scenarios—useful for budgeting, sensitivity analysis, and board‑level risk assessment.
-
Procurement playbook: Step‑by‑step frameworks for RFP crafting, performance specification checklists (sensors, tolerances, thermal inertia), site acceptance testing protocols, and negotiation levers that preserve long‑term service economics.
-
TCO and ROI tools: Discounted cash‑flow templates and payback calculators that incorporate energy consumption profiles, maintenance regimes, and uptime penalties—ready to drop into capital approval packages.
-
Supplier risk matrix and sourcing options: Tiered supplier maps, dual‑sourcing strategies for critical components, and criteria for deciding between modular panel builds vs. permanent structural installations.
-
Competitive intelligence and M&A playbook: Vendor scorecards, capability gap analyses, and a prioritized list of small‑cap acquisition targets (sensor manufacturers, software/monitoring specialists, regional service providers) for faster capability build.
-
Compliance and validation checklists: ICH‑aligned protocols, GMP and ISO 17025 compatibility frameworks, and audit templates tailored to pharmaceutical and medical device stability testing.
-
Technology roadmap: Adoption trajectories for digital monitoring, remote validation, energy recovery systems, and modular architectures that support both walk‑in and drive‑in solutions.
Competitive landscape — what to watch in 2026
The market includes a mix of legacy environmental simulation names, specialist room builders, and growing regional OEMs. Several recent company moves sharpen competitive dynamics and hint at strategic direction:
-
BINDER GmbH (Tuttlingen, Germany) recently expanded its capabilities through acquisition activity focused on humidity and temperature stability rooms. This enhances its competitive positioning in regulated pharmaceutical testing and accelerates product integrations around FDA‑compliant monitoring solutions.
-
Associated Environmental Systems (AES) has invested in significantly larger manufacturing capacity, improving its ability to scale custom and high‑load walk‑in projects and to shorten lead times for North American customers—an operational advantage in supply‑constrained cycles.
-
Weiss Technik North America (including CSZ heritage) is likewise expanding manufacturing and office capacity to address both customized industrial applications and volume orders, strengthening its service footprint for high‑availability sectors.
-
Specialists such as Darwin Chambers, Parameter Generation & Control (now aligned with larger group strategies), Russells Technical Products, Testron Group, and Wewon leverage differentiated strengths—pharma‑grade humidity control, modular construction, salt‑fog and large specimen testing, and regional cost advantages—allowing them to capture niche demand and contract manufacturing opportunities.
Collectively, these developments point to a market where scale, regulatory compliance capabilities, fast delivery, and local service are becoming decisive competitive attributes. Expect ongoing consolidation around complementary tech (remote monitoring, analytics) and service networks rather than pure product cross‑selling alone.
Strategic implications and recommended actions for 2026
-
For buyers: Prioritize suppliers with validated compliance histories and demonstrable local service footprints. Use our TCO models to compare energy and service costs over a 7–10 year horizon, not just initial purchase price.
-
For vendors: Focus on modular architectures, rapid delivery lines, and integrated monitoring software to capture growth. Pursue bolt‑on acquisitions that shore up sensor and controller supply or extend service networks in key geographies.
-
For investors: Seek targets in the mid‑market that offer proprietary humidity control algorithms, strong service margins, or regional dominance—these are likely consolidation candidates given current concentration dynamics.
-
For supply chain teams: Hedge exposure to critical raw materials (stainless steel, compressors, humidity sensors) and consider long‑term supplier agreements or strategic stock positions to protect project timelines.
What we’re deliberately leaving out here (and why)
In this executive preview we present overarching growth trends, competitive dynamics, and prescriptive actions designed to influence 2026 strategy. To preserve the value of the full research and adhere to our “trailer” approach, granular regional and application splits, vendor‑level revenue breakdowns, and detailed segment tables are not reproduced in this release. Those datasets are included in the complete PW Consulting report—along with downloadable models, supplier scorecards, and negotiation playbooks that procurement and strategy teams can operationalize immediately.
Next steps
If your organization is preparing capital plans, evaluating vendors, or sizing M&A opportunities in 2026, PW Consulting’s full Walk In Humidity Chambers report delivers the empirical models, compliance templates, and tactical playbooks to move from analysis to execution. Contact our industry team to arrange a briefing, obtain the full dataset and Excel modeling pack, or commission a custom workshop tailored to your portfolio and geographies of interest.
In a market growing at a sustained mid‑single‑digit CAGR and undergoing structural shifts in compliance, energy, and service economics, the right intelligence now will determine who wins tomorrow’s contracts. PW Consulting’s analysis turns market momentum into executable strategy.
For detailed analysis of this topic, please visit the official page: Walk In Humidity Chambers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Global Corn Flour Market to Expand at a 4.25% CAGR Through 2032
By pmarketresearch, 2026-07-01
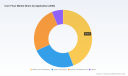
Corn Flour Market: Strategic Imperatives for 2026 — PW Consulting Preview
PW Consulting’s new Corn Flour Market report (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes macro growth trajectories, competitive dynamics, input-cost volatility and regulatory inflection points into a compact set of decision-ready insights for corporate leaders planning for 2026. This preview outlines the strategic value of the report: how procurement, product development, capacity planning, sustainability programs, and M&A strategies should adapt as the global corn flour market expands at a measured pace (CAGR 4.25% through 2032), growing from a 2025 base of USD 6.45 Billion to an expected USD 8.63 Billion by 2032.
Corn Flour Market
Why this report matters for 2026 planning
-
Timing: 2026 is a hinge year for many operators — legacy financing cycles, capital commitments made in 2023–2024, and new regulatory/tariff outcomes converge to alter supply-risk profiles and ROI expectations.
Corn Flour Market -
Clarity on trajectory: The market’s steady compound annual expansion (4.25% through 2032) signals predictable end-market demand growth but also highlights where margin pressure and differentiation will matter most.
Corn Flour Market -
Actionable intelligence: The report translates macro numbers into operational levers — from hedging frames and contract terms to plant utilisation thresholds and product formulation roadmaps — that procurement, commercial and strategy teams can apply immediately.
Market snapshot (headline metrics)
Key headline figures in the report: the global corn flour market moved from USD 5.94 Billion in 2023 to USD 6.45 Billion in 2025, and is forecast to reach approximately USD 8.63 Billion by 2032 under our central scenario. These topline dynamics, combined with observed market concentration metrics (CR3 ~28.5%; CR5 ~38.2%), point to a market that is neither a pure commodity nor tightly consolidated — an environment where scale, specialization and route-to-market decisions materially affect margin capture.
Five strategic shifts companies must address in 2026
-
Procurement and input-cost management: USDA’s 2025/26 season-average projection and contemporaneous futures activity (notably market quotes in the 463–466 USd/BU range as of April 2026) are shifting procurement calculus from short-cycle spot buying to layered hedging and forward contracting. Buyers should stress-test procurement policies across three scenarios (low, baseline, upside) and set triggers for rolling coverage and supplier diversification.
-
Product portfolio and formulation strategy: Margin uplift will not come from volume alone. Manufacturers should prioritize ingredient innovation (e.g., texturizing blends, gluten-free positioning, nixtamalized specialty lines) and channel-specific SKUs to capture higher-value programs in retail and foodservice. The report maps several high-opportunity product adjacencies and provides go-to-market timing windows aligned to forecast demand shifts.
-
Capacity, network and capital allocation: Given the steady CAGR and moderate market concentration, capital investments should be targeted: brownfield upgrades and flexible milling lines often offer better risk-adjusted returns than new greenfield builds. The full study includes utilisation thresholds and simple payback scenarios by plant type to aid capital committees in 2026 approval cycles.
-
Sustainability as a commercial lever: Recent moves by major processors to introduce regeneratively sourced flours and to decarbonize milling operations underscore how ESG credentials are becoming table stakes for certain buyers. The report offers a practical roadmap for integrating regenerative sourcing pilots, measuring scope-3 impacts across the supply chain, and converting sustainability investments into commercial differentiation with blue-chip customers.
-
Regulatory and trade risk management: Title 21 standards and the evolving U.S. tariff landscape — including a recent judicial decision overturning most 2025 IEEPA import tariffs and the prior implementation of reciprocal tariffs — create both compliance burdens and cost/revenue opportunities. The report provides a regulatory matrix and scenario playbooks for customs strategy, tariff mitigation, and rapid compliance checklists for product labelling and standards of identity.
Competitive landscape — what to watch in 2026
The corn flour competitive field is characterized by a mix of global agribusinesses, specialty ingredient firms, large consumer food companies with upstream integration, and regional millers focused on niche applications. The market’s CR3 and CR5 indicate room for differentiation by specialists and mid-sized players. In 2026, three dynamics will be decisive:
-
Vertical integration and supply-chain control: Large processors and agribusinesses continue to leverage scale to integrate wet and dry milling, co-products valorisation, and logistics. Expect continued investment in traceability and supplier programs.
-
Specialization and premiumization: Niche producers and specialty ingredient firms can protect or expand margins through certified non-GMO, organic, nixtamalized and gluten-free offerings — segments where brand credibility and certification matter.
-
Consolidation and partnerships: The fragmented mid-market is ripe for bolt-on acquisitions and commercial partnerships that provide channel access or technical capabilities rather than just capacity.
PW Consulting’s competitive profiles include leading global processors and specialists whose strategic moves will shape supply and pricing in 2026 and beyond. Among the firms covered are major processors with integrated milling platforms, specialty ingredient suppliers offering tailored texturizing solutions, established masa and nixtamalized producers with cultural and formulation expertise, and regional millers focused on industrial customers and niche retail segments. The report highlights recent corporate developments — for example, a leading global processor’s launch of regeneratively sourced flours and another’s announcement of a new ethanol complex in Brazil — and interprets their likely market impacts.
Practical deliverables — what’s inside the full report
The full PW Consulting Corn Flour Market report is designed to be immediately usable by commercial, procurement and strategy teams. Key deliverables include:
-
Proprietary topline and forecast model (2020–2032) with downloadable scenario variants and sensitivity tables.
-
Regulatory and tariff playbook mapping standards of identity, labelling checkpoints, and cross-border compliance actions for major trade lanes.
-
Supplier and competitor dossiers with strategic positioning, capability maps and recent corporate initiatives.
-
Commercial playbooks — pricing model templates, margin waterfall diagnostics, and channel-specific go-to-market recommendations.
-
Operational tools — utilisation thresholds, payoff analysis for brownfield versus greenfield options, and a small-capex product pilot checklist.
-
Risk matrix and mitigation options covering raw-material volatility, regulatory shocks, and trade disruptions (with recommended contingency contracts and insurance structures).
How executives should use this intelligence in 2026
-
Procurement leaders: adopt a layered hedging approach informed by the report’s scenario outputs; renegotiate supply agreements to include flexibility clauses and sustainability premiums where commercially viable.
-
Product and R&D heads: prioritize two to three high-margin formulations for development, leveraging available ingredient adjacencies and certification pathways documented in the study.
-
Operations and capex committees: prefer flexible capital that can be redeployed across product lines; use the included utilisation model to set go/no-go thresholds for 2026 investments.
-
Corporate strategy and M&A teams: target bolt-ons that add channel access or technical formulation expertise; use the competitive dossiers when approaching potential partners or targets.
Reading between the lines: risks and upside
The market’s steady growth masks asymmetric risks and opportunities. Input-price shocks remain a tail risk; conversely, favorable trade rulings or policy shifts can unlock import/ export flows that materially alter regional competitive balances. Sustainability initiatives are becoming commercial differentiators for premium channels but require careful ROI justification. The report quantifies these trade-offs and offers prioritized, pragmatically sequenced actions — the kind that differentiate winners from followers in 2026.
Next steps — where to get the full data
This release is intentionally selective: it highlights the strategic insights you need to evaluate the 2026 agenda, while preserving the detailed regional, application and product-level splits for subscribers. The full report contains the comprehensive tables, downloadable models and the granular segmentation that procurement, commercial and strategy teams will require to execute against the playbooks outlined above.
To access the complete report, the interactive forecast model, and the Excel workbooks that translate these insights into executable plans, please visit PW Consulting’s Corn Flour Market page. The full dataset includes the region-by-region, type-by-type and application-by-application breakdowns required for precise budgeting, sourcing and M&A diligence.
PW Consulting — strategic insight, operational rigor, and practical tools to turn market forecasts into 2026-ready decisions.
For detailed analysis of this topic, please visit the official page: Corn Flour Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Heavy Industry Hydraulic Systems Market to Top USD 56.83 Billion by 2032
By pmarketresearch, 2026-07-01
Heavy Industry Hydraulic System Market: Strategic Insights for 2026 Decision‑Makers
Executive snapshot
The heavy industry hydraulic system market is on a steady expansion path, driven by continued demand for reliable power-dense actuation in construction, mining, agriculture and other off‑highway sectors, coupled with accelerating innovation in electrification and digital controls. Our benchmarking of the historical period (2020–2025) and forward-looking forecasts (2026–2032) shows a compound annual growth rate of 4.85% across the forecast window. After recovering from pandemic‑era disruption, global market value moved from the low‑thirty‑billion USD range in 2020 to roughly forty‑billion USD by the 2025 base year, with projections pointing to meaningful upside by the early 2030s under current regulatory and technology trajectories.
Heavy Industry Hydraulic System Market
Why 2026 is a decision inflection point
-
Regulatory and standards momentum: The introduction of ISO 18464:2025 institutes a formal design methodology aimed at minimizing energy consumption in hydraulic fluid power systems. For product teams and compliance officers, the standard transforms “nice‑to‑have” efficiency features into near‑table stakes for new equipment certification and procurement tenders.
Heavy Industry Hydraulic System Market -
Technology convergence: Electrified hydraulic power units (eHPUs), smarter valve architectures and embedded telematics are moving from demonstration projects to OEM roadmaps—illustrated by award‑winning prototypes and prominent showcases at industry trade events earlier in 2026.
Heavy Industry Hydraulic System Market -
Supply‑side volatility: Raw material dynamics—particularly steel price fluctuation—are imposing cost and lead‑time variability across pumps, cylinders and valve casings. Procurement strategies established in 2026 will materially affect margin trajectories for the remainder of the forecast horizon.
What the PW Consulting report delivers (practical, action‑oriented)
-
Transparent market sizing and trend methodology calibrated to the 2025 base year and a 2026–2032 forecast window—enabling scenario comparisons and stress tests aligned to corporate planning cycles.
-
Demand drivers and elasticity analysis across industry use‑cases; technology adoption curves for digital hydraulics, eHPUs and energy‑recovery subsystems; and sensitivity matrices for steel and critical component cost inputs.
-
Supplier benchmarking and capability heatmaps that synthesize engineering performance, aftermarket reach, digital maturity and sustainability credentials into a decision matrix for sourcing, alliance and M&A prioritization.
-
Commercial playbooks for go‑to‑market optimization: price‑to‑value strategies, service monetization models, and channel segmentation advice for OEMs, Tier‑1s and targeted aftermarket players.
-
Operational checklists and procurement tooling: inventory hedging templates, dual‑sourcing frameworks, and product‑life‑cycle roadmaps that translate market signals into executable 12–24 month plans.
-
Executive scenarios: three modelled futures that show the financial and competitive impact of accelerated electrification, stricter energy regulation, or sustained raw‑material inflation—quantified to support board‑level deliberations in 2026.
Competitive landscape — who matters and why
Competition in the heavy hydraulic space remains diversified. Market concentration data show that the top three global players account for roughly one‑third of the market, while the top five capture under half—an industry structure that preserves both scale advantages for incumbents and opportunity for well‑positioned challengers.
-
Bosch Rexroth AG: A technology leader in connected and energy‑efficient hydraulics, their portfolio of pumps, valves, manifolds and integrated units positions them strongly where system integration and digitalization are prioritized—particularly in steel processing and large‑scale industrial installations.
-
Parker Hannifin Corporation: Broad product breadth and strong engineered solutions capability make Parker an attractive partner for OEMs seeking modular, serviceable subsystems and a pathway to smart hydraulics at scale.
-
Danfoss Power Solutions: With an explicit focus on energy efficiency and electrification interfaces, Danfoss is shaping the bridge between classical hydraulic actuation and hybrid/electric drive architectures—an important strategic vector for customers targeting lower lifecycle emissions.
-
Eaton Corporation: Known for high‑pressure, durable components, Eaton remains a go‑to supplier for operations where robustness and uptime trump cost‑minimization—mining and oil & gas remain core segments for such propositions.
-
European specialists (HYDAC, Bucher, HAWE, Linde Hydraulics): These firms continue to compete on niche engineering depth—filtration, bespoke valves, and high‑pressure systems—often winning on performance and lifetime cost rather than initial price.
-
Japanese OEM suppliers (Kawasaki, KYB) and integrated machinery producers (Caterpillar, select Asian manufacturers): these players combine regional manufacturing scale with vertical integration and strong OEM relationships, particularly across Asia Pacific markets.
-
Regional and specialized manufacturers: A competitive layer of regional cylinder and systems makers provides rapid lead times and cost flexibility for local OEMs; strategic buyers should evaluate these suppliers for nearshoring and risk‑mitigation plays.
Recent product and market signals to watch in 2026
-
Trade show demonstrations (CONEXPO‑CON/AGG 2026 and others) highlighted next‑generation mobile hydraulic solutions and purpose‑built cylinders intended to reduce total cost of ownership for OEMs.
-
An eHPU product recognized at a major agricultural expo demonstrates the maturation of electrified hydraulics from lab to field—an immediate indicator for fleet electrification pilots and service model redesign.
-
These signals, combined with ISO 18464:2025 and mounting regional energy efficiency mandates, suggest a near‑term bifurcation: premiumized, efficiency‑centric systems will grow faster and command higher margins, while legacy platforms face intensifying cost pressure.
How different corporate functions should use the report in 2026
-
Product and R&D: Prioritize modular architectures and a roadmap for electrified subsystems. Use the report’s technology adoption curves and component scorecards to set 18–36 month R&D milestones tied to certification timelines and OEM procurement cycles.
-
Procurement & Supply Chain: Implement the report’s supplier‑risk matrix and raw‑material sensitivity analysis to redesign contracts (indexing to steel price bands, dual‑sourcing critical forgings) and to evaluate nearshoring options where lead‑time reduction justifies incremental cost.
-
Commercial & Pricing: Leverage the customer‑willingness‑to‑pay frameworks and service monetization models to transition from capex‑led sales to outcome‑based and subscription offerings for fleets adopting telematics and preventive maintenance.
-
M&A & Corporate Development: Use the supplier benchmarking and fragmentation analysis to identify tuck‑ins that add electrification IP, regional aftermarket coverage or vertical coverage in pumps/cylinders—especially valuable in a landscape where the top five do not dominate outright.
-
Operations & Aftermarket: Adopt the operational checklists to reduce lifecycle costs through filtration strategies, predictive maintenance enabled by embedded sensors, and parts standardization across platforms.
Scenario framing and investment theses
PW Consulting models three plausible 2026‑onward scenarios: (1) Accelerated electrification driven by regulatory push and OEM investment, where eHPUs and hybrid architectures capture above‑average share; (2) Gradual transition where energy efficiency standards incrementally raise average selling prices but preserve core hydraulic demand; and (3) Cost‑pressure environment where raw material shocks compress margins and accelerate consolidation. Each scenario points to distinct winners—technology‑leading integrators, nimble regional manufacturers, and service‑centric business models respectively—and our report quantifies breakeven timelines and capital requirements for each path.
Executive recommendation — actions to prioritize in 2026
-
Immediate (0–12 months): Conduct a supplier stress test using our procurement toolkit; pilot an electrified hydraulic subsystem with clear test metrics aligned to ISO 18464 benchmarks.
-
Near term (12–24 months): Reprice service contracts to capture value from digital maintenance; implement dual‑sourcing for critical steel‑intensive components and lock in forward pricing on long‑lead items where appropriate.
-
Medium term (24–48 months): Evaluate M&A targets that accelerate electrification, digital controls, or regional aftermarket reach; retool product roadmaps for modulated, software‑enabled hydraulics that can be upgraded in the field.
Accessing the full intelligence
This release outlines the strategic contours and actionable line‑items we believe every heavy hydraulic market participant should consider during 2026 planning. To support tactical execution, the full PW Consulting Heavy Industry Hydraulic System Market report includes the granular regional and application splits, component‑level revenue forecasts, supplier scorecards, and downloadable financial models that the summary omits. Those granular datasets and scenario‑specific dashboards are intentionally retained in the complete report to support client engagements and bespoke strategy workshops.
For boards, CEOs and functional leaders preparing 2026 budgets and three‑year strategic plans, the report is designed as a decision‑support system: not only signaling where the business is headed, but providing the tools to operationalize response. Contact PW Consulting to arrange a briefing, obtain the full dataset, or commission a tailored analysis aligned to your corporate risk tolerance and investment priorities.
For detailed analysis of this topic, please visit the official page: Heavy Industry Hydraulic System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Fuel Vapor Canisters Market to Reach USD 3,730.7 Million by 2032 on a 3.42% CAGR, Led by Asia Pacific at USD 1,375.27 Million
By pmarketresearch, 2026-07-01
Automotive Fuel Vapor Canisters Market: Strategic Imperatives for 2026 Decision-Makers
PW Consulting’s new Automotive Fuel Vapor Canisters Market Report synthesizes five years of historical performance with a forward-looking, scenario-driven forecast to equip OEMs, tier suppliers, material producers, aftermarket players, and investors with decision-grade intelligence for 2026 and beyond. The market reached USD 2,952.2 Million in our base year (2025) and, under our central scenario, grows at a compound annual growth rate (CAGR) of 3.42% through 2032 — reaching roughly USD 3,730.7 Million by the end of the forecast horizon. These headline metrics understate the structural shifts now reshaping the business model for vapor control systems: intensified regulatory testing protocols, material feedstock pressures, and evolving OEM packaging requirements are forcing a rethink of product design, sourcing, and go-to-market strategies.
Automotive Fuel Vapor Canisters Market
Why this report matters for 2026 planning
-
Timing: 2026 is a pivot year for compliance and product launches. Regulatory test protocols and minimum canister requirements adopted in recent years are fully binding on new-model development cycles that begin in 2026 and crystallize procurement decisions for model years 2028–2030.
Automotive Fuel Vapor Canisters Market -
Risk management: Marginal shifts in activated carbon supply and specification have outsized implications for canister validation, warranty exposure, and production continuity. Our supply‑chain stress-tests quantify exposure by component class and identify material substitution thresholds that preserve regulatory compliance.
Automotive Fuel Vapor Canisters Market -
Competitive tactics: Market concentration is meaningful — the three largest suppliers control a majority share and the top five account for over 70% of the market by revenue — creating a dual dynamic of supplier power vis-à-vis raw material vendors and opportunity for focused challengers in niche subsegments.
Market trajectory and structural drivers
Overall market growth over the forecast period is modest but resilient. Two forces shape the trajectory: regulatory tightening on evaporative emissions and the continuing evolution of vehicle platforms. Stricter running-loss and canister sizing requirements, aligned with advanced butane-loading test protocols, are increasing the technical bar for canister performance and validation. At the same time, the mixed vehicle parc — including hybrids and a long tail of internal combustion engine (ICE) vehicles in many regions — sustains demand for evaporative control solutions even as the industry pursues electrification.
For 2026 planners, the practical implications are clear. Design windows are narrowing: specification freeze dates must accommodate more exhaustive canister cycling and breakthrough testing. Procurement strategies must incorporate tiered material qualification pathways that balance cost, performance, and availability. And product roadmaps should prioritize modular, scalable canister architectures that can be optimized to different purge strategies and fuel blends without a complete redesign.
Regulatory and testing landscape — what changes now mean in practice
Regulatory authorities have moved beyond prescriptive sizing to define test-based performance thresholds that directly inform acceptable media and housing choices. The adoption of new evaporative emission test procedures with defined breakthrough points and cycle protocols forces a stronger integration between materials science and system engineering. For program managers this translates into three programmatic shifts:
-
Upstream validation: earlier and deeper lab validation of activated carbon media under vehicle-representative cycling to avoid late-stage failures during certification.
-
Design for testability: canister and purge strategies must be engineered to pass standardized loading/purge sequences while meeting OEM packaging and durability requirements.
-
Cross-functional procurement: procurement, engineering, and compliance teams must set joint qualification gates that recognize both material variability and equipment-level tolerances.
Material dynamics: activated carbon at the center
Activated carbon remains the foundational adsorbent for fuel vapor canisters. However, feedstock variability and increasing demand for higher-capacity, durable media introduce supply-side volatility. Our analysis highlights pressure points at the interface between feedstock sourcing, media processing, and final canister assembly. Firms that can guarantee consistent butane working capacity metrics and robust cycle life will command pricing power or secure long-term commitments from OEMs. For materials suppliers and prospective investors, the opportunity lies in scale, process stability, and certification-ready product lines.
Competitive landscape — strategic profiles and tactical moves
The competitive set consists of entrenched global players with strong OEM relationships, niche specialists focused on aftermarket breadth, and material incumbents supplying the carbon media. Key themes we observed during our industry mapping and primary research:
-
Depth of product portfolio matters. Firms with modular canister platforms and integrated purge/vent solutions enjoy faster ramp-up with OEM programs and can reduce unit cost through common tooling and validated subassemblies.
-
Aftermarket scale is a strategic asset. Players who combine OEM-level product quality with extensive aftermarket coverage can monetize extended lifecycle service needs and capture retrofit opportunities driven by regulatory enforcement.
-
Material suppliers retain leverage where high-performance carbon formulations are validated for regulatory test cycles. Vertical coordination between media producers and canister assemblers shortens qualification timelines.
Representative company observations (non-exhaustive):
-
Suppliers with long-standing global portfolios and modular designs are positioned to support a wide tank-size range and multi-fuel applications — a strategic advantage as fuel blends and OEM specifications diversify.
-
European technical leaders continue to invest in complete canister systems, including valves and ventilation lines, positioning them strongly for integrated emission control contracts.
-
Aftermarket specialists that expanded late-model coverage in 2025–2026 have strengthened their serviceable addressable market and are building aftermarket programs that mirror OEM part complexity.
-
Activated carbon manufacturers that provide granular to honeycomb media are central to the value chain; tighter collaboration with assemblers will determine which canister designs are commercially viable under new test protocols.
Recent industry moves that matter for 2026
-
Program and product expansions by aftermarket suppliers in 2025–2026 have increased competitive intensity in late-model replacement segments and accelerated coverage for popular truck and van platforms.
-
Regulatory updates introduced earlier in the decade are now fully impacting vehicle specification cycles, making 2026 a critical year for engineering validation and procurement commitments.
-
Material and component suppliers are responding with higher-capacity media formats and multi-layer canister concepts to meet combined diurnal, hot-soak, and running-loss requirements.
Actionable playbook for corporate decision-makers in 2026
Our report translates market intelligence into a set of prioritized actions for different stakeholder groups. High-level recommendations include:
-
OEMs and Tier 1 suppliers: accelerate early-stage material validation and build flexible canister platforms that can be tuned for purge strategy variations without retooling. Protect program timelines by locking qualified media sources and creating contingency material lists.
-
Materials producers: focus investments on process stability and certification-ready product ranges. Consider co-development programs with assemblers to fast-track in-vehicle validation under regulatory protocols.
-
Aftermarket players: leverage expanded part coverage as a differential while investing in traceability and quality assurance to capture OEM-equivalent repair volumes and reduce warranty leakage.
-
Investors and M&A teams: prioritize targets that combine validated technical IP in canister design with secure media supply, and evaluate bolt-on acquisitions that expand late-model aftermarket portfolios.
What the PW Consulting report delivers — practical content you can act on
This study is built as a toolset for decision-making rather than a descriptive catalog. Key deliverables include:
-
A robust historical-to-forecast market model that captures revenue trajectories and scenario outcomes through 2032, including sensitivity to regulatory stringency and material disruptions.
-
Supplier scorecards assessing technology breadth, program delivery track record, aftermarket reach, and vertical integration with media suppliers.
-
Supply-chain risk maps with mitigation playbooks — including dual-sourcing strategies, inventory buffering thresholds, and qualification timelines tied to program milestones.
-
Engineering and validation checklists aligned to current test protocols, enabling program teams to avoid late-stage non-compliance.
-
Commercial playbooks for OEMs, tier suppliers, and aftermarket firms that cover pricing levers, warranty exposure management, and MRO monetization strategies.
-
Scenario-based investment cases for materials and assembly assets, with NPV sensitivity to feedstock prices, capacity utilization, and regulatory shocks.
Why PW Consulting’s perspective is unique
We combine granular laboratory validation frameworks, primary interviews across OEM and supplier tiers, and a proprietary financial model calibrated to historical revenue dynamics. That blend yields not only a point forecast but also operationally relevant program timelines and procurement checklists that procurement managers and R&D leads can use immediately. Critically, while we disclose high-level market figures and concentration metrics to establish context, we intentionally withhold granular split tables and client-ready modeling worksheets from this overview to protect the integrity of our primary research and to ensure interested parties access the full dataset through the official report delivery channel.
Next steps — how to use this intelligence in 2026
For teams preparing 2026 budgets or negotiating supplier contracts, our guidance is straightforward: align program milestone calendars with regulatory validation timelines, lock material qualification and contingency sourcing by Q2–Q3 2026 for programs targeting 2028–2030 launches, and structure supplier contracts with performance and supply continuity clauses tied to defined testing protocols.
For investors and M&A teams, focus on companies that combine validated media supply or proprietary canister designs with proven aftermarket distribution — these are most likely to sustain margin resilience and capture aftermarket tailwinds as regulatory enforcement accelerates.
Accessing the full report
This press summary is intentionally high-level and omits detailed segmentations, regional splits, and downloadable financial models to preserve the exclusivity of the full deliverable. The full Automotive Fuel Vapor Canisters Market Report from PW Consulting includes the complete datasets, spreadsheet models, supplier profiles, and program-oriented checklists required to convert insight into action. To obtain a sample table of contents, licensing options, or to purchase the full report, please contact our research desk through our official channels.
PW Consulting remains available to brief executive teams, lead workshop sessions to translate the findings into roadmaps, and to provide bespoke scenario modeling tailored to your program timelines and risk tolerances.
For detailed analysis of this topic, please visit the official page: Automotive Fuel Vapor Canisters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Paper Coaster Market to Climb from USD 530M in 2025 to USD 807.5M by 2032 at a 6.2% CAGR
By pmarketresearch, 2026-07-01
Paper Coaster Market 2026 Strategic Outlook — PW Consulting Release
Executive preview
PW Consulting’s new Paper Coaster Market report (base year 2025; historical 2020–2025; forecast 2026–2032) offers a decision-grade, scenario-based road map for commercial leaders, procurement chiefs, and sustainability officers preparing for the next strategic cycle. Our bottom-up market model pegs the global paper coaster market at USD 530.0 Million in 2025 and, under the central scenario, growing at a compound annual growth rate (CAGR) of 6.2% to a projected market size exceeding USD 800 Million by 2032. This press release highlights the report’s strategic value for 2026 planning while deliberately withholding granular segment and regional tabulations to preserve the premium insights available in the full report.
Paper Coaster Market
Why this matters for 2026 decisions
- Procurement resilience. Buyers face a near-term operating environment where raw-material availability, regional pricing differentials and regulatory compliance costs will increasingly affect landed cost. The report provides procurement playbooks that translate market movements into actionable sourcing levers for 2026 budget cycles.
- Product and channel strategy. Hospitality, promotional and retail channels exhibit distinct demand patterns and margin dynamics. The intelligence in this study enables product managers to prioritize SKUs, packaging formats and premium finishes that optimize margin capture across channels without overexposing production capacity.
- Sustainability compliance as strategy. Extended Producer Responsibility (EPR) is no longer a compliance footnote: it is a commercial variable. The report maps EPR timelines, compliance cost drivers and strategic responses so companies can convert regulatory obligations into competitive differentiation.
- M&A and consolidation playbook. Fragmentation and capacity dispersion create arbitrage opportunities for roll-up strategies, vertical integration, and smart licensing of designs and finishes. Our target-screening framework identifies the commercial thresholds that make acquisitions accretive under multiple price and demand scenarios.
Data-driven view of market momentum
The market’s historical trajectory (2020–2025) demonstrates a steady recovery and expansion pathway, culminating in the USD 530.0 Million base. Our forecast period (2026–2032) models demand uplift from hospitality rebound, promotional spending normalization, and incremental premiumization of coaster formats and finishes. Under baseline assumptions — which incorporate expected macroeconomic growth, hospitality sector recovery and current raw-material trends — the market grows at a 6.2% CAGR. We model upside and downside cases to reflect faster adoption of premiumization and accelerated regulatory cost pass-through, respectively.
Paper Coaster Market
Segment and cost dynamics — what’s moving the needle
- Raw material dynamics. Paperboard supply-chain kinetics are central to cost and lead-time volatility. Paperboard pricing shows meaningful regional dispersion and episodic pressure driven by pulp availability and logistics — with some Asian and Southeast Asian markets exhibiting relatively higher input prices than North America in recent months. At the same time, U.S. producer price indices for corrugated and paperboard categories have shown structural stability through early 2026, which moderates short-term risk for North American manufacturers.
- Regulatory pressure. Several U.S. states have enacted EPR laws for packaging and paper products. This includes comprehensive frameworks in California, Colorado, Maine, Maryland, Minnesota, Oregon and Washington, with state programs phasing toward fully funded producer responsibilities over the remainder of the decade. Washington’s Recycling Reform Act and Minnesota’s EPR program introduce phased compliance windows and producer responsibility organization (PRO) models that will affect cost allocation and recycling-systems economics.
- Material choice and sustainability trade-offs. Demand and margin differentials between virgin and recycled substrates are shaped by both cost and brand positioning. The report models total cost of ownership for commonly used substrates and evaluates lifecycle and end-of-life implications under EPR scenarios so companies can align packaging choices with both cost efficiency and brand commitments.
Competitive landscape — practical takeaways
The paper coaster supply base remains fragmented, with the top three players accounting for a modest share of market value (CR3 ~18.5%) and the top five representing under one-third (CR5 ~28.3%). That structure produces meaningful opportunities at both national and regional levels for differentiation, scale efficiency and channel specialization. Key firm-level implications include:
Paper Coaster Market
- Coaster Factory (United States). A direct manufacturer with scale in custom pulpboard production and advanced finishing options (UV spot gloss, foil stamping). Coaster Factory’s strengths are high-volume capabilities and deep technical know-how in specialty finishes—an advantage for national chains and beverage brands seeking bespoke branding at scale. Recommended response: prioritize partnerships or preferred-supplier contracts emphasizing lead-time guarantees and co-investment in premium finishes.
- Alfred Mank (European operations). Known for a broader material palette (absorbent tissues, budgetboard, Linclass® Airlaid) and PE laminate backing options, Alfred Mank is positioned to win hospitality and event customers that value absorbency and premium tactile experiences. Recommended response: emphasize product differentiation in bids where absorbency or upscale finishes command price premiums.
- Hoffmaster (United States). Offers a stable line of pulpboard and budgetboard coasters across common formats with color and two-sided printing options—optimized for durability in foodservice. Their value proposition is reliability and breadth. Recommended response: for buyers prioritizing availability and consistency, Hoffmaster is a resilient choice; negotiations should focus on volume discounts and lead-time assurance.
- Totally Promotional (United States). A versatile supplier for promotional and event segments with a strong eco-friendly messaging angle. Their product mix suits campaigns and brand activation work. Recommended response: leverage their promotional expertise when demand is campaign-driven and price elasticity permits premium imprinting fees.
- Singreen Package & Guangzhou Zhi Xiang (China). Competitive players in bulk and wholesale supply with cost advantages for commoditized formats. They are natural partners for large-volume, price-sensitive programs and export-led sourcing strategies. Recommended response: develop dual-source strategies that combine domestic specialty suppliers with offshore commoditized lines to optimize landed cost without sacrificing premium options.
What the PW Consulting report delivers (actionable table of contents)
This is not a passive market overview. The full report is structured to support immediate commercial action in 2026:
- Methodology and data annex — transparent assumptions behind market sizing, unit economics, and scenario boundaries for 2026–2032.
- Demand forecasting engine — SKU- and channel-level scenarios with sensitivity to hospitality recovery, promotional spend and premium finishes.
- Procurement playbook — negotiation levers, contract clauses, and landed-cost models that incorporate EPR liabilities and anticipated freight dynamics.
- Supplier scorecards and benchmarking — capabilities, lead-time profiles, margin archetypes and finish-specialty matrices for primary suppliers and offshore alternatives.
- Sustainability and compliance roadmap — EPR impact assessment, cost pass-through modeling, packaging redesign levers and a two-year compliance action plan for producers and brand owners.
- M&A and partnership playbook — consolidation scenarios, accretion thresholds, and a prioritized screening methodology for tuck-ins and capability buys.
- Implementation templates — RFP language, KPI dashboards, and pilot program checklists to accelerate 90–180 day initiatives.
Strategic recommendations for executives
- Treat EPR as a structural cost — and an opportunity. Integrate projected producer fees into product P&Ls and use them as a basis to optimize material mix and return on shelf-space.
- Adopt a dual-sourcing approach. Combine domestic specialty suppliers for premium lines with offshore commoditized sourcing for base volumes to protect margins and service levels.
- Invest selectively in finishing capabilities. Premium finishes deliver disproportionate brand value for key accounts—structure commercial offers that monetize these upgrades rather than absorbing the cost.
- Use M&A to capture scale benefits in distribution and specialty finishing. The market’s fragmentation means attractive buy-and-build returns if integration targets are chosen against robust margin-synergy models.
Access and next steps
PW Consulting’s Paper Coaster Market report is built to be operational on day one of 2026 planning cycles. This release intentionally summarizes the strategic implications without publishing segmented regional or application-level datasets that are included in the full analysis. For procurement teams, strategy groups and sustainability leads evaluating 2026 commitments, the full report includes the granular segmentations, supplier scorecards, and editable implementation templates needed to act decisively.
Visit our report page to obtain the complete dataset, downloadable annexes and a complimentary 60‑minute briefing with the PW Consulting industry team. The briefing is designed to align the report’s scenarios to your business model and produce a customized 100–180 day action plan.
PW Consulting — strategic clarity for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Paper Coaster Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Home Pet Deworming Market to Reach USD 4,975.99 Million by 2032 on a 6.75% CAGR
By pmarketresearch, 2026-07-01
Home Pet Deworming Medicine Market: Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market intelligence on the Home Pet Deworming Medicine market maps a commercially significant, resilient category that is entering its next phase of growth and structural reconfiguration. Our analysis shows the market expanding from a historical base of approximately USD 2.27 billion in 2020 to roughly USD 3.15 billion in 2025, with a projected compound annual growth rate (CAGR) of 6.75% over the 2026–2032 forecast window. Under that baseline trajectory the market is on course to approach USD 5.0 billion by 2032, implying sustained demand for both prescription-adjacent and over‑the‑counter pet deworming solutions.
Home Pet Deworming Medicine Market
This briefing is a strategic “trailer”: it surfaces the near-term commercial implications and executive actions that matter for 2026, demonstrates the analytical depth of the full report, and deliberately withholds granular segment-level tables and precise sub‑regional shares to encourage acquisition of the source report for detailed decision-making inputs.
Home Pet Deworming Medicine Market
Why this matters for 2026 — the executive takeaways
- Structural growth with tactical inflection points. The macro expansion underpins continued investment appetite: larger incumbents and challenger brands have room to grow through product line extensions, channel penetration, and formulation innovation. However, growth is uneven across modalities and geographies, and 2026 will be a year when selective investment decisions — not blanket scale-ups — generate value.
- Margin pressure from generic entrants and API sourcing. The advent of additional generic fenbendazole options and concentrated API production in Asia is resetting cost and pricing dynamics. Firms that secure resilient supply chains and flexible pricing strategies will protect margins and commercial momentum.
- Regulatory and labeling momentum affects go-to-market timing. FDA activity in recent quarters has influenced product availability and OTC labeling expectations; regulatory rhythm will determine timing for launches, relaunches, and promotional campaigns.
- Channel and care model evolution. The continuum from veterinary clinics to retail and e-commerce is becoming more fluid. Brands that align product formats, packaging, and messaging to channel-specific purchase triggers will capture higher lifetime value per pet.
Market dynamics shaping 2026 strategies
Several convergent forces are reshaping the competitive playing field:
Home Pet Deworming Medicine Market
- Persistent pet health demand: Companion animal ownership and preventive care penetration remain core demand engines. Pet owners increasingly view deworming as a routine component of wellness, creating recurring purchase behavior that favors multi-dose and palatable formats.
- Product format differentiation: While multiple delivery formats coexist, formulation convenience (palatability, single-dose effectiveness), safety labeling, and perceived value influence both channel acceptance and repeat purchase. R&D and packaging investments that improve user experience can deliver disproportionate returns.
- Supply-side economics: API concentration in parts of Asia—particularly for fenbendazole—has created a cost-advantaged supply base but also heightens geopolitical and quality-control risk. Manufacturers and private-label partners should reassess supplier diversification and qualification strategies in 2026.
- Regulatory catalysts: Recent approvals and emergency authorizations show regulators are actively engaged in the companion animal parasiticide space. These actions affect timing, labeling, and the competitive landscape for both prescription and OTC products.
Regulatory and industry events — implications for 2026
- New generic approvals accelerate price competition. The January 2026 FDA approval of a generic fenbendazole oral suspension highlights a trend: established chemical classes are becoming accessible to lower-cost manufacturers. Expect margin compression in categories where generics can replicate efficacy and labeling.
- Targeted emergency authorizations influence tactical response. Recent emergency use activity in late 2025 underscores how episodic regulatory actions (e.g., for emergent parasitic threats) can create short‑term procurement needs and reputational opportunities for market participants with pre‑cleared products.
- Labeling and OTC compliance remain non-negotiable. Home-use dewormers must adhere to approved labeling and clear usage instructions. Companies that preemptively optimize label clarity and consumer education reduce adverse events, OTC recalls, and reputational risk.
Competitive landscape — who to watch and why
The market remains led by established animal-health multinationals and a cohort of specialized veterinary pharmaceutical firms. Market concentration metrics show a moderate level of aggregation: the top three firms hold a meaningful portion of market value, and the top five consolidate an even larger share—creating both barriers and partnership opportunities for mid‑sized players.
- Zoetis (Parsippany, NJ) — A global leader with an extensive companion animal portfolio. Zoetis’s product set includes well‑established liquid formulations for puppies and dogs; its strengths are brand recognition, veterinary channel penetration, and scale manufacturing.
- Merck Animal Health (Rahway, NJ) — Known for broad-spectrum chemistries, Merck competes on proven efficacy and channel trust. Its established canine dewormer positions it well for clinical recommendations and bundled preventive care offerings.
- Elanco (Greenfield, IN) — Combines an aggressive commercial footprint with recent regulatory engagement. Its chewable and specialty offerings make Elanco a versatile competitor across retail and clinic channels.
- Virbac (Fort Worth, TX) — Focused on palatable chewables and targeted formulations; Virbac emphasizes product differentiation through flavoring and ease-of-administration for pet owners.
- PetIQ (Eagle, ID) — A retail-focused challenger with strong over‑the‑counter positioning and private-label agility; PetIQ competes on value and mass channel reach.
- Boehringer Ingelheim, Ceva, Dechra — These regional and global players augment the market through veterinary networks and niche product portfolios, often serving as innovation partners or acquisition targets.
- Central Garden & Pet (Farnam) and Durvet — Players with established OTC and farm-to-pet channels that can leverage distribution to scale companion animal formulations rapidly.
Collectively, incumbents combine brand trust, clinical trial data, and channel partnerships. Newer or niche entrants must therefore compete on either price (leveraging lower-cost APIs), user experience (palatability, dosing simplicity), or channel innovation (direct-to-consumer subscription models, vet telehealth integration).
What the PW Consulting report delivers — practical, transaction-ready outputs
Our full report is designed for commercial and corporate teams planning 12–36 month initiatives. Key practical deliverables include:
- Proprietary market-sizing models with historical validation (2020–2025) and scenario-based forecasts to 2032, including sensitivity analysis around API cost shocks and regulatory disruptions.
- Channel economics and go‑to‑market playbooks tailored to veterinary clinics, retail chains, e-commerce, and hybrid subscription models; recommended promotional mixes by channel archetype.
- Product positioning matrices that map efficacy, convenience, and price-to-value for chewables, spot-on treatments, and oral suspensions — coupled with SKU rationalization guidance for portfolio managers.
- Supply-chain risk heatmaps and a supplier‑segmentation framework reflecting API concentration, lead time risk, and quality-control checkpoints; actionable supplier diversification options.
- M&A and partnership screening tools: a short list of capability gaps where bolt‑on acquisitions or co‑development agreements can accelerate time‑to‑market, with payback scenarios.
- Regulatory playbook summarizing labeling requirements, filing timelines, and contingency plans for emergency authorizations or rapid approvals.
Strategic recommendations for 2026
- Prioritize supply resilience over lowest-cost sourcing. Given API concentration and recent generic entries, build dual sourcing, buffer inventory strategies, and supplier audit schedules into 2026 procurement plans.
- Segment products by customer journey, not just formulation. Design packaging, dosing guidance, and digital instruction flows that reduce perceived complexity for first-time pet owners and increase adherence in recurring purchasers.
- Be prepared for accelerated generic competition. Where chemical classes are off‑patent, protect margins through branded value propositions (convenience, palatability, vet endorsement) rather than head‑to‑head price confrontation.
- Leverage regulatory milestones as commercial catalysts. Monitor approval pipelines and emergency-use authorizations closely; align marketing and distribution ramp plans to regulatory timing to capture capture-to-market windows.
- Invest selectively in channels with data feedback loops. Digital and subscription channels that generate owner adherence and repeat purchase data create durable competitive advantage; prioritize pilots that can be scaled quickly.
- Use M&A selectively to fill capability gaps. Consider acquiring regional manufacturing or formulation capabilities that shorten lead times and reduce supply risk, or select brands that bring differentiated consumer trust in key markets.
Methodology note and data provenance
The report synthesizes company filings, regulatory databases, proprietary surveys of veterinarians and pet owners, trade-channel scans, and primary supplier interviews. Our forecasting applies scenario-based modeling to historical sales (2020–2025) and applies a 6.75% CAGR baseline for 2026–2032, with downside and upside variants reflecting API cost shocks and accelerated generic penetration. For confidentiality and strategic clarity, this public preview omits the granular tables, regional splits, and SKU-level forecasts that are included in the full dataset.
Next steps — how to use this intelligence in 2026
For executive teams preparing 2026 plans, the full PW Consulting Home Pet Deworming Medicine Market report provides the actionable inputs needed to:
- Build 12–36 month product and channel roadmaps supported by detailed financial models;
- Structure supplier contracts and inventory buffers to mitigate API concentration risk;
- Design launch sequences aligned to regulatory windows; and
- Screen M&A targets and JV partners with quantifiable payback thresholds.
If your team seeks a compact strategic workshop or a tailored version of the dataset (e.g., custom country-level demand curves, SKU P&L templates, or due-diligence checklists), PW Consulting can deliver modular deliverables aligned to board and investor decision calendars.
Call to action
This preview exposes the strategic inflection points that will define winners and laggards in 2026. To access the full segmentation tables, country and channel breakdowns, company scorecards, and the downloadable Excel model that underpins our forecasts, please consult the full Home Pet Deworming Medicine Market report on the PW Consulting website or contact our industry practice. The complete dataset contains the granular inputs required to translate the insights above into executable plans and financial commitments.
For detailed analysis of this topic, please visit the official page: Home Pet Deworming Medicine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com