

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Global Corn Flour Market to Expand at a 4.25% CAGR Through 2032

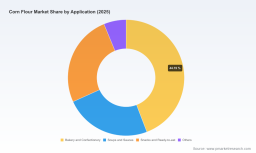
Corn Flour Market: Strategic Imperatives for 2026 — PW Consulting Preview
PW Consulting’s new Corn Flour Market report (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes macro growth trajectories, competitive dynamics, input-cost volatility and regulatory inflection points into a compact set of decision-ready insights for corporate leaders planning for 2026. This preview outlines the strategic value of the report: how procurement, product development, capacity planning, sustainability programs, and M&A strategies should adapt as the global corn flour market expands at a measured pace (CAGR 4.25% through 2032), growing from a 2025 base of USD 6.45 Billion to an expected USD 8.63 Billion by 2032.
Corn Flour Market
Why this report matters for 2026 planning
-
Timing: 2026 is a hinge year for many operators — legacy financing cycles, capital commitments made in 2023–2024, and new regulatory/tariff outcomes converge to alter supply-risk profiles and ROI expectations.
Corn Flour Market -
Clarity on trajectory: The market’s steady compound annual expansion (4.25% through 2032) signals predictable end-market demand growth but also highlights where margin pressure and differentiation will matter most.
Corn Flour Market -
Actionable intelligence: The report translates macro numbers into operational levers — from hedging frames and contract terms to plant utilisation thresholds and product formulation roadmaps — that procurement, commercial and strategy teams can apply immediately.
Market snapshot (headline metrics)
Key headline figures in the report: the global corn flour market moved from USD 5.94 Billion in 2023 to USD 6.45 Billion in 2025, and is forecast to reach approximately USD 8.63 Billion by 2032 under our central scenario. These topline dynamics, combined with observed market concentration metrics (CR3 ~28.5%; CR5 ~38.2%), point to a market that is neither a pure commodity nor tightly consolidated — an environment where scale, specialization and route-to-market decisions materially affect margin capture.
Five strategic shifts companies must address in 2026
-
Procurement and input-cost management: USDA’s 2025/26 season-average projection and contemporaneous futures activity (notably market quotes in the 463–466 USd/BU range as of April 2026) are shifting procurement calculus from short-cycle spot buying to layered hedging and forward contracting. Buyers should stress-test procurement policies across three scenarios (low, baseline, upside) and set triggers for rolling coverage and supplier diversification.
-
Product portfolio and formulation strategy: Margin uplift will not come from volume alone. Manufacturers should prioritize ingredient innovation (e.g., texturizing blends, gluten-free positioning, nixtamalized specialty lines) and channel-specific SKUs to capture higher-value programs in retail and foodservice. The report maps several high-opportunity product adjacencies and provides go-to-market timing windows aligned to forecast demand shifts.
-
Capacity, network and capital allocation: Given the steady CAGR and moderate market concentration, capital investments should be targeted: brownfield upgrades and flexible milling lines often offer better risk-adjusted returns than new greenfield builds. The full study includes utilisation thresholds and simple payback scenarios by plant type to aid capital committees in 2026 approval cycles.
-
Sustainability as a commercial lever: Recent moves by major processors to introduce regeneratively sourced flours and to decarbonize milling operations underscore how ESG credentials are becoming table stakes for certain buyers. The report offers a practical roadmap for integrating regenerative sourcing pilots, measuring scope-3 impacts across the supply chain, and converting sustainability investments into commercial differentiation with blue-chip customers.
-
Regulatory and trade risk management: Title 21 standards and the evolving U.S. tariff landscape — including a recent judicial decision overturning most 2025 IEEPA import tariffs and the prior implementation of reciprocal tariffs — create both compliance burdens and cost/revenue opportunities. The report provides a regulatory matrix and scenario playbooks for customs strategy, tariff mitigation, and rapid compliance checklists for product labelling and standards of identity.
Competitive landscape — what to watch in 2026
The corn flour competitive field is characterized by a mix of global agribusinesses, specialty ingredient firms, large consumer food companies with upstream integration, and regional millers focused on niche applications. The market’s CR3 and CR5 indicate room for differentiation by specialists and mid-sized players. In 2026, three dynamics will be decisive:
-
Vertical integration and supply-chain control: Large processors and agribusinesses continue to leverage scale to integrate wet and dry milling, co-products valorisation, and logistics. Expect continued investment in traceability and supplier programs.
-
Specialization and premiumization: Niche producers and specialty ingredient firms can protect or expand margins through certified non-GMO, organic, nixtamalized and gluten-free offerings — segments where brand credibility and certification matter.
-
Consolidation and partnerships: The fragmented mid-market is ripe for bolt-on acquisitions and commercial partnerships that provide channel access or technical capabilities rather than just capacity.
PW Consulting’s competitive profiles include leading global processors and specialists whose strategic moves will shape supply and pricing in 2026 and beyond. Among the firms covered are major processors with integrated milling platforms, specialty ingredient suppliers offering tailored texturizing solutions, established masa and nixtamalized producers with cultural and formulation expertise, and regional millers focused on industrial customers and niche retail segments. The report highlights recent corporate developments — for example, a leading global processor’s launch of regeneratively sourced flours and another’s announcement of a new ethanol complex in Brazil — and interprets their likely market impacts.
Practical deliverables — what’s inside the full report
The full PW Consulting Corn Flour Market report is designed to be immediately usable by commercial, procurement and strategy teams. Key deliverables include:
-
Proprietary topline and forecast model (2020–2032) with downloadable scenario variants and sensitivity tables.
-
Regulatory and tariff playbook mapping standards of identity, labelling checkpoints, and cross-border compliance actions for major trade lanes.
-
Supplier and competitor dossiers with strategic positioning, capability maps and recent corporate initiatives.
-
Commercial playbooks — pricing model templates, margin waterfall diagnostics, and channel-specific go-to-market recommendations.
-
Operational tools — utilisation thresholds, payoff analysis for brownfield versus greenfield options, and a small-capex product pilot checklist.
-
Risk matrix and mitigation options covering raw-material volatility, regulatory shocks, and trade disruptions (with recommended contingency contracts and insurance structures).
How executives should use this intelligence in 2026
-
Procurement leaders: adopt a layered hedging approach informed by the report’s scenario outputs; renegotiate supply agreements to include flexibility clauses and sustainability premiums where commercially viable.
-
Product and R&D heads: prioritize two to three high-margin formulations for development, leveraging available ingredient adjacencies and certification pathways documented in the study.
-
Operations and capex committees: prefer flexible capital that can be redeployed across product lines; use the included utilisation model to set go/no-go thresholds for 2026 investments.
-
Corporate strategy and M&A teams: target bolt-ons that add channel access or technical formulation expertise; use the competitive dossiers when approaching potential partners or targets.
Reading between the lines: risks and upside
The market’s steady growth masks asymmetric risks and opportunities. Input-price shocks remain a tail risk; conversely, favorable trade rulings or policy shifts can unlock import/ export flows that materially alter regional competitive balances. Sustainability initiatives are becoming commercial differentiators for premium channels but require careful ROI justification. The report quantifies these trade-offs and offers prioritized, pragmatically sequenced actions — the kind that differentiate winners from followers in 2026.
Next steps — where to get the full data
This release is intentionally selective: it highlights the strategic insights you need to evaluate the 2026 agenda, while preserving the detailed regional, application and product-level splits for subscribers. The full report contains the comprehensive tables, downloadable models and the granular segmentation that procurement, commercial and strategy teams will require to execute against the playbooks outlined above.
To access the complete report, the interactive forecast model, and the Excel workbooks that translate these insights into executable plans, please visit PW Consulting’s Corn Flour Market page. The full dataset includes the region-by-region, type-by-type and application-by-application breakdowns required for precise budgeting, sourcing and M&A diligence.
PW Consulting — strategic insight, operational rigor, and practical tools to turn market forecasts into 2026-ready decisions.
For detailed analysis of this topic, please visit the official page: Corn Flour Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com