

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Heavy Industry Hydraulic Systems Market to Top USD 56.83 Billion by 2032

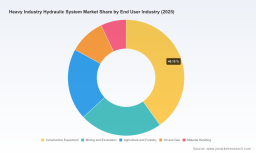
Heavy Industry Hydraulic System Market: Strategic Insights for 2026 Decision‑Makers
Executive snapshot
The heavy industry hydraulic system market is on a steady expansion path, driven by continued demand for reliable power-dense actuation in construction, mining, agriculture and other off‑highway sectors, coupled with accelerating innovation in electrification and digital controls. Our benchmarking of the historical period (2020–2025) and forward-looking forecasts (2026–2032) shows a compound annual growth rate of 4.85% across the forecast window. After recovering from pandemic‑era disruption, global market value moved from the low‑thirty‑billion USD range in 2020 to roughly forty‑billion USD by the 2025 base year, with projections pointing to meaningful upside by the early 2030s under current regulatory and technology trajectories.
Heavy Industry Hydraulic System Market
Why 2026 is a decision inflection point
-
Regulatory and standards momentum: The introduction of ISO 18464:2025 institutes a formal design methodology aimed at minimizing energy consumption in hydraulic fluid power systems. For product teams and compliance officers, the standard transforms “nice‑to‑have” efficiency features into near‑table stakes for new equipment certification and procurement tenders.
Heavy Industry Hydraulic System Market -
Technology convergence: Electrified hydraulic power units (eHPUs), smarter valve architectures and embedded telematics are moving from demonstration projects to OEM roadmaps—illustrated by award‑winning prototypes and prominent showcases at industry trade events earlier in 2026.
Heavy Industry Hydraulic System Market -
Supply‑side volatility: Raw material dynamics—particularly steel price fluctuation—are imposing cost and lead‑time variability across pumps, cylinders and valve casings. Procurement strategies established in 2026 will materially affect margin trajectories for the remainder of the forecast horizon.
What the PW Consulting report delivers (practical, action‑oriented)
-
Transparent market sizing and trend methodology calibrated to the 2025 base year and a 2026–2032 forecast window—enabling scenario comparisons and stress tests aligned to corporate planning cycles.
-
Demand drivers and elasticity analysis across industry use‑cases; technology adoption curves for digital hydraulics, eHPUs and energy‑recovery subsystems; and sensitivity matrices for steel and critical component cost inputs.
-
Supplier benchmarking and capability heatmaps that synthesize engineering performance, aftermarket reach, digital maturity and sustainability credentials into a decision matrix for sourcing, alliance and M&A prioritization.
-
Commercial playbooks for go‑to‑market optimization: price‑to‑value strategies, service monetization models, and channel segmentation advice for OEMs, Tier‑1s and targeted aftermarket players.
-
Operational checklists and procurement tooling: inventory hedging templates, dual‑sourcing frameworks, and product‑life‑cycle roadmaps that translate market signals into executable 12–24 month plans.
-
Executive scenarios: three modelled futures that show the financial and competitive impact of accelerated electrification, stricter energy regulation, or sustained raw‑material inflation—quantified to support board‑level deliberations in 2026.
Competitive landscape — who matters and why
Competition in the heavy hydraulic space remains diversified. Market concentration data show that the top three global players account for roughly one‑third of the market, while the top five capture under half—an industry structure that preserves both scale advantages for incumbents and opportunity for well‑positioned challengers.
-
Bosch Rexroth AG: A technology leader in connected and energy‑efficient hydraulics, their portfolio of pumps, valves, manifolds and integrated units positions them strongly where system integration and digitalization are prioritized—particularly in steel processing and large‑scale industrial installations.
-
Parker Hannifin Corporation: Broad product breadth and strong engineered solutions capability make Parker an attractive partner for OEMs seeking modular, serviceable subsystems and a pathway to smart hydraulics at scale.
-
Danfoss Power Solutions: With an explicit focus on energy efficiency and electrification interfaces, Danfoss is shaping the bridge between classical hydraulic actuation and hybrid/electric drive architectures—an important strategic vector for customers targeting lower lifecycle emissions.
-
Eaton Corporation: Known for high‑pressure, durable components, Eaton remains a go‑to supplier for operations where robustness and uptime trump cost‑minimization—mining and oil & gas remain core segments for such propositions.
-
European specialists (HYDAC, Bucher, HAWE, Linde Hydraulics): These firms continue to compete on niche engineering depth—filtration, bespoke valves, and high‑pressure systems—often winning on performance and lifetime cost rather than initial price.
-
Japanese OEM suppliers (Kawasaki, KYB) and integrated machinery producers (Caterpillar, select Asian manufacturers): these players combine regional manufacturing scale with vertical integration and strong OEM relationships, particularly across Asia Pacific markets.
-
Regional and specialized manufacturers: A competitive layer of regional cylinder and systems makers provides rapid lead times and cost flexibility for local OEMs; strategic buyers should evaluate these suppliers for nearshoring and risk‑mitigation plays.
Recent product and market signals to watch in 2026
-
Trade show demonstrations (CONEXPO‑CON/AGG 2026 and others) highlighted next‑generation mobile hydraulic solutions and purpose‑built cylinders intended to reduce total cost of ownership for OEMs.
-
An eHPU product recognized at a major agricultural expo demonstrates the maturation of electrified hydraulics from lab to field—an immediate indicator for fleet electrification pilots and service model redesign.
-
These signals, combined with ISO 18464:2025 and mounting regional energy efficiency mandates, suggest a near‑term bifurcation: premiumized, efficiency‑centric systems will grow faster and command higher margins, while legacy platforms face intensifying cost pressure.
How different corporate functions should use the report in 2026
-
Product and R&D: Prioritize modular architectures and a roadmap for electrified subsystems. Use the report’s technology adoption curves and component scorecards to set 18–36 month R&D milestones tied to certification timelines and OEM procurement cycles.
-
Procurement & Supply Chain: Implement the report’s supplier‑risk matrix and raw‑material sensitivity analysis to redesign contracts (indexing to steel price bands, dual‑sourcing critical forgings) and to evaluate nearshoring options where lead‑time reduction justifies incremental cost.
-
Commercial & Pricing: Leverage the customer‑willingness‑to‑pay frameworks and service monetization models to transition from capex‑led sales to outcome‑based and subscription offerings for fleets adopting telematics and preventive maintenance.
-
M&A & Corporate Development: Use the supplier benchmarking and fragmentation analysis to identify tuck‑ins that add electrification IP, regional aftermarket coverage or vertical coverage in pumps/cylinders—especially valuable in a landscape where the top five do not dominate outright.
-
Operations & Aftermarket: Adopt the operational checklists to reduce lifecycle costs through filtration strategies, predictive maintenance enabled by embedded sensors, and parts standardization across platforms.
Scenario framing and investment theses
PW Consulting models three plausible 2026‑onward scenarios: (1) Accelerated electrification driven by regulatory push and OEM investment, where eHPUs and hybrid architectures capture above‑average share; (2) Gradual transition where energy efficiency standards incrementally raise average selling prices but preserve core hydraulic demand; and (3) Cost‑pressure environment where raw material shocks compress margins and accelerate consolidation. Each scenario points to distinct winners—technology‑leading integrators, nimble regional manufacturers, and service‑centric business models respectively—and our report quantifies breakeven timelines and capital requirements for each path.
Executive recommendation — actions to prioritize in 2026
-
Immediate (0–12 months): Conduct a supplier stress test using our procurement toolkit; pilot an electrified hydraulic subsystem with clear test metrics aligned to ISO 18464 benchmarks.
-
Near term (12–24 months): Reprice service contracts to capture value from digital maintenance; implement dual‑sourcing for critical steel‑intensive components and lock in forward pricing on long‑lead items where appropriate.
-
Medium term (24–48 months): Evaluate M&A targets that accelerate electrification, digital controls, or regional aftermarket reach; retool product roadmaps for modulated, software‑enabled hydraulics that can be upgraded in the field.
Accessing the full intelligence
This release outlines the strategic contours and actionable line‑items we believe every heavy hydraulic market participant should consider during 2026 planning. To support tactical execution, the full PW Consulting Heavy Industry Hydraulic System Market report includes the granular regional and application splits, component‑level revenue forecasts, supplier scorecards, and downloadable financial models that the summary omits. Those granular datasets and scenario‑specific dashboards are intentionally retained in the complete report to support client engagements and bespoke strategy workshops.
For boards, CEOs and functional leaders preparing 2026 budgets and three‑year strategic plans, the report is designed as a decision‑support system: not only signaling where the business is headed, but providing the tools to operationalize response. Contact PW Consulting to arrange a briefing, obtain the full dataset, or commission a tailored analysis aligned to your corporate risk tolerance and investment priorities.
For detailed analysis of this topic, please visit the official page: Heavy Industry Hydraulic System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com