

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Fuel Vapor Canisters Market to Reach USD 3,730.7 Million by 2032 on a 3.42% CAGR, Led by Asia Pacific at USD 1,375.27 Million

Automotive Fuel Vapor Canisters Market: Strategic Imperatives for 2026 Decision-Makers
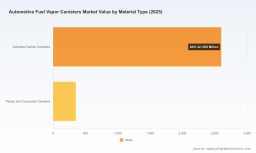
PW Consulting’s new Automotive Fuel Vapor Canisters Market Report synthesizes five years of historical performance with a forward-looking, scenario-driven forecast to equip OEMs, tier suppliers, material producers, aftermarket players, and investors with decision-grade intelligence for 2026 and beyond. The market reached USD 2,952.2 Million in our base year (2025) and, under our central scenario, grows at a compound annual growth rate (CAGR) of 3.42% through 2032 — reaching roughly USD 3,730.7 Million by the end of the forecast horizon. These headline metrics understate the structural shifts now reshaping the business model for vapor control systems: intensified regulatory testing protocols, material feedstock pressures, and evolving OEM packaging requirements are forcing a rethink of product design, sourcing, and go-to-market strategies.
Automotive Fuel Vapor Canisters Market
Why this report matters for 2026 planning
-
Timing: 2026 is a pivot year for compliance and product launches. Regulatory test protocols and minimum canister requirements adopted in recent years are fully binding on new-model development cycles that begin in 2026 and crystallize procurement decisions for model years 2028–2030.
Automotive Fuel Vapor Canisters Market -
Risk management: Marginal shifts in activated carbon supply and specification have outsized implications for canister validation, warranty exposure, and production continuity. Our supply‑chain stress-tests quantify exposure by component class and identify material substitution thresholds that preserve regulatory compliance.
Automotive Fuel Vapor Canisters Market -
Competitive tactics: Market concentration is meaningful — the three largest suppliers control a majority share and the top five account for over 70% of the market by revenue — creating a dual dynamic of supplier power vis-à-vis raw material vendors and opportunity for focused challengers in niche subsegments.
Market trajectory and structural drivers
Overall market growth over the forecast period is modest but resilient. Two forces shape the trajectory: regulatory tightening on evaporative emissions and the continuing evolution of vehicle platforms. Stricter running-loss and canister sizing requirements, aligned with advanced butane-loading test protocols, are increasing the technical bar for canister performance and validation. At the same time, the mixed vehicle parc — including hybrids and a long tail of internal combustion engine (ICE) vehicles in many regions — sustains demand for evaporative control solutions even as the industry pursues electrification.
For 2026 planners, the practical implications are clear. Design windows are narrowing: specification freeze dates must accommodate more exhaustive canister cycling and breakthrough testing. Procurement strategies must incorporate tiered material qualification pathways that balance cost, performance, and availability. And product roadmaps should prioritize modular, scalable canister architectures that can be optimized to different purge strategies and fuel blends without a complete redesign.
Regulatory and testing landscape — what changes now mean in practice
Regulatory authorities have moved beyond prescriptive sizing to define test-based performance thresholds that directly inform acceptable media and housing choices. The adoption of new evaporative emission test procedures with defined breakthrough points and cycle protocols forces a stronger integration between materials science and system engineering. For program managers this translates into three programmatic shifts:
-
Upstream validation: earlier and deeper lab validation of activated carbon media under vehicle-representative cycling to avoid late-stage failures during certification.
-
Design for testability: canister and purge strategies must be engineered to pass standardized loading/purge sequences while meeting OEM packaging and durability requirements.
-
Cross-functional procurement: procurement, engineering, and compliance teams must set joint qualification gates that recognize both material variability and equipment-level tolerances.
Material dynamics: activated carbon at the center
Activated carbon remains the foundational adsorbent for fuel vapor canisters. However, feedstock variability and increasing demand for higher-capacity, durable media introduce supply-side volatility. Our analysis highlights pressure points at the interface between feedstock sourcing, media processing, and final canister assembly. Firms that can guarantee consistent butane working capacity metrics and robust cycle life will command pricing power or secure long-term commitments from OEMs. For materials suppliers and prospective investors, the opportunity lies in scale, process stability, and certification-ready product lines.
Competitive landscape — strategic profiles and tactical moves
The competitive set consists of entrenched global players with strong OEM relationships, niche specialists focused on aftermarket breadth, and material incumbents supplying the carbon media. Key themes we observed during our industry mapping and primary research:
-
Depth of product portfolio matters. Firms with modular canister platforms and integrated purge/vent solutions enjoy faster ramp-up with OEM programs and can reduce unit cost through common tooling and validated subassemblies.
-
Aftermarket scale is a strategic asset. Players who combine OEM-level product quality with extensive aftermarket coverage can monetize extended lifecycle service needs and capture retrofit opportunities driven by regulatory enforcement.
-
Material suppliers retain leverage where high-performance carbon formulations are validated for regulatory test cycles. Vertical coordination between media producers and canister assemblers shortens qualification timelines.
Representative company observations (non-exhaustive):
-
Suppliers with long-standing global portfolios and modular designs are positioned to support a wide tank-size range and multi-fuel applications — a strategic advantage as fuel blends and OEM specifications diversify.
-
European technical leaders continue to invest in complete canister systems, including valves and ventilation lines, positioning them strongly for integrated emission control contracts.
-
Aftermarket specialists that expanded late-model coverage in 2025–2026 have strengthened their serviceable addressable market and are building aftermarket programs that mirror OEM part complexity.
-
Activated carbon manufacturers that provide granular to honeycomb media are central to the value chain; tighter collaboration with assemblers will determine which canister designs are commercially viable under new test protocols.
Recent industry moves that matter for 2026
-
Program and product expansions by aftermarket suppliers in 2025–2026 have increased competitive intensity in late-model replacement segments and accelerated coverage for popular truck and van platforms.
-
Regulatory updates introduced earlier in the decade are now fully impacting vehicle specification cycles, making 2026 a critical year for engineering validation and procurement commitments.
-
Material and component suppliers are responding with higher-capacity media formats and multi-layer canister concepts to meet combined diurnal, hot-soak, and running-loss requirements.
Actionable playbook for corporate decision-makers in 2026
Our report translates market intelligence into a set of prioritized actions for different stakeholder groups. High-level recommendations include:
-
OEMs and Tier 1 suppliers: accelerate early-stage material validation and build flexible canister platforms that can be tuned for purge strategy variations without retooling. Protect program timelines by locking qualified media sources and creating contingency material lists.
-
Materials producers: focus investments on process stability and certification-ready product ranges. Consider co-development programs with assemblers to fast-track in-vehicle validation under regulatory protocols.
-
Aftermarket players: leverage expanded part coverage as a differential while investing in traceability and quality assurance to capture OEM-equivalent repair volumes and reduce warranty leakage.
-
Investors and M&A teams: prioritize targets that combine validated technical IP in canister design with secure media supply, and evaluate bolt-on acquisitions that expand late-model aftermarket portfolios.
What the PW Consulting report delivers — practical content you can act on
This study is built as a toolset for decision-making rather than a descriptive catalog. Key deliverables include:
-
A robust historical-to-forecast market model that captures revenue trajectories and scenario outcomes through 2032, including sensitivity to regulatory stringency and material disruptions.
-
Supplier scorecards assessing technology breadth, program delivery track record, aftermarket reach, and vertical integration with media suppliers.
-
Supply-chain risk maps with mitigation playbooks — including dual-sourcing strategies, inventory buffering thresholds, and qualification timelines tied to program milestones.
-
Engineering and validation checklists aligned to current test protocols, enabling program teams to avoid late-stage non-compliance.
-
Commercial playbooks for OEMs, tier suppliers, and aftermarket firms that cover pricing levers, warranty exposure management, and MRO monetization strategies.
-
Scenario-based investment cases for materials and assembly assets, with NPV sensitivity to feedstock prices, capacity utilization, and regulatory shocks.
Why PW Consulting’s perspective is unique
We combine granular laboratory validation frameworks, primary interviews across OEM and supplier tiers, and a proprietary financial model calibrated to historical revenue dynamics. That blend yields not only a point forecast but also operationally relevant program timelines and procurement checklists that procurement managers and R&D leads can use immediately. Critically, while we disclose high-level market figures and concentration metrics to establish context, we intentionally withhold granular split tables and client-ready modeling worksheets from this overview to protect the integrity of our primary research and to ensure interested parties access the full dataset through the official report delivery channel.
Next steps — how to use this intelligence in 2026
For teams preparing 2026 budgets or negotiating supplier contracts, our guidance is straightforward: align program milestone calendars with regulatory validation timelines, lock material qualification and contingency sourcing by Q2–Q3 2026 for programs targeting 2028–2030 launches, and structure supplier contracts with performance and supply continuity clauses tied to defined testing protocols.
For investors and M&A teams, focus on companies that combine validated media supply or proprietary canister designs with proven aftermarket distribution — these are most likely to sustain margin resilience and capture aftermarket tailwinds as regulatory enforcement accelerates.
Accessing the full report
This press summary is intentionally high-level and omits detailed segmentations, regional splits, and downloadable financial models to preserve the exclusivity of the full deliverable. The full Automotive Fuel Vapor Canisters Market Report from PW Consulting includes the complete datasets, spreadsheet models, supplier profiles, and program-oriented checklists required to convert insight into action. To obtain a sample table of contents, licensing options, or to purchase the full report, please contact our research desk through our official channels.
PW Consulting remains available to brief executive teams, lead workshop sessions to translate the findings into roadmaps, and to provide bespoke scenario modeling tailored to your program timelines and risk tolerances.
For detailed analysis of this topic, please visit the official page: Automotive Fuel Vapor Canisters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com