

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Biomass Power Equipment Market Poised to Grow at a 6.99% CAGR Through 2032

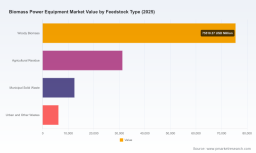
Biomass Power Equipment Market — Strategic Outlook for 2026: A PW Consulting Brief
As global energy systems accelerate the transition away from unabated fossil fuels, biomass power equipment has re-emerged as a pragmatic bridge technology for utilities, industrial off-takers, and municipal energy planners. PW Consulting’s latest market study examines the commercial dynamics and technology vectors shaping the biomass power equipment market through 2032, delivering a decision-grade framework that corporate strategists and capital allocators must engage with before making 2026 commitments.
Biomass Power Equipment Market
Why this study matters for 2026 decisions
Investment windows that open in 2026 will be defined by three converging forces: sustained market expansion, policy-driven incentives, and tightening carbon economics. Our analysis shows the global biomass power equipment market expanded from approximately USD 89.5 billion in 2020 to about USD 125.5 billion in 2025, and is forecast to exceed USD 201.5 billion by 2032 — a compound annual growth rate of roughly 7% across the 2026–2032 forecast horizon. That trajectory translates into high-visibility opportunities for equipment suppliers, plant developers, and engineering partners, but it also intensifies competitive pressures and supply-chain risk for late movers.
Biomass Power Equipment Market
Report scope and actionable deliverables
-
Forward-looking market sizing: verified historical base (2020–2025), and detailed forecasts to 2032 — useful for financial planning and capital budgeting.
Biomass Power Equipment Market -
Technology and procurement playbooks: comparative assessment of combustion, gasification, and anaerobic digestion pathways with pragmatic procurement checklists and LCoE-sensitive decision trees tailored to common utility and industrial use cases.
-
CapEx/Opex benchmarks and component cost indices: vendor-neutral tables and sensitivity matrices for boilers, turbines, flue-gas cleaning, and common balance-of-plant items that underpin credible project bids.
-
Supply chain and localization roadmap: supplier tier-mapping, critical-component lead-time scenarios, and contract structuring options to reduce schedule and price exposure.
-
Regulatory and carbon scenario planning: three stress-tested policy scenarios (accelerated decarbonization, status quo, and protectionist retrenchment) with implications for subsidy capture, eligibility, and carbon risk hedging.
-
Competitive intelligence and vendor scorecards: qualitative strengths, recent program wins, and execution risk profiles for the major equipment providers and regional challengers.
Market dynamics shaping supplier and investor choices
Several dynamics will determine winners and losers in 2026 and beyond:
-
Policy acceleration: Renewable energy mandates and investment tax credits materially alter project IRRs. For example, recent policy frameworks in major markets have increased subsidy availability and investment certainty for qualified biomass projects — altering financing structures and shortening payback periods for first-movers who can validate eligibility early in project development.
-
Carbon pricing squeeze: Elevated carbon allowance prices in mature emissions trading systems are already making biomass-fired generation relatively more attractive than fossil baseload in dispatch economics. Developers and OEMs should model carbon scenarios into long-lead procurement decisions to avoid stranded-asset risk.
-
Feedstock and logistics volatility: Feedstock costs and availability — from wood pellets to agricultural residues — remain the single largest operational unknown for many projects. Price spikes and logistical bottlenecks can erode margins quickly; our recommended mitigation tactics include diversified feedstock contracts and staged fuel sourcing strategies linked to indexed pricing.
-
Component and EPC cost pressure: Mechanical systems such as grate stoker assemblies and fluidized bed components carry concentrated cost exposure. Established cost bands for such components mean procurement timing and bundle strategies (equipment + installation) materially affect total installed cost.
-
Project execution complexity: Integration of flue gas cleaning, ash handling and CHP interfaces remains a proven source of schedule slippage. Vendors with turnkey delivery experience command a premium; however, modularization approaches and standardized plant packages are emerging as viable de-risking mechanisms for repeatable deployments.
Competitive landscape — what to watch in 2026
The market exhibits clear leadership in large-scale, turnkey solutions while also hosting regional specialists that capture niche demand. PW Consulting’s vendor analysis highlights several archetypes:
-
Global turnkey integrators: Established European and Japanese OEMs continue to win large-scale CHP and utility projects by offering end-to-end solutions — boilers, steam turbines, and emissions controls — bundled with project execution capability. These firms benefit from deep engineering benches and an installed-base advantage.
-
Specialist component suppliers: Firms with focused product portfolios (e.g., gasifiers, grate technology) can be attractive partners in hybrid contracting models where IP and manufacturing cost control are prioritized.
-
Regional system builders: Local manufacturers and operators that can tailor designs to feedstock realities and regulatory requirements provide a nimble alternative to larger OEMs, particularly in small- to mid-scale projects.
Recent vendor developments emphasize execution readiness: notable 2024–2025 milestones include new plant commissions, secured orders for medium-scale projects, and efficiency breakthroughs that directly influence project economics. These operational signals should form a critical input to supplier selection and commercial negotiations in 2026.
Strategic implications and recommended actions for C-suite and project teams
For executives making capital and procurement decisions in 2026, the study suggests a five-point strategic playbook:
-
Lock-in policy and subsidy eligibility early: Engage with legal and policy advisors during FEED to secure tax credits or renewable premium access; assumptions about subsidy capture should be conservative in base-case financial models.
-
Prioritize vendor execution track records over headline efficiency claims: Efficiency gains are valuable, but schedule and commissioning risk more often determine NPV outcomes for first-of-a-kind projects.
-
Adopt staged capital deployment: Use modular plant designs and phased capacity increases to align capital expenditure with confirmed offtake and feedstock contracts, reducing exposure to volatile input prices.
-
Diversify feedstock contracts and incorporate indexed pricing: Negotiate contracts that permit fuel-switching or co-firing and include price collars or stepped escalators tied to transparent indices.
-
Build carbon-market hedges into commercial bids: Where applicable, price carbon allowance exposure into offtake contracts or secure forward emissions allowances to stabilize dispatch economics.
How PW Consulting’s report adds unique decision advantage
Beyond headline forecasts, the report combines proprietary cost-benchmarks, vendor execution scoring, and scenario-based financial models to convert market signals into executable strategies. Practically, this means:
-
Procurement teams receive a prioritized vendor shortlist and negotiation playbook tailored to plant scale and feedstock mix.
-
Investment committees get stress-tested project cash flows under multiple policy and fuel-price scenarios to inform approval thresholds and financing structures.
-
Business development teams obtain go-to-market blueprints, including high-probability corridors for retrofit and greenfield opportunities over the next 18–30 months.
Where this leaves decision-makers entering 2026
Market momentum is unmistakable: growth since 2020 has been strong and structural drivers indicate sustained demand through 2032. But the path to value is selective. The most compelling opportunities favor organizations that combine early policy-compliance verification, disciplined feedstock strategies, and procurement models that prioritize execution resilience. For OEMs and EPCs, differentiating through proven modular solutions and guaranteed commissioning timelines will be decisive.
We designed this briefing to be a strategic preview — it demonstrates the depth of analysis you should expect, while reserving the granular regional, technology and feedstock splits that underpin procurement and M&A decisions for the full report. That detailed segmentation, our proprietary vendor scorecards, and the complete set of financial model assumptions are available in the full PW Consulting Biomass Power Equipment Market report and its interactive data annex.
Next steps
-
Request the full report to access the granular breakdowns and interactive scenario models required for bid preparation, CAPEX approval, or strategic partnerships.
-
Engage our advisory team for a tailored workshop: we translate report findings into a 90-day action plan for procurement, contracting and capital allocation aligned to your risk tolerance.
PW Consulting’s analysis equips leaders with the market context and practical tools needed to make high-confidence biomass equipment decisions in 2026. For executives preparing bids, arranging financing, or evaluating vendor partnerships, timely access to the full data set and our consulting support will be the difference between seizing advantage and reacting to it.
For detailed analysis of this topic, please visit the official page: Biomass Power Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com