

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Forecast: Fused Silica Tubing Market to Expand at a 6.12% CAGR — Strong Growth Ahead
By pmarketresearch, 2026-07-01
Fused Silica Tubing Market: Strategic Imperatives for 2026 — Insights from PW Consulting’s Latest Report
PW Consulting today releases a strategic briefing drawn from our comprehensive Fused Silica Tubing Market study (base year 2025, forecast period 2026–2032). This market — valued at USD 845.0 Million in 2025 — is positioned for steady expansion, tracking to approximately USD 1.28 Billion by 2032 at a compound annual growth rate (CAGR) of 6.12%. For corporate leaders, investors and supply-chain executives, the report crystallizes the commercial and operational choices that will determine winners and laggards across the next strategic planning cycle.
Fused Silica Tubing Market
Why this study matters for 2026 decision-makers
-
Clarity for capital allocation: Our scenario-aligned financial model translates market growth trajectories into required capex, timing imperatives and break-even horizons for capacity additions or brownfield upgrades.
Fused Silica Tubing Market -
Sourcing and risk mitigation: The report maps feedstock and processing chokepoints — enabling procurement teams to quantify exposure and design multi-tier sourcing strategies before shortages or price shocks materialize.
Fused Silica Tubing Market -
Product and route-to-market strategy: We translate application-level demand dynamics into SKU rationalization and premium-product roadmaps that help R&D and commercial teams prioritize high-margin niches.
-
M&A and partnership intelligence: The study’s competitive lens surfaces realistic bolt-on and JV targets, supported by seller scorecards and synergistic value estimates.
What the report contains (practical, decision-ready modules)
-
Robust market sizing and forecasting engine — bottom-up revenues for the global market, base-year reconciliation and multiple forecast scenarios reflecting moderate, upside and downside demand environments.
-
Demand-driver deep dives — detailed demand drivers across key end markets, adoption curves for higher-purity and larger-diameter tubing, and product-fit matrices tied to customer pain points.
-
Supply-side intelligence — plant-level capacity mapping, manufacturing route comparisons (plasma fusion, flame hydrolysis, synthetic routes), and a dynamic cost curve model showing where margin pressure will migrate under different feedstock and energy cost assumptions.
-
Feedstock and upstream risk assessment — concentrated sources of high-purity quartz, regulatory exposures in extraction regions, and geopolitical scenarios including tariff and trade friction outcomes that materially affect feedstock flows.
-
Competitive benchmarking and supplier scorecards — comparative capabilities (diameter range, purity, coatings, tolerances), practical supplier selection frameworks, and a consolidation outlook informed by market concentration metrics.
-
Commercial playbooks — tailored go-to-market strategies for global leaders, regional specialists and niche micro-tubing players (analytical and microfluidic segments), including pricing levers and channel tactics.
-
Investment decision matrices — capital versus outsourcing trade-offs, greenfield vs. brownfield scenarios, payback sensitivity tables, and recommended decision thresholds for 2026 capex cycles.
-
Regulatory and sustainability roadmap — compliance checklists, lifecycle-impact levers, and stakeholder engagement templates for licensing and community relations in extraction-heavy geographies.
-
Executive dashboards and downloadable financial models — editable spreadsheets for tailored sensitivity analysis and board-ready slides summarizing strategic options.
Macro dynamics reshaping the landscape
-
End-market momentum is heterogeneous. Semiconductor wafer processing and advanced electronics continue to underpin premium demand for high-purity and large-diameter tubing, while other segments — such as fiber-optics and laboratory equipment — contribute steady, quality demand. The net effect is a resilient, mid-single-digit growth path for the aggregate market.
-
Feedstock remains the dominant supply-side variable. Ultra-high purity quartz feedstock is a scarce and geographically concentrated input. Environmental regulation, local mining constraints and evolving permitting regimes are tightening availability for the very highest purity grades, creating a structural premium for assured supply and traceability.
-
Policy and trade dynamics matter more than ever. Tariff negotiations and trade policy shifts in 2025 introduced measurable supply-chain friction. Procurement strategies that do not explicitly model tariff and logistics volatility will be disadvantaged when spot shortages or diversion of shipments occur.
-
Technology and product evolution are differentiators. Manufacturers that can offer lower-defect tubing, larger diameter ranges, improved UV and laser stability, or integrated coatings (for microfluidics and analytical applications) capture outsized margins versus commodity players.
Competitive landscape — who matters and what they mean for strategy
The market exhibits moderate-to-high concentration: the top three global players capture the majority share, with the top five materially increasing that share. This concentration creates both barriers and opportunities: incumbents enjoy scale and long-term customer relationships, while specialists and regional players win where customization, speed-to-supply and technical service are critical.
-
Global scale leaders: Established producers with vertically integrated operations and broad product portfolios are positioned to defend premium customers and invest behind capacity expansions and quality upgrades. Their strategic playbooks will focus on optimization of global supply footprints and customer lock-in via long-term contracts and tailored service agreements.
-
Technology and process specialists: Firms using unique fusion or plasma-based processes can address large-diameter and custom cylinder demands that are difficult for commodity manufacturers to meet. These players are attractive targets for strategic partnerships or OEM agreements where technical exclusivity is valuable.
-
Regional and niche suppliers: Companies focused on precision, microcapillary, or polyimide-coated tubing serve analytical and instrument OEMs where tight tolerances and rapid customization trump scale. They excel in specialist aftermarket and instrument-level integration sales.
-
Integrated Asian producers: Large integrated upstream-to-downstream manufacturers in Asia provide competitive cost structures and scale; their strategic moves — including capacity and vertical integration — should be watched closely by Western buyers planning supplier rationalization.
Our report includes concise profiles of the market’s core participants, evaluating manufacturing footprints, recent capital projects, IP strengths and customer focus areas. Notable developments we highlight include capacity expansions and catalog extensions that incrementally shift competitive dynamics and customer expectations — events that every strategic planner should model into 2026 procurement and sourcing strategies.
Practical strategic recommendations for 2026
-
Prioritize secured feedstock arrangements. Buyers should negotiate multi-year agreements with tiered volume and quality clauses, and evaluate strategic investments or JV arrangements that provide preferential access to ultra-high purity feedstock.
-
Segment product portfolios by margin and complexity. Reallocate R&D and sales resources to higher-margin, lower-commodity-risk product lines and consolidate low-margin SKUs to improve utilization rates.
-
Invest in flexible manufacturing. Modular capacity and process versatility (ability to switch between diameters and purity classes) will mitigate demand volatility and reduce time-to-market for premium products.
-
Design for supply-chain resilience. Implement dual-sourcing for critical inputs, stress-test logistics under tariff and port-congestion scenarios, and develop contingency inventories for high-risk nodes.
-
Explore vertical or near-vertical plays. For producers, selective upstream integration or long-term supply partnerships can protect margins; for buyers, co-investment can secure priority allocation in constrained environments.
The PW Consulting advantage — what differentiates our analysis
Our study blends factory-level production economics, feedstock traceability mapping and customer-level demand projections. We operationalize insights into prioritized actions — not just charts. The report supplies an editable financial model, supplier scorecards and decision matrices that CFOs and business-unit leaders can use directly for board-level investment choices.
Trailer principle — what we intentionally withhold (and why)
In keeping with the “trailer” objective of this release, we present the strategic context, high-level market trajectory and executable recommendations while withholding certain segment-level revenue splits and granular pricing matrices that materially affect competitive positioning. These proprietary datasets — including detailed regional/application breakdowns and price-sensitivity curves — are available in the full report and the accompanying workbook. This approach preserves the commercial value of the primary data while giving executives the analytical framework needed to prioritize next steps immediately.
Next steps — how to use the report in your 2026 planning cycle
-
Board briefings: Use our executive summary and dashboard to frame capital-allocation debates and set risk tolerances for feedstock exposure.
-
Sourcing strategy updates: Integrate the supplier scorecards and scenario outputs into procurement RFPs and supplier audits.
-
M&A screening: Apply the acquisition filters and synergy calculators to shortlist targets that accelerate technical capability or market access.
To access the full dataset, proprietary segment-level models and the downloadable Excel workbook that powers our recommendations, please visit the PW Consulting website and request the Fused Silica Tubing Market report. For bespoke advisory engagements, our strategy team is available to run the report’s models with your internal data and produce an execution-ready roadmap tailored to your organization.
For detailed analysis of this topic, please visit the official page: Fused Silica Tubing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical-Grade Power Supplies Market at USD 1,450.0 Million (Base Year 2025), Forecast to Reach USD 2,151.6 Million by 2032 at 5.8% CAGR — North America Leads with USD 657.8M; Enclosed Supplies, Diagnostic Equipment Dominate (CR3 34.5%)
By pmarketresearch, 2026-07-01
Medical Grade Power Supplies Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting’s latest market intelligence on Medical Grade Power Supplies delivers a forward-looking playbook for C-suite executives, product leaders, and investors preparing for 2026. Built on a rigorous historical base (2020–2025) with 2025 as the base year, the study projects the market across a 2026–2032 forecast horizon. At the macro level, the market expanded from an estimated USD 1,094.34 Million in 2020 to USD 1,450.00 Million in 2025 and is modeled to reach USD 2,151.63 Million by 2032, reflecting a compound annual growth rate (CAGR) of 5.8% over the forecast period. This preview outlines the strategic value of the full report, highlights the competitive moves reshaping supplier dynamics, and sets out immediate decision levers for stakeholders entering 2026.
Medical Grade Power Supplies Market
Why this market matters in 2026
-
Convergence of demand and regulation: Device electrification trends across diagnostic, monitoring, therapeutic, and home-care segments are coinciding with tighter regulatory and EMC requirements. Recent standards updates require manufacturers and their power-supply partners to accelerate compliance investments and embed risk management and cybersecurity into product lifecycles.
Medical Grade Power Supplies Market -
Capital discipline and premiumization: As medical OEMs pursue higher-reliability, patient-proximal power architectures, willingness to pay for certified, low-leakage, and compact solutions is rising—shifting purchasing from lowest-cost sourcing to value-driven procurement.
Medical Grade Power Supplies Market -
Supply-side fragility: Material cost and availability pressures—exemplified by higher costs for high-purity transformer copper—are compressing supplier margins and increasing the value of near-term procurement strategies that prioritize continuity and design-to-cost expertise.
Top-line takeaways for 2026 strategy
-
Prioritize certification as product differentiation. Compliance to the latest medical safety and EMC standards (including updated IEC 60601-series editions and cybersecurity expectations) is a gating factor for market access and a durable competitive moat.
-
Rebalance procurement KPIs. Procurement teams should expand evaluation criteria beyond price and delivery to include isolation levels, leakage current guarantees, EMC performance, and documented cybersecurity controls—particularly for patient-contact and home-health applications.
-
De-risk supply chains. Manufacturers should secure dual sources for critical passive components, qualify alternate transformer suppliers, and negotiate price-escape mechanisms—actions that will materially reduce interruption risk in 2026.
-
Monetize services. Aftermarket calibration, extended warranties, and field-repair networks are underleveraged revenue streams for power-supply providers that can offer traceability and rapid field response.
What the full report delivers (practical, executable content)
-
Transparent market sizing and a reproducible forecasting model: The report documents our assumptions and sensitivity analyses underpinning the projection to USD 2,151.63 Million by 2032, enabling CFOs to test alternative scenarios against procurement or R&D budgets.
-
Regulatory and standards playbook: A decision-ready matrix that translates IEC 60601-series and related standards into product design requirements, test protocols, and procurement clauses.
-
Cost and margin mapping: Component cost drivers, bill-of-material pressure points (including the 2024 copper-foil episode), and margin levers for suppliers and OEMs.
-
Channel and contract strategies: Go-to-market options for OEMs, EMS providers, and component distributors—ranging from long-term strategic agreements to design-win templates for configurable platforms.
-
Competitive benchmarking and M&A screening criteria: A proprietary framework for evaluating targets and partners against technical certifications, capacity, geographic footprint, and after-sales capability.
Competitive landscape: who is moving and why it matters
The market concentration indicates that the top three players account for a meaningful share of the market (CR3 ~34.5%) and the top five reach close to half the market (CR5 ~46.2%). These concentration dynamics create a balance between scale-driven reliability and niche innovation—presenting distinct strategic choices for challengers and incumbents alike.
-
Advanced Energy Industries (Fort Collins, CO) — Strong in medical AC-DC and DC-DC platforms certified to medical safety editions for imaging, surgical, and monitoring equipment. Their emphasis on higher-power, parallel-capable modules signals a push into system-level power architecture for dental and imaging suites.
-
Artesyn Embedded Power (Advanced Energy) (Alpharetta, GA) — Offers series optimized for MRI, therapy, and dental systems with advanced-edition certification focus. Their portfolio strategy demonstrates demand for configurable, high-reliability modules.
-
XP Power (London, UK) — A notable supplier of internal and external medical supplies with certifications aligned to patient-proximal and home-health devices. Recent product introductions underscore their intent to capture higher-wattage imaging segments.
-
MEAN WELL (New Taipei City, Taiwan) — A leader in BF-class insulation and a broad range of medical offerings; certification updates for higher-power surgical applications illustrate the move to hospital-proximate systems.
-
TDK-Lambda (Tokyo, Japan) — Known for AC-DC medical series with strong EMC performance; their emphasis on 2xMOPP isolation and higher-density modules mirrors demand in diagnostic equipment.
-
Cosel (Tokyo, Japan) — Offers compact DIN-rail and chassis-mount medical approvals; relevant for OEMs with space-constrained monitoring and point-of-care solutions.
-
Delta Electronics (Taipei, Taiwan) — Broad portfolio for hospital infrastructure and surgical tools; their scale enables deep integration with hospital-grade equipment manufacturers.
-
SL Power Electronics (Advanced Energy) (Ventura, CA) — Specializes in external medical supplies with ultra-low leakage offerings targeting patient-contact use-cases.
Recent commercial activity reinforces these strategic moves: product launches and certification upgrades throughout 2025 and into late 2025 show suppliers racing to meet higher power-density and stricter EMC/isolation expectations. Examples include 4th-edition IEC-certified open-frame modules for imaging, new high-density AC-DC 2xMOPP units, and certification refreshes for surgical-robot power platforms. For procurement leaders, these signals indicate a window to renegotiate specifications towards higher value, certifiable solutions.
Regulatory and operational headwinds to plan for in 2026
-
Standards compliance is non-negotiable: IEC 60601-series updates (including the 3.2 edition and the 60601-1-2:2024 EMC requirements) plus risk management (ISO 14971) and device cybersecurity norms (IEC 81001-5-1) must be embedded early in product development.
-
Component volatility: Raw-material price moves and constrained supply for specialty passive components can drive sudden cost inflation; forward-buying and alternative-material strategies are essential.
-
Reimbursement nuance: Reimbursement codes for power-supply-inclusive devices (e.g., certain home-health equipment) can influence adoption economics for end-users and, by extension, OEM design priorities.
-
Quality and recall risk: Recent recalls underscore the reputational and financial impact of component failures—strengthening quality assurance and supplier audits must be prioritized.
Scenario planning and 2026 playbook
-
For OEMs: Adopt a two-track sourcing model—secure long-term agreements for certified, mission-critical modules while using configurable, lower-cost platforms for non-patient-proximal subsystems.
-
For Suppliers: Differentiate through certification, rapid lead-times for design wins, and bundled services (field calibration, extended warranties). Invest selectively in high-density, low-leakage architectures where margin expansion is feasible.
-
For Investors: Target assets with validated certifications, redundant supply arrangements, and serviceable aftermarket footprints. Apply diligence to EMC performance data and the robustness of compliance documentation.
-
For Regulators & Buyers: Define procurement clauses that require traceable compliance evidence, cybersecurity attestations, and acceptance testing aligned to the latest standards.
Methodology and data confidence
This study synthesizes primary interviews with OEMs, component suppliers, and industry experts; company disclosures; standards texts; and proprietary market modeling. The historical series covers 2020–2025 with 2025 as the base year; the forecast period spans 2026–2032. All monetary values are expressed in USD Million. The report includes sensitivity testing and scenario runs that allow readers to stress-test growth under alternative cost and demand assumptions.
Next steps: how to use the full report
This preview is designed as a strategic briefing. The full PW Consulting Medical Grade Power Supplies Market Report contains the detailed spreadsheets, supplier scorecards, and granular scenario outputs that procurement, R&D, and M&A teams will need to execute on the 2026 agenda. To preserve competitive value and ensure actionable monetization for subscribers, the report intentionally withholds certain segment-level tables and exact regional splits in this public summary.
Access the complete report and obtain customized briefings, model walkthroughs, and vendor templates by visiting our report landing page. PW Consulting will also be hosting a webinar in early 2026 to walk through the model assumptions and to deliver a live Q&A on market-entry strategies.
For executives planning capital allocation, product roadmaps, or M&A workstreams in 2026, this research converts market momentum and regulatory signals into a decision-grade framework—enabling faster, more confident choices where compliance, continuity, and clinical safety determine winning outcomes.
For detailed analysis of this topic, please visit the official page: Medical Grade Power Supplies Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Targeted Drugs for Multiple Myeloma Market to Surge from USD 25.85B in 2025 to USD 40.04B by 2032 at a 6.45% CAGR
By pmarketresearch, 2026-07-01
Targeted Drugs for Multiple Myeloma: Strategic Imperatives for 2026 — PW Consulting Market Insight
PW Consulting's latest market research, Targeted Drugs For Multiple Myeloma Market (base year 2025; forecast 2026–2032), translates a complex and fast-moving therapeutic landscape into decision-grade intelligence for executives, investors, and policy makers. The report synthesizes market modeling with regulatory inflection points, payer dynamics, and competitive playbooks to support high-consequence choices in 2026.
Targeted Drugs For Multiple Myeloma Market
Executive snapshot: why 2026 is an operating inflection
Our model projects the global targeted multiple myeloma market to continue its steady expansion beyond the 2025 base, tracking a compound annual growth rate (CAGR) of approximately 6.45% across the 2026–2032 forecast window. This growth trajectory is driven by a convergence of therapeutic innovation (bispecific antibodies, next-generation CELMoDs, optimized proteasome inhibitors, ADCs and CAR‑T), evolving regulatory acceptance of surrogate endpoints, and commercial strategies that emphasize combination regimens and earlier-line adoption.
Targeted Drugs For Multiple Myeloma Market
Concentration in the market remains meaningful: the top three companies collectively command a majority share, with the five largest firms controlling well over two-thirds of industry revenues. That structure creates both barriers and windows for entrants — scale matters for manufacturing, distribution and payer negotiations, yet differentiated clinical profiles and novel mechanisms can rapidly shift prescriber preference and formulary position.
Targeted Drugs For Multiple Myeloma Market
What this report delivers — practical chapters for 2026 decision-making
- Actionable market model: A transparent, auditable revenue model with scenario levers for uptake curves, line-of-therapy penetration, and pricing assumptions covering 2026–2032. The model is designed for rapid customization to reflect corporate-specific assets and regional go‑to‑market strategies.
- Regulatory and reimbursement playbook: Detailed implications of recent FDA guidance treating MRD negativity and complete response as potential primary endpoints, updated accelerated-approval pathways, and evolving HTA expectations in major markets.
- Competitive deep dives: Strategic profiles of incumbent and emerging companies — clinical positioning, commercial readiness, manufacturing capacity, and partnership maps — linked to our scenario-based share forecasts.
- Go-to-market sequencing & launch risk matrix: Prescriptive sequencing options (e.g., combination vs monotherapy launch, inpatient vs outpatient channels), required evidence generation, and payer negotiation tactics.
- Portfolio & M&A decision support: Valuation drivers and sensitivity analyses for bolt-on acquisitions, licensing deals, and clinical program prioritization in the context of patent cliffs and generic pressures.
- Real-world evidence (RWE) and safety monitoring roadmaps: Practical templates showing how to translate post‑launch RWE into label expansions, REMS removal petitions, and payer coverage policies.
Competitive landscape — strategic implications for market participants
The rapid cadence of approvals and pivotal data readouts through 2025–2026 has reconfigured therapeutic choices and created tactical priorities for industry participants.
- Large integrated pharmaceutical firms: Companies with broad oncology portfolios and advanced biologics platforms have leveraged diversified mechanisms (anti‑CD38 antibodies, bispecifics, CAR‑T) to defend and expand franchise value. Recent approvals and label expansions for combination regimens strengthen incumbents’ bargaining positions with payers, but they must continuously demonstrate cost-effectiveness and long-term benefit versus emerging oral agents and off-the-shelf bispecifics.
- Biotech innovators and specialty players: Firms advancing bispecific antibodies, CELMoDs, ADCs and nuclear-export inhibitors can disrupt line-of-therapy sequencing with compelling efficacy or convenience. Success will depend on clinical differentiation, manufacturing scale, and smart partnering that aligns regulatory pathways with reimbursement strategies.
- CAR‑T sponsors and cell-therapy platforms: Operational excellence (manufacturing yield, vein-to-vein time, and hospital network coverage) remains critical. Regulatory moves that streamline monitoring and REMS for certain CAR‑T constructs materially lower commercialization friction and broaden addressable populations.
Selected recent developments illustrate the speed and direction of change. In early 2026, approvals enabling combination uses of bispecifics with established monoclonal antibodies have accelerated adoption in relapsed and earlier lines. Positive Phase 3 data for next‑generation oral agents create competitive pressure on older backbone therapies, while regulatory acceptance of MRD as an endpoint is shortening evidence timelines for accelerated approvals. Concurrently, generic entry for legacy agents changed economics for long-term maintenance strategies in 2026 — a structural consideration for pricing and contracting.
Regulatory and payer dynamics: new rules, new playbooks
Two regulatory themes dominate near-term strategy: (1) increased regulatory acceptance of surrogate endpoints such as MRD negativity for accelerated approvals, and (2) selective de‑risking of cell therapy post‑market requirements informed by real-world evidence. These developments compress time-to-market for differentiated assets but escalate the importance of robust, early post-approval data collection plans.
From a payer perspective, the shift is toward outcome-based contracting and indication-based pricing for high-cost therapies. Integration of MRD into coverage criteria creates an opportunity for companies to design diagnostics-linked reimbursement strategies but also raises the bar for demonstrating durable benefit. Our report includes templates for payer dossiers and contract structures that reflect current HTA expectations across major markets.
Practical recommendations for 2026 boardrooms
- For incumbent biologics owners: Prioritize real-world evidence programs that demonstrate additive value of combination regimens; accelerate manufacturing investments to secure supply for earlier-line indications.
- For small and mid‑cap innovators: Focus on niche differentiation (e.g., safety profile, outpatient administration) and structure early partnerships to de‑risk scale-up and payer access.
- For investors and M&A teams: Recalibrate valuations to reflect the interplay of patent expiry on older agents, the probability-weighted revenue contribution of bispecifics and CAR‑T, and the speed at which MRD acceptance can convert accelerated approvals into commercial revenues.
- For hospital systems and providers: Implement capacity planning aligned to anticipated shifts from inpatient to outpatient delivery for select cell and bispecific therapies; leverage RWE to support expanded site-of-care adoption.
How to use this research in 2026 strategic planning
Executives should treat this report as both a diagnostic and an operational playbook. Key use cases include:
- Board-level briefing materials that translate forecast scenarios into revenue, margin and P&L sensitivities;
- Commercial launch plans that prioritize indication sequencing and payer engagement based on modeled uptake and pricing scenarios;
- Due-diligence scaffolds for licensing or acquisition that align clinical readouts with manufacturing and reimbursement risk;
- RWE and post‑market study blueprints to support label expansion, REMS removal, and durable coverage agreements.
Why PW Consulting’s approach is different
We combine a transparent financial model with on-the-ground regulatory tracking, MSL and payer interviews, and manufacturing capacity checks to produce forecasts that are not just plausible, but operationally executable. Our deliverables include an editable model, a prioritized list of clinical evidence gaps tied to commercial milestones, and a market-access playbook that maps negotiation points to contract structures and evidence generation timelines.
Next steps & how to access the full intelligence
This article intentionally highlights strategic conclusions and programmatic implications while withholding proprietary segmentation tables and granular revenue splits that underpin our scenario outputs. Those detailed slices — central to commercial planning and investment underwriting — are available in the full Targeted Drugs For Multiple Myeloma Market report and accompanying model.
Contact PW Consulting to request an executive briefing, obtain the full dataset, or commission a bespoke variant of the model tuned to an asset, portfolio or geographic footprint. In a market where regulatory shifts, therapeutic innovation and payer expectations are simultaneously accelerating, timely, nuanced intelligence will be the difference between market share retention and strategic obsolescence in 2026.
For detailed analysis of this topic, please visit the official page: Targeted Drugs For Multiple Myeloma Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: General Bio‑Based Polyamide Market Poised for Breakout, Growing at 15.02% CAGR Through 2032
By pmarketresearch, 2026-07-01
General Bio-Based Polyamide Market: Strategic Intelligence for 2026 Decision-Making
PW Consulting today releases a forward-looking briefing derived from our full market research report on the General Bio-Based Polyamide Market. The briefing synthesizes why 2026 will be a pivotal year for procurement, product development, and capital allocation decisions across automotive, textiles, consumer goods, electronics, and industrial manufacturing. It highlights the macro trajectory—built on our modeled market build from historical data (2020–2025) into a 2026–2032 forecast—and explains the practical, decision-ready content executives will find in the complete report.
General Bio Based Polyamide Market
Why 2026 Is a Strategic Inflection Point
Our modeling shows the global bio-based polyamide market expanding rapidly from its 2025 base to a materially larger market by the end of the 2026–2032 forecast window. The forecast period delivers a compound annual growth rate of 15.02%, driven by accelerating adoption in technical applications, regulatory incentives in key jurisdictions, and tangible downstream decarbonization commitments. By anchoring on the 2025 baseline and stress-testing plausible 2026 business scenarios, the full study equips leaders to prioritize investments, hedge supply-chain risk, and capture share in fast-moving adjacencies.
General Bio Based Polyamide Market
What Senior Executives Need to Know—At a Glance
- Market momentum: The market has grown consistently through the 2020–2025 period and enters 2026 with strong demand signals across multiple end-use sectors.
- Acceleration factors: Regulatory pressure (notably in European markets), corporate net-zero commitments, and product performance parity in many applications are accelerating commercial uptake.
- Concentration and competition: The market exhibits a moderate degree of supplier concentration—enough to reward strategic partnerships but still leave space for innovative entrants and niche specialists.
- Raw material dynamics: Renewable feedstocks—particularly castor oil derivatives—remain central to cost and availability dynamics, with feedstock supply volatility capable of producing short-term price spikes that affect feedstock-linked intermediates.
Market Dynamics and Near-Term Risks
Two structural dynamics will shape board-level choices in 2026. First, regulatory frameworks and procurement policies are rapidly moving from aspirational language to concrete procurement incentives and technical acceptance criteria. For companies operating in jurisdictions aligning incentives with circularity and carbon intensity reduction, bio-based polyamides are becoming a default option for new programs in automotive, consumer electronics, and select industrial applications.
General Bio Based Polyamide Market
Second, feedstock and intermediate-price volatility remains a tactical risk. Castor-derived intermediates and downstream sebacic acid have exhibited significant month-to-month price fluctuations in recent historical windows—an operational challenge for midstream processors and converters. Firms that align procurement strategies with forward contracting, offtake arrangements, and alternative feedstock options will have a measurable cost-of-goods advantage in 2026.
Competitive Landscape—Where Leaders Are Placing Bets
The competitive map is composed of legacy chemical majors and specialist bio-based players. Several strategic moves in 2024–2026 illustrate how incumbents are scaling and differentiating:
- Arkema has pursued integration and transparent-grade capacity expansion, bringing into production a high-transparency bio-based polyamide unit in Singapore that substantially scales supply for high-value niches such as medical devices and eyewear. Arkema’s carbon-footprint improvements—validated to a low-kilogram CO2e per kilogram production figure—signal how renewable electricity and process efficiency can create a class-leading sustainability claim.
- Evonik continues to position high-performance partially bio-based grades and powders for technical applications and additive manufacturing, targeting engineering customers that require predictable material properties and supply security.
- DSM-Firmenich (Envalior) and RadiciGroup have concentrated on automotive-grade polymers with demonstrated in-service performance, while Asian innovators such as Cathay Biotech are introducing novel monomer pathways (e.g., cadaverine-derived chemistries) that broaden feedstock optionality and fiber applications.
- Mass-balance and bio-attributed strategies are being adopted by producers such as DOMO and BASF, with ISCC-certified offerings enabling customers to credibly claim reduced lifecycle impacts without immediate upstream overhaul.
- Smaller specialists and technology developers—Toray, Mitsubishi Gas Chemical, and Avient among them—are targeting biodegradation, specialty cosmetic applications, and formulation-led replacement opportunities.
These moves together create a layered competitive field in which scale, certification, feedstock integration, and targeted application expertise determine which firms capture growth pockets. The market concentration metrics in our study confirm that a handful of suppliers command meaningful share, but there is clear room for differentiated entrants and regional champions.
Practical Capabilities in the Full Report (What We Don’t Publish Here)
Following the “trailer” principle, we present the strategic architecture of the full report without disclosing sensitive segment tables and supplier-level volumes. The comprehensive study, however, contains a suite of practical tools designed for immediate application in 2026 planning cycles:
- Scenario-driven demand model: A dynamic model that supports “what-if” runs for regulatory shifts, feedstock shocks, and premium adoption curves, calibrated to historical 2020–2025 data and our 2026–2032 forecast.
- Supply-risk heatmap: Granular assessment of feedstock risk, supplier concentration at sub-regional level, and contingency options that materially affect sourcing strategies and working-capital planning.
- Commercial playbooks: Tailored approaches for OEMs, converters, and polymer producers that translate sustainability claims into product specifications, cost-impact pathways, and phased adoption milestones.
- Capex and plant-siting decision frameworks: Investment appraisal templates that quantify payback under different incentive regimes and access to renewable power or integrated feedstock sources.
- Procurement and contracting templates: Best-practice terms for long-term offtake, indexation clauses for feedstock volatility, and certification verification workflows.
Strategic Recommendations for 2026 Planning
- Prioritize hybrid sourcing strategies: Combine contracted offtake from integrated suppliers with spot access to alternative feedstock-based grades to mediate price spikes and secure innovation premiums.
- Lock in sustainability credentials early: Work with ISCC and bio-attribution providers to set up traceable claims; mass-balanced offerings can bridge near-term carbon goals while dedicated bio-feedstock volumes scale.
- Target application-first substitution: Identify high-value, low-volume applications (connectors, tubing, selective consumer goods) where bio-based grades already match performance and command higher margin capture.
- Invest in co-development with material providers: Co-funded trials, joint validation, and shared technical roadmaps reduce time-to-adoption and align material roadmaps with OEM qualification cycles.
- Stress-test supply chains for feedstock shocks: Build buffers, diversify suppliers geographically, and model financial contingencies for the type of midstream price volatility observed historically.
Risk-Reward and the Executive Checklist
The risk-reward trade-off in 2026 favors organizations that take an active, structured approach to adoption. Risks include feedstock price volatility, qualification timelines for critical applications, and potential policy reversals or uneven regulatory alignment between markets. Rewards include accelerated compliance with decarbonization goals, access to premium product positioning, and first-mover advantage in emerging application clusters.
Executives evaluating engagement should consider this short checklist:
- Have you validated total-cost-of-ownership for bio-based alternatives at the product level, not just resin price?
- Do your suppliers have credible certification and transparent chain-of-custody mechanisms?
- Can your R&D and procurement functions run concurrent qualification and contractual negotiation tracks?
- Are capital and supply contingencies in place to manage feedstock-driven mid-cycle price shocks?
What the Full PW Consulting Report Delivers
The complete General Bio-Based Polyamide Market report is designed as an operational toolkit for 2026 boardrooms and commercial teams. It combines our proprietary demand-supply modeling, supplier benchmarking, certification and policy analysis, and executable playbooks into a single deliverable that supports strategy, procurement, and engineering stakeholders. The report also documents recent industry developments and supplier moves that matter for 2026 sourcing decisions—capacity ramp-ups, ISCC and low-carbon product launches, and measured carbon-footprint disclosures that materially affect procurement criteria.
Next Steps
PW Consulting invites corporate leaders, investors, and procurement teams to review the executive summary and access the full dataset and models via the report landing page. The full report includes source-level data, scenario models, and an annex of supplier profiles and validated performance claims that are essential for executable 2026 plans.
For teams seeking immediate support, PW Consulting offers bespoke briefings and rapid-turn validation workshops to align technical, commercial, and procurement stakeholders around a pragmatic adoption roadmap.
For detailed analysis of this topic, please visit the official page: General Bio Based Polyamide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Emergency Rescue Drone Market to Soar at a 12.45% CAGR Through 2032
By pmarketresearch, 2026-07-01
Emergency Rescue Drone Market 2026: Strategic Imperatives for Corporate Decision‑Makers
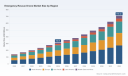
PW Consulting’s latest market research — Emergency Rescue Drone Market: 2026 Strategic Brief — synthesizes seven years of market evolution and a detailed seven‑year forecast to deliver a compact, decision‑grade intelligence package for executives planning 2026 investments. Built on historical observations (2020–2025) and a forecast horizon through 2032, the analysis identifies the structural forces reshaping emergency response capabilities and quantifies the market’s acceleration: a compound annual growth rate (CAGR) of 12.45%, with total market value moving from roughly USD 142 million in 2020 to USD 312.5 million in 2025 and projected to exceed USD 700 million by 2032. This release summarizes the strategic takeaway for corporates while intentionally reserving granular segmentation and vendor matrices for the full report.
Emergency Rescue Drone Market
Why this brief matters for 2026 planning
Emergency rescue drones have moved beyond proof‑of‑concept deployments into mission‑critical roles across public safety, disaster response, and medical logistics. For 2026 planning cycles, buyers, OEMs, integrators, and investors need a tightly focused understanding of three things:
Emergency Rescue Drone Market
- How regulatory and procurement realities (e.g., supply‑chain compliance and DFR program approvals) will gate adoption timelines;
- Which technology choices materially change total cost of ownership and operational effectiveness (autonomy, thermal and sensor stacks, VTOL vs. multirotor tradeoffs); and
- Where consolidation and competitive concentration create acquisition or partnership opportunities.
This brief translates those questions into board‑level recommendations and executable next steps — without disclosing the full granular charts and segmented revenue tables that appear in the full dossier.
Emergency Rescue Drone Market
Key market dynamics shaping 2026 decisions
Regulatory and procurement environment: Two regulatory signals are decisive. First, mandatory supply‑chain compliance for many government and public safety adopters — notably NDAA compliance — is now a prerequisite for meaningful contract eligibility. Second, aviation authorities have accelerated administrative pathways for Drone as First Responder (DFR) programs, reducing time‑to‑operational‑status when agencies use prepositioned systems. For purchasing officers and program managers, this means supplier selection must balance technical capability with verifiable compliance credentials and program‑specific approvals.
Technology and operational drivers: Advancements in onboard autonomy, high‑resolution thermal imaging, encrypted real‑time telemetry, and hybrid VTOL endurance are combining to change operational doctrines. Autonomous pathing, robust obstacle avoidance, and machine‑assisted search patterns materially increase the value of a deployed drone beyond raw flight time. Equally important are sensor modularity and communications resilience: payload ecosystems and hardened data links determine whether a platform becomes an operational asset or a temporary experiment.
Supply chain and component constraints: As defense and government programs require NDAA‑compliant batteries and parts, sourcing strategies must adapt. Our analysis highlights the strategic tradeoffs in locking into compliant supply streams versus pursuing cost‑optimized components. For procurement teams, mapping supplier certification timelines against planned deployments is now mission critical.
Market structure and competitive dynamics: The sector is moving toward a moderately concentrated topology. The top three players account for a significant share of revenue, and the top five approach parity with a substantial portion of market value — a pattern that favors specialist incumbents with public‑safety pedigree and scaled manufacturing. This structure has implications for pricing power, aftermarket service economics, and M&A activity.
What’s in the full report (practical, operational content)
Our 150+ page report is intentionally designed for users who need to act in 2026. Key practical assets included are:
- Decision frameworks for procurement: vendor scorecards, NDAA compliance checklist, and contract templates tailored for public‑safety and municipal procurement cycles;
- Operational deployment playbooks: step‑by‑step DFR station planning, maintenance cadence, and crew training matrices that convert a pilot project into a 24/7 operational capability;
- Financial tools: TCO models, scenario‑based ROI calculators, and risk‑adjusted investment timelines aligned to the market CAGR and adoption curves;
- Technology assessment rubrics: standardized test procedures for autonomy, sensor fusion, and communications resilience (including evaluation criteria for thermal imaging, two‑way communications, and glass‑breach capabilities);
- Supply‑chain and compliance mapping: supplier due‑diligence templates and alternative sourcing strategies for NDAA‑sensitive components such as batteries;
- Scenario planning: three plausible adoption trajectories (base, accelerated, and constrained) with associated budgetary implications and suggested operating cadences for each scenario;
- Implementation roadmaps: 6–18 month and 18–36 month playbooks that identify fast wins and medium‑term investments for municipal agencies and private operators.
We intentionally withhold the detailed segmentation tables and regional/application breakouts in this press brief to protect the commercial sensitivity of that analysis. Those datasets and vendor scorecards are available in the full report.
Competitive landscape—who matters and why
Our analysis profiles a compact set of specialist and system providers whose technology portfolios and go‑to‑market motions will shape 2026 outcomes:
- BRINC Drones — a public‑safety specialist notable for purpose‑built systems including indoor/dense‑urban tactical solutions, two‑way communications, and field‑proven breaching capabilities. Recent developments: in March 2026 BRINC announced a significant production expansion and launched a next‑generation response drone aimed at 24/7 DFR operations.
- Skydio — leading in autonomy and robust obstacle avoidance for complex environments; its AI‑driven platforms are increasingly deployed in hands‑off search and rescue missions where reliable navigation matters more than raw endurance.
- AeroVironment — historically defense‑oriented, providing tactical UAS and VTOL systems with proven rapid‑deployment characteristics, attractive to governmental programs requiring hardened logistics and ISR integration.
- Draganfly — a North American manufacturer focused on public safety payloads and domestic production footprints, which helps satisfy procurement preferences for localized manufacturing.
- ZenaDrone — a growth‑stage vendor offering long‑range, mission‑specific platforms built around robust telemetry and real‑time data transmission for remote search operations.
- Ascent Aerosystems — supplier of resilient coaxial designs optimized for compact operations in constrained environments and integration with defense/public‑safety systems.
Market concentration metrics reinforce the importance of these players: the top three firms hold a material portion of market revenues, and the top five capture over half of industry value — a structure that creates both competitive barriers and clear acquisition targets for strategic buyers.
Strategic recommendations for 2026
We advise corporate and public‑sector leaders to take four concurrent actions this year to convert market growth into competitive advantage:
- Prioritize compliance as a core capability. NDAA credentials and documented supply‑chain provenance are now as important as performance specifications. For manufacturers, this should be integrated into product roadmaps and supplier contracts; for buyers, certification should be a gated procurement milestone.
- Invest in autonomy and systems integration. Platforms with higher levels of autonomy reduce operator overhead and scale more cost‑effectively as programs move from pilot to continuous operations.
- Design modular service and payload ecosystems. The winning commercial models will combine hardware sales with subscription‑grade software, payload leasing, and field service — turning one‑off deployments into recurring revenue streams and reliable public‑safety capabilities.
- Use scenario‑based budgeting tied to adoption curves. With a 12.45% CAGR and clear upside under accelerated DFR adoption, procurement timelines should be staged: near‑term investments to secure interoperability and compliance, mid‑term capital for scaled deployments, and longer‑term R&D for next‑gen endurance and autonomy.
How to use this research in executive decision making
PW Consulting’s report is designed to be directly actionable for four audiences in 2026:
- CEOs and corporate strategy teams evaluating M&A or partnership plays — use our competitive concentration analysis and M&A scenarios to prioritize targets;
- Procurement and operations leaders at municipalities, utilities, and large enterprises — apply our procurement checklists and TCO models to replace pilots with scalable programs;
- R&D and product teams at OEMs — benchmark autonomy, payload interfaces, and compliance investments against the technology assessment rubrics;
- Investors and PE sponsors — use our market‑level forecasts, concentration metrics, and scenario returns to size investment tickets and staging requirements.
Each user group can adopt the report’s tools directly into board packets, procurement RFPs, or product investment cases. The deliverables were built to reduce time‑to‑decision while preserving the analytical rigor executives require.
Next steps
The executive brief you are reading condenses the core strategic implications of PW Consulting’s full Emergency Rescue Drone Market report. For procurement matrices, regional and application segmentation, granular vendor scores, and downloadable financial models, please consult the full report on our website. Those datasets are essential for teams building specific procurement packages, investment memos, or R&D roadmaps in 2026.
PW Consulting stands ready to help translate this research into a tailored implementation plan, whether you are evaluating a first DFR deployment, planning a national roll‑out, or considering M&A to capture aftermarket service value. Contact our Public Safety & Unmanned Systems practice to schedule a briefing and scenario workshop.
For detailed analysis of this topic, please visit the official page: Emergency Rescue Drone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Built-In Electric Curtains Market Reaches USD 3,248.5 Million in 2025, Poised for 10.51% CAGR Through 2032
By pmarketresearch, 2026-07-01
Built-In Electric Curtains Market: Strategic Imperatives for 2026 — A PW Consulting Preview
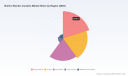
As organizations recalibrate product roadmaps and capital allocation for 2026, the built-in electric curtains market offers a high-growth, technology-inflected opportunity that demands an integrated strategic response. PW Consulting’s forthcoming market study — based on a 2025 base year and a 2026–2032 forecast horizon — shows the market expanding at a compound annual growth rate (CAGR) of 10.51%. After accelerating through 2020–2025, when industry revenue climbed from roughly USD 1.95 billion to USD 3.25 billion, the sector is projected to roughly double over the forecast window to an estimated USD 6.54 billion by 2032. This trajectory reframes the market from niche retrofit projects into a mainstream systems play for smart buildings, hospitality, and premium residential design.
Built In Electric Curtains Market
Why this market matters for 2026 decisions
- Macro upside with widening participation: A sustained double‑digit CAGR signals robust end-market demand across both retrofit and new-build channels. That growth converts into meaningful top-line opportunities for motor manufacturers, track systems suppliers, control-platform vendors, and integrators.
- Convergence of hardware, software and services: The value shift is clear — control ecosystems (smart home protocols, building management integration), installation and after-sales services, and embedded intelligence are increasingly decisive in capture and retention of value.
- Margin pressure from supply‑side dynamics: Raw material and component duties — notably on aluminum extrusions, tubular motor assemblies, and certain fabric classifications — are elevating landed costs for integrated track systems. Combined with global sourcing complexity, these factors require active procurement and product-design responses in 2026.
- Regulatory and safety imperatives: Standards such as ANSI/WCMA A100.1-2022 elevate safety and design requirements for motorized coverings, accelerating transitions from corded to motorized solutions and creating compliance-driven demand for certified systems.
What PW Consulting’s report delivers — operational intelligence, not just theory
Our study is designed as an immediate decision-support tool for executives and business units preparing 2026 strategies. Key deliverables include:
Built In Electric Curtains Market
- Comprehensive market sizing and trend analysis (historical: 2020–2025; base year: 2025; forecast: 2026–2032), with scenario modeling to stress-test plans under alternative macro and regulatory paths.
- Go‑to‑market playbooks for OEMs, system integrators, and distributors — including channel economics, pricing frameworks, and recommended bundling strategies that align hardware sales with recurring service revenue.
- Supply‑chain risk maps and cost levers: actionable interventions such as alternative material specifications, localized extrusion sourcing, and modular motor platforms to mitigate tariff and duty exposure.
- Technology adoption pathways that prioritize protocol compatibility (Matter/Thread/Zigbee/RTS), cybersecurity controls, and retrofit-friendly form factors to reduce installation friction.
- Competitive benchmarking and M&A opportunity maps highlighting potential consolidation targets and partnership archetypes across motors, track systems, and software platforms.
To respect the strategic “preview” intent of this release, we have deliberately highlighted the analysis framework and managerial takeaways while reserving detailed segment-level tables, regional and power-source splits, and company-level revenue breakdowns for the full report and accompanying data workbook.
Built In Electric Curtains Market
Competitive landscape — core players and what they signal for 2026
- Somfy (Cluses, France): A global motorization leader, Somfy’s strength is its ecosystem approach — specialized motors, track systems and smart-home integrations (e.g., TaHoma, RTS/Zigbee). For 2026, Somfy’s playbook will be instructive for firms aiming to combine robust hardware with platform hooks that lock-in integrators and installers.
- Hunter Douglas (Rotterdam, Netherlands): Known for premium window treatments, Hunter Douglas’s proprietary PowerView motorization and vertical channel relationships underscore the importance of design-led differentiation and spec-driven adoption in premium residential and hospitality projects.
- Lutron Electronics (Coopersburg, PA, USA): Lutron’s control-first strategy demonstrates how shading and lighting can be bundled to create outsized retrofit opportunities; their integration capabilities are a reminder that control ecosystems remain a defensible moat.
- Silent Gliss (Bern/Broadstairs): As a specialist in tracks and quiet motorized operation, Silent Gliss highlights the technical differentiation available through mechanical refinement — critical for healthcare, hospitality, and high-end residential installs that value noise and aesthetics.
- Coulisse / Motionblinds (Enter, Netherlands): A B2B smart-window manufacturer, Coulisse’s recent Motionblinds Matter Bridge launch (April 2025) signals accelerating platform convergence and the commercial importance of interoperable standards for clean built-in track integrations.
- Dooya (Ningbo, China): A scale motor OEM/ODM, Dooya illustrates the supply-side leverage of cost-efficient motor manufacturing and OEM partnerships — a capability that global OEMs and systems integrators will increasingly source to balance cost and feature velocity.
Market concentration metrics indicate a mid-range consolidation profile: the top three players account for a meaningful share of market value while the top five extend that advantage. This structure presents windows for challengers with differentiated tech, channel models, or cost structures to scale rapidly through partnerships and selective M&A.
Regulatory, tariff and procurement implications for 2026
- Tariff exposure: Import duties on components and aluminum extrusions are non-trivial and can materially affect unit economics for integrated tracks. Procurement teams should prioritize tariff mitigation strategies including alternative HS classification reviews, near-shore sourcing, and bonded-warehouse logistics for cross-border projects.
- Safety compliance: ANSI/WCMA A100.1-2022 not only raises the bar for product design but also creates specification opportunities for manufacturers who can certify compliance and communicate safety differentiators to builders and procurement officers.
- Standards and interoperability: With Matter/Thread gaining momentum — and vendors like Coulisse building bridges — 2026 will be a pivotal year for platform-level bets. Interoperability reduces install friction and increases conversion in retrofit channels.
Prioritized 2026 strategic moves — what to do first
- Product and platform alignment: Prioritize modular motor architectures and firmware-upgradeable platforms compatible with mainstream protocols. Deliver a clear migration path for installers moving clients from manual or legacy motor systems to integrated smart solutions.
- Supply‑chain resilience: Execute a targeted supplier rationalization to reduce exposure to single-country duties on extrusion and motor components. Establish dual-sourcing and prototype local extrusion runs to cut landed costs and lead times.
- Channel and service economics: Reframe commercial models to reflect install complexity: bundle hardware with certified installation and optional recurring maintenance subscriptions. Train and certify installer networks to reduce field rework and warranty costs.
- Go‑to‑market and partnerships: Forge platform partnerships (Matter/Thread, BMS vendors) and prioritized relationships with hospitality and commercial contractors to capture specification-driven demand. Invest in immersive digital showrooms and AR tools to shorten sales cycles.
- M&A and investment radar: Pursue tuck-in acquisitions that add complementary control software, certified installer networks, or specialized track manufacturing capacity to accelerate growth without diluting engineering focus.
90/180/360 day implementation roadmap
- Day 0–90 (Quick wins): Audit tariff exposure and reclassify critical components where possible; run protocol compatibility tests for core SKUs; launch pilot certified-installer program in one major market.
- Day 90–180 (Scale foundational moves): Finalize dual-sourcing contracts for primary extrusion and motor components; deploy OTA firmware architecture for a single product line; publish safety- and compliance-focused collateral tied to ANSI/WCMA A100.1-2022.
- Day 180–360 (Portfolio and growth): Roll out new modular product family with platform-ready controls; negotiate channel-level distribution agreements with targeted hospitality and integrator partners; evaluate M&A targets surfaced in the report’s opportunity map.
Conclusion — why the full report is mission‑critical for 2026
Built-in electric curtains are no longer a fringe luxury — they sit at the intersection of smart-building controls, design-driven specification, and after-sales service economics. For leadership teams planning 2026, the choices made now about modular product design, supply-chain structure, platform partnerships and channel economics will determine who captures the next wave of growth. PW Consulting’s full report provides the granular segmentation, regional and power-source breakdowns, company-level KPIs, and downloadable financial models necessary to convert these strategic imperatives into executable plans.
To access the full dataset, scenario models, and company benchmarking that support the strategic actions summarized here, visit our report page and request the PW Consulting Built‑In Electric Curtains Market report and accompanying Excel workbook.
For detailed analysis of this topic, please visit the official page: Built In Electric Curtains Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 5.5% CAGR for Jewelry Beads Market (2026–2032)
By pmarketresearch, 2026-07-01
Jewelry Beads Market 2026 Strategic Outlook — Why PW Consulting’s New Report Is a Decision-Maker’s Playbook
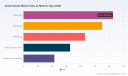
As buyers, manufacturers, and investors prepare budgets and strategic roadmaps for 2026, the jewelry beads market presents a blend of steady growth, structural change, and margin pressure that requires deliberate, data-backed responses. PW Consulting’s latest Jewelry Beads Market report (base year 2025) synthesizes a seven-year historical lens (2020–2025) with a seven-year forecast horizon (2026–2032), quantifying market dynamics and translating them into actionable decisions. The global market stood at USD 2,150 Million in 2025 and — under our base-case assumptions — resumes growth at a compound annual growth rate (CAGR) of 5.5% through 2032, reaching roughly USD 3,128 Million in 2032. This release is purpose-built to guide 2026 investment, sourcing, and product strategies.
Jewelry Beads Market
Why this matters for 2026 planning
- Predictable overall growth, uneven pockets of opportunity. After the pandemic-related shock and a period of volatility in the early 2020s, the market has stabilized into a mid-single-digit growth corridor. That macro consistency creates a reliable top-line backdrop for capital allocation — but the value will accrue disproportionately to firms that capture margin improvements and supply-chain optionality.
- Fragmented competitive structure that favors focused scale. The market concentration is low: the three largest firms account for under one-fifth of global value, and the top five capture less than a quarter. That fragmentation preserves opportunities for niche leaders, private-label play, and vertically integrated players to expand via targeted investments.
- Cost pressure vectors are identifiable and actionable. Energy cost increases for glass production, tariff uncertainty on certain origins, and tightening hazardous-material limits for jewelry components are the primary cost and compliance levers through 2026.
Data-driven takeaways for executives
- Prioritize SKU rationalization and value segmentation. With overall growth modest but consistent, the quickest uplift to margin comes from rebalancing assortments toward premium and differentiated beads (precision-cut crystals, premium seed beads, specialty gemstones) while pruning low-margin commodity SKUs.
- Hedge sourcing with multi-origin strategies. Given current tariff dynamics and sourcing risks tied to specific origins, adopt a dual- or tri-source model for critical inputs to reduce single-origin exposure and maintain negotiating leverage.
- Invest selectively in upstream integration. The fragmented market rewards firms that internalize key value-chain steps (e.g., precision finishing, specialty coatings, proprietary color ranges) that command price premiums and improve quality control.
- Operationalize regulatory compliance as a commercial differentiator. Compliance with cadmium and lead limits (including region-specific restrictions) is a baseline expectation for B2B and consumer channels — firms that can demonstrate robust testing, certifications, and transparent supply chains capture procurement preference.
- Leverage digital channels and community marketing. DIY and maker communities continue to drive demand in jewelry-making and fashion accessories; allocating marketing and fulfillment resources to these channels yields higher lifetime value and brand loyalty.
What the PW Consulting report delivers (practical, executable items)
- Comprehensive market model: A downloadable financial model with historical series (2020–2025) and baseline, upside, and downside scenarios for 2026–2032. The model is parametrized for price, volume, and input-cost shocks so users can run bespoke sensitivity tests.
- Go-to-market playbooks: Channel-specific playbooks for wholesale distribution, direct-to-consumer, kits and tutorials, and OEM partnerships — each with KPI frameworks, sample P&L impacts, and rollout roadmaps.
- Cost and margin diagnostic: Line-item cost builds for glass, crystal, metal, plastic/acrylic and gemstone beads, incorporating recent energy-cost trends and tariff exposures to inform pricing, promo cadence, and supplier contracts.
- Regulatory & compliance pack: Practical checklists and supplier audit templates addressing cadmium, lead, and surface-coating limits that are now standard expectations in major markets; includes recommended lab-testing frequency and sample QA language for contracts.
- M&A and partnership shortlist: A curated list of acquisition targets and strategic partners segmented by capability (manufacturing scale, specialty finishes, distribution reach), accompanied by valuation heuristics and integration risks.
- Risk matrix and contingency playbooks: Playbooks for tariffs, energy-price shocks, and logistic disruptions, with decision triggers that counsel when to renegotiate suppliers, raise prices, or accelerate product transitions.
Competitive landscape: what incumbents and challengers are doing
The competitive set is diverse, ranging from premium crystal specialists to high-volume wholesalers and vertically integrated manufacturers. Key companies profiled in the report include:
Jewelry Beads Market
- Fire Mountain Gems and Beads (Grants Pass, Oregon, USA; https://www.firemountaingems.com) — A large U.S.-based distributor with deep e-commerce and catalog capabilities. Strengths include assortment breadth and fulfillment scale; their challenge is protecting margins in commoditized categories while building exclusives.
- Preciosa Ornela (Zásada, Czech Republic; https://www.preciosa-ornela.com) — A lead player in Czech glass seed beads with strong heritage and color-trend leadership; their seasonal trend releases and manufacturing backlog can set design cycles for downstream customers.
- MIYUKI Co., Ltd. (Japan; https://www.miyuki-beads.co.jp/english/) — Synonymous with precision seed beads, Miyuki’s value is quality and consistency, enabling premium artisans and designers to command higher prices.
- Swarovski AG (Austria; https://www.swarovski.com) — The premium crystal lens for jewelry applications. Swarovski’s brand strength and technical finishing create durable pricing power for precision-cut crystal beads.
- PandaHall (China; https://www.pandahall.com) — High-volume wholesale and one-stop supplier model, important for cost-sensitive channels and fast-turn assortments.
- BeadKraft, Shipwreck Beads, PotomacBeads — U.S.-based specialists that have successfully blended curated assortments with community engagement and tutorial-driven commerce.
Recent industry activity in 2026 underscores market dynamics: trade shows and seasonal trend releases continue to shape demand (notably new color collections and designer collaborations), while procurement sensitivity to tariffs and energy-cost-driven supplier price actions has increased negotiation intensity. Our report synthesizes how these moves affect product cycles and channel economics.
Jewelry Beads Market
Regulatory and trade considerations that affect 2026 choices
- Materials compliance is non-negotiable. Jurisdictional limits on heavy metals in jewelry components now shape sourcing and product design. Buyers need to codify testing and supplier attestations into contracts to avoid recalls and reputational damage.
- Tariffs and origin risk influence sourcing decisions. Import duties on certain bead categories and periodic tariff actions on goods from particular origins create short-term cost variability; incorporate tariff-scenario funds into procurement planning.
- Energy and production-cost volatility. Facilities relying on energy-intensive glass production faced notable cost increases recently — an operational risk that can compress margins unless passed through or mitigated by efficiency upgrades.
Prioritized 90–180 day playbook for 2026
- 90 days: Run the PW Consulting model using your own SKU and supplier data; identify 10 SKUs to delist and 10 SKUs to premiumize. Demand a compliance certificate pack (test results + supplier attestation) from your top 10 suppliers.
- 180 days: Negotiate dual-sourcing contracts for high-risk inputs; pilot a premium-bead capsule with controlled marketing spend; implement a quarterly tariff-impact review tied to procurement approvals.
- 6–18 months: Evaluate small-scale vertical integration (e.g., finishing/coating capacity) or targeted M&A to secure differentiated product capabilities and shorten lead times.
Methodology, confidence, and what we intentionally withhold
PW Consulting’s estimates combine bottom-up supplier and channel surveys, customs and trade flows, price-tracking of commodities and finished beads, and validation interviews with manufacturers, distributors, and design houses. The report includes a transparent, scenario-based forecast framework and stress-tested sensitivity models. To honor the “trailer” principle and channel readers to the full report, we have deliberately not published granular segmentation tables and region/application-level share dashboards in this press release. The full report contains detailed splits by region, material type, and application; supplier-level concentration maps; and downloadable model files for client customization.
Next steps
If your organization is planning supply-chain moves, product-line pivots, or M&A activity in 2026, PW Consulting’s Jewelry Beads Market report offers the quant tools, competitive intelligence, and compliance playbooks you need to act with conviction. For an executive briefing, live model walkthrough, or to license the full dataset and segment-level projections, contact PW Consulting to schedule a tailored advisory session.
For detailed analysis of this topic, please visit the official page: Jewelry Beads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EV Charging Card Market to Expand at 18.24% CAGR as Europe and RFID Drive Growth
By pmarketresearch, 2026-07-01
EV Charging Card Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
As global electrification accelerates, the modest but rapidly scaling EV charging card market is emerging as a pivotal control point in the customer experience, network economics, and interoperability architectures of charging ecosystems. PW Consulting’s latest market brief—anchored on a 2025 base year and a forecast through 2032—translates our proprietary dataset and field work into actionable guidance designed to shape corporate decisions throughout 2026. This release is a strategic “trailer”: it surfaces the actionable insights and structural trends decision-makers need to prioritize, while directing readers to our full report for the granular segmentation and proprietary data that underpin the recommendations.
Ev Charging Card Market
Market snapshot: growth trajectory and market structure
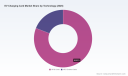
The EV charging card market has moved from a niche accessory to a critical commercial lever. Our analysis shows the total market expanding from USD 485.6 Million in 2020 to USD 1,345.5 Million in 2025, and continuing at a compound annual growth rate (CAGR) of approximately 18.24% through the 2026–2032 forecast window. By 2032 the market is projected to exceed USD 4.3 billion (USD Million unit basis), reflecting both the scale-up of public and commercial charging infrastructure and the increasing preference for physical and embedded access credentials as part of multi-modal billing and roaming ecosystems.
Ev Charging Card Market
Concentration metrics indicate a market that is neither monopolized nor atomized: the top three providers account for a meaningful but not dominant share of overall revenue, and the top five firms increase that share into a clear leadership tier. This mid-level concentration creates room for strategic alliances, niche specialization, and rapid repositioning by agile incumbents and new entrants alike.
Ev Charging Card Market
What the PW Consulting report delivers (practical, operational, ready-to-use)
- Commercial playbooks for CPOs and e-mobility platform providers on card issuance, subscription models, and invoicing flows—tested against live network pilots.
- Vendor selection matrices that score authentication technologies (RFID, NFC, chip-based credentials) against performance attributes, cost-to-implement, and roaming-readiness.
- Procurement templates and CAPEX/OPEX benchmarking tools to compare card issuance, reader retrofits, and backend billing integration alternatives while preserving procurement flexibility under evolving regulation.
- Interoperability and roaming checklists keyed to AFIR, NEVI guidance, and regional certification norms, with practical mitigation pathways for legacy fleet integrations.
- Commercial scenarios and sensitivity analyses that map pricing, station mix, and adoption pathways to revenue outcomes under multiple near-term regulatory and supply-chain environments.
- A confidential annex (available only in the full report) containing the granular regional and end-user splits, contract examples, and unit-cost curves that are essential for transaction diligence and M&A planning.
Competitive landscape: profiles and strategic positioning
The competitive field blends pure-play network operators, energy incumbents, charging hardware suppliers, and platform aggregators. Key players of high strategic visibility include:
- Tesla (Austin, USA): leverages proprietary card and authentication solutions tightly integrated with its Supercharger network to lock in a seamless experience for its user base, while selectively enabling compatibility for wider EV compatibility.
- EVgo (Los Angeles, USA): focuses on fast-charging access cards and payments, recently broadening protocol support to accommodate NACS connectors—an important tactical pivot with direct implications for fleet and public-network interoperability.
- Shell Recharge (The Hague, Netherlands): combines large retail footprint and roaming partnerships to deliver card-based access across diverse public networks, emphasizing scale and convenience.
- ChargePoint (Campbell, USA): integrates card issuance with a robust backend for commercial and fleet customers, selling flexibility and deep systems integration as differentiators.
- Blink Charging (Miami Beach, USA): targets user simplicity and subscription offerings, leveraging RFID as a low-friction authentication layer for large public deployments.
- Octopus Energy (London, UK): offers multi-network cards and integrated billing across partners—a model that underscores energy supplier advantage in bundled services.
- ABB and Siemens : system integrators that pair hardware sales with compatible card solutions, positioning authentication as a feature of comprehensive deployment packages.
- Fortum Charge & Drive, Radius, Tata Power, E-Flux : regional leaders and aggregators that demonstrate how multi-brand card strategies can simplify procurement and billing for fleets and commercial operators in specific markets.
Recent tactical moves—such as EVgo’s February 2026 expansion of NACS fast-charging connectors and Tata Power’s December 2025 launch of an RFID-enabled “EZ CHARGE” card—illustrate two concurrent market logics: the hardware/protocol-led race to accommodate vehicle-side standards, and the product innovation race around payment, security, and tap-and-go convenience in high-growth regions.
Policy, infrastructure, and supply-chain drivers to factor into 2026 decisions
- Regulatory frameworks like the EU’s AFIR mandate and updated U.S. NEVI guidance are re-shaping site selection and interoperability requirements; these dynamics make standardized access credentials a compliance and network-design imperative.
- Infrastructure deployment continues at pace—U.S. DC fast-charging capacity added materially in 2025—raising the stakes for scalable credentialing and billing systems that can support high-throughput sites.
- Installation cost dispersion—particularly between Level 2 and high-power DC—means card-strategy choices need to be modeled against site economics: high-power nodes require lower friction and more reliable payment flows.
- Trade policies encouraging onshoring of critical components are creating both procurement constraints and opportunities to localize card production and reader hardware under national content rules.
Strategic imperatives for 2026: seven focused actions
- Adopt an interoperability-first mindset. Prioritize card solutions that support roaming and multiple authentication protocols; treat roaming contracts as strategic assets, not commodities.
- Stress-test payment flows against high-load scenarios. Ensure card and backend systems can handle concurrent sessions at high-power sites without degrading authorization performance or reconciliation accuracy.
- Localize sourcing where regulation or economics demand it. Build supply-chain contingencies for card production and reader upgrades in markets with content or tariff constraints.
- Rethink fleet propositions. Fleet operators are a core growth cohort; design card+telemetry bundles that simplify invoicing, telemetry reconciliation, and driver experience.
- Use cards as retention levers. Integrate loyalty, dynamic pricing, and energy tariff optimization into card-based products to increase lifetime value.
- Secure the edge. Invest in cryptographic credentialing and OTA update pathways to reduce fraud risk and extend card lifecycle under evolving security frameworks.
- Price for scale and modularity. Build pricing that reflects issuance volumes, roaming fees, and backend integration complexity—use tiered contracts to accelerate adoption among small and mid-size CPOs.
How to use the report in 2026 planning cycles
For C-suite executives, the brief functions as a decision-ready dossier: it aligns market-sizing, concentration measures, regulatory milestones, and competitive moves into a prioritized set of investments, partnerships, and go-to-market pivots to consider for budgeting cycles and board discussions in 2026.
For commercial teams and product leaders, the playbooks and procurement templates reduce time-to-decision and provide defensible benchmarks for negotiations with hardware vendors, roaming platforms, and card manufacturers.
For M&A and corporate development groups, the market growth profile and concentration metrics frame target screening: the landscape supports bolt-ons that increase scale, technology that improves unit economics, and regional plays where regulatory timing accelerates demand.
Methodology and limits (why the full report matters)
Our projections are based on a harmonized synthesis of primary interviews with network operators, hardware vendors, energy suppliers, and fleet managers, combined with a proprietary dataset covering 2020–2025 and scenario-driven forecasts through 2032. To preserve the utility of this executive brief as a strategic “trailer,” we have intentionally withheld the granular regional and end-user splits and the transaction-level unit-cost curves, which are included in the full report and are essential for financial diligence and site-level modeling.
Next steps and how PW Consulting can assist
- Engage PW Consulting for a tailored executive workshop to translate the market brief into a 90-day action plan aligned to your organization’s capabilities and market exposure.
- Access the full report to unlock the confidential annex with granular segmentation, contract templates, and vendor scorecards required for procurement and M&A due diligence.
- Commission a custom scenario model: combine your portfolio of sites and vehicles with our demand and cost curves to test outcomes under regulatory and tariff permutations.
2026 will be a year of decisive moves in the EV charging card market—those who treat cards as strategic infrastructure rather than a commoditized add-on will capture disproportionate value as this market scales. PW Consulting’s full report provides the granular inputs and playbooks you need to make those moves with confidence.
For detailed analysis of this topic, please visit the official page: Ev Charging Card Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com