

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Fused Silica Tubing Market to Expand at a 6.12% CAGR — Strong Growth Ahead

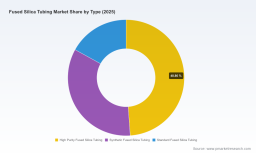
Fused Silica Tubing Market: Strategic Imperatives for 2026 — Insights from PW Consulting’s Latest Report
PW Consulting today releases a strategic briefing drawn from our comprehensive Fused Silica Tubing Market study (base year 2025, forecast period 2026–2032). This market — valued at USD 845.0 Million in 2025 — is positioned for steady expansion, tracking to approximately USD 1.28 Billion by 2032 at a compound annual growth rate (CAGR) of 6.12%. For corporate leaders, investors and supply-chain executives, the report crystallizes the commercial and operational choices that will determine winners and laggards across the next strategic planning cycle.
Fused Silica Tubing Market
Why this study matters for 2026 decision-makers
-
Clarity for capital allocation: Our scenario-aligned financial model translates market growth trajectories into required capex, timing imperatives and break-even horizons for capacity additions or brownfield upgrades.
Fused Silica Tubing Market -
Sourcing and risk mitigation: The report maps feedstock and processing chokepoints — enabling procurement teams to quantify exposure and design multi-tier sourcing strategies before shortages or price shocks materialize.
Fused Silica Tubing Market -
Product and route-to-market strategy: We translate application-level demand dynamics into SKU rationalization and premium-product roadmaps that help R&D and commercial teams prioritize high-margin niches.
-
M&A and partnership intelligence: The study’s competitive lens surfaces realistic bolt-on and JV targets, supported by seller scorecards and synergistic value estimates.
What the report contains (practical, decision-ready modules)
-
Robust market sizing and forecasting engine — bottom-up revenues for the global market, base-year reconciliation and multiple forecast scenarios reflecting moderate, upside and downside demand environments.
-
Demand-driver deep dives — detailed demand drivers across key end markets, adoption curves for higher-purity and larger-diameter tubing, and product-fit matrices tied to customer pain points.
-
Supply-side intelligence — plant-level capacity mapping, manufacturing route comparisons (plasma fusion, flame hydrolysis, synthetic routes), and a dynamic cost curve model showing where margin pressure will migrate under different feedstock and energy cost assumptions.
-
Feedstock and upstream risk assessment — concentrated sources of high-purity quartz, regulatory exposures in extraction regions, and geopolitical scenarios including tariff and trade friction outcomes that materially affect feedstock flows.
-
Competitive benchmarking and supplier scorecards — comparative capabilities (diameter range, purity, coatings, tolerances), practical supplier selection frameworks, and a consolidation outlook informed by market concentration metrics.
-
Commercial playbooks — tailored go-to-market strategies for global leaders, regional specialists and niche micro-tubing players (analytical and microfluidic segments), including pricing levers and channel tactics.
-
Investment decision matrices — capital versus outsourcing trade-offs, greenfield vs. brownfield scenarios, payback sensitivity tables, and recommended decision thresholds for 2026 capex cycles.
-
Regulatory and sustainability roadmap — compliance checklists, lifecycle-impact levers, and stakeholder engagement templates for licensing and community relations in extraction-heavy geographies.
-
Executive dashboards and downloadable financial models — editable spreadsheets for tailored sensitivity analysis and board-ready slides summarizing strategic options.
Macro dynamics reshaping the landscape
-
End-market momentum is heterogeneous. Semiconductor wafer processing and advanced electronics continue to underpin premium demand for high-purity and large-diameter tubing, while other segments — such as fiber-optics and laboratory equipment — contribute steady, quality demand. The net effect is a resilient, mid-single-digit growth path for the aggregate market.
-
Feedstock remains the dominant supply-side variable. Ultra-high purity quartz feedstock is a scarce and geographically concentrated input. Environmental regulation, local mining constraints and evolving permitting regimes are tightening availability for the very highest purity grades, creating a structural premium for assured supply and traceability.
-
Policy and trade dynamics matter more than ever. Tariff negotiations and trade policy shifts in 2025 introduced measurable supply-chain friction. Procurement strategies that do not explicitly model tariff and logistics volatility will be disadvantaged when spot shortages or diversion of shipments occur.
-
Technology and product evolution are differentiators. Manufacturers that can offer lower-defect tubing, larger diameter ranges, improved UV and laser stability, or integrated coatings (for microfluidics and analytical applications) capture outsized margins versus commodity players.
Competitive landscape — who matters and what they mean for strategy
The market exhibits moderate-to-high concentration: the top three global players capture the majority share, with the top five materially increasing that share. This concentration creates both barriers and opportunities: incumbents enjoy scale and long-term customer relationships, while specialists and regional players win where customization, speed-to-supply and technical service are critical.
-
Global scale leaders: Established producers with vertically integrated operations and broad product portfolios are positioned to defend premium customers and invest behind capacity expansions and quality upgrades. Their strategic playbooks will focus on optimization of global supply footprints and customer lock-in via long-term contracts and tailored service agreements.
-
Technology and process specialists: Firms using unique fusion or plasma-based processes can address large-diameter and custom cylinder demands that are difficult for commodity manufacturers to meet. These players are attractive targets for strategic partnerships or OEM agreements where technical exclusivity is valuable.
-
Regional and niche suppliers: Companies focused on precision, microcapillary, or polyimide-coated tubing serve analytical and instrument OEMs where tight tolerances and rapid customization trump scale. They excel in specialist aftermarket and instrument-level integration sales.
-
Integrated Asian producers: Large integrated upstream-to-downstream manufacturers in Asia provide competitive cost structures and scale; their strategic moves — including capacity and vertical integration — should be watched closely by Western buyers planning supplier rationalization.
Our report includes concise profiles of the market’s core participants, evaluating manufacturing footprints, recent capital projects, IP strengths and customer focus areas. Notable developments we highlight include capacity expansions and catalog extensions that incrementally shift competitive dynamics and customer expectations — events that every strategic planner should model into 2026 procurement and sourcing strategies.
Practical strategic recommendations for 2026
-
Prioritize secured feedstock arrangements. Buyers should negotiate multi-year agreements with tiered volume and quality clauses, and evaluate strategic investments or JV arrangements that provide preferential access to ultra-high purity feedstock.
-
Segment product portfolios by margin and complexity. Reallocate R&D and sales resources to higher-margin, lower-commodity-risk product lines and consolidate low-margin SKUs to improve utilization rates.
-
Invest in flexible manufacturing. Modular capacity and process versatility (ability to switch between diameters and purity classes) will mitigate demand volatility and reduce time-to-market for premium products.
-
Design for supply-chain resilience. Implement dual-sourcing for critical inputs, stress-test logistics under tariff and port-congestion scenarios, and develop contingency inventories for high-risk nodes.
-
Explore vertical or near-vertical plays. For producers, selective upstream integration or long-term supply partnerships can protect margins; for buyers, co-investment can secure priority allocation in constrained environments.
The PW Consulting advantage — what differentiates our analysis
Our study blends factory-level production economics, feedstock traceability mapping and customer-level demand projections. We operationalize insights into prioritized actions — not just charts. The report supplies an editable financial model, supplier scorecards and decision matrices that CFOs and business-unit leaders can use directly for board-level investment choices.
Trailer principle — what we intentionally withhold (and why)
In keeping with the “trailer” objective of this release, we present the strategic context, high-level market trajectory and executable recommendations while withholding certain segment-level revenue splits and granular pricing matrices that materially affect competitive positioning. These proprietary datasets — including detailed regional/application breakdowns and price-sensitivity curves — are available in the full report and the accompanying workbook. This approach preserves the commercial value of the primary data while giving executives the analytical framework needed to prioritize next steps immediately.
Next steps — how to use the report in your 2026 planning cycle
-
Board briefings: Use our executive summary and dashboard to frame capital-allocation debates and set risk tolerances for feedstock exposure.
-
Sourcing strategy updates: Integrate the supplier scorecards and scenario outputs into procurement RFPs and supplier audits.
-
M&A screening: Apply the acquisition filters and synergy calculators to shortlist targets that accelerate technical capability or market access.
To access the full dataset, proprietary segment-level models and the downloadable Excel workbook that powers our recommendations, please visit the PW Consulting website and request the Fused Silica Tubing Market report. For bespoke advisory engagements, our strategy team is available to run the report’s models with your internal data and produce an execution-ready roadmap tailored to your organization.
For detailed analysis of this topic, please visit the official page: Fused Silica Tubing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com