

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Targeted Drugs for Multiple Myeloma Market to Surge from USD 25.85B in 2025 to USD 40.04B by 2032 at a 6.45% CAGR

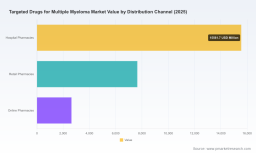
Targeted Drugs for Multiple Myeloma: Strategic Imperatives for 2026 — PW Consulting Market Insight
PW Consulting's latest market research, Targeted Drugs For Multiple Myeloma Market (base year 2025; forecast 2026–2032), translates a complex and fast-moving therapeutic landscape into decision-grade intelligence for executives, investors, and policy makers. The report synthesizes market modeling with regulatory inflection points, payer dynamics, and competitive playbooks to support high-consequence choices in 2026.
Targeted Drugs For Multiple Myeloma Market
Executive snapshot: why 2026 is an operating inflection
Our model projects the global targeted multiple myeloma market to continue its steady expansion beyond the 2025 base, tracking a compound annual growth rate (CAGR) of approximately 6.45% across the 2026–2032 forecast window. This growth trajectory is driven by a convergence of therapeutic innovation (bispecific antibodies, next-generation CELMoDs, optimized proteasome inhibitors, ADCs and CAR‑T), evolving regulatory acceptance of surrogate endpoints, and commercial strategies that emphasize combination regimens and earlier-line adoption.
Targeted Drugs For Multiple Myeloma Market
Concentration in the market remains meaningful: the top three companies collectively command a majority share, with the five largest firms controlling well over two-thirds of industry revenues. That structure creates both barriers and windows for entrants — scale matters for manufacturing, distribution and payer negotiations, yet differentiated clinical profiles and novel mechanisms can rapidly shift prescriber preference and formulary position.
Targeted Drugs For Multiple Myeloma Market
What this report delivers — practical chapters for 2026 decision-making
- Actionable market model: A transparent, auditable revenue model with scenario levers for uptake curves, line-of-therapy penetration, and pricing assumptions covering 2026–2032. The model is designed for rapid customization to reflect corporate-specific assets and regional go‑to‑market strategies.
- Regulatory and reimbursement playbook: Detailed implications of recent FDA guidance treating MRD negativity and complete response as potential primary endpoints, updated accelerated-approval pathways, and evolving HTA expectations in major markets.
- Competitive deep dives: Strategic profiles of incumbent and emerging companies — clinical positioning, commercial readiness, manufacturing capacity, and partnership maps — linked to our scenario-based share forecasts.
- Go-to-market sequencing & launch risk matrix: Prescriptive sequencing options (e.g., combination vs monotherapy launch, inpatient vs outpatient channels), required evidence generation, and payer negotiation tactics.
- Portfolio & M&A decision support: Valuation drivers and sensitivity analyses for bolt-on acquisitions, licensing deals, and clinical program prioritization in the context of patent cliffs and generic pressures.
- Real-world evidence (RWE) and safety monitoring roadmaps: Practical templates showing how to translate post‑launch RWE into label expansions, REMS removal petitions, and payer coverage policies.
Competitive landscape — strategic implications for market participants
The rapid cadence of approvals and pivotal data readouts through 2025–2026 has reconfigured therapeutic choices and created tactical priorities for industry participants.
- Large integrated pharmaceutical firms: Companies with broad oncology portfolios and advanced biologics platforms have leveraged diversified mechanisms (anti‑CD38 antibodies, bispecifics, CAR‑T) to defend and expand franchise value. Recent approvals and label expansions for combination regimens strengthen incumbents’ bargaining positions with payers, but they must continuously demonstrate cost-effectiveness and long-term benefit versus emerging oral agents and off-the-shelf bispecifics.
- Biotech innovators and specialty players: Firms advancing bispecific antibodies, CELMoDs, ADCs and nuclear-export inhibitors can disrupt line-of-therapy sequencing with compelling efficacy or convenience. Success will depend on clinical differentiation, manufacturing scale, and smart partnering that aligns regulatory pathways with reimbursement strategies.
- CAR‑T sponsors and cell-therapy platforms: Operational excellence (manufacturing yield, vein-to-vein time, and hospital network coverage) remains critical. Regulatory moves that streamline monitoring and REMS for certain CAR‑T constructs materially lower commercialization friction and broaden addressable populations.
Selected recent developments illustrate the speed and direction of change. In early 2026, approvals enabling combination uses of bispecifics with established monoclonal antibodies have accelerated adoption in relapsed and earlier lines. Positive Phase 3 data for next‑generation oral agents create competitive pressure on older backbone therapies, while regulatory acceptance of MRD as an endpoint is shortening evidence timelines for accelerated approvals. Concurrently, generic entry for legacy agents changed economics for long-term maintenance strategies in 2026 — a structural consideration for pricing and contracting.
Regulatory and payer dynamics: new rules, new playbooks
Two regulatory themes dominate near-term strategy: (1) increased regulatory acceptance of surrogate endpoints such as MRD negativity for accelerated approvals, and (2) selective de‑risking of cell therapy post‑market requirements informed by real-world evidence. These developments compress time-to-market for differentiated assets but escalate the importance of robust, early post-approval data collection plans.
From a payer perspective, the shift is toward outcome-based contracting and indication-based pricing for high-cost therapies. Integration of MRD into coverage criteria creates an opportunity for companies to design diagnostics-linked reimbursement strategies but also raises the bar for demonstrating durable benefit. Our report includes templates for payer dossiers and contract structures that reflect current HTA expectations across major markets.
Practical recommendations for 2026 boardrooms
- For incumbent biologics owners: Prioritize real-world evidence programs that demonstrate additive value of combination regimens; accelerate manufacturing investments to secure supply for earlier-line indications.
- For small and mid‑cap innovators: Focus on niche differentiation (e.g., safety profile, outpatient administration) and structure early partnerships to de‑risk scale-up and payer access.
- For investors and M&A teams: Recalibrate valuations to reflect the interplay of patent expiry on older agents, the probability-weighted revenue contribution of bispecifics and CAR‑T, and the speed at which MRD acceptance can convert accelerated approvals into commercial revenues.
- For hospital systems and providers: Implement capacity planning aligned to anticipated shifts from inpatient to outpatient delivery for select cell and bispecific therapies; leverage RWE to support expanded site-of-care adoption.
How to use this research in 2026 strategic planning
Executives should treat this report as both a diagnostic and an operational playbook. Key use cases include:
- Board-level briefing materials that translate forecast scenarios into revenue, margin and P&L sensitivities;
- Commercial launch plans that prioritize indication sequencing and payer engagement based on modeled uptake and pricing scenarios;
- Due-diligence scaffolds for licensing or acquisition that align clinical readouts with manufacturing and reimbursement risk;
- RWE and post‑market study blueprints to support label expansion, REMS removal, and durable coverage agreements.
Why PW Consulting’s approach is different
We combine a transparent financial model with on-the-ground regulatory tracking, MSL and payer interviews, and manufacturing capacity checks to produce forecasts that are not just plausible, but operationally executable. Our deliverables include an editable model, a prioritized list of clinical evidence gaps tied to commercial milestones, and a market-access playbook that maps negotiation points to contract structures and evidence generation timelines.
Next steps & how to access the full intelligence
This article intentionally highlights strategic conclusions and programmatic implications while withholding proprietary segmentation tables and granular revenue splits that underpin our scenario outputs. Those detailed slices — central to commercial planning and investment underwriting — are available in the full Targeted Drugs For Multiple Myeloma Market report and accompanying model.
Contact PW Consulting to request an executive briefing, obtain the full dataset, or commission a bespoke variant of the model tuned to an asset, portfolio or geographic footprint. In a market where regulatory shifts, therapeutic innovation and payer expectations are simultaneously accelerating, timely, nuanced intelligence will be the difference between market share retention and strategic obsolescence in 2026.
For detailed analysis of this topic, please visit the official page: Targeted Drugs For Multiple Myeloma Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com