

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Market Insights: Walk‑In Humidity Chambers Poised to Expand at a 6.3% CAGR Through 2026–2032

Walk In Humidity Chambers Market: Strategic Intelligence for 2026 Decision-Makers
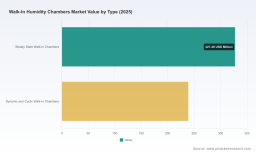
As organizations across pharmaceuticals, electronics, automotive, aerospace, and industrial testing recalibrate capital plans for 2026, the Walk In Humidity Chambers market presents a clear, actionable growth narrative that we quantify and contextualize in PW Consulting’s latest study. The global market—anchored on a rigorous base-year analysis through 2025—has demonstrated steady expansion and is modeled to continue at a compound annual growth rate (CAGR) of 6.3% through our 2026–2032 forecast window. In plain terms, this is a market moving from mid‑single‑hundreds of USD millions toward a near‑billion dollar arena by the end of the decade, creating decisive strategic choices for buyers, suppliers, and investors.
Walk In Humidity Chambers Market
Why this study matters for 2026 strategy
-
Timing: 2026 is the inflection year for many capex programs initiated in 2022–2024; procurement teams must decide between immediate replacement, scaled retrofits, or staged procurement to match evolving testing profiles.
Walk In Humidity Chambers Market -
Risk management: Supply chain fragilities—particularly for stainless steel interiors, specialized insulation, high‑performance compressors and precision humidity sensors—require preemptive sourcing and inventory strategies.
Walk In Humidity Chambers Market -
Regulatory alignment: Stricter compliance requirements (ICH guidelines for stability testing, FDA/GMP, ISO 17025 and CE standards) are raising minimum performance and validation expectations for walk‑in solutions, changing the economics of procurement and lifecycle management.
-
Service economics: As energy efficiency and uptime become as important as footprint, total cost of ownership (TCO) and availability of local service networks will increasingly determine supplier selection and aftermarket revenues.
Key market dynamics shaping 2026 decisions
-
Moderate fragmentation with consolidation potential: Market concentration metrics show a competitive landscape where the top three players do not dominate the sector entirely (CR3 ~31.4%), and the top five control under half of market revenues (CR5 ~42.8%). This creates fertile ground for bolt‑on acquisitions, differentiated service models, and regional scale plays.
-
Sector-driven demand diversity: Pharmaceutical stability programs, electronics and semiconductor qualification, automotive and EV environmental testing, and aerospace/defense qualification are driving different performance requirements—forcing vendors to balance standardized product lines against bespoke, regulated solutions.
-
Energy and efficiency premium: New designs that reduce life‑cycle energy consumption and improve humidity control precision command pricing and shorten payback periods—an increasingly common procurement criterion in capital approval committees.
-
Supply chain sensitivities: Component-level concentration (compressors, sensors) introduces procurement risk and creates strategic options for vertical integration, supplier redundancy, and inventory hedging.
What the PW Consulting report delivers (practical, executable content)
-
Actionable market sizing and forward scenarios: Our model quantifies baseline demand and stresses it under three adoption and regulatory scenarios—useful for budgeting, sensitivity analysis, and board‑level risk assessment.
-
Procurement playbook: Step‑by‑step frameworks for RFP crafting, performance specification checklists (sensors, tolerances, thermal inertia), site acceptance testing protocols, and negotiation levers that preserve long‑term service economics.
-
TCO and ROI tools: Discounted cash‑flow templates and payback calculators that incorporate energy consumption profiles, maintenance regimes, and uptime penalties—ready to drop into capital approval packages.
-
Supplier risk matrix and sourcing options: Tiered supplier maps, dual‑sourcing strategies for critical components, and criteria for deciding between modular panel builds vs. permanent structural installations.
-
Competitive intelligence and M&A playbook: Vendor scorecards, capability gap analyses, and a prioritized list of small‑cap acquisition targets (sensor manufacturers, software/monitoring specialists, regional service providers) for faster capability build.
-
Compliance and validation checklists: ICH‑aligned protocols, GMP and ISO 17025 compatibility frameworks, and audit templates tailored to pharmaceutical and medical device stability testing.
-
Technology roadmap: Adoption trajectories for digital monitoring, remote validation, energy recovery systems, and modular architectures that support both walk‑in and drive‑in solutions.
Competitive landscape — what to watch in 2026
The market includes a mix of legacy environmental simulation names, specialist room builders, and growing regional OEMs. Several recent company moves sharpen competitive dynamics and hint at strategic direction:
-
BINDER GmbH (Tuttlingen, Germany) recently expanded its capabilities through acquisition activity focused on humidity and temperature stability rooms. This enhances its competitive positioning in regulated pharmaceutical testing and accelerates product integrations around FDA‑compliant monitoring solutions.
-
Associated Environmental Systems (AES) has invested in significantly larger manufacturing capacity, improving its ability to scale custom and high‑load walk‑in projects and to shorten lead times for North American customers—an operational advantage in supply‑constrained cycles.
-
Weiss Technik North America (including CSZ heritage) is likewise expanding manufacturing and office capacity to address both customized industrial applications and volume orders, strengthening its service footprint for high‑availability sectors.
-
Specialists such as Darwin Chambers, Parameter Generation & Control (now aligned with larger group strategies), Russells Technical Products, Testron Group, and Wewon leverage differentiated strengths—pharma‑grade humidity control, modular construction, salt‑fog and large specimen testing, and regional cost advantages—allowing them to capture niche demand and contract manufacturing opportunities.
Collectively, these developments point to a market where scale, regulatory compliance capabilities, fast delivery, and local service are becoming decisive competitive attributes. Expect ongoing consolidation around complementary tech (remote monitoring, analytics) and service networks rather than pure product cross‑selling alone.
Strategic implications and recommended actions for 2026
-
For buyers: Prioritize suppliers with validated compliance histories and demonstrable local service footprints. Use our TCO models to compare energy and service costs over a 7–10 year horizon, not just initial purchase price.
-
For vendors: Focus on modular architectures, rapid delivery lines, and integrated monitoring software to capture growth. Pursue bolt‑on acquisitions that shore up sensor and controller supply or extend service networks in key geographies.
-
For investors: Seek targets in the mid‑market that offer proprietary humidity control algorithms, strong service margins, or regional dominance—these are likely consolidation candidates given current concentration dynamics.
-
For supply chain teams: Hedge exposure to critical raw materials (stainless steel, compressors, humidity sensors) and consider long‑term supplier agreements or strategic stock positions to protect project timelines.
What we’re deliberately leaving out here (and why)
In this executive preview we present overarching growth trends, competitive dynamics, and prescriptive actions designed to influence 2026 strategy. To preserve the value of the full research and adhere to our “trailer” approach, granular regional and application splits, vendor‑level revenue breakdowns, and detailed segment tables are not reproduced in this release. Those datasets are included in the complete PW Consulting report—along with downloadable models, supplier scorecards, and negotiation playbooks that procurement and strategy teams can operationalize immediately.
Next steps
If your organization is preparing capital plans, evaluating vendors, or sizing M&A opportunities in 2026, PW Consulting’s full Walk In Humidity Chambers report delivers the empirical models, compliance templates, and tactical playbooks to move from analysis to execution. Contact our industry team to arrange a briefing, obtain the full dataset and Excel modeling pack, or commission a custom workshop tailored to your portfolio and geographies of interest.
In a market growing at a sustained mid‑single‑digit CAGR and undergoing structural shifts in compliance, energy, and service economics, the right intelligence now will determine who wins tomorrow’s contracts. PW Consulting’s analysis turns market momentum into executable strategy.
For detailed analysis of this topic, please visit the official page: Walk In Humidity Chambers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com