

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Predicts 22.46% CAGR for Three-Dimensional Topological Insulator Market, Fueling a Quantum Computing and Spintronics Boom
By pmarketresearch, 2026-07-02
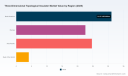
Three Dimensional Topological Insulator Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting today releases an executive preview of our forthcoming Three Dimensional (3D) Topological Insulator Market report, a practical intelligence product designed to inform high-stakes corporate decision-making in 2026. Built on a rigorous historical series (2020–2025) and a detailed forecast to 2032, this analysis synthesizes market sizing, technology maturation, supplier dynamics, and regulatory shocks to deliver decision-ready guidance for materials suppliers, device OEMs, investors, and advanced research organizations.
Three Dimensional Topological Insulator Market
Market Trajectory at a Glance
Our base-year assessment shows the 3D topological insulator market as an emerging but rapidly scaling segment of the broader quantum-materials economy. Measured in USD Million, the market expanded notably during 2020–2025 and, based on our deterministic scenario, is projected to grow at a compound annual growth rate (CAGR) of 22.46% over the 2026–2032 forecast horizon. Under the central projection, the market transitions from a niche, research-dominated space in 2025 toward a more commercially actionable market by the end of this decade, reflecting accelerating commercialization in quantum computing, spintronics, thermoelectric overlaps, and specialized optoelectronic modules.
Three Dimensional Topological Insulator Market
Two structural observations are critical for 2026 strategy: first, the market is not winner-take-all; it is moderately concentrated with the top three suppliers accounting for roughly 44% of identifiable commercial activity and the top five nearing the mid-60s percentile in aggregate concentration. Second, this concentration coexists with a diversified set of specialized suppliers — ranging from single-crystal producers to target and film providers — creating both partnership and competitive-play opportunities.
Three Dimensional Topological Insulator Market
Why 2026 Is a Strategic Inflection Point
- Technology-to-product handoffs: Several device classes dependent on 3D topological insulators reach critical maturity for prototype-to-pilot transitions in 2026–2028, compressing timelines for supply agreements and qualification.
- Supply-side stressors: Raw-material shocks and export controls experienced in 2025 materially change procurement economics and risk profiles for bismuth/telluride-based chemistries — altering cost, lead times, and contracting practices.
- Consolidation and specialization: With moderate market concentration, 2026 presents opportunistic windows for selective M&A, vertical integration, and strategic partnerships to secure IP, fabrication capability, or materials feedstock.
Supply Chain, Raw Materials and Regulatory Dynamics
Our analysis identifies tellurium and related chalcogenide precursors as the single most consequential supply-side variable for topological-insulator module economics and project timelines. In 2025 the market experienced pronounced price volatility and sourcing friction driven by changes in primary refining dynamics and export/licensing policies. For procurement and sourcing teams, this translates into three immediate operational needs: tightened visibility into feedstock origin, contractual clauses to mitigate shipment timing and licensing uncertainty, and scenario-based sourcing roadmaps that include material substitutions and inventory buffering.
Regulatory developments — notably export licensing practices that lengthened approval workflows in major refining hubs — are already changing lead-time assumptions. Companies that treat access to precursor chemistry as a strategic asset (not just a commodity procurement item) will gain short-term advantage in project execution and long-term lead on cost curves.
Competitive Landscape: Profiles and Strategic Postures
Our competitive analysis synthesizes product portfolios, go-to-market models, and technology moats across the active supplier base. The market comprises specialized crystal growers, materials manufacturers, thin-film and deposition suppliers, and distribution channels that serve both academic and industrial R&D customers.
- HQ Graphene (Groningen, Netherlands): Recognized for high-quality single crystals of prototypical 3D topological insulators and quaternary alloys used in foundational research. Their value proposition centers on material quality control for physics-driven device programs.
- American Elements (Los Angeles, USA): Operates at the manufacturing and distribution junction, supplying high-purity chalcogenide chemistries across crystal, powder, and sputtering-target formats. Their scale and breadth position them as a reliable sourcing partner for applied R&D and pilot manufacturing.
- Stanford Advanced Materials (Lake Forest, USA): Combines CVD film offerings and crystal products to serve device developers pushing toward prototype demonstrations. Their film capability is particularly relevant for firms transitioning to device integration.
- Kurt J. Lesker Company (Jefferson Hills, USA): A key supplier of sputtering targets and evaporation materials, addressing thin-film deposition pathways critical for device manufacturability and process repeatability.
- MSE Supplies LLC (Tucson, USA): Functions as an important distribution channel, aggregating specialty crystals and films for academic and industrial labs where reproducibility and logistic convenience matter.
- 2D Semiconductors / Nuevogen LLC (Phoenix, USA): Differentiates on guaranteed topological properties in single-crystal materials and specialized layered chalcogenides, catering to device developers who require verified performance baselines.
Strategically, these firms illustrate three archetypal plays: (1) vertical suppliers that emphasize material purity and reliability; (2) scale manufacturers that optimize format diversity (powders, targets, films); and (3) channel/distribution specialists that accelerate market access for small-scale adopters. Each archetype presents different partnership, investment, and competitive defense implications for corporate strategists.
Report Contents — Practical Tools Included
The full PW Consulting report is structured to be directly actionable for leadership teams preparing 2026 budgets and strategic programs. Key deliverables include:
- Comprehensive market model (historical and forecasted USD Million series, 2020–2032) with built-in scenario toggles for high/low adoption and raw-material shock paths.
- Supplier risk matrix and mitigation playbook highlighting critical nodes in the materials/value chain and practical contractual language templates for supply agreements and co-development arrangements.
- Technology readiness mapping and device-route decision framework, enabling product teams to prioritize materials/formats by commercialization risk, scaleability, and integration cost.
- Go-to-market and procurement playbooks tailored to four buyer archetypes (materials manufacturers, device OEMs, R&D institutions, and system integrators), including sample short- and mid-term KPIs.
- An M&A and partnership checklist identifying value-creation levers for rapid inorganic expansion and non-dilutive collaboration models. Note: the report provides anonymized target archetypes and due-diligence scorecards rather than named transaction advice.
- Data annex with vendor mapping, supplier capability matrices, and an executive dashboard for board-level briefings.
We deliberately package granular datasets behind the full report to preserve the commercial utility of detailed segmentation and supplier share tables. This preview intentionally avoids publishing segment-by-segment percentages and deal-level finance metrics so that decision-makers obtain maximum value from the original report deliverable.
Strategic Recommendations for 2026 Decision Cycles
Combining market growth, supplier concentration, and near-term material risks, PW Consulting advises three immediate priorities for 2026 planning:
- Secure material optionality: Establish multi-tiered supply agreements that balance long-term offtake with optionality for substitute chemistries and secondary suppliers. Where feasible, structure contracts with price-hedging or indexation clauses tied to validated raw-material benchmarks.
- Invest in scale-ready process capability: For device OEMs and integrators, prioritize development paths that de-risk deposition, integration, and testing at pilot scale — particularly for thin-film routes that offer manufacturability advantages.
- Partner early with materials specialists: Consider co-development arrangements with crystal growers and target manufacturers to accelerate qualification timelines and lock in proprietary process tolerances that translate directly into product differentiation.
For investors and corporate development teams, a targeted approach that combines minority equity in materials innovators with strategic supply or IP agreements reduces downside risk while preserving option value as the market scales. For procurement leaders, treating tellurium and bismuth-supply strategies as strategic initiatives — complete with quarterly risk reviews and scenario rehearsals — will materially reduce program slippage in 2026.
How PW Consulting’s Report Supports 2026 Decisions
The value proposition of this report lies in translating high-level market momentum into discrete, executable choices. Whether a company needs to decide on capital allocation for pilot fabs, to pursue a bolt-on acquisition, or to rework supplier contracts in the face of export-controls, our modeling tools and pragmatic playbooks are calibrated for real-world procurement cycles and board-level decision timelines.
Importantly, the analysis is designed for rapid assimilation: executive dashboards summarize the forecast and supplier risk; scenario templates enable sensitivity testing against raw-material shocks; and playbooks convert strategic intent into 90/180/360-day action plans suitable for 2026 planning cadences.
Next Steps and Access
This preview outlines the strategic contours and implications for 2026 stakeholders. The complete PW Consulting Three Dimensional Topological Insulator Market report contains the full data suite — including the granular market model, supplier-level matrices, contract templates, and the bespoke scenario outputs required to operationalize the recommendations above.
Organizations that require accelerated access for procurement negotiations, investment diligence, or product roadmap prioritization can contact our research desk to arrange a briefing and to license the dataset and deliverable set. For public details and ordering information, please visit our report page on the PW Consulting website.
Methodology and Independent Rigor
Our forecast integrates primary interviews with material suppliers and device developers, price and shipment data triangulated from commodity reporting, and proprietary adoption modeling validated against pilot-program disclosures. We apply conservative adoption curves where device value chains remain unproven at scale and overlay stress-testing for material-price and regulatory scenarios consistent with 2025 market events.
For executives who require a distilled briefing that maps the report findings into an operational 2026 roadmap — including tailored supplier negotiation scripts and a pilot qualification checklist — PW Consulting offers bespoke advisory packages that couple the report’s data with hands-on implementation support.
PW Consulting — translating advanced-materials complexity into strategic clarity for the decisions that matter in 2026.
For detailed analysis of this topic, please visit the official page: Three Dimensional Topological Insulator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 6.82% CAGR for PHS Resin in KrF Photoresist Market Through 2032
By pmarketresearch, 2026-07-02
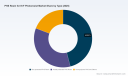
PHS Resin for KrF Photoresist Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s new market brief on PHS (polyhydroxystyrene) resins for KrF (248 nm) photoresists provides a focused intelligence product designed to inform capital allocation, sourcing strategies, and M&A choices in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the report positions the global market (base year 2025) at approximately USD 300.6 Million and models growth to 2032 under a compounded annual growth rate (CAGR) of 6.82%. Those headline figures understate an important nuance: while the headline market expands steadily, supply-side concentration, raw‑material dynamics, and regulatory pressure create asymmetric risks and strategic opportunities that require active management this year.
PHS Resin for KrF Photoresist Market
Why this matters for 2026 planning
- Supply security is strategic. PHS-based KrF resins remain critical inputs for mature-node logic, certain memory applications and advanced packaging lithography. Market concentration is high: the three largest suppliers account for a dominant share of production, and the top five approach near-total market control. For buyers, this creates single-supplier risk that materializes quickly under capacity disruptions or rapid demand re-profiling.
- Macro growth masks micro volatility. A mid-single-digit CAGR to 2032 signals a healthy, predictable market overall, but pockets of rapid capacity build-out and domestic substitution—especially in APAC—produce episodic swings in availability, pricing and qualification lead times. Tactical agility in 2026 will out‑perform static long-term plans.
- Raw inputs and cost pressure are real. Industry tracking shows global production of PHS resin for KrF photoresists reached roughly 321 tons in 2024, with an average market price near US$575/kg. These inputs carry material cost and inventory implications for formulators and OEMs, particularly as feedstock and specialty monomer availability can fluctuate with petrochemical cycles.
What our report delivers (operational, purchase‑ready intelligence)
The brief is structured as a toolkit for executives setting 2026 priorities. Highlights include:
PHS Resin for KrF Photoresist Market
- Actionable market sizing and scenario modeling — base year 2025 and an IT‑grade forecast to 2032 (including sensitivity testing for demand shocks, substitution waves and regulatory uplifts).
- Supply‑chain heat maps — mapped upstream feedstocks, synthesis bottlenecks, qualification timelines, and time-to-volume for new resin chemistries.
- Supplier scorecards — qualitative and quantitative assessments across technology maturity, capacity footprint, geographic risk, and qualification velocity (full share tables and granular supplier metrics are available in the full report).
- Regulatory and sustainability playbook — impact analysis of PFAS-related developments, hazardous substance trends and compliance pathways for chemically amplified resist systems that use PHS base resins.
- Commercial playbook for buyers and investors — sourcing strategies (dual‑sourcing, toll manufacturing options, consignment), contracting levers (price collars, volume-flex terms), and JV/partner evaluation criteria.
- M&A and capacity investment guidance — a prioritized short list of acquisition and greenfield targets, with decision trees for quick-win vs. long-term integration plays.
Competitive landscape — who matters and why
The PHS-for-KrF arena is populated by three strategic cohorts: established global specialty chemical houses (legacy Japanese and Western players); fast‑scaling domestic Chinese suppliers; and specialized regional producers targeting niche formulation requirements. Key industry participants profiled in the report include long‑standing resin and resist manufacturers and several emerging local contenders:
PHS Resin for KrF Photoresist Market
- Nippon Soda Co., Ltd. — long experience supplying high‑purity PHS derivatives and recognized for stable qualification pathways with tier‑1 resist formulators.
- Maruzen Petrochemical Co., Ltd. — established PHS lines targeted at KrF base polymers with reliable product performance histories.
- Shin‑Etsu Chemical Co., Ltd. — a major lithography material supplier with integrated capabilities across protected PHS systems for KrF resists.
- DuPont de Nemours, Inc. — a global formulators’ scale player that recently increased KrF photoresist manufacturing capacity, reinforcing its role as a strategic supplier to semiconductor fabs and foundries.
- Tokyo Ohka Kogyo Co., Ltd. (TOK) and TOHO Chemical Industry Co., Ltd. — both provide technology‑intensive resist systems and have long product pedigrees in PAG‑driven chemistries.
- Chinese innovators — several firms (including Bayi Space LCD, Tongcheng New Materials, WEIMAS and others) are moving from pilot to ton‑scale supply, accelerating domestic substitution and lowering qualification barriers for local formulators.
What these dynamics mean: incumbent suppliers continue to exert pricing and qualification discipline, but new entrants are reducing barriers to entry in predictable product bands (pilot‑to‑hundred‑kg scale moving toward hundred‑ton capacities). Buyers that treat supplier engagement as a binary choice (single dominant vendor vs. generic market) will miss opportunities to secure cost advantage and mitigate disruption.
Recent developments to watch (signal vs. noise)
- DuPont’s incremental capacity expansion in Japan (2024) materially increases available KrF photoresist throughput and shortens lead times for formulators that have long qualification relationships with the company.
- Several Chinese firms have progressed pilot runs to hundred‑kg scale and signalled hundred‑ton expansions under construction; these moves are meaningful for regional sourcing strategies and for fabs targeting domestic supply chains.
- Regulatory exploration of PFAS alternatives in chemically amplified resists continues, but no full performance replacement for current PAG‑enabled KrF chemistries has been broadly validated — meaning compliance cost and disclosure risk are material but substitution risk is still emergent.
Strategic imperatives for 2026
Our fieldwork and financial modeling point to a short list of high‑leverage actions executives should prioritize in 2026:
- Lock in flexible supply agreements. Negotiate contracts that combine minimum commitments with scalable options and performance milestones. Where possible, secure qualification slots with at least two approved resin sources to avoid single‑node failure exposures.
- Invest in qualification pipelines. Time-to‑qualified‑supply is the dominant operational lead time. Devoting engineering resources and co‑development funding to shorten qualification cycles (material matching labs, joint reliability testing) yields outsized near‑term benefits.
- Pursue targeted partnerships with upstream producers. Equity investments, tolling arrangements, or long‑term supply‑for‑off‑take deals with mid‑tier producers can lock in cost advantage and provide optionality versus competition for incumbent capacity.
- Hedge raw material exposure tactically. Given observed price points and the limited global tonnage of PHS, buyers should model variable‑price scenarios and consider inventory hedges or strategic buffer stocks for critical launches.
- Plan for PFAS‑driven compliance costs. Even absent a full substitution, evolving regulation will impose documentation, testing and potential reformulation costs. Incorporate these into 2026 product and R&D roadmaps now to avoid last‑minute tradeoffs.
- Make data‑driven M&A choices. Prioritize targets that offer rapid qualification capabilities, complementary geographies, and controllable capital intensity rather than chasing scale alone.
Risk matrix and monitoring priorities
For 2026 decision cycles we recommend ongoing monitoring in four domains:
- Capacity movements: new plant commissioning, expansions, and qualification throughput of emerging suppliers;
- Regulatory signals: changes in hazardous substance rules, PFAS policy updates, and regional reporting requirements;
- Feedstock volatility: monomer availability, petrochemical feedstock cycles and substitution pressure from ArF/EUV process migration in adjacent product families;
- Customer qualification timelines: measured lead times from sample to production acceptance, which remain the practical gating factor for converting availability into revenue.
How PW Consulting’s brief supports your 2026 playbook
The value proposition of this deliverable is immediate: it provides commercial leaders and strategy teams a compact, actionable evidence base to accelerate decisions this year. The report synthesizes supplier intelligence, scenario financials, and a procurement playbook into a format that can be operationalized by sourcing, product and corporate development teams within 90 days.
Note: this public summary is intentionally selective. The full report includes granular supplier scorecards, a downloadable financial model, scenario outputs for demand shocks and substitution paths, and a prioritized list of acquisition targets and partnership metrics. Those details are gated to ensure strategic confidentiality and to preserve the competitive value of the contained intelligence.
Next steps
If your 2026 plan includes CAPEX allocation, M&A pursuit, new fab ramps, or a supplier renegotiation cycle for KrF photoresist materials, schedule a briefing with PW Consulting. Our analysts can run an on‑demand sensitivity sweep using your specific demand profile, map the fastest supplier qualification pathway, and provide the procurement template your sourcing team needs to execute within Q3–Q4 2026.
To access the full market model, supplier share matrix, and tactical playbooks, please visit the official report page linked in this release. PW Consulting’s team is available to customize the findings to your organization’s risk tolerance, regional exposure, and product roadmaps.
For detailed analysis of this topic, please visit the official page: PHS Resin for KrF Photoresist Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ferrochrome Powder Market Reaches USD 505.5 Million in 2025, Set to Grow at a 4.85% CAGR During 2026–2032
By pmarketresearch, 2026-07-02
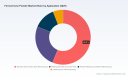
Ferrochrome Powder Market — 2026 Strategic Outlook (PW Consulting)
PW Consulting’s new market study on Ferrochrome Powder (base year 2025; forecast period 2026–2032) positions senior executives and deal teams to make higher-confidence decisions as the sector navigates decarbonization, energy volatility and customer premiumization. Our high-level market model shows the ferrochrome powder market expanded from approximately USD 385.12 Million in 2020 to USD 505.5 Million in 2025, and—at a compound annual growth rate (CAGR) of 4.85%—is projected to reach roughly USD 704.21 Million by 2032. This briefing distills the strategic implications for 2026 decision cycles while reserving the segment-level tables, supplier scorecards and scenario workbooks for the full report.
Ferrochrome Powder Market
Why this report matters for 2026 corporate decisions
- Procurement and cost strategy: Quantifies exposure to feedstock (chromite) volatility and energy price swings, enabling procurement teams to design hedging and contractual protections tailored to powder grades and carbon profiles.
- Capex and plant planning: Provides a decision framework for investments in low‑emission smelting, enrichment and powder atomization facilities linked to payback sensitivity under carbon price regimes.
- Product and commercial strategy: Maps the premiumization pathways for low‑carbon and high‑purity powders across welding, powder metallurgy and additive manufacturing (AM) applications.
- M&A and partnerships: Identifies the value levers private equity and strategic corporates should seek—vertical integration, energy-secured assets, and specialty powder capability.
- Regulatory and market access: Translates incoming carbon policy (notably CBAM) into actionable supplier selection criteria and cost-to-serve models for imports and exports.
Macro dynamics reshaping the ferrochrome powder market
- Transition economics and CBAM: The European Union’s Carbon Border Adjustment Mechanism came into force in January 2026. Importers of ferrochrome products now face certificate obligations tied to embedded emissions, materially altering landed cost calculus for high-emission powder imports into Europe. For buyers and suppliers competing in or exporting to markets with carbon adjustments, carbon intensity is now as commercially salient as micron distribution or carbon-content grade.
- Feedstock supply concentration: Ferrochrome production remains closely tied to chromite ore availability. South Africa, Kazakhstan and India continue to command outsized upstream influence; supply disruptions or price spikes in ore markets transmit quickly to producer margins and to downstream powder pricing.
- Energy and decarbonization: Smelting energy intensity, grid reliability and access to low‑carbon power are determinative for future competitive advantage—particularly for players pursuing low-carbon, high‑purity powders targeted at premium stainless and specialty steelmakers.
- Shifts in Chinese production: Recent capacity additions and regional restart dynamics have led to notable shifts in high‑carbon ferrochrome output year‑on‑year. These movements affect global freight flows and short‑term price arbitrage opportunities for powder purchasers and traders.
- Demand bifurcation: End markets are polarizing—large-volume stainless mills prioritize cost and stable supply, while rapidly growing niches (additive manufacturing, powder metallurgy, surface engineering) demand tighter quality controls and traceable low‑carbon credentials.
Competitive landscape — structure and strategic postures
The market shows moderate concentration: the top-three producers account for roughly 42% of market share, while the top-five approach close to 59%. This concentration profile creates an environment where scale, integration and energy security confer durable advantages, but specialist powder producers retain pricing power in premium niches.
Ferrochrome Powder Market
- Outokumpu Oyj (Helsinki): Leveraging the Kemi chrome mine and the Tornio smelter, Outokumpu is positioning itself as a vertically integrated supplier of low‑carbon ferrochrome and enriched chromium materials. Its announced pilot plant investment in the U.S. (late‑2025) signals an intent to scale high‑purity, low‑emission powder capabilities for third‑party sales—a strategic play to capture premiums in markets where carbon and origin matter.
- Glencore / Glencore‑Merafe Chrome Venture (Baar / South Africa): A major supplier into stainless steel value chains, Glencore’s scale is complemented by strategic moves toward energy collaboration in South Africa. Their MoU for sustainable energy solutions suggests an industry pivot to secure lower‑carbon power for smelting, an essential step to defend competitiveness under carbon pricing.
- Samancor Chrome (Johannesburg): One of the largest integrated producers, Samancor’s volume and logistics clout underpin supply security for high‑carbon specialties and metallurgical demand—important for buyers prioritizing throughput and cost.
- Tata Steel Limited (Mumbai): Beyond scale, Tata is differentiating on sustainability credentials—issuing an Environmental Product Declaration in the ferrochrome segment—thereby improving access to European and sustainability-driven buyers.
- Specialist powder groups (e.g., Metal Powder Group, Stanford Advanced Materials) and Chinese producers (multiple regional manufacturers): These players focus on product quality, consistency and competitive factory-gate pricing across carbon grades. Their technical know‑how and flexible supply models make them go‑to partners for welding consumables, AM feedstock and tailored metallurgy.
- Mid‑tier and regional players: Producers in Kazakhstan, India and China provide important capacity buffers and offer partnership opportunities for offtake and tolling arrangements that can be structured to manage carbon and feedstock risks.
What PW Consulting’s full report delivers (practical, transaction‑ready content)
- Market sizing and forecast models (2020–2032) with scenario layers for carbon-pricing, ore shocks and energy cost pathways—includes dynamic dashboards that allow users to re-run the model under alternate assumptions.
- Supplier scorecards and due‑diligence templates covering quality controls, traceability, emissions intensity, energy mix, logistics resilience and counterparty ratings.
- Capex & project tracker: a monitored registry of announced brownfield and greenfield investments, pilot plants and atomization lines—mapped by expected ramp timelines and strategic intent.
- Price and cost build‑ups: atomized cost models for representative powder grades (energy, reductant, ferroalloy inputs, labor, freight) to support margin and negotiation scenarios.
- Regulatory impact matrices: CBAM exposure matrices, customs & tariff sensitivities, and compliance playbooks for European access.
- Commercial playbooks: buyer segmentation, go‑to‑market pricing frameworks for premium low‑carbon powder, and sample specification sheets for welding, AM and metallurgical customers.
- M&A and partnership shortlist: targets and valuation cushions for strategic acquirers and private equity, including integration risk checklists and synergies templates.
- Operational checklists: recommended retrofits and digital controls for improving yield and reducing emissions in existing powder production lines.
Note: The report reserves segment‑level numerical breakdowns, regional tables and supplier-specific financials behind the full analysis package; the above is designed to communicate practical value without disclosing the granular tables that underpin our models.
Ferrochrome Powder Market
Practical 90/180/360‑day playbook for 2026
- 0–90 days: Rapid carbon exposure audit. Map your powder sourcing by embedded emissions and landed cost into target markets (especially EU). Secure short-term offtake or tolling arrangements with suppliers that can provide traceability and provisional low‑carbon certificates. Run stress tests against a CBAM‑plus-energy‑spike scenario.
- 90–180 days: Selective supply chain de‑risking. Negotiate flexible contracts with volume bands and emergency allocation clauses. Evaluate tolling or JV options with regional low‑carbon smelters. Begin technical trials with specialist powder suppliers for AM and powder metallurgy applications to capture premium demand.
- 180–360 days: Capital and commercial moves. Finalize capex or retrofit plans where IRR is resilient under carbon price forecasts. Pursue targeted M&A or minority investments in powder specialists that have two‑to‑three year scale-up visibility or proprietary low‑carbon process IP. Launch certified low‑carbon product lines for customers willing to pay a premium.
Scenario framing and recommended responses
- Baseline (CAGR ~4.85%): Steady stainless steel demand with gradual premiumization for low‑carbon powders. Recommended response—invest selectively in low‑emission product capability and sign multi‑year procurement contracts with carbon-adjusted pricing floors.
- Carbon‑constrained (accelerated CBAM & stricter import measures): Risk of premiuming low‑carbon powder and penalizing high‑emission imports. Recommended response—fast‑track certification, partner with energy-secured smelting projects and consider localizing production to regulated markets.
- Supply shock (ore or energy disruption): Tightening volumes and spot price spikes. Recommended response—activate contingency inventory, ramp supplier diversification, and assess tolling/prefinance deals that convert feedstock into powder without immediate capital outlay.
Key takeaways for executives and investors
- The market is growing and re‑pricing along carbon and quality dimensions—our top‑line forecast to 2032 reflects that structural shift as well as cyclical influence.
- Energy availability and chromite feedstock access are the twin operational levers that will determine which producers can sustainably capture premium margins in low‑carbon powder segments.
- Companies that combine traceable low‑carbon production, technical powder expertise and flexible commercial structures will outperform peers in the emerging CBAM era.
For procurement leaders, operations heads, corporate strategists and investors preparing 2026 budgets and M&A pipelines, PW Consulting’s full Ferrochrome Powder Market Report delivers the models, supplier intelligence and actionable playbooks needed to convert market insight into measurable outcomes. The deep segmentation tables, supplier financials, and scenario workbooks referenced above are available in the complete report.
For detailed analysis of this topic, please visit the official page: Ferrochrome Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automated Ophthalmic Perimeters Market to Grow from USD 379.9 Million in 2025 to USD 545.34 Million by 2032 at a 5.31% CAGR — North America Leading with USD 131.48M
By pmarketresearch, 2026-07-02
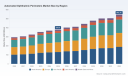
Automated Ophthalmic Perimeters Market: Strategic Briefing for 2026 Decision-Makers
PW Consulting is pleased to release a strategic briefing drawn from our full market research report on the Automated Ophthalmic Perimeters market. As senior strategy advisors and the firm’s chief industry analysts, we prepared this executive preview to articulate why healthcare executives, product leaders, investors, and hospital procurement teams should recalibrate strategies in 2026. The market for automated perimetry is neither static nor niche—overall industry revenues expanded from roughly USD 295.4 Million in 2020 to about USD 379.9 Million in 2025, and our base-case forecast projects growth to approximately USD 545.3 Million by 2032 at a 5.31% CAGR. These headline dynamics matter: they reflect durable demand driven by aging populations, expanding glaucoma diagnostics, and rapid feature-led substitution across clinical workflows.
Automated Ophthalmic Perimeters Market
Why this briefing matters for 2026
-
Timing: 2026 is a pivotal inflection year. Capital equipment cycles in hospitals, shifting reimbursement bandings, and the maturation of objective and VR-based perimetry converge to create opportunity windows for new entrants and incumbent expansion. Decisions made in 2026—on product roadmaps, clinical evidence investments, and channel realignment—will determine share trajectories into the next funding and procurement cycle.
Automated Ophthalmic Perimeters Market -
Momentum: The market’s medium-term trajectory shows a steady climb from a mid‑2020s baseline to a materially larger opportunity by 2032. That trajectory supports multi-year commercialization investments, but only where companies align innovation with adoption frictions faced by end users.
Automated Ophthalmic Perimeters Market -
Concentration: Market concentration remains meaningful. Our analysis shows the top three players account for a strong majority of revenue, and the top five amplify that dominance—an important input when modeling competitive responses, price elasticity, and partnership leverage.
Key market dynamics shaping strategy
-
Technology integration and workflow efficiency: Buyers increasingly prize perimeters that integrate imaging, active retinal tracking, AI-driven progression algorithms, and faster test protocols. Vendors advertising measurable workflow gains—reduced patient chair-time, parallel imaging plus perimetry, or binocular testing modes—are gaining traction in high-volume settings. Expect acceleration of hybrid offerings combining traditional static perimetry with VR and portable modalities for outreach and screening workflows.
-
Regulatory and evidence thresholds: Market access remains gated by device clearance regimes. In the U.S., 510(k) clearance is required for many perimetry systems and CE Mark under the EU Medical Device Regulation is the baseline for Europe. Notably, objective perimetry systems have begun to clear both pathways, increasing the bar for clinical claims and creating differentiation via evidence-backed, objective endpoints.
-
Reimbursement and commercialization economics: Visual field testing is supported by established CPT codes that cover automated threshold perimetry. Typical payment schedules provide a predictable technical and professional revenue stream in many markets, with fee levels that influence acquisition payback calculations for hospitals and clinics. Procurement models are therefore sensitive to test throughput, technician time, and the ability to deliver measurable improvements in operational KPIs.
-
Hospital capital cycles: Hospitals remain a central end-user and primary commercial channel for capital perimeters. Their CapEx decisions are influenced by overall hospital budgets, competing diagnostic priorities, and demonstrable ROI tied to disease management pathways like glaucoma clinics. Vendors that can quantify per-device throughput gains, reduced downstream costs through earlier detection, or service simplifications are advantaged.
-
Pricing and tiering: The market bifurcates between full-featured premium platforms and lean, portable/virtual screening solutions. A pragmatic commercial playbook requires a clear tiered offering, bundled service options, and flexible financing to align with buyer procurement rhythms.
Competitive landscape—what to watch in 2026
The competitive map includes established optical and ophthalmic device leaders, specialized perimetry manufacturers, and several agile new entrants leveraging VR or objective retinal-tracking technologies. Key firms in the ecosystem have complementary strengths that define likely competitive moves and partnership opportunities:
-
Carl Zeiss Meditec AG (Jena, Germany) —a foundational platform player known for its Humphrey Field Analyzer series and extensive installed base; strength lies in clinician trust, validated progression analysis tools, and broad service networks.
-
Haag-Streit AG (Köniz, Switzerland) —offers projection-based systems with a reputation in both static and kinetic perimetry and robust progression analytics aimed at clinical users requiring flexible testing paradigms.
-
Topcon Corporation (Tokyo, Japan) —competes on speed and workflow integration with compact and binocular solutions; claims of substantive time savings in testing translate directly into procurement arguments for high-volume practices.
-
NIDEK Co., Ltd. (Gamagori, Japan) and Heidelberg Engineering GmbH (Heidelberg, Germany) —both pursue integration of imaging and perimetry, pushing toward unified diagnostic suites that facilitate single‑visit comprehensive glaucoma assessments.
-
Centervue/iCare (Padua/Finland) —notable for combining retinal tracking with confocal fundus imaging, positioning itself at the intersection of imaging and functional testing.
-
Konan Medical USA, Inc. (Irvine, CA) —a pivotal recent development: objectiveFIELD (OFA) achieved regulatory milestones that validate objective perimetry with retinal tracking for major markets. This regulatory progress accelerates adoption conversations around objective endpoints and will pressure incumbents to articulate comparative evidence strategies.
-
Additional regional players and new technology providers (including VR-focused entrants and several established instrument OEMs) create a competitive set where niche innovation, regional channels, and cost positioning matter.
Strategic implications and recommended moves
-
For incumbents: defend share through evidence and service economics. Prioritize clinical validation that demonstrates superiority on adoption-relevant metrics (time-per-test, reproducibility, progression detection sensitivity), strengthen installed-base service contracts, and consider platform modularity to accommodate hybrid imaging/perimetry workflows.
-
For challengers and startups: target clear use-cases where incumbents are weakest—portable screening, outreach programs, and objective perimetry for populations that struggle with subjective testing. Secure regulatory pathways early and design pricing models that lower procurement friction (e.g., OPEX-based contracts, pay-per-use, or bundled screening programs).
-
For hospital systems and large eye-care networks: leverage purchasing power by specifying workflow and interoperability requirements; include throughput and outcome KPIs in procurement contracts; and pilot VR/portable solutions in community outreach before broader rollouts.
-
For private equity and strategic investors: prioritize targets with defensible clinical data, recurring consumables or service revenue, and access to distribution channels that can scale. Given the market’s concentration and steady growth, bolt-on consolidation in regions with fragmented supply remains a practical route to expand share.
What our full report delivers (practical, actionable content)
The full PW Consulting Automated Ophthalmic Perimeters report is structured to be deployment-ready for 2026 planning cycles. Highlights include:
-
Market model and forecast (2020–2032) with scenarios—base, upside, and conservative—anchored to macro drivers and tested against sensitivity levers such as reimbursement shifts and hospital CapEx trends.
-
Competitive playbooks—detailed profiles of incumbent and emerging players, product positioning matrices, likely go-to-market tactics, and M&A target shortlists mapped to strategic themes.
-
Commercial adoption maps—buyer personas, procurement cycles, and decision criteria across hospitals, ophthalmic clinics, and diagnostic centers with pragmatic sales scripts and ROI templates.
-
Regulatory and reimbursement navigators—step-by-step pathways for market entry in major jurisdictions, plus clinical evidence checklists tailored to claim substantiation for objective perimetry and hybrid imaging-perimetry solutions.
-
Pricing and contracting toolkit—recommended tiered pricing, service bundling, and financing constructs designed to shorten procurement approval times and protect margins.
-
Scenario-based investment cases—three investment roadmaps for investors and corporate development teams with expected payback horizons under different adoption assumptions.
How to use this briefing in 2026 planning
-
Begin by stress‑testing your product roadmap against the report’s scenarios. If your R&D timeline crosses the next two procurement cycles, adjust feature prioritization toward clinically validated workflow gains and interoperability.
-
Calibrate go-to-market resources to hospital and high-volume specialty clinic behaviors: prioritize pilot sites that can generate peer-reviewed evidence and broadcaster testimonials for scaling procurement approvals.
-
Where regulatory milestones have recently shifted (e.g., objective systems achieving dual-market clearances), re-run ROI models to capture new premium pricing or faster uptake in certain payer systems.
-
Use the report’s commercial templates to simulate pricing with your local reimbursement realities in mind; in many jurisdictions visual field CPT equivalents provide a stable baseline for payback calculations.
Next steps and where to find the full intelligence
This executive preview is intended to inform 2026 strategic choices and to highlight the operationally relevant intelligence contained in the full PW Consulting market study. The comprehensive report contains the granular segmentation, region‑level demand drivers, and downloadable datasets that senior leaders and deal teams require to execute. We intentionally hold back detailed segment and regional allocations in this briefing to protect the actionable modeling embedded in the primary research.
To engage PW Consulting for a tailored briefing—where we map the market analysis directly to your balance sheet, product roadmap, or M&A thesis—please contact our Industry Practice. Access to the full dataset and segmentation tables is available through the report landing page and via a direct request to our research team.
Closing perspective
The Automated Ophthalmic Perimeters market is evolving into a higher‑value, evidence-driven arena where product differentiation, regulatory credibility, and service economics are the principal drivers of competitive advantage. A mid-single-digit CAGR and expanding absolute market size make this a compelling sector for disciplined investment. However, the winners in 2026 will be those who translate technological novelty into verifiable clinical and operational outcomes, align pricing with procurement realities, and navigate regulatory gateways proactively. PW Consulting’s full report equips you to take those next steps with precision; this briefing is your roadmap to why 2026 is the year to act.
For detailed analysis of this topic, please visit the official page: Automated Ophthalmic Perimeters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Military Ammonium Perchlorate Market to Grow at a 5.48% CAGR Through 2032
By pmarketresearch, 2026-07-02
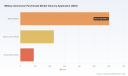
Military Ammonium Perchlorate Market — Strategic Intelligence for 2026 Decisions
Executive snapshot
PW Consulting today releases an executive primer drawn from our forthcoming Military Ammonium Perchlorate Market research. The study consolidates five years of historical observation (2020–2025) with a forward-looking forecasting horizon (2026–2032) and is designed to support board-level and business-unit decisions in 2026. At the macro level, the global market measured approximately USD 921.54 Million in the base year 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.48% across the 2026–2032 forecast window, reaching an estimated USD 1,338.76 Million by 2032. The market remains highly concentrated (CR3 ≈ 78.45%; CR5 ≈ 91.12%), underscoring the strategic importance of supplier relationships, capacity security, and regulatory compliance for defense and space programs.
Military Ammonium Perchlorate Market
Why 2026 is an inflection year for AP strategy
-
Demand signal intensification: Defense modernizations, allied integration on missile and solid-rocket motor programs, and a steady cadence of civil launch activity are collectively increasing requirements for high-spec ammonium perchlorate (AP) grades. Even modest annual growth compounds quickly in a concentrated supplier market.
Military Ammonium Perchlorate Market -
Supply-side reconfiguration: Recent capacity investments and targeted expansions are reshaping available supply. Notably, a major U.S. producer has received board-level approval for a material-capex expansion—approximately a USD 100 million program to add a new production line, with more than 50% capacity uplift targeted for completion in 2026—an action with clear implications for domestic sourcing and allied supply assurance.
Military Ammonium Perchlorate Market -
Regulatory tightening and trade controls: AP and its precursors are subject to export-control regimes and munitions-list designations. In early 2025–2026 we have observed heightened enforcement and scrutiny on certain perchlorate precursors, increasing compliance overheads and creating strategic incentives for onshore or allied-sourced inventory and dual-sourcing strategies.
-
Cost volatility drivers: AP production economics are tightly coupled to upstream feedstocks—principally ammonia and perchloric chemistry—and logistics. Recent price behavior across production centers has driven benchmark pricing upward, creating a renewed focus on cost-to-deliver, indexation clauses, and feedstock hedging for long-term contracts.
What the PW Consulting report delivers (practical, decision-ready content)
Our full study is organized to convert market intelligence into executable decisions for 2026. The deliverables include:
-
An integrated market model (historical 2020–2025; forecast 2026–2032) that supports scenario testing across demand shocks, regulatory shifts, and feedstock price swings.
-
Supply-chain mapping down to primary feedstocks, critical intermediates, and logistic pinch points, with a supplier concentration heatmap that highlights single-source risk exposures.
-
Regulatory and export-control matrix—detailing jurisdictional constraints, licensing timelines, and mitigation levers for program planners and export-control teams.
-
Unit-cost build-ups and margin sensitivity analyses that quantify the impact of ammonia and chemical feedstock swings on producer economics and bid competitiveness.
-
Supplier scorecards and procurement playbooks—covering quality certifications, security-of-supply evidence, capacity ramp profiles, and negotiation levers for long-lead purchases.
-
Capex and M&A decision frameworks tailored to strategic investors, incumbent producers, and defense contractors evaluating vertical integration versus contracting strategies.
-
Operational risk and contingency templates for program managers to size inventory buffers, expedite-insurance needs, and fallback sourcing routes in the event of export-control escalation.
We intentionally withhold granular regional and application-level splits in this press release to preserve the report’s commercial value. The report itself contains the full segmentation, tables, and downloadable model available to subscribers and licensed users.
Competitive landscape — what incumbents and challengers are signaling
The AP market is dominated by legacy producers with deep process know-how and defense-grade certifications. Leading players combine long production pedigrees, specialist process capabilities, and proximity to defense ecosystems. Key strategic observations:
-
Domestic anchoring and compliance credentials matter: Producers that operate under sustained government oversight and hold long-term DoD/NASA or national defense certifications retain positional advantage for sensitive programs. Certification footprints (e.g., MIL-A spec compliance, ISO regimes, and REACH where applicable) are a gating factor for program-level procurement.
-
Capacity expansions are not neutral: Announcements of large-scale investments materially change procurement calculus—reducing some premium-on-security pricing but introducing risk around qualification timelines, first-off quality, and ramp reliability. Buyers should insist on staged acceptance criteria tied to production audits and sample qualification runs.
-
Regional diversification is increasing: Newer and regional suppliers in Asia and Europe supply defense and civil programs but face higher barriers for transfer into U.S.-controlled programs due to export-control regimes and qualification hurdles. For allied programs, however, reciprocal arrangements and bilateral approvals can lower these barriers subject to political dynamics.
-
Non-transparent seller economics: The concentration metrics indicate that three to five suppliers dominate supply. This elevates negotiation asymmetries, especially for non-standard grades and ultra-fine particles used in high-performance motors.
Regulatory, feedstock, and price dynamics that will shape supplier strategies
-
Export-control overlay: AP is frequently captured under munitions-list and missile-control regimes, which impacts cross-border flows, licensing timelines, and the viability of certain procurement routes. Precursor shipments have seen heightened enforcement and selective denial policies that require legal and compliance functions to be tightly integrated into sourcing decisions.
-
Feedstock sensitivity: AP production is a chemistry-driven process built on ammonia and perchloric-acid derivatives. Price direction and availability of these feedstocks directly influence producer margins and contract pricing. Our modelling shows that even modest upward moves in upstream costs can materially compress supplier margins absent pass-through mechanisms.
-
Benchmark pricing behavior: Recent market checks indicate upward pressure on AP benchmark levels across major production locales during Q1–Q2 2026. Buyers negotiating multi-year supply agreements should incorporate indexed pricing, performance-based volume commitments, and cadence-linked escalators.
Strategic imperatives for corporate and program leaders in 2026
Based on PW Consulting’s integrated analysis, organizations should prioritize the following actions this year to convert market intelligence into operational advantage:
-
Lock in qualification windows early: For defense and space programs with fixed launch or production milestones, start material qualification cycles in 2026. The supplier-base concentration and recent capacity projects mean that lead times for qualified production can be the critical path for schedule adherence.
-
Adopt a multi-layer sourcing strategy: Blend long-term offtake from certified incumbents with contingent contracts from regional suppliers who can step in for non-sensitive applications. Ensure all contracts include clear traceability, audit access, and reciprocal quality clauses.
-
Hedge feedstock exposure: Work with suppliers to embed feedstock-hedging clauses or develop joint-buying pools for ammonia and perchlorate intermediates where appropriate. This reduces cost volatility exposure and aligns incentives for continuous supply.
-
Integrate compliance into procurement KPIs: Export-control and licensing risks are now procurement risks. Add regulatory compliance, licensing cycle time, and export footprint to supplier scorecards to reduce program-level surprises.
-
Evaluate strategic investments selectively: For firms contemplating vertical integration or minority stakes in production assets, our capex sensitivity modelling highlights the scale and timeline needed to realize facility-level security benefits. Not every program requires ownership; in many cases, secured long-term contracts with escalation and capacity reservation outperform greenfield builds.
How this report supports executable 2026 decisions
PW Consulting’s report is structured as a hands-on toolkit rather than a descriptive narrative. It provides the financial model and regulatory playbooks procurement, program managers, strategy teams, and corporate development functions need to:
-
Stress-test procurement strategies against realistic price and regulatory scenarios;
-
Prioritize supplier audits and MRO/qualification milestones to match program timelines;
-
Quantify the trade-offs between onshore capacity, allied sourcing, and inventory carrying costs;
-
Identify M&A targets and partnership structures that close critical capability gaps with minimal program risk.
Next steps — where to get the full intelligence
This press release is a strategic extract intended to orient executives and program leaders to the actionable value within PW Consulting’s Military Ammonium Perchlorate Market report. To preserve commercial sensitivity and the practical edge it provides, we have intentionally withheld the granular regional and application-level tabulations and unit-level forecasts. Licensed users of the full report receive the underlying data model, supplier worksheets, regulatory heatmaps, and a set of bespoke scenario outputs aligned to program and investor questions.
For subscription access, corporate licensing, or to request a tailored briefing for your procurement, compliance, or M&A team, please contact PW Consulting through our website or client services desk to arrange a secure briefing and data delivery.
For detailed analysis of this topic, please visit the official page: Military Ammonium Perchlorate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global LNG Market to Rise from USD 135 Billion in 2025 to USD 179 Billion by 2032, Forecasting a 4.09% CAGR
By pmarketresearch, 2026-07-02
PW Consulting: Strategic Preview — LNG Market Outlook 2026 and Why This Report Will Shape Your Next 12–36 Month Decisions
Executive snapshot
PW Consulting’s new LNG Market report (base year 2025) delivers a compact, decision-centric synthesis designed for boardrooms, transaction teams, and strategy functions planning around 2026. The global LNG market that expanded from roughly USD 100 Billion in 2020 to USD 135 Billion in 2025 is projected to continue expanding into the next decade, with our base forecast showing a mid-single-digit compound annual growth rate (CAGR) of 4.09% over the 2026–2032 horizon. In plain terms: the market is large, resilient, and in active reconfiguration — and executives who align capital allocation, contracting strategy, and portfolio hedging to these dynamics in 2026 will materially influence outcomes through 2032.
LNG Market
Why 2026 is a strategic inflection
Two features make 2026 a pivotal year for corporate LNG strategy. First, policy and permitting dynamics that shifted in 2024–2025 have already altered capital flows and project run-rates. Second, a cluster of major project milestones and long-term commercial commitments reached in late 2025–early 2026 is changing near-term supply availability and contract structures. Those developments, combined with a stable-to-optimistic price environment for feedstock, create a narrow window in 2026 for organizations to lock in competitive advantage — whether through greenfield green-lighting, offtake renegotiations, or value-chain diversification.
LNG Market
Market trajectory: evidence-based but practical
Our historical analysis (2020–2025) and scenario-weighted forecast (2026–2032) quantify a market that has already demonstrated strong recovery and steady growth. Using 2025 as the base year, the market rises into 2026 before advancing through our forecast period; our deterministic baseline reaches an estimated USD 179 Billion by 2032 under the central scenario. The 4.09% CAGR we publish reflects aggregated demand, supply additions, and mid-term price assumptions aligned with current feedstock trends and recent policy movements.
LNG Market
- Historical trend: a robust rebound and market expansion between 2020 and 2025 underpin near-term confidence.
- Short-term inflection: 2026 is projected to be a year in which announced capacity and contractual flows materially influence the supply-demand balance.
- Medium-term outlook: by 2032 the market is substantively larger than the 2025 baseline, but pathway risk remains concentration on a handful of large projects and the evolution of trade/hydrogen policy frameworks.
What is changing on the ground (and what it means for decisions)
Four dynamics should drive board-level discussion in 2026:
- Permitting and policy normalization: The lifting of the U.S. pause on LNG export permits for non‑FTA countries in early 2025 reopened a major margin lever for North American supply. For offtakers and project sponsors, this reduces regulatory tail-risk but raises the bar on commercial discipline — projects that cannot demonstrate creditworthy offtake or robust shipping solutions will face tighter financing terms.
- Price and input stability: Henry Hub averaged around $3.50/MMBtu in 2026, a level that keeps many U.S. export projects commercially viable while allowing buyers to evaluate alternative sourcing at competitive landed costs. This feedstock backdrop favors sellers with trading capability and buyers that can structure flexible supply agreements.
- Fiscal and trade policy shifts: Recent national-level policy reversals on clean-tech subsidies have altered capital allocation patterns. Expect higher thresholds for green-premium projects and greater focus on absolute economics — decarbonization commitments will remain, but financing for incremental greenfield will be conditional on clear near-term returns or regulatory incentives.
- Project milestone clustering: Several marquee projects achieved major milestones in 2025–2026, shifting implied near-term capacity and bargaining power across the value chain. These milestones are reducing one dimension of supply uncertainty while accentuating competition for long-term demand contracts and skilled project execution resources.
Competitive landscape — who matters and how
Market concentration remains meaningful: the top three players account for roughly half of identifiable market influence (CR3 ≈ 50%), and the top five account for approximately 60% (CR5 ≈ 60%). That concentration shapes pricing power, contracting norms, and the structure of strategic partnerships.
Key archetypes and implications:
- Large integrated majors with trading platforms (e.g., Shell, ExxonMobil, TotalEnergies, BP, Chevron): These firms leverage global portfolios and advanced trading desks to optimize routing, arbitrate regional spreads, and offer flexible offtake structures. For corporates, partnering or contracting with these players often buys price-flexibility and credit reliability — at a premium.
- U.S.-based project specialists (e.g., Cheniere Energy, Venture Global): Focused players that own and operate liquefaction capacity in the U.S. have pushed the frontier on modularized build and scale. Their projects are central to short- to mid-term supply elasticity; counterparties should expect contract models that reflect seller-levered commercial terms unless buyers secure early-stage commitments.
- National oil companies and upstream-integrated exporters (e.g., Petronas): State-backed sponsors combine resource access with strategic long-term offtake ambitions. Their role is particularly important where projects link upstream gas developments to export capacity; these sponsors are natural partners for market-entry strategies in specific basins.
Recent developments that matter for 2026 decisions:
- Golden Pass LNG achieved first production in early 2026 — a structural addition that changes terminal availability and offtake timing.
- Major long-term commercial commitments were formalized in early 2026, including multi-decade export agreements that affect project cash-flow profiles.
- Large exporters reported record cargo and production statistics for 2025 — a sign of operational scale and a signal for suppliers and buyers about surplus capacity windows in the immediate term.
What the PW Consulting report contains — practical outputs for 2026 decision-makers
This is not a high-level narrative: the report delivers tactical tools executives can use in 2026. Highlights include:
- Proprietary market-sizing and sanity-check models (historical 2020–2025 and forecast 2026–2032) with transparent assumptions and sensitivity levers for feedstock price, shipping cost, and carbon pricing inputs.
- Scenario playbooks: three actionable scenarios (base, upside, downside) with triggers, impact matrices on contracted revenues, and recommended commercial responses per scenario.
- Deal-readiness checklists and contracting templates that accelerate FID conversations: term-length guidance, indexation options, and delivery-flex clauses structured to 2026 market realities.
- Project and counterparty heatmaps that rank projects and partners on execution risk, commercial attractiveness, and ESG exposure — designed to inform M&A and JV prioritization without disclosing sensitive segmentation datapoints directly in this release.
- Regulatory risk dashboard and mitigation playbooks: tailored to North American permitting shifts and recent trade policy changes that have altered subsidy regimes.
- Trading and hedging playbook for corporates entering short- to medium-term merchant exposure, calibrated to current Henry Hub dynamics and freight cost trajectories.
How to use this analysis in your 2026 planning cycle
For decision-makers preparing capital allocation, contracting, or M&A actions in 2026, the report is structured around three immediate uses:
- Investment gating: Use our scenario outputs and project heatmaps to decide which greenfield or brownfield opportunities clear your internal return threshold under multiple market settings.
- Commercial structuring: Apply the contracting templates and pricing sensitivity models to design offtake terms that balance price certainty with optionality, and use our negotiation playbooks to improve counterparty outcomes.
- Portfolio hedging and trading: Adopt the hedging frameworks to protect margin in an environment where mid-term supply additions and policy shifts can produce localized volatility.
What we intentionally withhold here (and why)
In keeping with the “trailer” principle, this release demonstrates analytical depth while deliberately withholding granular segmentation tables, region/application percentage splits, and detailed project-level cash flows. Those elements are central to transaction execution and competitive positioning; releasing them publicly would blunt the strategic advantage that subscribing clients receive. The full report and accompanying datasets provide these confidential details, model files, and executable negotiation playbooks.
Concluding recommendation
2026 presents a compressed window in which regulatory normalization, new project start-ups, and evolving fiscal frameworks create both opportunity and execution risk. Executives who move early — leveraging scenario tests, targeted contractual flexibility, and selective partnering with major integrated players or project specialists — will be able to secure advantaged positions before market signals fully propagate.
PW Consulting’s LNG Market report is designed to convert market intelligence into executable decisions: not only to explain what is happening, but to tell you precisely how to act in 2026 to influence outcomes through 2032. For access to the full dataset, project-level analysis, and client-only advisory options, contact PW Consulting’s Energy Practice to request the full report and set up a tailored briefing.
For detailed analysis of this topic, please visit the official page: LNG Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Palm Kernel Shell (PKS) Market to Grow at 6.0% CAGR, Reaching USD 1,879.5 Million by 2032 as Asia‑Pacific Dominates
By pmarketresearch, 2026-07-02
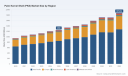
Palm Kernel Shell (PKS) Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
Executive summary
PW Consulting’s latest Palm Kernel Shell (PKS) Market report — based on a 2025 base year and a historical window covering 2020–2025, with a forecast period of 2026–2032 — provides pragmatic, board-level and operational intelligence for energy buyers, biomass processors, trading houses, and strategic investors preparing decisions in 2026. Our model values the global PKS market at USD 1,250.0 Million in 2025 and anticipates growth to approximately USD 1,879.5 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.0% over the forecast window. The market exhibits moderate concentration (CR3 ≈ 42.5%; CR5 ≈ 58.2%), creating both competitive tensions and opportunities for scale plays.
Palm Kernel Shell (PKS) Market
Why this matters for 2026 decision-makers
PKS is shifting from a residual-byproduct to a traded bioenergy commodity with role-specific pricing dynamics, certification complexity, and logistics-driven margins. In 2026, energy transition targets, tightening procurement requirements in key importing markets, and trade/regulatory moves in supply countries are converging to create discrete windows for differentiated strategy. PW Consulting’s brief synthesizes macro sizing, market structure, supply-side readiness, and regulatory inflection points into a pragmatic playbook: the base math is established (steady mid-single-digit CAGR), the competitive map is observable, and the levers that will determine who captures value in 2026 are actionable.
Palm Kernel Shell (PKS) Market
Market dynamics — what’s changing right now
-
Demand trajectory: The global PKS market has demonstrated resilient expansion through 2025 and our forecast anticipates continued steady growth at roughly 6.0% CAGR to 2032. This is driven by ongoing demand from biomass power generation and industrial thermal applications as operators seek lower-carbon, cost-competitive fuel blends.
Palm Kernel Shell (PKS) Market -
Certification & market access: Importer-side environmental verification is now a procurement gate. Notably, Japan’s market has tightened third-party certification requirements for feed-in-tariff eligibility, elevating the commercial value of certified PKS and increasing the premium for suppliers who can demonstrate chain-of-custody compliance under recognized schemes.
-
Supply-side policy: Export taxation and levies in key producing countries are shaping trade flows and landed costs. Policy packages introduced into 2026 have a measurable effect on arbitrage and sourcing optimization for buyers and traders.
-
Industrialization of processing: Suppliers are investing in staged processing (screening, drying, pelletizing) and port-centric covered stockyards to reduce moisture/contaminant risk and provide consistent calorific quality — an operational differentiation increasingly rewarded by buyers focused on boiler reliability and emissions compliance.
Competitive landscape — practical takeaways
The PKS supply ecosystem includes integrated palm groups, specialist biomass processors, and trading aggregators. The competitive fabric blends upstream control (mill-by-mill sourcing) with midstream processing and downstream logistics capability. Our analysis of market participants yields three strategic archetypes:
-
Integrated originators: Major palm groups leverage mill networks to recover PKS as an energy feedstock. Their advantages are scale, visibility into raw availability, and the option to internalize use in captive power plants. These players are attractive partners for off-take arrangements where reliability and sustainability disclosures matter.
-
Specialist processors and exporters: Companies that invest in drying, screening, pelletization, and port-side facilities can deliver a more commoditized, quality-assured product to premium markets. Recent facility launches and MOUs point to an industry pivot where processed PKS commands higher access to the Japanese and other certified markets.
-
Regional aggregators and traders: Firms that stitch supplies across mills and geographies by offering flexible delivery, blended quality profiles, and third-party compliance documentation are increasingly critical for markets with complex regulatory regimes.
Representative companies span these archetypes and include vertically integrated palm producers, specialist biomass suppliers with port-side handling and quality-control capabilities, and global traders that facilitate flows to thermal power and industrial consumers. The report provides company-by-company profiles, recent strategic moves, and a comparative assessment of capability gaps — all framed to help buyers and investors prioritize counterparties for 2026 engagements.
Recent developments that change the 2026 playing field
-
Trade promotion and market demand signals: Industry association participation in major biomass expos and bilateral forums has reinforced Japan’s role as a high-volume importer and a trendsetter on certification demand.
-
Capital projects: New biomass processing capacity brought online in 2026 — including medium-to-large capacity processing plants located close to export ports — materially strengthens exportable quality PKS supply and shortens order-to-delivery lead times for premium markets.
-
Policy tailwinds and headwinds: Export levy structures in origin markets affect landed price models, while importer-side certification rules create differentiation for suppliers who have invested ahead of regulatory curves.
Operational implications and tactical playbook for 2026
Below are practical steps we advise by role to capture value and manage risk in 2026:
-
For energy buyers and utilities:
- Prioritize counterparties with third-party certification capability and documented calorific/moisture quality assurance; this materially reduces boiler operational risk and protects tariff eligibility in certified markets.
- Structure flexible multi-sourcing contracts with port-centric delivery options and short-notice volume adjustments to hedge origin-policy shocks.
-
For biomass processors and suppliers:
- Invest selectively in staged processing (screening, low-moisture stockyards, modular drying) near port hubs to capture premium differentials. Operational improvements often yield outsized margin uplift relative to incremental CAPEX.
- Obtain and actively maintain recognized sustainability certifications — the market for certified PKS will command better pricing and lower commercial friction in key import markets.
-
For trading houses and aggregators:
- Develop logistics and financing packages that address payment terms, quality guarantees, and documentary compliance for certifications; bundling these services de-risks transactions for large buyers.
-
For investors and strategic acquirers:
- Target assets that combine origin control (sourcing) with processing and port-handling capabilities — these horizontally integrated models are likely to capture the margin between raw recovery and premium certified product supply.
- Assess exposure to origin policy risk and the elasticity of demand in key importing markets; value-accretive acquisitions are those that shorten the certification and logistics pathway to premium buyers.
Key risks and how to mitigate them
-
Policy risk: Export levies and changing tariff regimes in origin countries can compress arbitrage. Mitigation: diversify sourcing across suppliers and negotiate contract clauses that share policy-change impacts.
-
Certification and market access risk: Tighter importer certification requirements can morph demand patterns quickly. Mitigation: invest early in recognized certifications and traceability systems; prioritize counterparties with established third-party verification.
-
Quality & logistics risk: Moisture, foreign materials, and inconsistent sizing increase boiler downtime and penalties. Mitigation: specify strict acceptance testing, insist on port-side covered storage where feasible, and adopt moisture-hedging clauses in contracts.
What the PW Consulting report contains (practical utility)
The full PW Consulting PKS report is designed as an operational playbook for 2026 decision cycles. It includes:
- Time-series market sizing and a transparent model of demand drivers (historical 2020–2025 plus forecast 2026–2032).
- Concentration analysis and an assessment of competitive dynamics across supplier archetypes.
- Company profiles with capability matrices covering sourcing, processing, certification, port handling, and commercial reach.
- Trade-flow and landed-cost scenarios under alternative policy and cost shocks.
- Actionable procurement templates, due-diligence checklists for counterparties, and a 12–36 month strategic roadmap keyed to different corporate objectives (cost leadership, secured supply, certified supply for premiums).
To preserve the strategic value of proprietary segmentation and transaction-level pricing, this brief intentionally omits the granular regional and application-level breakdowns that are in the full report. Those detailed splits, including modeled scenarios and supplier-level exposures, are available in the complete PW Consulting package.
Concluding recommendation — a 90-day decision agenda
- Immediate (0–90 days): Audit your PKS exposure, confirm certification needs for your target markets, and run a supply continuity stress test under origin levy scenarios.
- Near-term (3–12 months): Secure medium-term offtake or call-off arrangements with suppliers who can demonstrate certified chain-of-custody and port-based moisture control; consider minority investments in processing capacity where strategic.
- Medium-term (12–36 months): Consolidate supplier relationships, integrate traceability systems, and, if pursuing growth, evaluate M&A targets that close sourcing-to-port capability gaps.
Next steps
PW Consulting’s PKS Market report equips commercial leaders with the quantitative sizing, concentration metrics, and tactical playbooks to make informed procurement, investment, and partnership decisions in 2026. For stakeholders who require the full regional and application segmentation, supplier exposure tables, and scenario-modeled price impacts, please consult the complete report on our website or contact our team to arrange a briefing and tailored scenario run.
For detailed analysis of this topic, please visit the official page: Palm Kernel Shell (PKS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting forecast: Short‑Range Air Defense market poised for 6.38% CAGR, reaching USD 34,689.86 Million by 2032
By pmarketresearch, 2026-07-02
Short Range Air Defense Systems Market: Strategic Imperatives for 2026 — PW Consulting Insights
Why this report matters for decision-makers in 2026
As armed forces and security architects recalibrate force posture for the coming decade, Short Range Air Defense (SHORAD) systems have moved from niche capability to operational imperative. PW Consulting’s new market research brief synthesizes five years of historical data and a multi-scenario forecast to deliver a clear, actionable view of the market entering 2026. Our analysis places the global SHORAD market at USD 22,500 Million in the base year (2025) and models a compound annual growth rate (CAGR) of 6.38% across the 2026–2032 forecast window, with a directional market value approaching USD 34,690 Million by 2032 under the central case. These macro signals are decisive for procurement planners, program managers, supply-chain strategists, and investor due diligence teams preparing budgets, partnerships, and production ramps in the year ahead.
Short Range Air Defense System Market Research
Executive summary: what strategic choices 2026 will force
-
Scale versus specialization. A sustained mid-single-digit CAGR signals growing demand, but the market remains partially concentrated — the top three vendors account for a meaningful share, and the top five capture a majority of industry revenues — creating space for specialized challengers and focused subsystem suppliers.
Short Range Air Defense System Market Research -
Modernization pressure. Nations are accelerating procurement of mobile, integrated short-range layers to counter swarms, loitering munitions, and increasingly autonomous air threats. Procurement cycles in 2026 will favor platforms that demonstrate integration maturity across sensors, interceptors, and command-and-control.
Short Range Air Defense System Market Research -
Industrial preparedness. The jump from prototype to production will be constrained not only by engineering but by industrial base readouts — supplier capacity, component lead times, and production-rate frameworks negotiated with defense ministries.
What the PW Consulting report delivers — pragmatic, transaction-ready intelligence
-
Market sizing and validated forecasts: a 2020–2025 historical baseline, a detailed 2026–2032 central forecast, and upside/downside scenario paths linked to geopolitical and budgetary triggers.
-
Procurement pipelines and tender watch: a prioritized tracker of national procurement programs, including near-term award windows and likely contract vehicles that will be decisive in 2026 procurement cycles.
-
Buy-side decision playbooks: tailored guidance for defense ministries outlining evaluation criteria, integration test sequences, sustainment commitments, and negotiation levers to shorten fielding timelines.
-
Supplier and subsystem heatmaps: capability benchmarking across missile interceptors, gun systems, sensors, fire-control, and vehicle integration — identifying where suppliers can command margin premiums through proven system-of-systems integration.
-
Supply-chain risk matrix: component tightness analysis (semiconductors, propulsion, EO/IR sensors), configurable mitigation options, and near-term red flags for manufacturing scale-ups.
-
Commercial scenarios for OEMs and tier‑1s: pricing and margin model frameworks, production-rate stress tests, and partnership archetypes for co-development and technology-transfer constrained by export controls.
-
Customizable board-level briefings and live Q&A: actionable deliverables to support investment committees, business unit planning, and rapid go/no-go decisions for 2026 contract pursuits.
Competitive landscape — who matters and why
The SHORAD market is populated by legacy prime contractors and regional specialists, each pursuing different value propositions: integrated multi-domain networks, mobile turreted cannons, lightweight man-portable interceptors, or sensor-and-C2-centric architectures. Our competitive benchmarking synthesizes public program affiliations, platform offerings, and differentiated capabilities to produce decision-grade vendor profiles.
-
RTX Corporation (Raytheon) and Kongsberg — combining networked interceptors and mature C2 for high-confidence engagements. RTX’s recent ballistic test successes for next‑generation interceptors underscore a technology-forward posture that is influencing procurement risk appetites in allied armies.
-
Lockheed Martin — leveraging deep systems integration and flight-test progress on next-generation interceptors to compete for maneuver SHORAD programs where certified munitions and integration roadmaps shorten field timelines.
-
Rheinmetall — a frontrunner in automatic cannon-based mobile SHORAD whose program momentum with major national buyers highlights the demand for highly mobile, vehicle-mounted air defense packages.
-
MBDA, Saab, Thales, Leonardo — European specialists that combine missile design, radars, and modular C2 to appeal to regional blocs prioritizing sovereign supply chains and interoperability within alliance frameworks.
-
Rafael, IAI, and Elbit Systems — Israeli firms emphasize rapid adaptation to active threats, demonstrated by recent test programs and export framework agreements that focus on layered protection across short and very-short ranges.
-
Northrop Grumman, BAE Systems, Hanwha, ASELSAN, Kongsberg — these players either bring C2 strengths, vehicle integration expertise, or emerging indigenous SHORAD solutions relevant to buyers balancing cost, sustainment, and quick-reaction capability.
-
L3Harris — a critical supplier in propulsive components and sub-systems who shapes interceptor availability through industrial supply agreements.
Recent developments that reshape the 2026 decision calculus
-
Flight and ballistic testing activity in early 2026 has validated multiple next-generation interceptor concepts, reducing technology risk for fielding programs and tightening windows for competitive bids.
-
Major national program plans and framework agreements announced in 2024–2025 signal a near-term uplift in orders for mobile SHORAD platforms — a structural demand driver our scenarios quantify and stress-test for capacity planning.
-
Export-control regimes and allied procurement networks continue to channel capability flows into partnership clusters. This dynamic both protects IP for originators and creates barriers to purely commercial entrants without sovereign teaming arrangements.
-
Supply-side policy moves to accelerate munitions production are altering prime-contractor manufacturing economics, making scale a competitive differentiator for players able to secure long-term component supply agreements.
Implications for 2026 procurement, investment, and industrial strategy
-
For primes: pursue partnerships that combine turreted effectors, sensor suites, and seamless C2. Integration speed will outcompete point improvements in many procurement competitions.
-
For subsystem suppliers: prioritize design-for-integration and modularity to be selected into long-term sustainment packages; consider dual-sourcing strategies to mitigate supplier concentration risk.
-
For nation-states and procurement authorities: use the report’s tender watch and maturity matrices to structure staged contracts that de-risk capability deliveries while preserving sovereign industrial participation.
-
For investors and M&A strategists: the market’s mid-single-digit CAGR coupled with concentrated share among the top firms creates specific arbitrage opportunities for technology-led niche players that can plug into prime platforms.
Scenario insights: how 2026 choices alter the 2032 outcomes
Our central forecast — reflecting an aggregate CAGR of 6.38% — yields a near-term pathway where increased procurement of mobile SHORAD assets and incremental interceptor modernization maintain steady market expansion through 2032. Under downside scenarios (fiscal tightening, slowed exports), growth compresses; under upside scenarios (accelerated force modernization or conflict-driven procurement surges), the market expands materially faster and stresses supply chains. PW Consulting’s scenario suite ties these outcomes to concrete indicators — budget amendments, export policy shifts, technology qualification milestones — enabling decision-makers to map early-warning signals to contingency plans.
Why PW Consulting’s analysis is different
-
Action-first research: every chart and forecast is paired with an operational recommendation — whether to hedge capacity, pursue a particular partnership architecture, or stagger contract milestones to de-risk delivery.
-
Triangulated methodology: we combine procurement pipeline reconstruction, vendor interviews, program-level cost proxies, and macro demand drivers to produce forecasts rooted in observable contracting behavior.
-
Commercially usable outputs: from a competitive heatmap to a supplier-risk register and a procurement playbook, the report is designed to be integrated directly into program planning and boardroom debates.
Trailer: what we intentionally withhold — and why
To preserve the report’s utility for subscribers and protect commercially sensitive modeling elements, we intentionally do not publish detailed segmentation tables and regional split values in this release. The granular breakdown by component, platform, country-specific procurement timetables, and per-contract unit economics are included in the full PW Consulting report and are available through our client portal. This “trailer” approach ensures the public synopsis communicates strategic judgment without revealing transaction-level intelligence that buyers and suppliers rely upon in negotiation contexts.
Next steps — how to use this insight in 2026
-
Schedule a tailored briefing: our strategic analysts will walk procurement teams or investor committees through scenario triggers and supplier-specific recommendations relevant to prioritized award windows.
-
Request the detailed annexes: available to purchasers, these include the tender watch, supplier scorecards, and our scenario-adjusted demand curves that map directly to production-rate planning.
-
Engage our advisory team for implementation support: from drafting acquisition RFP language to structuring industrial participation clauses, we help operationalize the intelligence for decisive action.
Contact PW Consulting to access the full Short Range Air Defense Systems Market Research report, schedule a briefing, or commission a customized study aligned with your 2026 business or government planning cycle. The window to translate validated market visibility into program wins is narrow — our work is designed to help you make those 2026 choices with confidence.
For detailed analysis of this topic, please visit the official page: Short Range Air Defense System Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com