

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 6.82% CAGR for PHS Resin in KrF Photoresist Market Through 2032

PHS Resin for KrF Photoresist Market — Strategic Outlook for 2026 Decision‑Makers
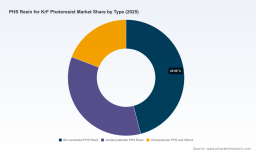
PW Consulting’s new market brief on PHS (polyhydroxystyrene) resins for KrF (248 nm) photoresists provides a focused intelligence product designed to inform capital allocation, sourcing strategies, and M&A choices in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the report positions the global market (base year 2025) at approximately USD 300.6 Million and models growth to 2032 under a compounded annual growth rate (CAGR) of 6.82%. Those headline figures understate an important nuance: while the headline market expands steadily, supply-side concentration, raw‑material dynamics, and regulatory pressure create asymmetric risks and strategic opportunities that require active management this year.
PHS Resin for KrF Photoresist Market
Why this matters for 2026 planning
- Supply security is strategic. PHS-based KrF resins remain critical inputs for mature-node logic, certain memory applications and advanced packaging lithography. Market concentration is high: the three largest suppliers account for a dominant share of production, and the top five approach near-total market control. For buyers, this creates single-supplier risk that materializes quickly under capacity disruptions or rapid demand re-profiling.
- Macro growth masks micro volatility. A mid-single-digit CAGR to 2032 signals a healthy, predictable market overall, but pockets of rapid capacity build-out and domestic substitution—especially in APAC—produce episodic swings in availability, pricing and qualification lead times. Tactical agility in 2026 will out‑perform static long-term plans.
- Raw inputs and cost pressure are real. Industry tracking shows global production of PHS resin for KrF photoresists reached roughly 321 tons in 2024, with an average market price near US$575/kg. These inputs carry material cost and inventory implications for formulators and OEMs, particularly as feedstock and specialty monomer availability can fluctuate with petrochemical cycles.
What our report delivers (operational, purchase‑ready intelligence)
The brief is structured as a toolkit for executives setting 2026 priorities. Highlights include:
PHS Resin for KrF Photoresist Market
- Actionable market sizing and scenario modeling — base year 2025 and an IT‑grade forecast to 2032 (including sensitivity testing for demand shocks, substitution waves and regulatory uplifts).
- Supply‑chain heat maps — mapped upstream feedstocks, synthesis bottlenecks, qualification timelines, and time-to-volume for new resin chemistries.
- Supplier scorecards — qualitative and quantitative assessments across technology maturity, capacity footprint, geographic risk, and qualification velocity (full share tables and granular supplier metrics are available in the full report).
- Regulatory and sustainability playbook — impact analysis of PFAS-related developments, hazardous substance trends and compliance pathways for chemically amplified resist systems that use PHS base resins.
- Commercial playbook for buyers and investors — sourcing strategies (dual‑sourcing, toll manufacturing options, consignment), contracting levers (price collars, volume-flex terms), and JV/partner evaluation criteria.
- M&A and capacity investment guidance — a prioritized short list of acquisition and greenfield targets, with decision trees for quick-win vs. long-term integration plays.
Competitive landscape — who matters and why
The PHS-for-KrF arena is populated by three strategic cohorts: established global specialty chemical houses (legacy Japanese and Western players); fast‑scaling domestic Chinese suppliers; and specialized regional producers targeting niche formulation requirements. Key industry participants profiled in the report include long‑standing resin and resist manufacturers and several emerging local contenders:
PHS Resin for KrF Photoresist Market
- Nippon Soda Co., Ltd. — long experience supplying high‑purity PHS derivatives and recognized for stable qualification pathways with tier‑1 resist formulators.
- Maruzen Petrochemical Co., Ltd. — established PHS lines targeted at KrF base polymers with reliable product performance histories.
- Shin‑Etsu Chemical Co., Ltd. — a major lithography material supplier with integrated capabilities across protected PHS systems for KrF resists.
- DuPont de Nemours, Inc. — a global formulators’ scale player that recently increased KrF photoresist manufacturing capacity, reinforcing its role as a strategic supplier to semiconductor fabs and foundries.
- Tokyo Ohka Kogyo Co., Ltd. (TOK) and TOHO Chemical Industry Co., Ltd. — both provide technology‑intensive resist systems and have long product pedigrees in PAG‑driven chemistries.
- Chinese innovators — several firms (including Bayi Space LCD, Tongcheng New Materials, WEIMAS and others) are moving from pilot to ton‑scale supply, accelerating domestic substitution and lowering qualification barriers for local formulators.
What these dynamics mean: incumbent suppliers continue to exert pricing and qualification discipline, but new entrants are reducing barriers to entry in predictable product bands (pilot‑to‑hundred‑kg scale moving toward hundred‑ton capacities). Buyers that treat supplier engagement as a binary choice (single dominant vendor vs. generic market) will miss opportunities to secure cost advantage and mitigate disruption.
Recent developments to watch (signal vs. noise)
- DuPont’s incremental capacity expansion in Japan (2024) materially increases available KrF photoresist throughput and shortens lead times for formulators that have long qualification relationships with the company.
- Several Chinese firms have progressed pilot runs to hundred‑kg scale and signalled hundred‑ton expansions under construction; these moves are meaningful for regional sourcing strategies and for fabs targeting domestic supply chains.
- Regulatory exploration of PFAS alternatives in chemically amplified resists continues, but no full performance replacement for current PAG‑enabled KrF chemistries has been broadly validated — meaning compliance cost and disclosure risk are material but substitution risk is still emergent.
Strategic imperatives for 2026
Our fieldwork and financial modeling point to a short list of high‑leverage actions executives should prioritize in 2026:
- Lock in flexible supply agreements. Negotiate contracts that combine minimum commitments with scalable options and performance milestones. Where possible, secure qualification slots with at least two approved resin sources to avoid single‑node failure exposures.
- Invest in qualification pipelines. Time-to‑qualified‑supply is the dominant operational lead time. Devoting engineering resources and co‑development funding to shorten qualification cycles (material matching labs, joint reliability testing) yields outsized near‑term benefits.
- Pursue targeted partnerships with upstream producers. Equity investments, tolling arrangements, or long‑term supply‑for‑off‑take deals with mid‑tier producers can lock in cost advantage and provide optionality versus competition for incumbent capacity.
- Hedge raw material exposure tactically. Given observed price points and the limited global tonnage of PHS, buyers should model variable‑price scenarios and consider inventory hedges or strategic buffer stocks for critical launches.
- Plan for PFAS‑driven compliance costs. Even absent a full substitution, evolving regulation will impose documentation, testing and potential reformulation costs. Incorporate these into 2026 product and R&D roadmaps now to avoid last‑minute tradeoffs.
- Make data‑driven M&A choices. Prioritize targets that offer rapid qualification capabilities, complementary geographies, and controllable capital intensity rather than chasing scale alone.
Risk matrix and monitoring priorities
For 2026 decision cycles we recommend ongoing monitoring in four domains:
- Capacity movements: new plant commissioning, expansions, and qualification throughput of emerging suppliers;
- Regulatory signals: changes in hazardous substance rules, PFAS policy updates, and regional reporting requirements;
- Feedstock volatility: monomer availability, petrochemical feedstock cycles and substitution pressure from ArF/EUV process migration in adjacent product families;
- Customer qualification timelines: measured lead times from sample to production acceptance, which remain the practical gating factor for converting availability into revenue.
How PW Consulting’s brief supports your 2026 playbook
The value proposition of this deliverable is immediate: it provides commercial leaders and strategy teams a compact, actionable evidence base to accelerate decisions this year. The report synthesizes supplier intelligence, scenario financials, and a procurement playbook into a format that can be operationalized by sourcing, product and corporate development teams within 90 days.
Note: this public summary is intentionally selective. The full report includes granular supplier scorecards, a downloadable financial model, scenario outputs for demand shocks and substitution paths, and a prioritized list of acquisition targets and partnership metrics. Those details are gated to ensure strategic confidentiality and to preserve the competitive value of the contained intelligence.
Next steps
If your 2026 plan includes CAPEX allocation, M&A pursuit, new fab ramps, or a supplier renegotiation cycle for KrF photoresist materials, schedule a briefing with PW Consulting. Our analysts can run an on‑demand sensitivity sweep using your specific demand profile, map the fastest supplier qualification pathway, and provide the procurement template your sourcing team needs to execute within Q3–Q4 2026.
To access the full market model, supplier share matrix, and tactical playbooks, please visit the official report page linked in this release. PW Consulting’s team is available to customize the findings to your organization’s risk tolerance, regional exposure, and product roadmaps.
For detailed analysis of this topic, please visit the official page: PHS Resin for KrF Photoresist Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com