

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Carboxymethyl Tamarind Gum Market to Rise from USD 18.5 Million in 2025 to USD 28.74 Million by 2032 at a 6.49% CAGR, Led by Asia‑Pacific
By pmarketresearch, 2026-07-02
Carboxymethyl Tamarind Gum (CMT) Market — Strategic Briefing for 2026 Decision Makers
Executive preview
PW Consulting’s new market study on Carboxymethyl Tamarind Gum (CMT) consolidates five years of historical observation (2020–2025) and a seven‑year forecast (2026–2032) into a decision-grade intelligence package for commercial, procurement and corporate development leaders. The global market — tracked in USD Million — expanded from an estimated 13.5 in 2020 to 18.5 in our 2025 base year, and is projected to surpass 20.2 in 2026 on the way to approximately 28.7 by 2032. The forecast period carries a compound annual growth rate (CAGR) of 6.49% for 2026–2032. At a concentration level where the top three players account for roughly 38.4% of supply and the top five for about 52.2%, this is a market where mid‑sized incumbents and nimble newcomers can create outsized commercial returns if they move strategically.
Carboxymethyl Tamarind Gum (CMT) Market
Why this report matters in 2026
- Turn market momentum into commercial advantage: The growth trajectory shows stable demand expansion across legacy and adjacent applications; the question for 2026 is what moves will unlock margin expansion, not whether demand exists.
- Risk‑aware sourcing in a raw‑material‑centric supply base: India remains the primary origin of tamarind seed feedstock, and raw‑material dynamics (production, quality, logistics) are the single largest determinant of near‑term cost volatility.
- Concentration creates both opportunity and constraint: With moderate CR3/CR5 metrics, well‑timed M&A or offtake agreements can materially shift supplier economics — but they require granular supplier intelligence and scenario modelling to avoid overpaying for transient advantages.
- Regulatory and product‑grade stratification is decisive: Recognition of tamarind kernel powder in manufacturing contexts lowers a regulatory barrier for industrial uses, while higher‑value purified grades open doors to cosmetics, pharma and premium personal‑care segments.
What’s inside the report — operational modules that support 2026 programs
- Executive decision memo: concise scenarios (base, upside, downside) and recommended plays for procurement, product and M&A teams.
- Top‑level market model: annualized historical series and forecast to 2032 (USD Million), with driver decomposition (volume, price, grade mix) and sensitivity levers.
- Price and margin simulator: inputs for raw‑material cost, conversion yield and conversion economics by grade to stress‑test sourcing choices.
- Supply‑chain map and heat‑map: origin nodes, processing steps, logistics chokepoints and a risk index tied to seasonality and policy scenarios.
- Competitive scorecards: capability matrices for leading manufacturers, distributors and specialty processors (capex, grade portfolio, export footprint, technical service capability).
- Product & formulation playbook: application profiles for textile, paper, industrial and high‑purity segments, including formulation parameters, pilot protocols and scale‑up checklists.
- Commercial playbook: channel strategies, distributor economics, tender templates and win/loss playbooks for upstream and downstream commercial teams.
- M&A and partnership shortlist: validated targets and integration risk assessment with modeled synergies and payback horizons.
- Regulatory matrix and compliance checklist: mapped to food, industrial and cosmetic use cases, with incremental compliance steps for purified grades.
Note: The full dataset, vendor scorecards and line‑item segmentation detail are available in the complete report to support transaction execution and contract negotiation. This release is intentionally selective — a precise preview rather than exhaustive disclosure.
Carboxymethyl Tamarind Gum (CMT) Market
Market dynamics and strategic implications
Three structural forces drive the CMT market in 2026: raw‑material geography and seasonality; grade bifurcation between industrial and purified applications; and continuing demand resilience in textile printing alongside incremental uptake in technical industrial uses.
Carboxymethyl Tamarind Gum (CMT) Market
On raw materials: India remains the dominant source of tamarind kernel feedstock, producing on the order of several hundred thousand tonnes of tamarind annually. That concentration yields cost advantages for regionally integrated processors but introduces single‑country risk. Buyers and processors should plan for weather‑driven supply variability, upstream quality swings and logistics disruptions during peak harvest season. Practical mitigations include multi‑tier offtake agreements, inventory optimization calibrated to seasonality, and selective investment in on‑shore processing to shorten critical lead times.
On product grades: CMT is not a monolith. The industry differentiates between technical/industrial grades used as textile thickeners, paper sizing agents and drilling/binder additives, and higher‑purity grades that address cosmetics, personal‑care and pharmaceutical adjacencies. Achieving and certifying purified grades requires additional process steps (seed selection, coat removal, milling, sieving and controlled chemical modification), which create higher entry barriers but also wider margin pools for firms that can operationalize consistent quality and regulatory compliance.
On demand patterns: Textile printing continues to anchor demand, particularly where reactive and disperse dye systems require stable, high‑viscosity thickeners with excellent wash‑off and color‑fastness characteristics. Meanwhile, the product’s cold‑water solubility and rheology profile are opening new use cases in energy‑sensitive industrial processes and water‑sensitive paper applications. Buyers should quantify the uplift potential from specialty grades and consider product stewardship and sample support as differentiators in commercial negotiations.
Competitive landscape — tactical read on core suppliers
- Indian Hydrocolloids — A leading manufacturer and exporter with a clear focus on customizable grades and broad pH/temperature stability. Strategic posture: premium, service‑oriented supplier with the capacity to win technical partnerships for textile and oil‑field formulations.
- Adachi Group — Known for cost‑competitive textile‑grade thickeners, with emphasis on color fastness and wash‑off. Strategic posture: volume player that competes on consistency and pricing; attractive as a volume partner or OEM supply source.
- Sudev International — Focused on high‑viscosity grades and international quality standards. Strategic posture: niche supplier for customers requiring defined rheological windows and documented performance.
- Chhaya Industries — Specialist in high‑viscosity CMT grades for synthetic fiber printing; strong in technical service and filterability performance. Strategic posture: technology‑led supplier useful for pilot collaborations where processability matters.
- Other regional producers and distributors (including Premcem, Altrafine, Shivam, Mahesh Agro, Mysore Starch, Wego, Riverland, Allwyn, Creative Polymer and DHN International) form a competitive ecosystem of integrated manufacturers and merchant distributors. Strategic posture: diverse — from upstream agricultural integration to global distribution networks that can accelerate market entry for downstream formulators.
For buyers and investors, the immediate takeaway is clear: segment suppliers by capability (commodity vs specialty), then define sourcing and partnership strategies accordingly. A blended approach — strategic partnerships for specialty grades and competitive tenders for commodity volumes — typically minimizes total cost of ownership while preserving access to innovation.
2026 strategic playbook — prioritized actions
- Conduct an immediate 90‑day supply risk audit: map top‑tier suppliers, assess seasonality exposure, and secure 12–18 month conditional offtake terms to buffer near‑term volatility.
- Establish a product‑grade roadmap: identify a short list of high‑value purified grades that align with existing customers or attractive adjacent markets (cosmetics, pharma) and define pilot‑to‑scale timelines.
- Negotiate capability‑anchored partnerships: prioritize suppliers that offer technical service, customized grades and co‑development arrangements rather than purely transactional pricing.
- Model M&A and JV scenarios using concentration metrics: use CR3/CR5-informed valuations to identify targets where synergies are operationally credible (capacity expansion, raw‑material control, or entry into higher‑margin segments).
- Implement sustainability and traceability actions: build simple, auditable chain‑of‑custody mechanisms for tamarind feedstock to support customer sustainability commitments and de‑risk reputation exposure.
- Deploy KPIs and early‑warning indicators: raw‑material inventory days, conversion yield variance, grade‑specific rejection rates and net landed cost per functional kilo will highlight margin pressure before it erodes profitability.
Concluding guidance
The CMT market in 2026 is neither a niche curiosity nor a mature commodity with a single playbook. It is a mid‑growth specialty chemical market shaped by agricultural upstreams, process chemistry and application‑level differentiation. For organizations that pair disciplined supply‑chain tactics with a selective product innovation agenda, there is a clear path to premium returns.
PW Consulting’s full Carboxymethyl Tamarind Gum (CMT) Market Report contains the detailed models, supplier scorecards, playbooks and forensic risk scenarios required to execute these strategies. This briefing is a strategic trailer — it demonstrates the rigor and operational focus of our analysis while preserving the dataset and transaction playbooks that enable execution. To access the full report, proprietary vendor matrices and our consulting engagement options, please visit PW Consulting’s market reports portal or contact our strategy team to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Carboxymethyl Tamarind Gum (CMT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electronic Plastic Enclosure Market to Expand from USD 6.25B in 2025 to USD 9.4B by 2032 at a 6% CAGR — Asia‑Pacific Leads with USD 2.67B in 2025
By pmarketresearch, 2026-07-02
Electronic Plastic Enclosure Market 2026: Strategic Imperatives for Manufacturers, OEMs and Investors
PW Consulting’s newest market briefing on Electronic Plastic Enclosures draws a clear line from data to decision for 2026. The global market — sized at USD 6,248.5 Million in our 2025 base year — is forecast to grow at a steady compound annual growth rate (CAGR) of 6.0% through our 2026–2032 horizon, reaching roughly USD 9.4 Billion by 2032. That macro trajectory masks a highly dynamic competitive and supply-side environment. This release summarizes the report’s strategic value, the practical intelligence inside, and the near-term plays companies should consider as they prepare budgets, product roadmaps, and M&A pipelines for 2026.
Electronic Plastic Enclosure Market
Why this report matters for 2026 decision cycles
-
Actionable market sizing to set realistic topline targets: Executive teams and corporate development groups gain a defensible baseline and growth runway for budgeting and valuation work.
Electronic Plastic Enclosure Market -
Supply-side risk mapping linked to pricing scenarios: Raw material volatility and trade policy are already shifting cost structures; the report translates those shifts into margin and capex planning implications.
Electronic Plastic Enclosure Market -
Regulatory and sustainability readiness: New reporting and chemical-content standards are not future hypotheticals — they are procurement and product-design constraints to be managed this year.
-
Competitive playbooks and M&A priority lists: We convert market structure and capability gaps into prioritized actions — product development, capacity moves, and bolt-on acquisition criteria.
What the report delivers (practical components)
-
Comprehensive market sizing and a seven-year forecast (2026–2032) with base-year 2025 alignment for reconciliation to internal plans.
-
Segmentation by material (ABS, polycarbonate, polyamide, PVC, and other high-performance polymers), by application (consumer, industrial, automotive, telecoms, medical), and by region — with methodology and sensitivity testing. Note: this press summary highlights strategic observations only; detailed subsegment tables and downloadable data packs are available in the full report.
-
Price and cost modeler: a scenario tool that converts raw material price moves and manufacturing mix into unit-cost and margin outcomes, including break-even curves for tooling vs. soft-tool/rapid-turn approaches.
-
Supply-chain resilience matrix: supplier concentration scores, nearshoring potential, dual-sourcing checklists, and actionable mitigation steps for tariff exposure and logistics disruption.
-
Regulatory and materials compliance playbook: templates for EHS engineering, materials declarations (to support compliance such as national registry requirements), and verification pathways for market claims (e.g., chemical-content limits).
-
Competitive benchmarks and capability heatmaps: product portfolios, manufacturing footprints, customization capabilities, and go-to-market models for leading players.
-
M&A and partnership thesis: prioritized target profiles, valuation logic, and integration checklists aligned to scale, margin, and IP objectives.
Market structure and competitive texture
The market exhibits moderate fragmentation: the three largest suppliers together account for roughly just under a third of global revenues, and the top five approach around two-fifths of the market. That structure creates both headroom for scale consolidation and defensibility for regional or specialized players who can leverage design, certification, or local-service advantages.
Across the competitive set, a few consistent strategic archetypes appear:
-
Volume-oriented, off-the-shelf specialists who compete on breadth of catalogue and fast availability.
-
Design-led firms that add ergonomic and aesthetic differentiation for handheld and customer-facing devices.
-
Custom and tooling-capable suppliers that capture higher ASPs in low-to-medium volume OEM programs (medical, industrial controls, lab automation).
-
Engineering partners focused on high-performance and environmental sealing for harsh environments (industrial, outdoor telecoms, and certain automotive segments).
Profiles and strategic implications for named competitors
-
Polycase (Avon, Ohio) — Strengths: US manufacturing, NEMA-rated enclosures, balanced off-the-shelf and custom capability. Strategic implication: momentum in domestically produced NEMA-rated lines positions Polycase well for nearshoring-led demand; scalability and raw-material cost management will be the near-term axes to protect margins.
-
Bud Industries (Willoughby, Ohio) — Strengths: broad general-purpose catalogue and industrial offerings. Strategic implication: catalogue breadth is a moat for distribution-led channels; further differentiation will require modularization and digital configuration tools.
-
Hammond Manufacturing (Guelph, Ontario) — Strengths: EMI/RFI shielding options, cross-material competence. Strategic implication: opportunity to capture higher-value industrial and communications niches that require shielding and hybrid material approaches, especially where performance trumps basic cost.
-
OKW Enclosures (Germany/US) — Strengths: ergonomic, design-forward solutions and customization. Strategic implication: premium positioning benefits from OEM relationships in handheld and medical classes; expansion in durable industrial solutions can broaden TAM.
-
New Age Enclosures — Strengths: off-the-shelf and injection-molding services for electronics. Strategic implication: vertical customers seeking single-source suppliers (design to injection) are prime targets — investments in shorter lead-time molding and digital quoting systems will pay back quickly.
-
Productive Plastics — Strengths: thermoforming and large custom enclosures for robotics and sensors. Strategic implication: as automation and robotics drive demand for bespoke housings, thermoforming and near-net shaping capabilities become attractive acquisition targets for firms wishing to enter large-format enclosures.
-
European specialists (Fibox, Bopla, Rolec) — Strengths: durable materials expertise and modern design language. Strategic implication: European players can exploit proximity advantages for industrial automation and utility markets subject to strong regulatory frameworks.
-
Allied Moulded Products, Integra, Toolless — Strengths: niche material mixes (fiberglass, stainless combinations), and no-tool or low-tool rapid customization. Strategic implication: these firms occupy defensible niches that become attractive targets for consolidators seeking to add specialty capabilities or to reduce time-to-market for regulated industries.
Recent market signals that should influence 2026 strategy
-
Raw-material swings: ABS feedstock tightening and producer-level price increases surfaced in early 2026, while polycarbonate softened materially in late 2025. Procurement roadmaps should incorporate both short-term pass-through scenarios and multi-year hedging strategies tied to polymer blends used across product families.
-
Regulatory tightening: national producer registries and international product-chemistry criteria (notably restrictions on certain brominated and chlorinated flame retardants) mean design teams must embed compliance earlier in the product lifecycle to avoid costly retrofits or market exclusion.
-
Trade policy friction: continued tariff adjustments on China-origin goods in strategic sectors increase the business case for diversified sourcing and regional production nodes.
-
Product innovation cadence: recent product launches and line extensions from leading players underscore a two-track innovation strategy—expand catalogue sizes for fast-moving SKUs while selectively developing ruggedized, certified products for high-growth verticals.
Practical strategic plays for 2026
-
Rebase product portfolios by margin contribution, not just revenue — rationalize low-margin SKUs where tooling and inventory drag ROI below company thresholds.
-
Optimize material mix: where polycarbonate pricing advantage exists, evaluate design swaps for equivalent performance; where ABS costs spike, pursue formulation blends or alternate polymer families for near-term relief.
-
Move to dual-source and geographically balanced supply footprints for critical resins and components; prioritize suppliers with validated compliance documentation to speed approvals.
-
Invest in compliance-as-a-service capabilities — materials declaration, test-lab partnerships, and documented chain-of-custody — as buyer requirements tighten in medical and enterprise tech markets.
-
Pursue bolt-on M&A to acquire specialty manufacturing (thermoforming, EMI-treated housings, or IP in sealed enclosures) that can boost realized ASPs and reduce dependence on commodity segments.
-
Deploy digital configurators and modular enclosure platforms to capture distribution revenue while reducing bespoke engineering costs; short lead-time, toolless product pathways can open medical and low-volume OEM opportunities.
How to use the full report
The full PW Consulting report contains the granular tables, regional and application breakouts, supplier scorecards and our scenario financial modeler that converts raw-material and tariff assumptions into P&L outcomes. This briefing purposefully omits detailed regional and application line-item disclosure to preserve the full dataset for buyers. For procurement teams, product leaders, and corporate development groups, the downloadable data pack and client workshop we provide turn findings into a 90–180 day execution roadmap.
Closing recommendation
With a projected rise from USD 6.25 Billion in 2025 toward the USD 9.4 Billion neighborhood by 2032 at a 6.0% CAGR, the electronic plastic enclosure market offers constructive growth backed by steady demand from consumer, industrial and automotive electronics. Yet the path to profitable growth in 2026 will be decided by three near-term capabilities: disciplined materials and cost management, demonstrable compliance and sustainability evidence, and operational agility to serve both catalogue and bespoke demand. PW Consulting’s full study equips leadership teams with the data, scenarios, and tactical playbooks needed to convert that market growth into durable margin expansion.
To obtain the complete report, regional and application breakouts, and the interactive scenario modeller, visit PW Consulting’s market reports page or contact our industry practice. The full package includes raw data downloads, supplier scorecards, and a tailored executive workshop to operationalize findings for 2026 planning.
For detailed analysis of this topic, please visit the official page: Electronic Plastic Enclosure Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: BT Laminate Market Set to Expand at a 7.25% CAGR, Fueled by Asia‑Pacific Demand
By pmarketresearch, 2026-07-02
BT Laminate Market 2026 Strategic Brief: Navigating Cost Shock, Concentration, and Opportunity
PW Consulting’s latest BT Laminate Market report (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes proprietary modeling, supplier-level intelligence, and scenario-based stress tests to give senior executives the decision-ready insights needed for 2026. Our analysis shows the global BT laminate market expanding from approximately USD 3,212.5 Million in 2025 to USD 5,243.5 Million by 2032, implying a compound annual growth rate (CAGR) of 7.25% over the forecast horizon. These headline figures underscore both resilience and structural change — but the near-term operating environment is where the most urgent strategic choices lie.
BT Laminate Market
Why this report matters for 2026 decision cycles
- Timesensitive procurement and pricing decisions: After an extended period of margin resilience, 2025–2026 has delivered sharp upstream cost shocks — from copper foil to electronic-grade glass cloth and specialty resins — that are forcing price pass-through decisions across the value chain. Our scenario models quantify the operating leverage and margin sensitivity for typical OEMs, substrate suppliers, and contract manufacturers.
- Concentrated supply base with strategic implications: The BT laminate market is highly concentrated. Our competitive analysis shows the top-tier players commanding the lion’s share of capacity and technology leadership. That concentration shapes negotiating dynamics, capacity allocation during cycles of tight supply, and the viability of near-term vertical integration moves.
- Regulatory and product-spec shifts: Accelerating adoption of halogen-free grades and lower-transmission-loss materials is creating bifurcated product roadmaps. Firms that can reconcile regulatory compliance with cost-effective process flows will capture disproportionate upside.
What executives will find actionable in the report
We designed this deliverable to be a playbook for 2026 strategy workstreams. The core assets include:
BT Laminate Market
- Demand-supply and price cascade models: Multi-scenario forecasts that map upstream input price moves to laminate cost curves and to downstream pricing elasticity. These models support three pricing-implementation templates: full pass-through, staged recovery, and margin protection via product mix optimization.
- Supplier risk heatmap and contingency plans: A weighted supplier-risk framework that combines concentration, geographic exposure, raw-material dependency, and technological differentiation. Each risk tier links to recommended tactical responses — from dual-sourcing playbooks to inventory buffering guidelines and JIT-to-JIC transition triggers.
- Technology and product readiness assessment: Comparative benchmarking of BT resin chemistries, low-warp formulations, and low-loss grades. The assessment includes manufacturing maturity scoring, retrofit cost estimates, and time-to-market roadmaps for process qualification cycles.
- Commercial playbooks: Negotiation templates and contracting structures (tiered pricing, indexation clauses, CPFR triggers) tailored to both buyers and producers to manage pass-through timing and protect margins during volatile input cycles.
- M&A and CapEx decision support: A prioritized list of capability and capacity gaps, complemented by valuation scenarios and synergies diagnostics for acquisition or greenfield investment. Our capital-allocation matrices help management prioritize capacity expansion, retrofits for low-loss grades, or investment in alternative substrate technologies.
- ESG and regulatory roadmaps: Compliance pathways for halogen-free adoption, supply-chain traceability templates, and product stewardship playbooks that align with global hazardous-substance regulations and customer procurement policies.
Competitive landscape — what our strategic read is
The BT laminate arena combines deep, technology-led incumbency with aggressive regional capacity investments. Our company dossiers synthesize technological strengths, geographic footprints, and product roadmaps for each major player. High-level takeaways:
BT Laminate Market
- Technology incumbency matters: Firms that pioneered BT chemistry and have continued materials R&D retain pricing power in advanced packaging and high-frequency applications. Their IP in low-warp and halogen-free grades serves as a barrier to low-cost entrants.
- Scale and product breadth are defensive moats: Large-scale copper-clad laminate producers with integrated upstream inputs have greater ability to smooth margin volatility and prioritize high-value customers during tight supply periods.
- Regional footprint is a competitive differentiator: Suppliers with multi-site manufacturing across Asia, North America, and Europe can manage logistics and regulatory variances more effectively and are preferred partners for global OEMs seeking supply resilience.
Representative strategic profiles (high level): Mitsubishi Gas Chemical retains deep technical leadership in BT resin technology and recently received industry recognition for next-generation low-warp grades — an advantage in high-density packaging. Major global material suppliers and laminate producers remain the primary capacity anchors, while several large Asian manufacturers are focusing on scale and cost competitiveness for high-volume segments. A subset of specialized suppliers competes on high-frequency and thermal-stability performance, addressing telecom, automotive, and semiconductor packaging niches.
Recent market shocks and what they signal
- Upstream cost inflation and an industry price response: In early 2026 a major supplier implemented a uniform price increase across several electronic-material product lines, citing raw-material and logistics cost pressures. This move crystallized margin compression risk across the supply chain and set a new bargaining baseline for pass-through negotiations.
- Supply constraints for key inputs: Glass-fabric availability tightened late in 2025 amid memory-sector strength and AI-driven demand. When raw-material tightness coincides with concentrated production, allocation risk rises rapidly and short-term spot premiums can spike.
- Regulatory-driven product migration: Demand for halogen-free and lower-transmission-loss BT formulations continues to grow, driven by both customer specifications and regulatory compliance. This creates a two-track market where premium, compliant grades command differentiated pricing and qualification timelines.
Strategic implications and recommended 90–180 day actions for 2026
For leadership teams planning 2026 budgets and operational priorities, the report translates market dynamics into a prioritized set of actions:
- Immediate (0–90 days): Run supplier exposure audits and implement short-term buy-side protections (indexation clauses, spot hedges for copper and glass cloth where economically justified). Activate contract-renegotiation templates and scenario-driven inventory thresholds.
- Near term (90–180 days): Accelerate qualification for alternative material grades and diversify sourcing across suppliers and geographies. Commission a cost-to-serve analysis to inform customer pricing strategies and margin preservation. Begin stress-testing planned CapEx against “high-cost” and “material-shortage” scenarios in our report.
- Medium term (6–18 months): Prioritize investments in low-loss BT variants and halogen-free process capabilities where ROI and customer funnel support. Consider strategic partnerships or bolt-on acquisitions to secure critical upstream inputs or to access differentiated resin chemistries.
Why PW Consulting’s dataset matters to you
The value of our report is the integration of market-level forecasting with supplier-level intelligence and executable templates. We combine a macro view — the market trajectory from roughly USD 3.21 Billion in 2025 to USD 5.24 Billion by 2032 at a 7.25% CAGR — with granular tools: cost-pass-through matrices, supplier-risk scores, technology-readiness assessments, and commercial contracting playbooks. That linkage from numbers to executable decisions is what makes this work actionable for 2026 planning cycles.
What we intentionally withhold here (and why)
Consistent with our “trailer” approach, this briefing demonstrates the analytical depth and strategic utility of the full report while intentionally omitting detailed subsegment splits, region-by-region revenue percentages, and proprietary supplier-level financials. Those datasets and the interactive models are included in the full report package and are best accessed directly to support confidential decision workflows and financial planning models.
Next steps — how to use this insight
- Download the full report and interactive workbooks to run supplier and price scenarios against your own demand profiles.
- Schedule a strategy workshop with our materials and procurement specialists to tailor the supplier heatmap and CapEx scenarios to your balance sheet.
- Engage our M&A advisory team to evaluate prioritized gap-filling targets or joint-venture structures that accelerate access to low-warp and halogen-free BT capabilities.
PW Consulting’s BT Laminate Market report is built for executive teams that need not just forecasts, but playbooks — tested, quantifiable, and ready for immediate deployment. For access to the full dataset, supplier dossiers, and customizable models that underpin these conclusions, please visit the report page and request the executive package.
For detailed analysis of this topic, please visit the official page: BT Laminate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Roadmarking Paints Market Poised to Reach USD 10.6 Billion by 2032 on 5.8% CAGR, Led by Asia‑Pacific at USD 2.91 Billion
By pmarketresearch, 2026-07-02
Roadmarking Paints Market 2026 Outlook — Strategic Imperatives for Infrastructure Leaders
Executive snapshot
PW Consulting’s latest Roadmarking Paints Market report (base year 2025) synthesizes five years of historical performance and a seven-year forecast horizon (2026–2032) to deliver a decision-ready view of a market returning to structural growth. After recovering through the early 2020s, the market reached approximately USD 7.18 billion in 2025, and our modelling shows a steady compound annual growth rate (CAGR) of 5.8% over the forecast period — consistent with durable demand driven by road safety programmes, airport and parking infrastructure renewal, and a gradual premiumisation of specification standards. By 2032 the market is expected to approach a new scale, underscoring strategic opportunities for suppliers, specifiers, and investors preparing plans for 2026 and beyond.
Roadmarking Paints Market
What the report delivers (practical, operationally focused)
- Forward-looking market sizing and scenario mapping that translates macro growth into prioritized, risk-weighted opportunities by product family and end-use (methodology and granular segment tables are available in the full report).
- Cost-to-serve and margin sensitivity templates that let suppliers run “what-if” scenarios against raw-material shocks, VOC compliance costs, and procurement hedging strategies.
- Competitive scorecards and capability matrices for incumbent producers and regional challengers — designed to support partner screening, M&A diligence, and tender strategy.
- Practical playbooks for procurement teams and infrastructure owners that cover specification optimization, lifecycle-cost comparisons, and rapid pilot programmes for newer application technologies.
- Regulatory and standards impact assessment, including compliance roadmaps and capital planning inputs for 2026–2028 implementation windows.
Market dynamics that will shape 2026 decisions
- Demand fundamentals: Traffic growth, renewed public investment in road safety, and selective capacity additions continue to underpin long-term demand. The market’s mid-single-digit CAGR reflects a balance of replacement cycles and faster adoption of higher-durability systems in urban and high-traffic corridors.
- Specification premiumisation: Owners are increasingly weighting lifecycle cost, retroreflectivity, and environmental attributes into tender evaluations. This is prompting a shift from lowest-capex buys toward paints and systems that deliver longer service lives and lower whole-life maintenance costs.
- Raw-material and input-cost volatility: Suppliers face margin pressure from fluctuating prices for resins, thermoplastic compounds, and specialty glass beads. These cost swings are a primary driver of short-term margin compression and procurement renegotiations in 2026 planning cycles.
- Regulatory constraints: Tighter VOC and environmental standards — and recent updates to regional specifications such as the IS 164 revision — are reshaping formulation strategies. Manufacturers who move early to low-VOC, compliant systems will find preferential access to public tenders and lower compliance risk.
- Concentration and competitive behaviour: The market exhibits moderate concentration at the top: a small group of global and regional players controls a meaningful share of supply, creating advantages in R&D scale, distribution reach, and specification influence. This structure makes M&A and alliance strategies attractive tools to gain rapid footprint expansion.
Product and application trends to watch in 2026
- Waterborne adoption: Continued momentum toward waterborne formulations where environmental regulation and operator preference allow, driven by VOC reduction goals and ease of cleanup.
- Durability premium: Thermoplastic and two-component systems retain appeal in high-wear contexts. Procurement teams are increasingly receptive to lifecycle-cost models that justify higher up-front expenses.
- Specialty additives: Innovations in glass-bead technology and polymer modifiers that improve retroreflectivity and abrasion resistance will be differentiators in specification-driven procurements.
- Application productivity: Field application technology — from mechanised spraying systems to automated layout and curing processes — will drive value capture in fast-turnaround projects and high-traffic sites.
Competitive landscape: strategic profiles and implications
The market is shaped by a mix of global coating majors and specialised regional players. PW Consulting’s proprietary review highlights how leading players are positioning themselves for 2026 opportunities:
Roadmarking Paints Market
- PPG Industries (ENNIS-FLINT family) — With a broad portfolio spanning waterborne and solvent-based traffic paints, PPG leverages global R&D and application know-how. Their strength is in scale and specification leadership, which supports premium positioning on large public tenders. For 2026, PPG’s playbook will likely emphasise bundled service offerings and specification partnerships with agencies aiming to improve lifecycle outcomes.
- Swarco — Known for solvent-based and waterborne paints alongside two-component systems, Swarco’s integrated product-and-service model suits clients seeking turnkey marking solutions. Their engineering orientation and systems integration capability make them a natural choice for complex projects — a position that will matter as infrastructure managers demand guaranteed performance metrics.
- Meon Ltd — A specialist in line marking paints and cold plastic systems, Meon’s niche focus gives it agility in parking, airport, and municipal markets. Smaller, specialised players like Meon can exploit tender fragmentation and local service advantages; strategic partners and distributors should evaluate such players for targeted geographic expansion.
- Axalta Coating Systems — With formulations including spirit-soluble and modified alkyd products, Axalta competes on formulation breadth and application expertise. Their capability to service legacy specifications alongside newer offerings positions them well for clients transitioning fleets of vehicles and surfaces under mixed tender specifications.
- Cloverdale Paint Inc — A regional player with waterborne traffic paint formulations approved against stringent infrastructure specs, Cloverdale exemplifies how local approvals and compliance can create defensible positions in regulated markets. For buyers prioritising compliance risk reduction, such suppliers are strategic targets for long-term contracts.
Strategic actions for 2026 planning (who should do what)
- Manufacturers and formulators: Prioritise margin defence through raw-material hedging, tiered product portfolios (budget, standard, premium), and early investment in low-VOC technologies. Establish rapid-response supply chains for specialty glass beads and thermoplastic feedstocks.
- Distributors and applicators: Differentiate on service quality and application productivity. Invest selectively in mechanised application capabilities and operator training to win performance-based tenders.
- Infrastructure owners and specifiers: Move from capex-centric tendering to lifecycle-cost frameworks that reward longer-life systems and verified retroreflectivity performance. Pilot higher-spec systems on critical corridors to build the case for scaled adoption.
- Investors and M&A teams: Target bolt-on acquisitions that fill formulation or geographic gaps. Given moderate top-tier concentration, consolidation can accelerate access to regulated tenders and reduce unit costs via scale.
How PW Consulting’s report accelerates 2026 decision cycles
Our report is structured to close the gap between strategic intent and operational execution. Alongside market-sizing and trend analysis, it contains practical artefacts you can use today: supplier scorecards, margin-sensitivity models calibrated to current resin and bead pricing, a regulatory-impact timeline (including the implications of IS 164 changes), and a tender-response playbook designed to win in specification-led procurements. For procurement teams running 2026 RFPs, the modelling tools translate market growth assumptions into optimal inventory, pricing, and supplier-mix decisions.
Roadmarking Paints Market
Why a “trailer” reading is intentionally limited
To maintain the integrity of PW Consulting’s proprietary modelling and to encourage informed engagement, this communication highlights the critical directional signals and strategic levers without publishing the granular segment and regional tables that underpin procurement and investment decisions. The full report contains the detailed breakdowns — region and application splits, type-level forecasts, unit-price trajectories, and supplier financial benchmarks — that underpin robust 2026 strategies.
Next steps
- For executives preparing 2026 capital and procurement plans: request the report’s scenario worksheets to stress-test budget allocations against raw-material volatility and regulatory compliance costs.
- For commercial teams and product leaders: schedule a strategy briefing with PW Consulting to preview supplier scorecards and product roadmaps tailored to your geographic footprint.
- For investors and M&A teams: book a diligence deep-dive to access the full segmentation tables, valuation multiples, and target screening filters used in our advisory work.
PW Consulting’s Roadmarking Paints Market report translates measurable market growth — from a 2025 base of roughly USD 7.18 billion and a 5.8% CAGR across the 2026–2032 forecast window — into concrete, deployable strategies for the 2026 decision cycle. For the full dataset, granular segment modelling, and bespoke scenario work tailored to your organisation, visit our report landing page or contact our advisory desk to arrange a workshop.
For detailed analysis of this topic, please visit the official page: Roadmarking Paints Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Turbine Inlet Air Cooling (TIAC) Market Poised for Robust Growth — 7.35% CAGR Projected for 2026–2032
By pmarketresearch, 2026-07-02
Turbine Inlet Air Cooling (TIAC) Market: Strategic Compass for 2026 Decisions
As air temperatures rise and grid dynamics become more volatile, the role of Turbine Inlet Air Cooling (TIAC) in safeguarding and augmenting gas-turbine output has moved from niche optimization to board-level strategic planning. PW Consulting’s latest market study — covering 2020–2025 history and a 2026–2032 forecast horizon — distills the actionable intelligence executives need to make high‑confidence capital, procurement, and partnership decisions in 2026. This release outlines the report’s high-level findings, competitive map, and practical tools while deliberately withholding the granular segment tables and model outputs that deliver the full investment case (available in the full report).
Turbine Inlet Air Cooling (TIAC) Market
Market Trajectory — What the headline numbers mean for strategy
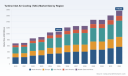
Our macro modelling shows the global TIAC market expanding materially over the next decade. After advancing through a cyclical recovery in 2020–2025, the market is forecast to grow at a compound annual growth rate (CAGR) of approximately 7.35% across 2026–2032. The overall market scale exceeds one billion USD by the 2025 base year and grows into the multi‑billion range over the forecast period. This trajectory reflects three intersecting forces: (1) ongoing demand for peak and mid‑merit power capacity optimization, (2) the operational economics of output augmentation in warm climates, and (3) technology-led cost declines and modularization enabling faster deployments.
Turbine Inlet Air Cooling (TIAC) Market
For executives, the headline takeaway is clear: TIAC is no longer a tactical add‑on; it is an investable capability that can materially influence plant-level dispatch economics and fleet availability. The CAGR implies that waiting for “perfect” market conditions risks being outpaced by competitors who deploy TIAC to secure more reliable, flexible generation capacity.
Turbine Inlet Air Cooling (TIAC) Market
Why 2026 is a pivotal decision window
- CapEx and replacement cycles: Many gas‑turbine operators are entering scheduled overhauls in 2026–2028. These windows minimize integration costs for TIAC systems compared with brownfield retrofits outside outage windows.
- Grid flexibility premium: Markets valuing fast-response capacity and ancillary services are increasing the revenue uplift associated with higher turbine output and ramp capability — creating improved payback profiles for TIAC investments.
- Supplier consolidation and M&A: Recent transactions demonstrate industry consolidation, altering supplier bargaining power and acquisition targets for industrial buyers seeking vertically integrated solutions.
Report anatomy — what PW Consulting provides (practical, modelled, implementable)
PW Consulting’s TIAC study is structured to move executives from strategic intent to executable plans in months, not years. Key deliverables include:
- Market sizing and forecast model (interactive): scenario‑driven top‑down forecasts with sensitivity levers for ambient temperature trends, gas turbine fleet retirement/retrofit rates, and regional demand growth. Note: the public synopsis highlights overall market scale and growth rate; the detailed model that disaggregates by region, type, and application is only available in the full report.
- Investment and payback toolkit: plant-level financial templates that calculate IRR, NPV, and simple payback under variable fuel, power price, and capacity-remuneration regimes.
- Technology decision matrix: a pragmatic framework that maps evaporative systems, fogging, mechanical chillers, and absorption chillers to site conditions (humidity, space, water availability), regulatory constraints, and O&M complexity.
- Procurement and contracting playbook: standardised RFP language, performance acceptance tests, and warranty structures tailored to TIAC modules and integrated systems.
- Deployment playbooks: modular installation pathways (containerized chillers, field-built evaporative systems, packaged fogging), integration checklists for control systems, and commissioning sequencing aligned with turbine maintenance windows.
- Risk and resilience matrix: supply‑chain stress tests, raw‑material exposure analysis, and contingency plans for prolonged warm‑season demand peaks.
Competitive landscape — who matters and why
The TIAC supplier ecosystem is diverse: specialist system integrators, large HVAC and chiller OEMs, and filtration and humidification technology providers converge on the value chain. The market concentration is moderate: the top three players account for a meaningful but not overwhelming share of market revenues, and the top five collectively hold a clear majority, reflecting an industry where regional specialists coexist with global suppliers.
Selected company profiles and recent moves highlighted in the report illustrate the strategic positioning you should monitor as you shape 2026 agendas:
- Stellar Energy (Jacksonville, Florida) — turnkey TIAC systems with thermal energy storage options; claims of up to 30% turbine output enhancement position them strongly for integrated power and data‑center cooling opportunities. Their acquisition by a major thermal systems player in early 2026 underscores the attractiveness of TIAC technologies to broader HVAC/energy companies and signals further consolidation.
- ARANER (Madrid, Spain) — specialist in indirect cooling with heat-exchanger approaches and condensate management; their engineering focus is well-suited to sites where water constraints or regulatory limits favour indirect solutions.
- Mee Industries (California) — leading high‑pressure fogging systems provider; recent industry recognition and product content publications indicate an effort to codify performance benefits and accelerate adoption.
- Johnson Controls (global) — mechanical chiller packaging and containerized systems; their global supply footprint and packaged product lines make them a logical partner for fastest time‑to‑market deployments.
- SPX Cooling Technologies, Munters, Camfil, Caldwell Energy — firms that span evaporative cooling, fogging, filtration, and system integration; their offerings illustrate the modular build vs. integrated system tradeoff faced by buyers.
These profiles reveal two strategic supplier archetypes: product‑centric OEMs (packaged chillers, foggers, filtration) and solution integrators that bundle hardware, controls, and performance guarantees. Buyers should decide whether to optimize for lowest CAPEX (product buys + internal integration) or lowest time/operational risk (turnkey systems with performance contracts).
Market dynamics and risk factors to factor into 2026 planning
- Regulatory and standards environment: Industry bodies continue to develop best practices and standards for TIAC implementation. Organizations that proactively align with these emerging standards will shorten approval cycles and reduce permitting risk.
- Supply‑chain and input cost pressure: Rising commodity prices for steel and aluminum have increased manufacturing input costs for cooling system components. Procurement strategies must incorporate input‑cost escalation clauses, multi‑vendor sourcing, and longer lead‑time planning for critical frames and heat‑exchanger cores.
- Water availability and environmental constraints: Site water use and condensate handling are growing determinants in technology selection, particularly in arid regions. Indirect and closed‑loop systems require more CAPEX but can avoid regulatory constraints associated with evaporative approaches.
- Technology convergence: Thermal energy storage, hybrid cooling architectures, and IoT-enabled controls are creating new value pools by enabling time‑shifted cooling and predictive performance guarantees.
Actionable recommendations for executives (fast moves and strategic bets)
- Supply‑chain readiness (fast move): Lock lead times and component prices for projects scheduled in 2026–2028. Consider call‑off orders or vendor financing where possible to protect against commodity inflation.
- Bundle vs. buy decision framework (fast move): Use a three‑criterion assessment (time to revenue, integration risk, total lifecycle cost) to decide between turnkey providers and best‑of‑breed OEM stacks on each project.
- Targeted pilots (strategic bet): Run two pilots in the 2026 window — one with a high‑augmentation solution (e.g., fogging + wet compression) and one with a conservative, low‑water indirect chiller — to produce empiric delta performance and refine financial models for fleet rollouts.
- M&A and partnership scanning (strategic bet): Monitor specialist integrators and thermal‑storage players as potential acquisition targets to accelerate capability ownership and capture margin uplift from bundled services.
- Contracting innovation (operational): Negotiate performance‑linked contracts where vendors accept partial performance risk in return for higher maintenance or upgrade fees — aligning incentives and de‑risking capital deployment.
What the full PW Consulting TIAC report delivers (and why you should download it)
The public brief identifies the market’s direction and primary decision levers. The full report provides the proprietary, drillable analytics that translate insight into executable project plans: region and application breakdowns, technology share modelling, plant‑level ROI calculators, vendor scorecards, and a suite of procurement templates. We intentionally withhold the granular segmentation figures from this overview to preserve the value of the proprietary datasets and modelling logic that enable confident capital allocation.
If you are evaluating capacity upgrades, negotiating supplier contracts, or sizing acquisition targets in 2026, the full TIAC market study supplies the comparative data, scenario stress‑testing, and commercial templates you need to shorten decision cycles and reduce execution risk.
Next steps
- Download the full report to access the detailed regional, technology, and application models along with the interactive financial toolkit.
- Schedule a briefing with PW Consulting to run a customized site‑level assessment using our plant‑level ROI model and vendor selection matrix.
- Use the procurement playbook immediately to preview standardised RFP language and acceptance testing criteria for your 2026 procurement cycle.
TIAC is more than a technical retrofit; it is a strategic lever for capacity monetization and resilience in a warming world. For leaders shaping 2026 investment plans, the question is not whether TIAC can add value, but how quickly you can operationalize that value into controllable, revenue‑generating capacity. PW Consulting’s TIAC study gives you the roadmap, tools, and vendor insights required to move from consideration to commissioning within the next procurement cycle.
For detailed analysis of this topic, please visit the official page: Turbine Inlet Air Cooling (TIAC) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 6.29% CAGR for Fiberglass Composite Rail Ties Market During 2026–2032
By pmarketresearch, 2026-07-02
Fiberglass Composite Rail Ties Market: Strategic Briefing for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market study on Fiberglass Composite Rail Ties offers an operationally focused intelligence package tailored for executives, strategy teams, and procurement leaders planning 2026 initiatives. The market has shifted from niche specification to a scalable alternative for high‑decay zones and sustainability‑driven infrastructure programs. Our findings show a steady expansion in total market value — rising from approximately 178.5 Million USD in 2020 to 242.4 Million USD in the base year 2025 — and a projected compound annual growth rate (CAGR) of 6.29% across the 2026–2032 forecast window, taking the market toward roughly 371.8 Million USD by 2032. These macro dynamics create discrete windows for product development, supply chain repositioning, and commercial pilots; the report is designed to convert these windows into executable 2026 plans.
Fiberglass Composite Rail Ties Market
Why this matters for 2026 planning
-
Timing and scale: A mid‑single‑digit CAGR combined with accelerating replacement demand in certain geographies means that 2026 will be a year for capacity and commercial positioning, not merely R&D experimentation.
Fiberglass Composite Rail Ties Market -
Cost and risk profile: Raw material volatility — particularly in fiberglass and recycled plastics feedstocks — is material to unit economics. The sector will reward firms that pair technical differentiation with supply resilience and pricedown strategies.
Fiberglass Composite Rail Ties Market -
Standards and procurement gates: Compliance with rail authority standards (for example, widely recognized chapters that govern engineered composite ties) is a threshold requirement for mainstream procurement. Early alignment with testing protocols de‑risks pilot-to-scale transitions.
Market trajectory: what the numbers hide and reveal
The headline growth trajectory described above masks two important realities that frame 2026 choices. First, absolute market expansion is driven by a mix of replacement cycles in high‑decay zones, targeted transit projects, and bridge/tunnel applications where long life and environmental risk mitigation are prioritized. Second, growth is geographically and technically uneven: different tie constructions (e.g., long fiber versus continuous fiber systems) and application classes are evolving on distinct adoption curves. PW Consulting’s analysis identifies where early commercial traction is concentrated and where proof‑point investments are still required — we present directional momentum and scenario outcomes while intentionally reserving granular split data in this release to encourage direct engagement with the full study.
Dynamics shaping 2026 decision windows
-
Raw material supply and pricing: The fiberglass market experienced notable swings around late‑2025 and into 2026. After a period of moderation, upward pressure has resumed driven by raw material cost pass‑through, energy dynamics, and localized supply shortages. Procurement strategies that combine multi‑sourcing, indexed purchase agreements, and selective vertical integration will materially alter competitive cost curves.
-
Technical advances: Recent formulation work using recycled HDPE reinforced with high glass‑fiber loads and engineered fillers has improved flexural modulus and rigidity. These advances reduce barriers for mainline acceptance and open cost/performance tradeoffs that 2026 product roadmaps should exploit.
-
Regulatory and standards enforcement: Compliance with established design and performance frameworks is non‑negotiable for railroad buyers. Companies that institutionalize test rigs, third‑party validation, and variant documentation will shorten procurement cycles.
-
Sustainability and lifecycle economics: Composite ties made with recycled plastics and fiberglass offer end‑of‑life recyclability and eliminate creosote‑related hazards, enabling new procurement requirements tied to corporate ESG and public funding criteria. Lifecycle cost modeling, not simple upfront price comparisons, determines commercial viability in many tenders.
Competitive landscape: who to watch and why
The supplier base blends established composite specialists, plastics recyclers, and metal/wood incumbents adapting to new materials. Market concentration metrics indicate a sector that is neither fragmented nor tightly consolidated — there is room for national champions and specialist niche leaders alike. Key players we profile in the report exemplify the strategic archetypes buyers and investors should model:
-
Evertrak LLC — A North American player that emphasizes GFRP ties produced from recycled polyolefins and glass fiber, backed by product claims around 50‑year service life and standards alignment. A strategic investment by a major trading and manufacturing partner in early 2025 accelerated their production and distribution posture, signaling broader institutional capital interest in proven, recyclable GFRP systems.
-
EFG TieTek — An operational veteran focused on composite ties built from recycled plastics, rubber, and waste fiberglass with a diversified portfolio (cross ties, switch ties, bridge ties). Certification and longstanding production experience make them a reference point for technical maturity.
-
Triton Ties (Granite Peak Plastics affiliate) — Positions itself on extrusion technology and plastics recycling know‑how. Their strategy illustrates the value of marrying recycling scale with tie engineering to achieve competitive unit costs for mainline applications.
-
AGICO Rail and Pioonier — International entrants showing adoption pathways in metro systems and European markets, where processing patents and conformity to local standards facilitate municipal and transit procurement wins.
Recent supplier moves — strategic investment activity, refreshed technical messaging, and published formulation research — demonstrate how capital, branding, and R&D interact to accelerate readiness for larger tenders. PW Consulting’s supplier risk maps and partner suitability frameworks translate these dynamics into buy/partner/screen recommendations for 2026.
Strategic implications and prioritized actions for 2026
For executive teams building 2026 roadmaps, our analysis yields five prioritized decision areas that convert market growth into competitive advantage:
-
1) Launch targeted pilots aligned to replacement cycles: Prioritize pilot deployments in corridors where wood‑tie decay rates concentrate tie replacement volumes. Fast, well‑documented pilots shorten procurement lead times and create replicable case studies for network rollout.
-
2) Hedge raw material exposure: Implement layered procurement tactics — forward contracts where liquidity exists, indexed arrangements with major recyclers, and selective inventorying of critical glass fiber grades — to stabilize gross margins against 2026 price volatility.
-
3) Standardize testing and documentation: Invest in an in‑house or partner‑based testing regimen aligned with industry chapters that specify design, dimensional and performance equivalence to hardwood alternatives. This reduces technical objections during tender evaluation.
-
4) Prioritize lifecycle cost models over sticker price: Build TLCC (Total Lifecycle Cost and Carbon) models that incorporate maintenance intervals, expected service life, disposal or recycling credits, and environmental externalities to win tenders that weight sustainability metrics.
-
5) Pursue selective partnerships and M&A: Capital infusion and alliances — whether to expand capacity, secure feedstock, or acquire certification expertise — are becoming the faster route to scale than greenfield capacity alone. Monitor strategic moves by well‑capitalized buyers and engage with potential partners early.
What PW Consulting’s report delivers (practical components)
This study is built to be operationally useful in 2026. Among the deliverables:
-
Scenario models projecting demand and margin sensitivity across multiple raw‑material and adoption curves;
-
Supplier segmentation and suitability matrices, including production capacity, standards certification, and strategic fit;
-
Procurement playbook with contract structures, hedging options, and lead‑time mitigation tactics;
-
Pilot design templates and test protocols mapped to regulatory acceptance criteria;
-
Lifecycle cost calculators and ESG value capture frameworks for tender pricing and public funding submissions;
-
M&A and partnership scouting list with acquisition thesis and integration checklists targeted at 2026 consolidation scenarios.
To preserve commercial value for subscribers, the report presents detailed segmentation, regional and application revenue splits, and vendor share tables in the full document; this briefing intentionally focuses on strategic takeaways while directing practitioners to the full report for transaction‑grade numbers and supplier profiles.
How to use this briefing in 2026
-
Senior strategy teams: Use the scenario outputs to set capital allocation for 2026 R&D and capacity investments.
-
Procurement leaders: Adopt the playbook to design supplier panels and negotiate raw material supply terms keyed to expected demand curves.
-
Business development and product teams: Prioritize feature sets (mechanical performance, installability, recyclability) for pilot kits that can be validated under existing standards.
-
Investors and corporate development: Use supplier risk maps and concentration metrics to screen targets and co‑investment opportunities.
Closing perspective
Fiberglass composite rail ties are transitioning from an experimental substitute into a mainstream procurement option for segments of the rail network where longevity, environmental risk, and total lifecycle cost matter. Our market baseline and forecast quantify that transition, while the operational frameworks included in the full PW Consulting study translate those data into 2026‑ready actions. For decision‑makers aiming to move beyond pilots, the practical question for 2026 is not whether composites will matter — it is which organizations will have the contractual, technical, and supply‑chain scaffolding in place to capture that material demand growth. PW Consulting’s report is designed to be the scaffolding.
Download the full study and access vendor, regional and application level intelligence, as well as our proprietary supplier suitability tools, on the PW Consulting research portal.
For detailed analysis of this topic, please visit the official page: Fiberglass Composite Rail Ties Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cellular Base Station Antenna Market Reaches USD 10,480 Million in 2025, Projected to Expand at a 15% CAGR Through 2032
By pmarketresearch, 2026-07-02
Cellular Base Station Antenna For Telecommunications Industry Market — 2026 Strategic Outlook
PW Consulting’s latest market study, with a 2025 base year and a seven‑year forecast through 2032, frames the cellular base station antenna market as a rapid-growth, strategic battleground for network operators, infrastructure suppliers, and capital investors. The global market, measured in USD Million for base station antennas and related RF subsystems, stood at approximately 10,480 million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 15.0% over 2026–2032, reaching an expected total near 27,877 million by 2032. These headline dynamics underscore why antenna choices, deployment timing, and supplier strategy will be core determinants of competitive advantage for organizations making decisions in 2026.
Cellular Base Station Antenna For Telecommunications Industry Market
Why this report matters for 2026 decision-makers
-
Investment prioritization: Capital allocation decisions for macro and small cell rollouts hinge on realistic, technology‑specific cost and performance tradeoffs. Our study translates market growth into calibrated procurement scenarios that reflect both incumbent and emerging architectures.
Cellular Base Station Antenna For Telecommunications Industry Market -
Vendor selection and risk mitigation: With market concentration materially favoring a small set of global suppliers, operators must balance performance, security/compliance (e.g., supply‑chain provenance and NDAA considerations), and resilience. We provide a decision framework to operationalize those tradeoffs.
Cellular Base Station Antenna For Telecommunications Industry Market -
Regulatory timing and spectrum strategy: Recent regulatory moves—most notably U.S. modernization efforts and proposed repurposing of portions of the Upper C‑band—create narrow windows for network upgrades and auction planning. The report maps deployment and upgrade timelines against plausible regulatory milestones.
-
Sustainability and OPEX reduction: Energy efficiency is no longer ancillary. Our analysis translates antenna architecture choices into projected network energy footprints and identifies where passive and active designs produce measurable user‑experience and cost benefits.
Key findings — a preview
-
Robust, technology‑driven expansion: The favorable 15% CAGR through 2032 is being driven by the combined momentum of Massive MIMO, multi‑band integration, densification through small cells, and evolution of active antenna systems. These technology drivers are shifting spend from discrete RF components toward integrated antenna‑radio solutions.
-
Consolidated competitive structure: The sector exhibits meaningful concentration at the top, with the largest manufacturers and integrated radio suppliers capturing a disproportionate share of spend. This creates both bargaining leverage for leading vendors and strategic vulnerabilities for buyers that over‑concentrate procurement.
-
Deployment economics remain the gating factor: High installation and maintenance costs, together with limited contiguous spectrum in key bands, continue to constrain densification strategies despite strong demand for greater capacity and coverage.
-
Standards and coordination matter: Industry harmonization—exemplified by recent updates to antenna description frameworks—reduces integration risk for multi‑vendor installations and accelerates time‑to‑revenue for new 5G rollouts.
-
Near‑term disruptions and catalysts: New product introductions (e.g., compact RU units optimized for sub‑6 GHz Massive MIMO) and regulatory reforms that streamline modifications to existing towers are immediate catalysts that will re‑shape vendor roadmaps and procurement windows in 2026.
Competitive landscape — what incumbents and challengers mean for buyers
The market’s competitive texture mixes global infrastructure OEMs, specialized antenna manufacturers, and vertically integrated radio vendors. This report profiles leading players across technology, go‑to‑market model, and value propositions, and it interprets the practical implications for sourcing and risk management:
-
Huawei Technologies Co. Ltd. — A broad portfolio across passive and active antennas including high‑port Massive MIMO and multi‑band designs. Strength: integrated, energy‑efficient high‑port arrays for large‑scale macro deployments.
-
Ericsson AB — Deep integration between antenna systems and RAN infrastructure (e.g., Ericsson Antenna System) with strong performance in Massive MIMO and hybrid architectures; notable for optimizing beam efficiency and cell‑edge throughput.
-
Nokia Corporation — Multi‑band and Massive MIMO solutions tailored to both dense urban and rural use cases, integrated with its AirScale platforms for operators prioritizing end‑to‑end coordination.
-
CommScope — Emphasizes scalable RF and hybrid LTE/5G solutions and distributed antenna systems, positioning for operators seeking modularity and retrofit capability.
-
Amphenol Antenna Solutions, Comba, Rosenberger, RFS, ACE Technologies, Tongyu, and others — A mix of tier‑2 players offering cost‑optimized passive designs, specialized mechanical and RF engineering, and localized supply options that matter for procurement diversification and geographic footprinting.
-
Regional and specialist entrants — Firms with domestic manufacturing footprints or sustainability‑focused designs offer differentiated value for governments and operators with local‑sourcing or environmental targets.
Importantly, PW Consulting’s competitive scoring synthesizes technical capability, supply‑chain resilience, regulatory compliance posture, and total cost outcomes. Report readers can access a vendor scorecard and shortlist builder to filter suppliers against procurement policies and risk appetite.
Regulatory and standards context shaping 2026 choices
-
Streamlining modernization: Recent regulatory orders aim to lower administrative barriers to tower and infrastructure upgrades—accelerating the upgrade cadence but compressing decision timelines for operators.
-
Spectrum reconfiguration: Proposed repurposing of mid‑band spectrum in flagship markets creates both deployment urgency and selective demand for antennas optimized for newly available bands.
-
Standards updates: Industry recommendations that harmonize how passive, active, and hybrid antennas are described simplify procurement specifications and integration testing—an immediate advantage for multi‑vendor rollouts.
What the PW Consulting report includes — practical, operational deliverables
This study is purpose‑built for executives and program managers who must translate market intelligence into executable plans. Deliverables include:
-
Executive decision frameworks that convert market growth scenarios into phased capex and opex plans.
-
Vendor scorecards and sourcing playbooks that balance technical fit, security/compliance, and supply‑chain exposure.
-
Deployment scenario templates and TCO models that capture capital expenditure, installation labor, maintenance trajectories, and energy consumption outcomes across antenna architectures.
-
Regulatory impact maps that align procurement and deployment milestones with expected policy actions and auction timelines.
-
Risk matrices and mitigation plans covering component shortages, tariff exposure, and single‑supplier dependencies.
-
Investment and M&A screening criteria for strategic acquisitions, joint ventures, or localized manufacturing investments.
Readers should note that the report contains granular segmentation and vendor‑level commercial estimates that are intentionally omitted from this press release to preserve actionable value; full datasets and model access are available via the report portal.
Actionable strategic recommendations for 2026
-
Prioritize modular, upgradeable architectures: Buy antennas and radio systems that enable incremental capacity scaling and remote software enablement to avoid costly rip‑and‑replace cycles.
-
Integrate energy efficiency into procurement KPIs: Require vendors to demonstrate beam‑efficiency and radio energy metrics tied to realistic cell‑edge throughput scenarios; these metrics materially affect OPEX and user experience.
-
Time spectrum‑dependent rollouts to regulatory windows: Align major macro upgrades to confirmed spectrum repurposing and auction timelines to maximize spectral efficiency and spectrum value extraction.
-
Diversify supplier footprint with domestic or NDAA‑compliant options where geopolitical risk or procurement rules demand it, but retain a performance‑first sourcing layer for large‑scale deployments.
-
Use scenario planning for densification economics: Employ PW Consulting’s TCO templates to compare capex/opex across small‑cell densification, macro upgrades with Massive MIMO, and hybrid models under alternative traffic growth paths.
-
Invest in integration and test capabilities: For multi‑vendor ecosystems, onshore lab resources and shared testbeds reduce rollout risk and speed time‑to‑service.
Buyer use‑cases — who benefits most
-
Mobile network operators — Strategic planning for capacity and coverage upgrades, supplier selection, and spectrum monetization.
-
Towercos and infrastructure investors — Valuation and retrofit prioritization for assets in spectrum‑rich markets.
-
Governments and regulators — Impact assessment of spectrum policy and infrastructure modernization incentives.
-
Component and antenna manufacturers — Competitive benchmarking, product roadmap validation, and partner identification.
-
Private equity and strategic acquirers — Target screening and synergy analysis for consolidation plays in a concentrated market.
Closing perspective
PW Consulting’s market study provides a pragmatic, decision‑grade synthesis of fast‑evolving technology, regulatory developments, and competitive positioning in the cellular base station antenna market. With an industry trajectory implying more than doubling market scale over the forecast horizon at a 15.0% CAGR, 2026 is a pivotal inflection year: regulatory windows are opening, product roadmaps are accelerating, and supply choices made now will determine total cost and time‑to‑market for the next wave of 5G and beyond deployments.
For procurement teams, technology strategists, and investors preparing 2026 plans, the full report supplies the models, vendor assessments, and scenario playbooks needed to convert these macro trends into executable, low‑risk programs. To access the complete dataset, granular segmentation, and vendor‑level analytics not disclosed here, please visit the PW Consulting report portal for subscription and licensing options.
For detailed analysis of this topic, please visit the official page: Cellular Base Station Antenna For Telecommunications Industry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ytterbium‑176 Market to Soar from USD 37.2 Million in 2025 to USD 175.95 Million by 2032 at a 24.85% CAGR — Top 3 Firms Command 88.42% Share
By pmarketresearch, 2026-07-02
Ytterbium-176 Market: Strategic Imperatives for 2026
PW Consulting’s latest Ytterbium-176 Market report (base year 2025; historical review 2020–2025; forecast 2026–2032) arrives at a pivotal moment for life‑science suppliers, radiopharmaceutical manufacturers, and strategic procurement teams. The market for enriched Yb‑176 has transitioned from niche research volumes to a commercially investable ecosystem—driven by the accelerating demand for no‑carrier‑added Lutetium‑177 production, advances in enrichment technologies, and deliberate policy shifts to diversify supply chains. Our analysis quantifies that transition and translates it into actionable options for executives planning investments, sourcing strategies, and regulatory engagement in 2026.
Ytterbium-176 Market
Why 2026 Is a Strategic Inflection Point
Between 2020 and 2025 the global Yb‑176 market expanded rapidly as capabilities matured and early commercial shipments began. PW Consulting’s baseline shows a multi‑fold increase in market size over that five‑year span, with continued momentum expected through 2032 under a compound annual growth rate of approximately 24.85%. The first forecast years (2026–2028) mark a shift from capacity demonstration to commercial scaling: producers that convert pilot output into repeatable, regulatory‑ready supply lines will define market leadership.
Ytterbium-176 Market
For corporate leaders, 2026 will not be a year to “wait and see.” It will be the year to convert strategic intent into operational positioning—securing long‑lead feedstock agreements, locking in manufacturing slots for Lu‑177 production, and embedding resilience in procurement contracts to mitigate geopolitical and regulatory risks.
Ytterbium-176 Market
What the Report Provides: Practical, Decision‑Ready Intelligence
- Market trajectory and scenario modeling. We present a base and alternative scenarios that reconcile historical shipments, announced capacity expansions, and plausible commercialization timelines—yielding forecast bands for planning and treasury modeling through 2032.
- Supply‑chain mapping and risk scoring. The report maps current producers, technology pathways (electromagnetic separation vs. laser‑based quantum enrichment), and bilateral dependencies. Each node is scored for capacity, ramp risk, export controls exposure, and time‑to‑certified supply.
- Procurement playbooks for buyers. Practical contracting templates and staging recommendations for the short (12 months), medium (12–36 months), and long (>36 months) horizons—covering MOQ strategies, quality acceptance criteria, and contingency clauses tied to irradiation cycles and Lu‑177 yield outcomes.
- Operational checklists for producers. Manufacturing readiness metrics (including feedstock sourcing, enrichment technology validation, impurity controls, and documentation needed for medical target manufacture) to accelerate regulatory acceptance by radiopharmacies and irradiation centers.
- Regulatory and compliance matrix. Consolidated guidance on nuclear safety standards, transport controls, export compliance considerations, and research‑use vs. commercial‑use distinctions that materially affect supply availability.
- M&A and strategic partner screening. A prioritized list of capability adjacencies—upstream enrichment, materials handling, irradiation capacity, and contract manufacturing—that create defensible value chains for entrants and incumbents alike.
Competitive Landscape: Technologies, Players, and Tactical Moves
The Yb‑176 marketplace is nascent but concentrated. A small set of specialized producers and government programs currently accounts for the vast majority of supply capacity; our competitive concentration metrics indicate a highly consolidated supply base. This concentration creates both a structural premium for secure supply and an opportunity for differentiated entrants to capture value through reliability, documentation, and service levels.
- Laser‑based entrants. Newer vendors deploying quantum enrichment laser systems have demonstrated faster theoretical enrichment pathways and lower footprint operations. These technology vendors are focused on demonstrating reproducible quality at commercial batches and translating lab results into certified supply chains.
- Electromagnetic‑separator incumbents. Established players using electromagnetic isotope separation have moved from proof‑of‑concept to commercial shipments, leveraging incremental capacity builds to serve initial customers with high‑purity material specifically tailored for medical target manufacture.
- Government and research suppliers. National isotope programs continue to play a role for R&D and capacity bridging, but their material is typically restricted to research quantities and not available as a full commercial supply solution. Nonetheless, their role in validating isotopic workflows and serving as strategic anchor providers cannot be understated.
Key industry movements in 2024–2025 already illustrate the reshaping of the ecosystem: commercial sample shipments by laser‑enrichment producers, capacity expansions by electromagnetic suppliers, and public announcements of commercial availability by established isotope firms. Taken together, these events signal a transition from scarcity to a more diversified commercial market—albeit one still dominated by a few players.
Risk and Opportunity: What to Watch in 2026
- Supply concentration risk. A small number of producers currently controls most commercial output. Buyers should prioritize multi‑sourcing strategies and contractual protections (e.g., supply assurance tiers and rollover options) to insulate irradiation schedules and downstream Lu‑177 production.
- Technology validation and quality parity. Not all enrichment methods are operationally equal when integrated into a medical‑grade production chain. Buyers and investors must evaluate not just isotopic purity claims but impurity profiles, material form (oxide vs. metal), documentation, and evidence of irradiation performance.
- Regulatory gating factors. Transport, handling, and export control regimes are evolving as governments aim to reduce single‑country dependencies. Firms should track policy shifts and align compliance roadmaps early to avoid operational delays.
- Commercialization cadence. Early entrants who demonstrated sample shipments in 2024–2025 still face the challenge of consistent, certified throughput. Monitoring production yields, lot reproducibility, and customer feedback will be essential to distinguish durable suppliers from one‑off producers.
How Investors and Strategic Buyers Should Use This Report in 2026
Executives can apply the report in three immediate ways:
- Portfolio prioritization. Use our scenario outputs to stress‑test capital projects and acquisition targets under different demand curves and supply ramp timelines. This is especially relevant for radiopharma firms planning to secure irradiation slots or for industrial players evaluating vertical integration into enriched targets.
- Procurement design. Implement layered sourcing frameworks: short‑term tactical purchases to maintain production runs; mid‑term contracts with capacity build options; and long‑term strategic partnerships to co‑finance upstream capacity expansions.
- Regulatory and stakeholder engagement. Allocate resources to documentation, safety case development, and export‑control compliance now—these investments reduce time‑to‑market advantages for new entrants and materially shorten commercial qualification periods for suppliers.
Case Illustrations (Non‑Exhaustive)
PW Consulting synthesizes public milestones and company disclosures into a practical set of lessons learned for 2026 planners. Examples include:
- Producers that paired technology demonstrations with early customer shipments built credibility faster; however, those that failed to publish qualification data struggled to convert pilots into recurring orders.
- Proactive buyers who negotiated conditional capacity options with multiple suppliers reduced their effective supply risk at marginal cost, compared with those relying on single‑source arrangements.
- Companies that integrated documentation and traceability into the handover from isotope supplier to irradiation facility significantly shortened regulatory review cycles for medical‑grade Lu‑177 synthesis.
What We Intentionally Omit (and Why)
In keeping with the “trailer” philosophy of this release, PW Consulting presents high‑confidence macro metrics and strategic guidance while reserving granular segmentation tables, region and end‑use breakdowns, and detailed price curves for subscribers of the full report. Readers seeking the complete data set—annualized market values by year, granular regional and application splits, supplier share tables, and facility‑level capacity schedules—should consult the full market study on our website.
Executive Recommendation: A 90‑Day Action Plan
- Supply assurance review: Map current and alternative suppliers; initiate contingency contracts for critical production slots.
- Technical validation: Commission independent analytical verification of isotopic and impurity profiles for any new supplier under consideration.
- Regulatory preparedness: Update transport and export‑control assessments and align quality documentation expectations with irradiation partners.
- Strategic scouting: Identify 2–3 potential M&A or JV targets—upstream enrichment or irradiation capacity—with the goal of securing optionality without bearing full build‑out risk.
Conclusion
The Ytterbium‑176 market is evolving from a constrained, research‑centric supply environment into a commercially viable segment with pronounced growth potential. PW Consulting’s report quantifies that pathway—with a strong historical growth trajectory and an aggressive forecast through 2032—while laying out the practical steps companies must take to translate market momentum into durable advantage. 2026 will reward organizations that combine technical due diligence, multi‑layered procurement, and regulatory foresight. For teams preparing capital allocations, vendor selection, or integration strategies this year, the full PW Consulting report delivers the underlying data and executable templates to move from strategic intent to operational certainty.
To access the full dataset, supplier profiles, and the detailed playbooks behind these insights, please visit the PW Consulting report page for the Ytterbium‑176 Market Study.
For detailed analysis of this topic, please visit the official page: Ytterbium-176 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com