

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ytterbium‑176 Market to Soar from USD 37.2 Million in 2025 to USD 175.95 Million by 2032 at a 24.85% CAGR — Top 3 Firms Command 88.42% Share

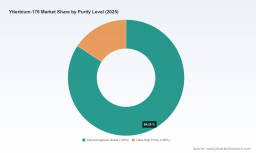
Ytterbium-176 Market: Strategic Imperatives for 2026
PW Consulting’s latest Ytterbium-176 Market report (base year 2025; historical review 2020–2025; forecast 2026–2032) arrives at a pivotal moment for life‑science suppliers, radiopharmaceutical manufacturers, and strategic procurement teams. The market for enriched Yb‑176 has transitioned from niche research volumes to a commercially investable ecosystem—driven by the accelerating demand for no‑carrier‑added Lutetium‑177 production, advances in enrichment technologies, and deliberate policy shifts to diversify supply chains. Our analysis quantifies that transition and translates it into actionable options for executives planning investments, sourcing strategies, and regulatory engagement in 2026.
Ytterbium-176 Market
Why 2026 Is a Strategic Inflection Point
Between 2020 and 2025 the global Yb‑176 market expanded rapidly as capabilities matured and early commercial shipments began. PW Consulting’s baseline shows a multi‑fold increase in market size over that five‑year span, with continued momentum expected through 2032 under a compound annual growth rate of approximately 24.85%. The first forecast years (2026–2028) mark a shift from capacity demonstration to commercial scaling: producers that convert pilot output into repeatable, regulatory‑ready supply lines will define market leadership.
Ytterbium-176 Market
For corporate leaders, 2026 will not be a year to “wait and see.” It will be the year to convert strategic intent into operational positioning—securing long‑lead feedstock agreements, locking in manufacturing slots for Lu‑177 production, and embedding resilience in procurement contracts to mitigate geopolitical and regulatory risks.
Ytterbium-176 Market
What the Report Provides: Practical, Decision‑Ready Intelligence
- Market trajectory and scenario modeling. We present a base and alternative scenarios that reconcile historical shipments, announced capacity expansions, and plausible commercialization timelines—yielding forecast bands for planning and treasury modeling through 2032.
- Supply‑chain mapping and risk scoring. The report maps current producers, technology pathways (electromagnetic separation vs. laser‑based quantum enrichment), and bilateral dependencies. Each node is scored for capacity, ramp risk, export controls exposure, and time‑to‑certified supply.
- Procurement playbooks for buyers. Practical contracting templates and staging recommendations for the short (12 months), medium (12–36 months), and long (>36 months) horizons—covering MOQ strategies, quality acceptance criteria, and contingency clauses tied to irradiation cycles and Lu‑177 yield outcomes.
- Operational checklists for producers. Manufacturing readiness metrics (including feedstock sourcing, enrichment technology validation, impurity controls, and documentation needed for medical target manufacture) to accelerate regulatory acceptance by radiopharmacies and irradiation centers.
- Regulatory and compliance matrix. Consolidated guidance on nuclear safety standards, transport controls, export compliance considerations, and research‑use vs. commercial‑use distinctions that materially affect supply availability.
- M&A and strategic partner screening. A prioritized list of capability adjacencies—upstream enrichment, materials handling, irradiation capacity, and contract manufacturing—that create defensible value chains for entrants and incumbents alike.
Competitive Landscape: Technologies, Players, and Tactical Moves
The Yb‑176 marketplace is nascent but concentrated. A small set of specialized producers and government programs currently accounts for the vast majority of supply capacity; our competitive concentration metrics indicate a highly consolidated supply base. This concentration creates both a structural premium for secure supply and an opportunity for differentiated entrants to capture value through reliability, documentation, and service levels.
- Laser‑based entrants. Newer vendors deploying quantum enrichment laser systems have demonstrated faster theoretical enrichment pathways and lower footprint operations. These technology vendors are focused on demonstrating reproducible quality at commercial batches and translating lab results into certified supply chains.
- Electromagnetic‑separator incumbents. Established players using electromagnetic isotope separation have moved from proof‑of‑concept to commercial shipments, leveraging incremental capacity builds to serve initial customers with high‑purity material specifically tailored for medical target manufacture.
- Government and research suppliers. National isotope programs continue to play a role for R&D and capacity bridging, but their material is typically restricted to research quantities and not available as a full commercial supply solution. Nonetheless, their role in validating isotopic workflows and serving as strategic anchor providers cannot be understated.
Key industry movements in 2024–2025 already illustrate the reshaping of the ecosystem: commercial sample shipments by laser‑enrichment producers, capacity expansions by electromagnetic suppliers, and public announcements of commercial availability by established isotope firms. Taken together, these events signal a transition from scarcity to a more diversified commercial market—albeit one still dominated by a few players.
Risk and Opportunity: What to Watch in 2026
- Supply concentration risk. A small number of producers currently controls most commercial output. Buyers should prioritize multi‑sourcing strategies and contractual protections (e.g., supply assurance tiers and rollover options) to insulate irradiation schedules and downstream Lu‑177 production.
- Technology validation and quality parity. Not all enrichment methods are operationally equal when integrated into a medical‑grade production chain. Buyers and investors must evaluate not just isotopic purity claims but impurity profiles, material form (oxide vs. metal), documentation, and evidence of irradiation performance.
- Regulatory gating factors. Transport, handling, and export control regimes are evolving as governments aim to reduce single‑country dependencies. Firms should track policy shifts and align compliance roadmaps early to avoid operational delays.
- Commercialization cadence. Early entrants who demonstrated sample shipments in 2024–2025 still face the challenge of consistent, certified throughput. Monitoring production yields, lot reproducibility, and customer feedback will be essential to distinguish durable suppliers from one‑off producers.
How Investors and Strategic Buyers Should Use This Report in 2026
Executives can apply the report in three immediate ways:
- Portfolio prioritization. Use our scenario outputs to stress‑test capital projects and acquisition targets under different demand curves and supply ramp timelines. This is especially relevant for radiopharma firms planning to secure irradiation slots or for industrial players evaluating vertical integration into enriched targets.
- Procurement design. Implement layered sourcing frameworks: short‑term tactical purchases to maintain production runs; mid‑term contracts with capacity build options; and long‑term strategic partnerships to co‑finance upstream capacity expansions.
- Regulatory and stakeholder engagement. Allocate resources to documentation, safety case development, and export‑control compliance now—these investments reduce time‑to‑market advantages for new entrants and materially shorten commercial qualification periods for suppliers.
Case Illustrations (Non‑Exhaustive)
PW Consulting synthesizes public milestones and company disclosures into a practical set of lessons learned for 2026 planners. Examples include:
- Producers that paired technology demonstrations with early customer shipments built credibility faster; however, those that failed to publish qualification data struggled to convert pilots into recurring orders.
- Proactive buyers who negotiated conditional capacity options with multiple suppliers reduced their effective supply risk at marginal cost, compared with those relying on single‑source arrangements.
- Companies that integrated documentation and traceability into the handover from isotope supplier to irradiation facility significantly shortened regulatory review cycles for medical‑grade Lu‑177 synthesis.
What We Intentionally Omit (and Why)
In keeping with the “trailer” philosophy of this release, PW Consulting presents high‑confidence macro metrics and strategic guidance while reserving granular segmentation tables, region and end‑use breakdowns, and detailed price curves for subscribers of the full report. Readers seeking the complete data set—annualized market values by year, granular regional and application splits, supplier share tables, and facility‑level capacity schedules—should consult the full market study on our website.
Executive Recommendation: A 90‑Day Action Plan
- Supply assurance review: Map current and alternative suppliers; initiate contingency contracts for critical production slots.
- Technical validation: Commission independent analytical verification of isotopic and impurity profiles for any new supplier under consideration.
- Regulatory preparedness: Update transport and export‑control assessments and align quality documentation expectations with irradiation partners.
- Strategic scouting: Identify 2–3 potential M&A or JV targets—upstream enrichment or irradiation capacity—with the goal of securing optionality without bearing full build‑out risk.
Conclusion
The Ytterbium‑176 market is evolving from a constrained, research‑centric supply environment into a commercially viable segment with pronounced growth potential. PW Consulting’s report quantifies that pathway—with a strong historical growth trajectory and an aggressive forecast through 2032—while laying out the practical steps companies must take to translate market momentum into durable advantage. 2026 will reward organizations that combine technical due diligence, multi‑layered procurement, and regulatory foresight. For teams preparing capital allocations, vendor selection, or integration strategies this year, the full PW Consulting report delivers the underlying data and executable templates to move from strategic intent to operational certainty.
To access the full dataset, supplier profiles, and the detailed playbooks behind these insights, please visit the PW Consulting report page for the Ytterbium‑176 Market Study.
For detailed analysis of this topic, please visit the official page: Ytterbium-176 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com