

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 6.29% CAGR for Fiberglass Composite Rail Ties Market During 2026–2032

Fiberglass Composite Rail Ties Market: Strategic Briefing for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market study on Fiberglass Composite Rail Ties offers an operationally focused intelligence package tailored for executives, strategy teams, and procurement leaders planning 2026 initiatives. The market has shifted from niche specification to a scalable alternative for high‑decay zones and sustainability‑driven infrastructure programs. Our findings show a steady expansion in total market value — rising from approximately 178.5 Million USD in 2020 to 242.4 Million USD in the base year 2025 — and a projected compound annual growth rate (CAGR) of 6.29% across the 2026–2032 forecast window, taking the market toward roughly 371.8 Million USD by 2032. These macro dynamics create discrete windows for product development, supply chain repositioning, and commercial pilots; the report is designed to convert these windows into executable 2026 plans.
Fiberglass Composite Rail Ties Market
Why this matters for 2026 planning
-
Timing and scale: A mid‑single‑digit CAGR combined with accelerating replacement demand in certain geographies means that 2026 will be a year for capacity and commercial positioning, not merely R&D experimentation.
Fiberglass Composite Rail Ties Market -
Cost and risk profile: Raw material volatility — particularly in fiberglass and recycled plastics feedstocks — is material to unit economics. The sector will reward firms that pair technical differentiation with supply resilience and pricedown strategies.
Fiberglass Composite Rail Ties Market -
Standards and procurement gates: Compliance with rail authority standards (for example, widely recognized chapters that govern engineered composite ties) is a threshold requirement for mainstream procurement. Early alignment with testing protocols de‑risks pilot-to-scale transitions.
Market trajectory: what the numbers hide and reveal
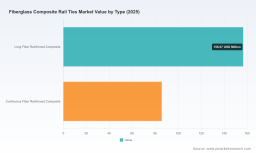
The headline growth trajectory described above masks two important realities that frame 2026 choices. First, absolute market expansion is driven by a mix of replacement cycles in high‑decay zones, targeted transit projects, and bridge/tunnel applications where long life and environmental risk mitigation are prioritized. Second, growth is geographically and technically uneven: different tie constructions (e.g., long fiber versus continuous fiber systems) and application classes are evolving on distinct adoption curves. PW Consulting’s analysis identifies where early commercial traction is concentrated and where proof‑point investments are still required — we present directional momentum and scenario outcomes while intentionally reserving granular split data in this release to encourage direct engagement with the full study.
Dynamics shaping 2026 decision windows
-
Raw material supply and pricing: The fiberglass market experienced notable swings around late‑2025 and into 2026. After a period of moderation, upward pressure has resumed driven by raw material cost pass‑through, energy dynamics, and localized supply shortages. Procurement strategies that combine multi‑sourcing, indexed purchase agreements, and selective vertical integration will materially alter competitive cost curves.
-
Technical advances: Recent formulation work using recycled HDPE reinforced with high glass‑fiber loads and engineered fillers has improved flexural modulus and rigidity. These advances reduce barriers for mainline acceptance and open cost/performance tradeoffs that 2026 product roadmaps should exploit.
-
Regulatory and standards enforcement: Compliance with established design and performance frameworks is non‑negotiable for railroad buyers. Companies that institutionalize test rigs, third‑party validation, and variant documentation will shorten procurement cycles.
-
Sustainability and lifecycle economics: Composite ties made with recycled plastics and fiberglass offer end‑of‑life recyclability and eliminate creosote‑related hazards, enabling new procurement requirements tied to corporate ESG and public funding criteria. Lifecycle cost modeling, not simple upfront price comparisons, determines commercial viability in many tenders.
Competitive landscape: who to watch and why
The supplier base blends established composite specialists, plastics recyclers, and metal/wood incumbents adapting to new materials. Market concentration metrics indicate a sector that is neither fragmented nor tightly consolidated — there is room for national champions and specialist niche leaders alike. Key players we profile in the report exemplify the strategic archetypes buyers and investors should model:
-
Evertrak LLC — A North American player that emphasizes GFRP ties produced from recycled polyolefins and glass fiber, backed by product claims around 50‑year service life and standards alignment. A strategic investment by a major trading and manufacturing partner in early 2025 accelerated their production and distribution posture, signaling broader institutional capital interest in proven, recyclable GFRP systems.
-
EFG TieTek — An operational veteran focused on composite ties built from recycled plastics, rubber, and waste fiberglass with a diversified portfolio (cross ties, switch ties, bridge ties). Certification and longstanding production experience make them a reference point for technical maturity.
-
Triton Ties (Granite Peak Plastics affiliate) — Positions itself on extrusion technology and plastics recycling know‑how. Their strategy illustrates the value of marrying recycling scale with tie engineering to achieve competitive unit costs for mainline applications.
-
AGICO Rail and Pioonier — International entrants showing adoption pathways in metro systems and European markets, where processing patents and conformity to local standards facilitate municipal and transit procurement wins.
Recent supplier moves — strategic investment activity, refreshed technical messaging, and published formulation research — demonstrate how capital, branding, and R&D interact to accelerate readiness for larger tenders. PW Consulting’s supplier risk maps and partner suitability frameworks translate these dynamics into buy/partner/screen recommendations for 2026.
Strategic implications and prioritized actions for 2026
For executive teams building 2026 roadmaps, our analysis yields five prioritized decision areas that convert market growth into competitive advantage:
-
1) Launch targeted pilots aligned to replacement cycles: Prioritize pilot deployments in corridors where wood‑tie decay rates concentrate tie replacement volumes. Fast, well‑documented pilots shorten procurement lead times and create replicable case studies for network rollout.
-
2) Hedge raw material exposure: Implement layered procurement tactics — forward contracts where liquidity exists, indexed arrangements with major recyclers, and selective inventorying of critical glass fiber grades — to stabilize gross margins against 2026 price volatility.
-
3) Standardize testing and documentation: Invest in an in‑house or partner‑based testing regimen aligned with industry chapters that specify design, dimensional and performance equivalence to hardwood alternatives. This reduces technical objections during tender evaluation.
-
4) Prioritize lifecycle cost models over sticker price: Build TLCC (Total Lifecycle Cost and Carbon) models that incorporate maintenance intervals, expected service life, disposal or recycling credits, and environmental externalities to win tenders that weight sustainability metrics.
-
5) Pursue selective partnerships and M&A: Capital infusion and alliances — whether to expand capacity, secure feedstock, or acquire certification expertise — are becoming the faster route to scale than greenfield capacity alone. Monitor strategic moves by well‑capitalized buyers and engage with potential partners early.
What PW Consulting’s report delivers (practical components)
This study is built to be operationally useful in 2026. Among the deliverables:
-
Scenario models projecting demand and margin sensitivity across multiple raw‑material and adoption curves;
-
Supplier segmentation and suitability matrices, including production capacity, standards certification, and strategic fit;
-
Procurement playbook with contract structures, hedging options, and lead‑time mitigation tactics;
-
Pilot design templates and test protocols mapped to regulatory acceptance criteria;
-
Lifecycle cost calculators and ESG value capture frameworks for tender pricing and public funding submissions;
-
M&A and partnership scouting list with acquisition thesis and integration checklists targeted at 2026 consolidation scenarios.
To preserve commercial value for subscribers, the report presents detailed segmentation, regional and application revenue splits, and vendor share tables in the full document; this briefing intentionally focuses on strategic takeaways while directing practitioners to the full report for transaction‑grade numbers and supplier profiles.
How to use this briefing in 2026
-
Senior strategy teams: Use the scenario outputs to set capital allocation for 2026 R&D and capacity investments.
-
Procurement leaders: Adopt the playbook to design supplier panels and negotiate raw material supply terms keyed to expected demand curves.
-
Business development and product teams: Prioritize feature sets (mechanical performance, installability, recyclability) for pilot kits that can be validated under existing standards.
-
Investors and corporate development: Use supplier risk maps and concentration metrics to screen targets and co‑investment opportunities.
Closing perspective
Fiberglass composite rail ties are transitioning from an experimental substitute into a mainstream procurement option for segments of the rail network where longevity, environmental risk, and total lifecycle cost matter. Our market baseline and forecast quantify that transition, while the operational frameworks included in the full PW Consulting study translate those data into 2026‑ready actions. For decision‑makers aiming to move beyond pilots, the practical question for 2026 is not whether composites will matter — it is which organizations will have the contractual, technical, and supply‑chain scaffolding in place to capture that material demand growth. PW Consulting’s report is designed to be the scaffolding.
Download the full study and access vendor, regional and application level intelligence, as well as our proprietary supplier suitability tools, on the PW Consulting research portal.
For detailed analysis of this topic, please visit the official page: Fiberglass Composite Rail Ties Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com