

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Electronic Plastic Enclosure Market to Expand from USD 6.25B in 2025 to USD 9.4B by 2032 at a 6% CAGR — Asia‑Pacific Leads with USD 2.67B in 2025

Electronic Plastic Enclosure Market 2026: Strategic Imperatives for Manufacturers, OEMs and Investors
PW Consulting’s newest market briefing on Electronic Plastic Enclosures draws a clear line from data to decision for 2026. The global market — sized at USD 6,248.5 Million in our 2025 base year — is forecast to grow at a steady compound annual growth rate (CAGR) of 6.0% through our 2026–2032 horizon, reaching roughly USD 9.4 Billion by 2032. That macro trajectory masks a highly dynamic competitive and supply-side environment. This release summarizes the report’s strategic value, the practical intelligence inside, and the near-term plays companies should consider as they prepare budgets, product roadmaps, and M&A pipelines for 2026.
Electronic Plastic Enclosure Market
Why this report matters for 2026 decision cycles
-
Actionable market sizing to set realistic topline targets: Executive teams and corporate development groups gain a defensible baseline and growth runway for budgeting and valuation work.
Electronic Plastic Enclosure Market -
Supply-side risk mapping linked to pricing scenarios: Raw material volatility and trade policy are already shifting cost structures; the report translates those shifts into margin and capex planning implications.
Electronic Plastic Enclosure Market -
Regulatory and sustainability readiness: New reporting and chemical-content standards are not future hypotheticals — they are procurement and product-design constraints to be managed this year.
-
Competitive playbooks and M&A priority lists: We convert market structure and capability gaps into prioritized actions — product development, capacity moves, and bolt-on acquisition criteria.
What the report delivers (practical components)
-
Comprehensive market sizing and a seven-year forecast (2026–2032) with base-year 2025 alignment for reconciliation to internal plans.
-
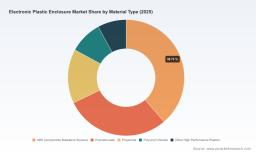
Segmentation by material (ABS, polycarbonate, polyamide, PVC, and other high-performance polymers), by application (consumer, industrial, automotive, telecoms, medical), and by region — with methodology and sensitivity testing. Note: this press summary highlights strategic observations only; detailed subsegment tables and downloadable data packs are available in the full report.
-
Price and cost modeler: a scenario tool that converts raw material price moves and manufacturing mix into unit-cost and margin outcomes, including break-even curves for tooling vs. soft-tool/rapid-turn approaches.
-
Supply-chain resilience matrix: supplier concentration scores, nearshoring potential, dual-sourcing checklists, and actionable mitigation steps for tariff exposure and logistics disruption.
-
Regulatory and materials compliance playbook: templates for EHS engineering, materials declarations (to support compliance such as national registry requirements), and verification pathways for market claims (e.g., chemical-content limits).
-
Competitive benchmarks and capability heatmaps: product portfolios, manufacturing footprints, customization capabilities, and go-to-market models for leading players.
-
M&A and partnership thesis: prioritized target profiles, valuation logic, and integration checklists aligned to scale, margin, and IP objectives.
Market structure and competitive texture
The market exhibits moderate fragmentation: the three largest suppliers together account for roughly just under a third of global revenues, and the top five approach around two-fifths of the market. That structure creates both headroom for scale consolidation and defensibility for regional or specialized players who can leverage design, certification, or local-service advantages.
Across the competitive set, a few consistent strategic archetypes appear:
-
Volume-oriented, off-the-shelf specialists who compete on breadth of catalogue and fast availability.
-
Design-led firms that add ergonomic and aesthetic differentiation for handheld and customer-facing devices.
-
Custom and tooling-capable suppliers that capture higher ASPs in low-to-medium volume OEM programs (medical, industrial controls, lab automation).
-
Engineering partners focused on high-performance and environmental sealing for harsh environments (industrial, outdoor telecoms, and certain automotive segments).
Profiles and strategic implications for named competitors
-
Polycase (Avon, Ohio) — Strengths: US manufacturing, NEMA-rated enclosures, balanced off-the-shelf and custom capability. Strategic implication: momentum in domestically produced NEMA-rated lines positions Polycase well for nearshoring-led demand; scalability and raw-material cost management will be the near-term axes to protect margins.
-
Bud Industries (Willoughby, Ohio) — Strengths: broad general-purpose catalogue and industrial offerings. Strategic implication: catalogue breadth is a moat for distribution-led channels; further differentiation will require modularization and digital configuration tools.
-
Hammond Manufacturing (Guelph, Ontario) — Strengths: EMI/RFI shielding options, cross-material competence. Strategic implication: opportunity to capture higher-value industrial and communications niches that require shielding and hybrid material approaches, especially where performance trumps basic cost.
-
OKW Enclosures (Germany/US) — Strengths: ergonomic, design-forward solutions and customization. Strategic implication: premium positioning benefits from OEM relationships in handheld and medical classes; expansion in durable industrial solutions can broaden TAM.
-
New Age Enclosures — Strengths: off-the-shelf and injection-molding services for electronics. Strategic implication: vertical customers seeking single-source suppliers (design to injection) are prime targets — investments in shorter lead-time molding and digital quoting systems will pay back quickly.
-
Productive Plastics — Strengths: thermoforming and large custom enclosures for robotics and sensors. Strategic implication: as automation and robotics drive demand for bespoke housings, thermoforming and near-net shaping capabilities become attractive acquisition targets for firms wishing to enter large-format enclosures.
-
European specialists (Fibox, Bopla, Rolec) — Strengths: durable materials expertise and modern design language. Strategic implication: European players can exploit proximity advantages for industrial automation and utility markets subject to strong regulatory frameworks.
-
Allied Moulded Products, Integra, Toolless — Strengths: niche material mixes (fiberglass, stainless combinations), and no-tool or low-tool rapid customization. Strategic implication: these firms occupy defensible niches that become attractive targets for consolidators seeking to add specialty capabilities or to reduce time-to-market for regulated industries.
Recent market signals that should influence 2026 strategy
-
Raw-material swings: ABS feedstock tightening and producer-level price increases surfaced in early 2026, while polycarbonate softened materially in late 2025. Procurement roadmaps should incorporate both short-term pass-through scenarios and multi-year hedging strategies tied to polymer blends used across product families.
-
Regulatory tightening: national producer registries and international product-chemistry criteria (notably restrictions on certain brominated and chlorinated flame retardants) mean design teams must embed compliance earlier in the product lifecycle to avoid costly retrofits or market exclusion.
-
Trade policy friction: continued tariff adjustments on China-origin goods in strategic sectors increase the business case for diversified sourcing and regional production nodes.
-
Product innovation cadence: recent product launches and line extensions from leading players underscore a two-track innovation strategy—expand catalogue sizes for fast-moving SKUs while selectively developing ruggedized, certified products for high-growth verticals.
Practical strategic plays for 2026
-
Rebase product portfolios by margin contribution, not just revenue — rationalize low-margin SKUs where tooling and inventory drag ROI below company thresholds.
-
Optimize material mix: where polycarbonate pricing advantage exists, evaluate design swaps for equivalent performance; where ABS costs spike, pursue formulation blends or alternate polymer families for near-term relief.
-
Move to dual-source and geographically balanced supply footprints for critical resins and components; prioritize suppliers with validated compliance documentation to speed approvals.
-
Invest in compliance-as-a-service capabilities — materials declaration, test-lab partnerships, and documented chain-of-custody — as buyer requirements tighten in medical and enterprise tech markets.
-
Pursue bolt-on M&A to acquire specialty manufacturing (thermoforming, EMI-treated housings, or IP in sealed enclosures) that can boost realized ASPs and reduce dependence on commodity segments.
-
Deploy digital configurators and modular enclosure platforms to capture distribution revenue while reducing bespoke engineering costs; short lead-time, toolless product pathways can open medical and low-volume OEM opportunities.
How to use the full report
The full PW Consulting report contains the granular tables, regional and application breakouts, supplier scorecards and our scenario financial modeler that converts raw-material and tariff assumptions into P&L outcomes. This briefing purposefully omits detailed regional and application line-item disclosure to preserve the full dataset for buyers. For procurement teams, product leaders, and corporate development groups, the downloadable data pack and client workshop we provide turn findings into a 90–180 day execution roadmap.
Closing recommendation
With a projected rise from USD 6.25 Billion in 2025 toward the USD 9.4 Billion neighborhood by 2032 at a 6.0% CAGR, the electronic plastic enclosure market offers constructive growth backed by steady demand from consumer, industrial and automotive electronics. Yet the path to profitable growth in 2026 will be decided by three near-term capabilities: disciplined materials and cost management, demonstrable compliance and sustainability evidence, and operational agility to serve both catalogue and bespoke demand. PW Consulting’s full study equips leadership teams with the data, scenarios, and tactical playbooks needed to convert that market growth into durable margin expansion.
To obtain the complete report, regional and application breakouts, and the interactive scenario modeller, visit PW Consulting’s market reports page or contact our industry practice. The full package includes raw data downloads, supplier scorecards, and a tailored executive workshop to operationalize findings for 2026 planning.
For detailed analysis of this topic, please visit the official page: Electronic Plastic Enclosure Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com