

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cellular Base Station Antenna Market Reaches USD 10,480 Million in 2025, Projected to Expand at a 15% CAGR Through 2032

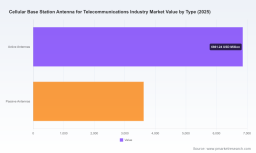
Cellular Base Station Antenna For Telecommunications Industry Market — 2026 Strategic Outlook
PW Consulting’s latest market study, with a 2025 base year and a seven‑year forecast through 2032, frames the cellular base station antenna market as a rapid-growth, strategic battleground for network operators, infrastructure suppliers, and capital investors. The global market, measured in USD Million for base station antennas and related RF subsystems, stood at approximately 10,480 million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 15.0% over 2026–2032, reaching an expected total near 27,877 million by 2032. These headline dynamics underscore why antenna choices, deployment timing, and supplier strategy will be core determinants of competitive advantage for organizations making decisions in 2026.
Cellular Base Station Antenna For Telecommunications Industry Market
Why this report matters for 2026 decision-makers
-
Investment prioritization: Capital allocation decisions for macro and small cell rollouts hinge on realistic, technology‑specific cost and performance tradeoffs. Our study translates market growth into calibrated procurement scenarios that reflect both incumbent and emerging architectures.
Cellular Base Station Antenna For Telecommunications Industry Market -
Vendor selection and risk mitigation: With market concentration materially favoring a small set of global suppliers, operators must balance performance, security/compliance (e.g., supply‑chain provenance and NDAA considerations), and resilience. We provide a decision framework to operationalize those tradeoffs.
Cellular Base Station Antenna For Telecommunications Industry Market -
Regulatory timing and spectrum strategy: Recent regulatory moves—most notably U.S. modernization efforts and proposed repurposing of portions of the Upper C‑band—create narrow windows for network upgrades and auction planning. The report maps deployment and upgrade timelines against plausible regulatory milestones.
-
Sustainability and OPEX reduction: Energy efficiency is no longer ancillary. Our analysis translates antenna architecture choices into projected network energy footprints and identifies where passive and active designs produce measurable user‑experience and cost benefits.
Key findings — a preview
-
Robust, technology‑driven expansion: The favorable 15% CAGR through 2032 is being driven by the combined momentum of Massive MIMO, multi‑band integration, densification through small cells, and evolution of active antenna systems. These technology drivers are shifting spend from discrete RF components toward integrated antenna‑radio solutions.
-
Consolidated competitive structure: The sector exhibits meaningful concentration at the top, with the largest manufacturers and integrated radio suppliers capturing a disproportionate share of spend. This creates both bargaining leverage for leading vendors and strategic vulnerabilities for buyers that over‑concentrate procurement.
-
Deployment economics remain the gating factor: High installation and maintenance costs, together with limited contiguous spectrum in key bands, continue to constrain densification strategies despite strong demand for greater capacity and coverage.
-
Standards and coordination matter: Industry harmonization—exemplified by recent updates to antenna description frameworks—reduces integration risk for multi‑vendor installations and accelerates time‑to‑revenue for new 5G rollouts.
-
Near‑term disruptions and catalysts: New product introductions (e.g., compact RU units optimized for sub‑6 GHz Massive MIMO) and regulatory reforms that streamline modifications to existing towers are immediate catalysts that will re‑shape vendor roadmaps and procurement windows in 2026.
Competitive landscape — what incumbents and challengers mean for buyers
The market’s competitive texture mixes global infrastructure OEMs, specialized antenna manufacturers, and vertically integrated radio vendors. This report profiles leading players across technology, go‑to‑market model, and value propositions, and it interprets the practical implications for sourcing and risk management:
-
Huawei Technologies Co. Ltd. — A broad portfolio across passive and active antennas including high‑port Massive MIMO and multi‑band designs. Strength: integrated, energy‑efficient high‑port arrays for large‑scale macro deployments.
-
Ericsson AB — Deep integration between antenna systems and RAN infrastructure (e.g., Ericsson Antenna System) with strong performance in Massive MIMO and hybrid architectures; notable for optimizing beam efficiency and cell‑edge throughput.
-
Nokia Corporation — Multi‑band and Massive MIMO solutions tailored to both dense urban and rural use cases, integrated with its AirScale platforms for operators prioritizing end‑to‑end coordination.
-
CommScope — Emphasizes scalable RF and hybrid LTE/5G solutions and distributed antenna systems, positioning for operators seeking modularity and retrofit capability.
-
Amphenol Antenna Solutions, Comba, Rosenberger, RFS, ACE Technologies, Tongyu, and others — A mix of tier‑2 players offering cost‑optimized passive designs, specialized mechanical and RF engineering, and localized supply options that matter for procurement diversification and geographic footprinting.
-
Regional and specialist entrants — Firms with domestic manufacturing footprints or sustainability‑focused designs offer differentiated value for governments and operators with local‑sourcing or environmental targets.
Importantly, PW Consulting’s competitive scoring synthesizes technical capability, supply‑chain resilience, regulatory compliance posture, and total cost outcomes. Report readers can access a vendor scorecard and shortlist builder to filter suppliers against procurement policies and risk appetite.
Regulatory and standards context shaping 2026 choices
-
Streamlining modernization: Recent regulatory orders aim to lower administrative barriers to tower and infrastructure upgrades—accelerating the upgrade cadence but compressing decision timelines for operators.
-
Spectrum reconfiguration: Proposed repurposing of mid‑band spectrum in flagship markets creates both deployment urgency and selective demand for antennas optimized for newly available bands.
-
Standards updates: Industry recommendations that harmonize how passive, active, and hybrid antennas are described simplify procurement specifications and integration testing—an immediate advantage for multi‑vendor rollouts.
What the PW Consulting report includes — practical, operational deliverables
This study is purpose‑built for executives and program managers who must translate market intelligence into executable plans. Deliverables include:
-
Executive decision frameworks that convert market growth scenarios into phased capex and opex plans.
-
Vendor scorecards and sourcing playbooks that balance technical fit, security/compliance, and supply‑chain exposure.
-
Deployment scenario templates and TCO models that capture capital expenditure, installation labor, maintenance trajectories, and energy consumption outcomes across antenna architectures.
-
Regulatory impact maps that align procurement and deployment milestones with expected policy actions and auction timelines.
-
Risk matrices and mitigation plans covering component shortages, tariff exposure, and single‑supplier dependencies.
-
Investment and M&A screening criteria for strategic acquisitions, joint ventures, or localized manufacturing investments.
Readers should note that the report contains granular segmentation and vendor‑level commercial estimates that are intentionally omitted from this press release to preserve actionable value; full datasets and model access are available via the report portal.
Actionable strategic recommendations for 2026
-
Prioritize modular, upgradeable architectures: Buy antennas and radio systems that enable incremental capacity scaling and remote software enablement to avoid costly rip‑and‑replace cycles.
-
Integrate energy efficiency into procurement KPIs: Require vendors to demonstrate beam‑efficiency and radio energy metrics tied to realistic cell‑edge throughput scenarios; these metrics materially affect OPEX and user experience.
-
Time spectrum‑dependent rollouts to regulatory windows: Align major macro upgrades to confirmed spectrum repurposing and auction timelines to maximize spectral efficiency and spectrum value extraction.
-
Diversify supplier footprint with domestic or NDAA‑compliant options where geopolitical risk or procurement rules demand it, but retain a performance‑first sourcing layer for large‑scale deployments.
-
Use scenario planning for densification economics: Employ PW Consulting’s TCO templates to compare capex/opex across small‑cell densification, macro upgrades with Massive MIMO, and hybrid models under alternative traffic growth paths.
-
Invest in integration and test capabilities: For multi‑vendor ecosystems, onshore lab resources and shared testbeds reduce rollout risk and speed time‑to‑service.
Buyer use‑cases — who benefits most
-
Mobile network operators — Strategic planning for capacity and coverage upgrades, supplier selection, and spectrum monetization.
-
Towercos and infrastructure investors — Valuation and retrofit prioritization for assets in spectrum‑rich markets.
-
Governments and regulators — Impact assessment of spectrum policy and infrastructure modernization incentives.
-
Component and antenna manufacturers — Competitive benchmarking, product roadmap validation, and partner identification.
-
Private equity and strategic acquirers — Target screening and synergy analysis for consolidation plays in a concentrated market.
Closing perspective
PW Consulting’s market study provides a pragmatic, decision‑grade synthesis of fast‑evolving technology, regulatory developments, and competitive positioning in the cellular base station antenna market. With an industry trajectory implying more than doubling market scale over the forecast horizon at a 15.0% CAGR, 2026 is a pivotal inflection year: regulatory windows are opening, product roadmaps are accelerating, and supply choices made now will determine total cost and time‑to‑market for the next wave of 5G and beyond deployments.
For procurement teams, technology strategists, and investors preparing 2026 plans, the full report supplies the models, vendor assessments, and scenario playbooks needed to convert these macro trends into executable, low‑risk programs. To access the complete dataset, granular segmentation, and vendor‑level analytics not disclosed here, please visit the PW Consulting report portal for subscription and licensing options.
For detailed analysis of this topic, please visit the official page: Cellular Base Station Antenna For Telecommunications Industry Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com